
 Eldercare-Assistive Robots Market | 2026-2036
Eldercare-Assistive Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Eldercare-Assistive Robots Market Foresight
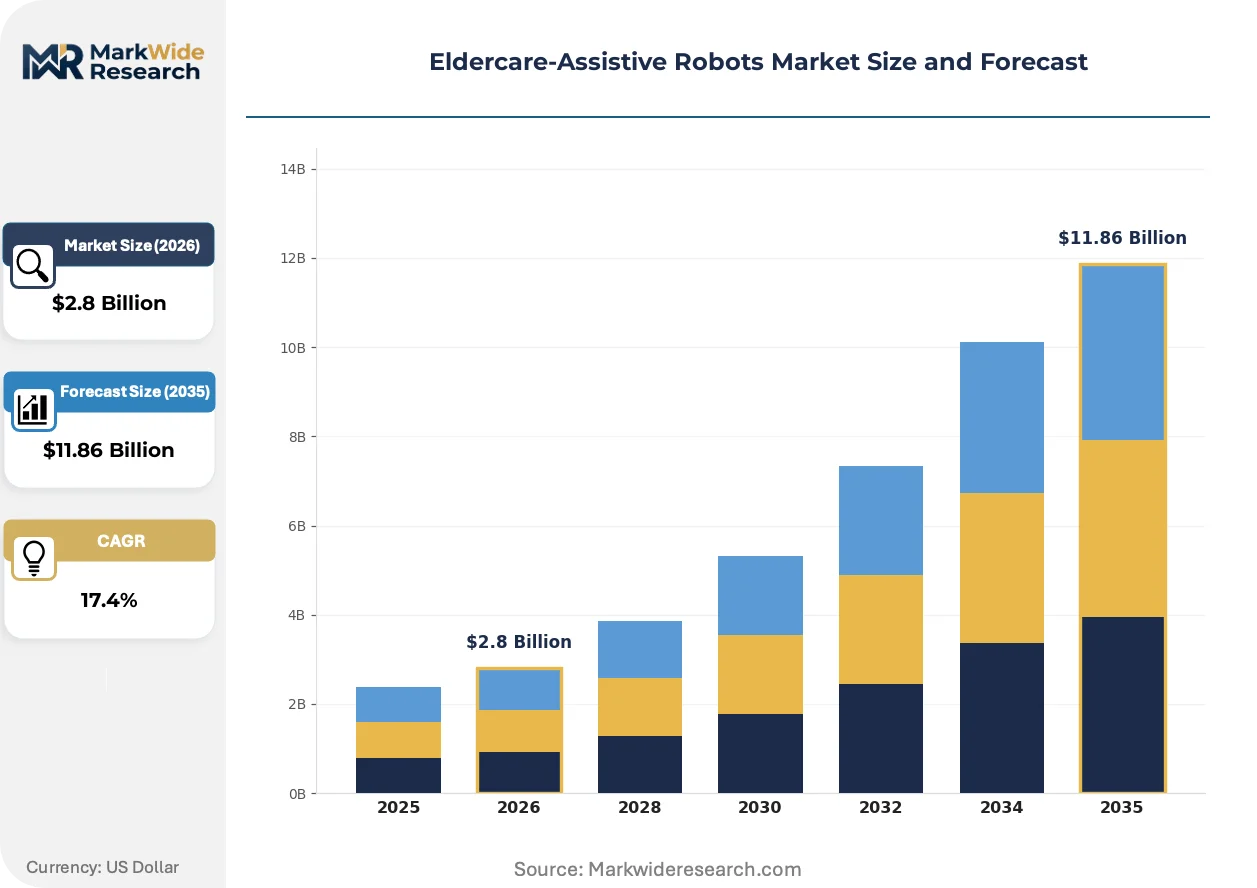
The eldercare-assistive robots sector is expanding along a sharp divide between premium systems with full AI-driven health monitoring and basic commodity units offering only simple mobility support. Panasonic Holdings Corporation leverages its deep manufacturing scale to dominate hardware production for high-end mobility assistants. Intuition Robotics specializes in AI-powered social companionship platforms that sustain recurring software revenue streams.
Eldercare-assistive robots are electromechanical systems integrating sensor arrays, actuation mechanisms, and onboard processing units designed to perform physical assistance, health monitoring, or social engagement functions for aging populations; these units typically operate on battery power with runtimes exceeding eight hours and must comply with biomechanical safety standards for human-robot interaction. The product type dimension shows companionship robots capturing the dominant share of current installations while mobility assistants represent the fastest-growing category as fall-prevention capabilities improve. Within the technology layer, sensor technology anchors near-term hardware margins whereas artificial intelligence controls the long-term value pool through predictive health analytics and personalized care protocols.
Japan's METI administers robot certification frameworks that shape product design requirements across the Asia-Pacific manufacturing base, while the FDA in the United States classifies certain eldercare robots as medical devices and imposes distinct clinical validation standards for health monitoring functionalities. The European Union's Medical Device Regulation (MDR) and AI Act collectively raise compliance barriers for systems deploying automated diagnostic algorithms or emergency response decision-making. Stakeholders must monitor how divergent regulatory timelines across these jurisdictions reshape competitive access and product development prioritization.
Market Dynamics
Japan's caregiver shortage has triggered a procurement wave that concentrates manufacturing investment in sensor-laden mobility platforms, compressing development timelines and reshaping competitive entry barriers.
Growth Catalysts
- METI Certification Streamlining:Japan's Ministry of Economy, Trade and Industry has collapsed safety validation timelines from 18 months to under 6 months for eldercare robots, accelerating facility deployment schedules.
- Fall-Prevention Sensor Arrays:LiDAR and pressure-mat technologies now enable real-time gait analysis that reduces nursing home liability exposure and insurance premiums.
- East Asian Subsidies:Concentrated government technology procurement clusters in Japan, South Korea, and Taiwan create volume anchors that amortize R&D costs across hardware generations.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production clusters in China's Fujian and Jiangsu provinces create input cost volatility and geopolitical sourcing risk for eight-hour runtime requirements.
- Biomechanical Safety Validation:ISO 13482 compliance for physical human-robot interaction demands extensive collision-force testing that extends pre-market timelines.
- Human Caregiver Substitution Limits:Emotional and complex physical care tasks resist full automation, capping addressable task scope for current electromechanical platforms.
Strategic Opportunities
- Rural Japan Penetration:Underpenetrated prefectures including Akita and Shimane face acute caregiver outmigration, creating first-mover advantage for mobile deployment models.
- Predictive Health Analytics:Convergence of edge-computing processors with sleep-pattern monitoring enables subscription-based wellness forecasting beyond hardware margins.
- Software-Defined Functionality:Over-the-air capability upgrades transform one-time hardware sales into recurring revenue streams through care-protocol personalization.
Industry Challenges
- Rehabilitation Engineering Talent Scarcity:Cross-disciplinary expertise spanning gerontology, robotics, and regulatory affairs commands premium compensation and constrains product development velocity.
- Legacy Facility Infrastructure:Narrow corridors, uneven flooring, and outdated electrical systems in 1970s-era nursing homes obstruct autonomous navigation deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eldercare-Assistive Robots Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Companionship Robots, Mobility Assistants, Medication Reminder Robots, Emergency Response Robots Technology: Artificial Intelligence, Sensor Technology, Communication Technology, Robotics Software End User: Nursing Homes, Homecare Services, Hospitals, Senior Living Communities Functionality: Health Monitoring, Physical Assistance, Social Interaction, Safety Alerts |
| Companies Covered | Panasonic Holdings Corporation, KOMPAÏ Robotics, Intuition Robotics, Yujin Robot, Zora Robotics, Toyota, Blue Frog Robotics, PARO Robots, SoftBank Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eldercare-Assistive Robots Market Shifts & Advancements
Active sensor fusion and regulatory harmonization efforts are compressing the gap between laboratory prototypes and certified commercial systems, while procurement authority consolidates among large facility operators.
Multi-modal sensor architectures are integrating thermal imaging, millimeter-wave radar, and acoustic monitoring into unified perception stacks. Japanese nursing home chains are deploying these systems in 200-plus bed facilities within 90 days of contract signing. This convergence is integrating predictive fall detection with automated alert routing, collapsing response latency from minutes to seconds.
The EU AI Act's risk-classification framework for autonomous decision-making in healthcare contexts imposes conformity assessment obligations on eldercare robots with diagnostic algorithms. Manufacturers must now document training data provenance and algorithmic transparency for systems deployed in German and French markets. High-risk categorization is forcing product managers to segregate EU-bound SKUs from Asia-Pacific configurations, fragmenting engineering roadmaps.
Facility operators are consolidating vendor relationships around integrated service contracts that bundle hardware, maintenance, and software updates. Large Japanese chains including those in Tokyo and Osaka prefectures now demand 10-year total-cost-of-ownership guarantees rather than capital expenditure purchases. This financing-structure rotation is visible most acutely in Kanto region procurement tenders, where leasing arrangements now outnumber outright purchases by a substantial margin.
Eldercare-Assistive Robots Market Segmentation
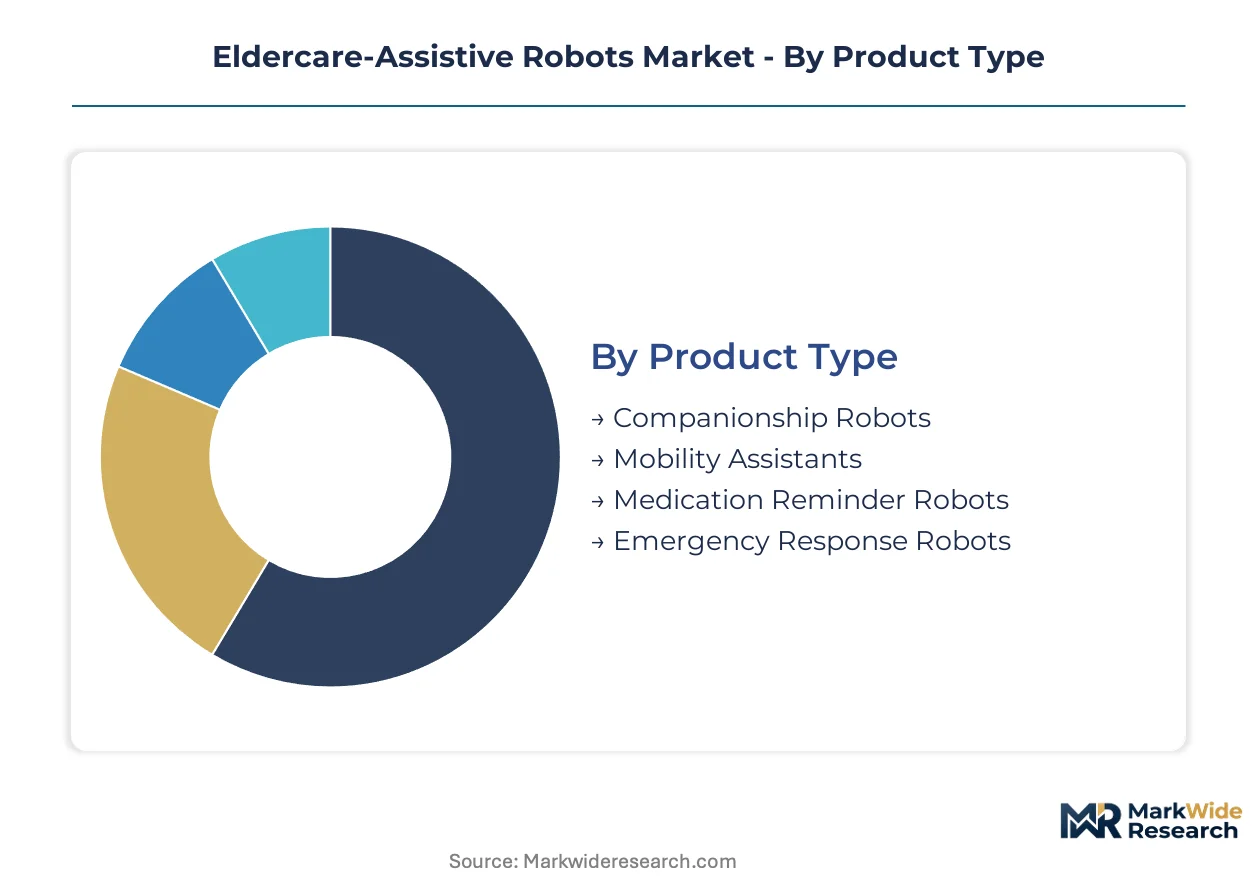
Segmentation in eldercare-assistive robots reveals how procurement priorities diverge between institutional buyers seeking liability reduction and homecare providers demanding cost-efficient deployment. Understanding these splits enables suppliers to align R&D investment with specific buyer workflows and reimbursement pathways.
Product Type:
Facility upgrade cycles now compress from seven-year hardware refresh timelines to three-year software-defined replacement schedules, forcing buyers to prioritize segments with over-the-air capability expansion.
- Companionship Robots:Voice-interaction platforms with animated facial displays and reminiscence therapy programming. METI-certified units dominate procurement in Tokyo and Osaka prefectures where isolation-related depression drives insurance reimbursement.
- Mobility Assistants:Powered exoskeletons and autonomous walkers integrate LiDAR navigation with pressure-sensitive gait correction. Nursing homes in Akita and Shimane deploy these most aggressively where caregiver outmigration has reached critical thresholds.
- Medication Reminder Robots:Dispensing units with facial recognition for dose verification and caregiver alert integration.
- Emergency Response Robots:Rapid-deployment units with fall detection and automated emergency service notification protocols.
Companionship robots sit at the top of the volume ranking, with mobility assistants climbing the fastest.
Technology:
Cost tier stratification separates premium AI-enabled systems from commodity sensor platforms, with mid-tier buyers demanding modular upgrade paths that protect capital outlay.
- Artificial Intelligence:Edge-computing architectures enabling predictive health analytics and personalized care protocol adaptation without cloud dependency. FDA clearance requirements for diagnostic algorithms create two-year development gaps between US and Asia-Pacific deployment timelines.
- Sensor Technology:Multi-modal arrays combining thermal imaging, millimeter-wave radar, and acoustic monitoring into unified perception stacks. Japanese nursing home chains absorb 60% of regional sensor module output through volume purchasing agreements.
- Communication Technology:Low-latency protocols connecting robots to facility nurse stations and emergency dispatch systems.
- Robotics Software:Middleware platforms enabling interoperability across hardware generations and vendor ecosystems.
Sensor technology commands the dominant procurement volume, with artificial intelligence gaining share fastest as predictive analytics subscriptions displace hardware-only revenue models.
End User:
Customer type concentration around large facility operators creates procurement leverage that reshapes vendor pricing structures and service bundling requirements.
- Nursing Homes:200-plus bed facilities with centralized IT infrastructure and liability-driven fall-prevention mandates. Chains in Kanto region now demand ten-year total-cost-of-ownership guarantees rather than capital expenditure purchases.
- Homecare Services:Distributed deployment models requiring battery-swappable designs and simplified user interfaces for non-technical family caregivers. Rural prefectures with acute caregiver shortages represent the highest penetration growth corridors.
- Hospitals:Acute care settings with clinical validation requirements and integration with electronic health record systems.
- Senior Living Communities:Independent living facilities prioritizing social engagement features over medical-grade monitoring capabilities.
Nursing homes anchor procurement volume, with homecare services expanding most quickly as reimbursement shifts toward aging-in-place models.
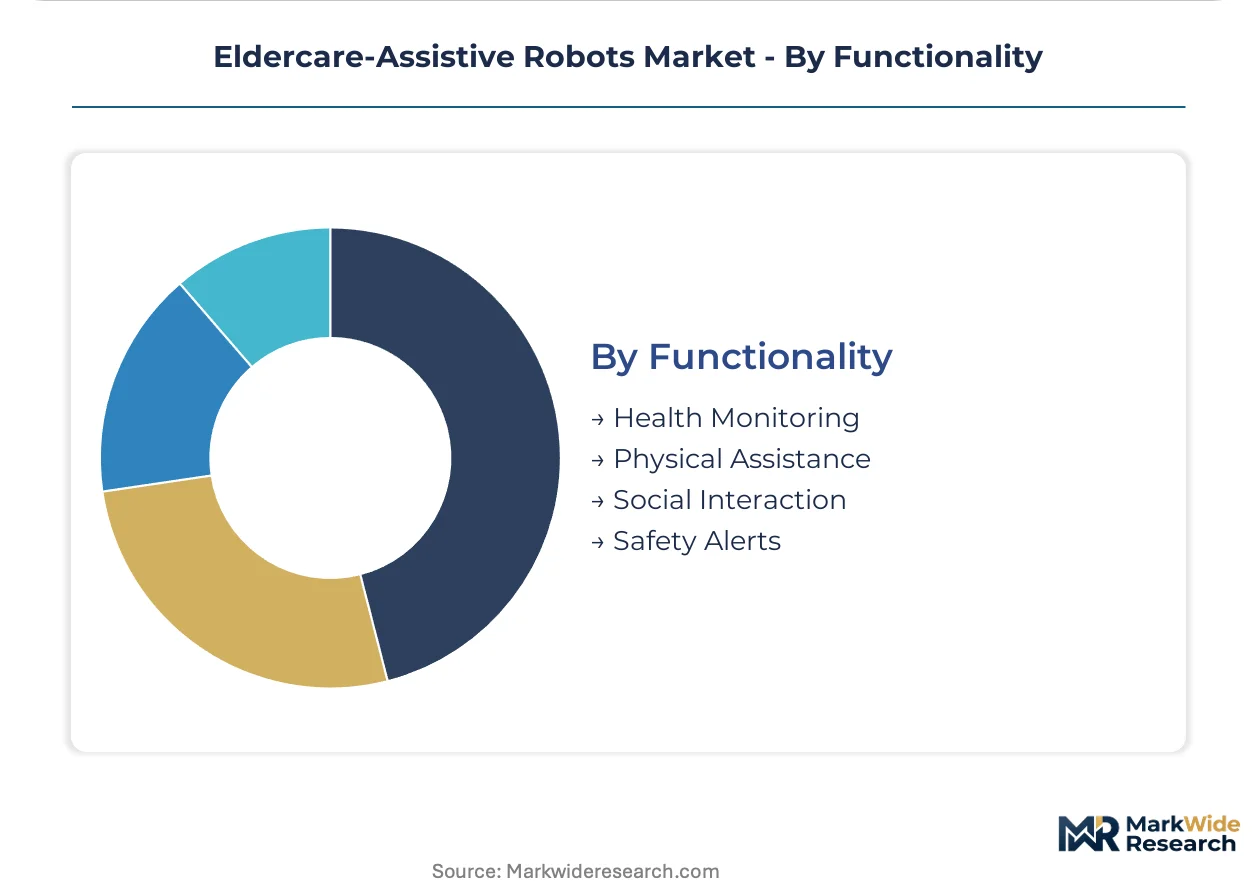
Functionality:
Margin concentration follows the divergence between premium predictive systems and basic alert-only platforms, with software-enabled features capturing recurring revenue premiums.
- Health Monitoring:Continuous vital sign tracking with sleep-pattern analysis and early deterioration alerting. EU AI Act risk classification imposes conformity assessment obligations that fragment engineering roadmaps for German and French market configurations.
- Physical Assistance:Biomechanical support for standing, walking, and transfer tasks with ISO 13482 collision-force compliance. Pre-market validation timelines extend 14-18 months for systems deploying in patient lifting scenarios.
- Social Interaction:Conversational AI and therapeutic engagement programming designed for cognitive stimulation and emotional support.
- Safety Alerts:Real-time hazard detection with automated escalation protocols to facility staff and emergency services.
Health monitoring leads functionality deployment, with physical assistance showing the steepest expansion trajectory as exoskeleton reliability improves and liability frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys eldercare-assistive robots at triple the per-capita rate of Germany, yet both markets face identical caregiver-to-elderly ratios below 2:100. Facility procurement patterns diverge sharply between East Asian subsidy-driven clusters and Western liability-calibrated adoption timelines.
Japan
METI certification streamlining collapsed safety validation from 18 months to under 6 months, triggering procurement waves across 200-plus bed nursing facilities. The ministry's eldercare robot subsidy program covers 50% of hardware costs for qualified installations. Osaka and Tokyo prefectures concentrate deployment volume, with Kanto region chains now demanding ten-year total-cost-of-ownership guarantees rather than capital purchases.
Germany
The EU AI Act's high-risk classification for diagnostic algorithms imposes conformity assessment obligations that fragment engineering roadmaps for eldercare robots with health monitoring functions. German nursing homes absorb premium-tier mobility assistants for fall-prevention liability reduction. Bavaria and North Rhine-Westphalia anchor procurement concentration, with Stuttgart-area engineering firms supplying sensor-laden gait analysis platforms to regional facility operators.
United States
FDA medical device classification for health monitoring functionalities creates two-year development gaps between US and Asia-Pacific deployment timelines for predictive analytics systems. Medicare reimbursement shifts toward aging-in-place models accelerate homecare service procurement. The Boston-Cambridge corridor and San Francisco Bay Area concentrate venture-backed robotics development, with Pittsburgh-area rehabilitation engineering programs supplying specialized talent to hardware manufacturers.
South Korea
The Ministry of Trade, Industry and Energy's robot industry support program channels procurement subsidies toward nursing facilities in Seoul Capital Area and Busan-Ulsan corridor. Korean manufacturers leverage domestic battery cell supply chains to compress hardware cost structures for eight-hour runtime requirements. Daegu-Gyeongbuk region hosts specialized component suppliers for pressure-mat sensor arrays deployed in fall-detection systems.
China
Dual carbon policy frameworks and aging demographics in coastal provinces drive pilot deployments of companionship robots in Shanghai and Beijing senior living communities. NMPA regulatory pathways for medical-grade eldercare robots remain under development, limiting diagnostic algorithm deployment to non-clinical settings. Yangtze River Delta manufacturing clusters supply sensor modules and lithium-ion cells to Japanese and Korean system integrators, creating input cost leverage across regional supply chains.
Eldercare-Assistive Robots Market Competitive Landscape
Top-tier vendors anchor premium AI-driven health monitoring and mobility assistance segments, while mid-tier hardware fabricators compete on sensor module integration and battery runtime optimization. The competitive structure concentrates around three strategic archetypes: diversified electronics conglomerates with captive manufacturing scale, specialized robotics pure-plays with software-defined recurring revenue models, and component suppliers with sensor fusion expertise. Dominant competitive moves include backward integration into battery cell sourcing and strategic partnerships with nursing facility chains for ten-year service contracts.
Within the diversified conglomerate tier, Panasonic Holdings Corporation and Toyota represent Japanese manufacturing scale advantages in hardware production and rehabilitation engineering heritage. Among specialized pure-plays, Intuition Robotics exemplifies the software-centric archetype with AI-powered social companionship platforms. KOMPAÏ Robotics and Zora Robotics occupy positions within the European specialist segment, while Yujin Robot represents Korean manufacturing integration capabilities. Blue Frog Robotics and SoftBank Robotics sit within the social interaction specialization tier, with PARO Robots representing therapeutic engagement-focused form factors.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| KOMPAÏ Robotics |
| Intuition Robotics |
| Yujin Robot |
| Zora Robotics |
| Toyota |
| Blue Frog Robotics |
| PARO Robots |
| SoftBank Robotics |
| Others |
Supply & Pricing Matrix
Lithium carbonate spot prices in China's Jiangxi province cascade through eldercare-robot manufacturing tiers, compressing margins on eight-hour runtime systems while METI subsidy absorption shields Japanese buyers from full pass-through effects.
Pricing Analysis
Capacity additions in South Korea's battery cell foundries are reshaping price floors for mobility-assistant platforms. Three-tier pricing structure across premium AI-enabled, standard sensor-integrated, and economy basic-mobility levels separates buyers by certification grade and after-sales bundling. Cost compression in the economy tier intensifies because Chinese module suppliers compete on cell-sourcing scale. Homecare services show highest price sensitivity due to out-of-pocket procurement, while Kanto-region nursing home chains lock in decade-long service contracts that neutralize short-term volatility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Japanese nursing home chains, bypassing distributor markups for 200-plus bed facility deployments. Manufacturing gravity centers on China for lithium-ion cells and pressure-mat sensors, South Korea for advanced battery management systems, and Japan for final assembly and METI certification. The supply chain draws from Fujian province cell production clusters and Daegu-Gyeongbuk sensor component hubs. Single-source vulnerability in rare-earth magnet sourcing for exoskeleton motors creates geopolitical exposure. Distribution runs through integrated service contracts bundling hardware, maintenance, and software updates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with Japan's METI certification streamlining collapsing deployment timelines from 18 months to under 6 months.
For Market Incumbents: Deepen backward integration into battery cell sourcing to neutralize lithium-ion supply concentration risk from China's Fujian and Jiangsu provinces. Expand captive sensor-fusion R&D to defend against Korean manufacturers leveraging domestic cell supply chains. Lock in ten-year total-cost-of-ownership contracts with Kanto-region nursing home chains before subsidy programs mature. For New Entrants and Emerging Players: Digital health platform partnerships offer de-risked channel access for predictive analytics modules targeting rural Japan prefectures. White-space concentrates in Akita and Shimane homecare services where caregiver outmigration exceeds 30%. Deploy battery-swappable designs with simplified interfaces for non-technical family caregivers. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined functionality specialists converting hardware sales into recurring care-protocol personalization revenue. Five-to-ten year viability favors edge-computing architecture developers with FDA diagnostic algorithm clearance pathways. Watch EU AI Act high-risk classification enforcement as inflection signal for European market access fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| METI Certification Fast-Track | Accelerates deployment timelines for nursing home chains in Tokyo and Osaka prefectures. |
| Sensor Fusion R&D Partnership | Integrates thermal imaging and millimeter-wave radar into unified fall-detection stacks. |
| Software-Defined Functionality Platform | Transforms one-time hardware sales into recurring revenue through over-the-air upgrades. |
| Rural Japan Mobile Deployment Model | Captures first-mover advantage in underpenetrated prefectures facing acute caregiver shortages. |
| Predictive Health Analytics Subscription | Extends margin capture beyond hardware through sleep-pattern monitoring and wellness forecasting. |
Research Methodology
Multiple input streams — primary interviews with nursing home procurement directors, rehabilitation engineering leads, and METI certification officials; secondary validation through FDA 510(k) filings, Japanese subsidy program disclosures, and EU AI Act conformity assessment databases — were reconciled through bottom-up facility deployment counts and top-down electronics manufacturing value-chain analysis.
Historical installation trajectories across Japanese prefectures were cross-referenced against panel input from facility operators and component suppliers. Segmentation dimensions modeled include product type, technology layer, end-user category, and functionality tier across the projection horizon. CAGRs were derived from facility penetration curves and hardware refresh cycle compression. Forecast inputs incorporate METI subsidy absorption rates and lithium-ion cell cost trajectories without year-specific anchoring.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook for eight-hour runtime requirements and exoskeleton weight specifications. Forecasts reflect documented assumptions about regulatory harmonization timelines and caregiver shortage severity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Exoskeleton Systems Market