
 Harvesting Robot Market | 2026-2036
Harvesting Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Harvesting Robot Market Insights
Commercial growers is unwinding the historical dominance of family farms as the primary buyer archetype for harvesting robots. Deere & Company leverages its entrenched dealer network to dominate North American grain belt deployments. AGCO Corporation competes through open-architecture platforms that integrate third-party perception stacks. FFRobotics specializes in tree-fruit robotic grippers, anchoring its position in Mediterranean and Middle Eastern orchard markets.
Harvesting robots are electromechanical systems combining computer vision, articulated manipulators, and autonomous mobility platforms to perform selective crop removal with minimal bruising or damage. These machines typically operate at speeds of 0.5 to 2.5 kilometers per hour while processing RGB-D and multispectral data to identify ripeness, enabling 24-hour continuous field operations where manual labor availability fluctuates seasonally. Fruit harvesters command premium pricing due to the technical complexity of gentle handling protocols for soft-skinned varieties. Vegetable harvesters are scaling fastest in leafy green and root vegetable applications where crop uniformity simplifies machine learning training datasets. Grain harvesters represent the most mature segment, with margin pools shifting from hardware sales to subscription-based fleet optimization software.
The EPA regulates off-road diesel emissions thresholds for self-propelled agricultural equipment, directly influencing powertrain architecture decisions for U.S.-market robots. The EU Green Deal and F-Gas Regulation are accelerating electric and hydrogen fuel cell propulsion roadmaps for equipment sold within European member states. ISO 18497 safety standards for autonomous agricultural machinery establish functional safety benchmarks that determine market access eligibility across multiple jurisdictions. Stakeholders must monitor how carbon border adjustment mechanisms reshape total cost of ownership calculations for imported robotic platforms versus locally manufactured alternatives.
Market Dynamics
Labor scarcity across California's Central Valley specialty crop belt is accelerating capital substitution toward autonomous selective harvesters, compressing payback period thresholds from five years to under three for commercial growers.
Growth Catalysts
- EPA Tier 4 Final emissions mandates:Diesel particulate limits for off-road equipment are forcing powertrain electrification roadmaps, expanding addressable market for battery-electric platforms in U.S. row-crop applications.
- RGB-D sensor fusion:Multispectral imaging combined with depth sensing enables bruise-free handling of soft-skinned tree fruits, opening robotic penetration into stone fruit and berry categories previously resistant to mechanization.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions on agricultural refrigeration and climate control are creating bundled procurement incentives for zero-emission harvesting platforms in Mediterranean orchard belts.
Market Restraints
- Lithium-ion cell supply concentration:Cathode precursor refining clusters in China create input cost volatility and geopolitical exposure for electric platform manufacturers targeting North American and European buyers.
- ISO 18497 functional safety certification:Autonomous machinery standards require redundant perception systems and fail-safe actuation architectures, adding eighteen to thirty-six months to product development cycles.
- Manual labor wage arbitrage:Seasonal harvest worker availability in Eastern European and North African sourcing regions remains price-competitive against capital-intensive robotic alternatives for commodity grain operations.
Strategic Opportunities
- India PLI scheme for agricultural mechanization:Production-linked incentives for precision farming equipment create localized manufacturing pathways for cost-optimized platforms targeting smallholder consolidation trends.
- Leafy green robotic harvesting:Crop uniformity in greenhouse lettuce and spinach operations enables simplified machine learning training datasets, accelerating deployment velocity relative to variable tree-fruit environments.
- Subscription fleet optimization software:Margin pool migration from hardware sales to recurring revenue models creates customer lock-in and predictive maintenance revenue streams for grain harvester incumbents.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineering teams combining computer vision, robotic manipulation, and agricultural domain expertise command premium compensation, constraining R&D scaling for mid-tier equipment vendors.
- Legacy fleet integration friction:Proprietary CAN bus protocols and data formats from incumbent manufacturers create interoperability barriers for third-party autonomous retrofit kits seeking dealer channel access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harvesting Robot Market |
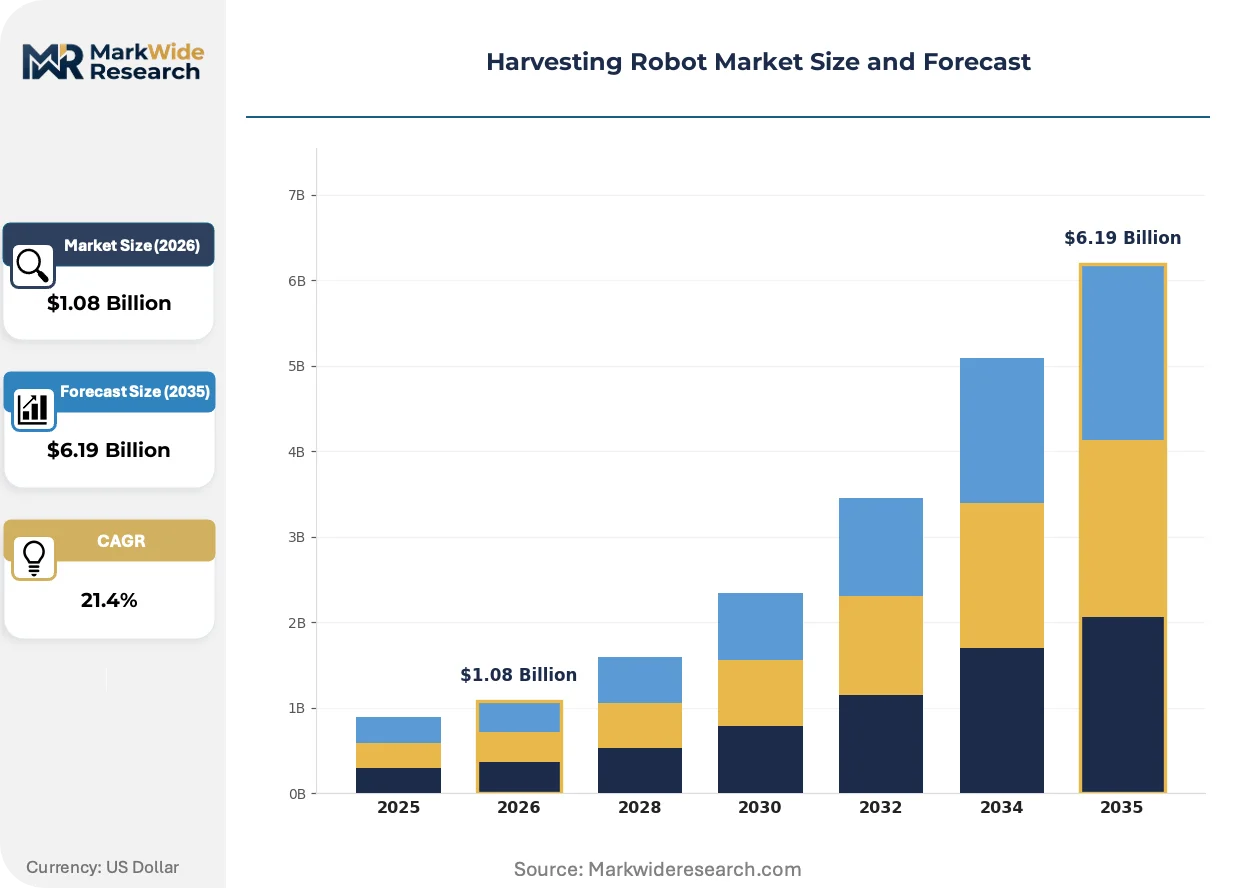
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Harvesters, Vegetable Harvesters, Grain Harvesters, Specialty Harvesters End User: Agricultural Firms, Commercial Growers, Family Farms, Organic Producers Technology: Autonomous Navigation, Sensor-Based Systems, AI Integration, Machine Learning Deployment: On-Farm, Contract Services, Cooperative Ventures, Research Institutions |
| Companies Covered | Deere & Company, AGCO Corporation, Clearpath Robotics Inc., AgEagle Aerial Systems Inc., YANMAR HOLDINGS CO., LTD, Kubota Corporation, FFRobotics, Harvest Automation, Harvest CROO Robotics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harvesting Robot Market Trends and Innovations
Harvesting robot architectures are fragmenting from monolithic platforms toward modular subsystems, enabling component-level upgrades and supplier specialization. This decomposition is compressing development cycles and expanding the vendor ecosystem beyond traditional agricultural equipment incumbents.
RGB-D perception stacks are decomposing the historical integration between machine vision and robotic manipulation. Specialty crop operators in Spain and Italy are adopting third-party depth-sensing modules for retrofitting existing tractor platforms. Component-level procurement is displacing turnkey system purchases, compressing supplier margins while expanding addressable volume.
EU Green Deal carbon border adjustment mechanisms are reshaping equipment import economics. Embedded emissions calculations for steel and battery components favor locally manufactured robotic platforms over Asian-sourced alternatives. Mediterranean orchard operators are responding by prioritizing European-assembled harvesters with verifiable supply chain carbon footprints.
Commercial growers are consolidating procurement authority at the enterprise level, displacing decentralized purchasing by individual farm managers. Large-scale specialty crop operations in California and Australia's Murray-Darling Basin are centralizing technology vendor selection under dedicated automation divisions. This concentration is compressing sales cycles while raising barriers for niche suppliers lacking enterprise-scale service infrastructure.
Harvesting Robot Market Segmentation
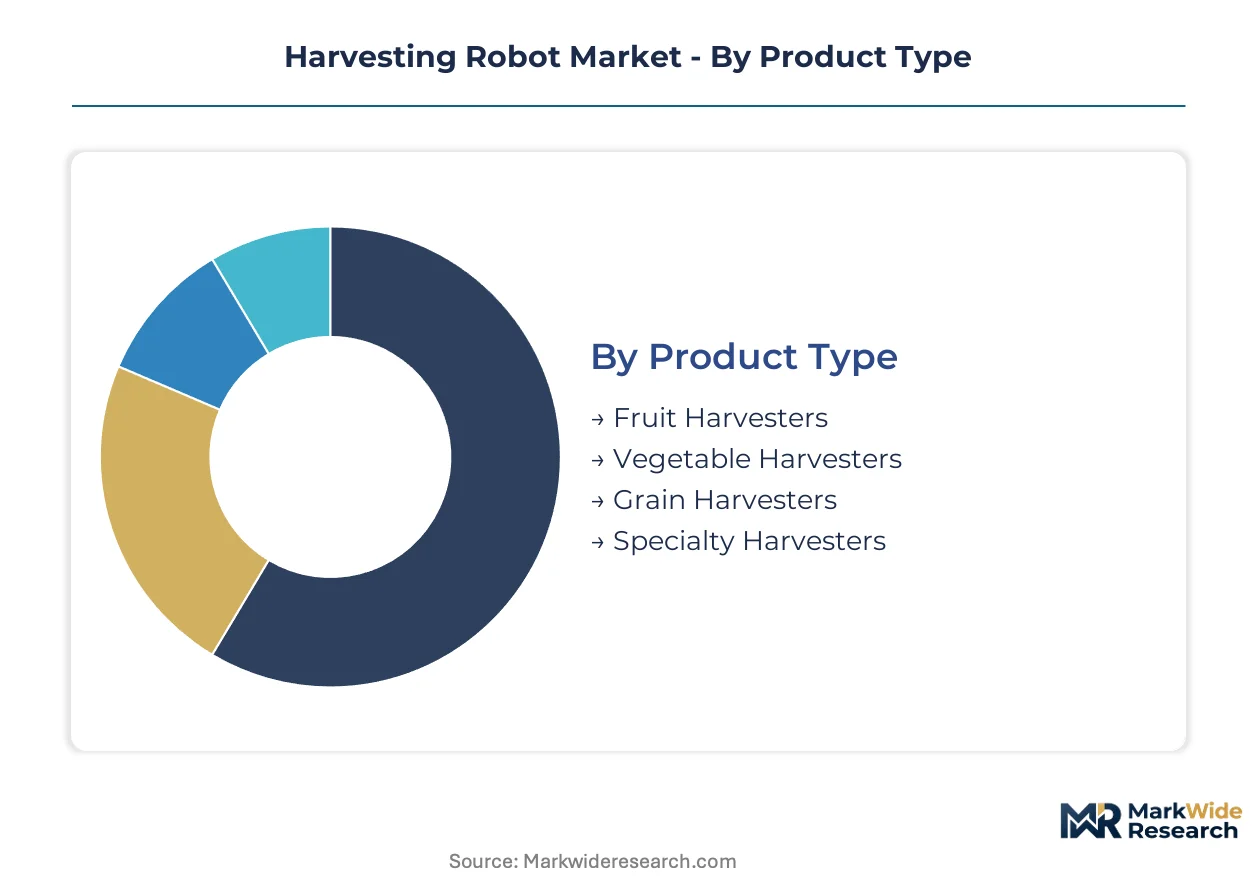
Harvesting robot architectures vary sharply across crop type, operator scale, and autonomy level. Segmentation reveals where regulatory pressure, labor economics, and technical complexity concentrate commercial opportunity.
Product Type:
EPA Tier 4 Final and EU F-Gas Regulation create divergent compliance burdens across propulsion and handling subsystems. Diesel particulate mandates favor electric platforms in vegetable and grain categories, while gentle-handling protocols for soft-skinned produce impose additional certification complexity on fruit harvesters.
- Fruit Harvesters:Articulated manipulators with pneumatic or soft-robotic grippers process RGB-D data to identify ripeness and minimize bruising. Demand clusters in California's Central Valley stone fruit operations and Mediterranean citrus belts where labor scarcity compresses payback thresholds. ISO 18497 functional safety requirements add eighteen to thirty-six months to development cycles for autonomous orchard platforms.
- Vegetable Harvesters:Crop uniformity in leafy green and root vegetable applications simplifies machine learning training datasets, accelerating deployment velocity. Greenhouse lettuce operations in Spain and Italy adopt third-party depth-sensing modules for retrofitting existing tractor platforms, displacing turnkey system purchases.
- Grain Harvesters:Mature segment with margin pools shifting from hardware sales to subscription-based fleet optimization software.
- Specialty Harvesters:Niche platforms for hops, nuts, and vineyard applications where crop-specific geometries resist standardization.
Grain harvesters handle the majority of throughput; vegetable harvesters are gaining share fastest on simplified perception requirements.
End User:
Procurement authority is concentrating at the enterprise level, displacing decentralized purchasing by individual farm managers. Cost tier differentiation separates capital-intensive autonomous platforms from semi-automated equipment accessible to smaller operators.
- Commercial Growers:Large-scale specialty crop operations in California and Australia's Murray-Darling Basin centralize technology vendor selection under dedicated automation divisions. These buyers command volume discounts and demand enterprise-scale service infrastructure, compressing sales cycles while raising barriers for niche suppliers.
- Agricultural Firms:Vertically integrated agribusinesses deploy harvesting robots across diversified crop portfolios to optimize capital utilization rates. Their procurement teams prioritize open-architecture platforms that integrate third-party perception stacks, avoiding proprietary lock-in.
- Family Farms:Capital constraints and smaller acreage limit adoption to cooperative purchasing arrangements or contract harvesting services.
- Organic Producers:Certification requirements for mechanical weeding compatibility influence gripper and cutting tool specifications.
Commercial growers deploy the largest fleet volumes; agricultural firms are expanding most quickly on portfolio diversification strategies.
Technology:
Customer type and application maturity determine which technology layers buyers prioritize. Volume buyers in grain operations favor proven autonomous navigation stacks, while specialty crop operators invest in frontier perception systems.
- Autonomous Navigation:GPS-RTK and LiDAR-based localization enable 24-hour continuous field operations where manual labor availability fluctuates seasonally. Grain belt deployments in the US and Ukraine prioritize reliability metrics over handling sophistication.
- Sensor-Based Systems:Multispectral imaging combined with depth sensing dominates tree-fruit applications where bruise-free protocols command premium pricing.
- AI Integration:Edge-computing inference engines process ripeness classification in real-time, reducing dependency on cloud connectivity in rural bandwidth-constrained environments.
- Machine Learning:Training dataset quality varies sharply by crop uniformity; greenhouse environments enable faster model convergence than variable orchard canopies.
Sensor-based systems anchor current revenue; AI integration shows the steepest expansion trajectory on inference cost reductions.
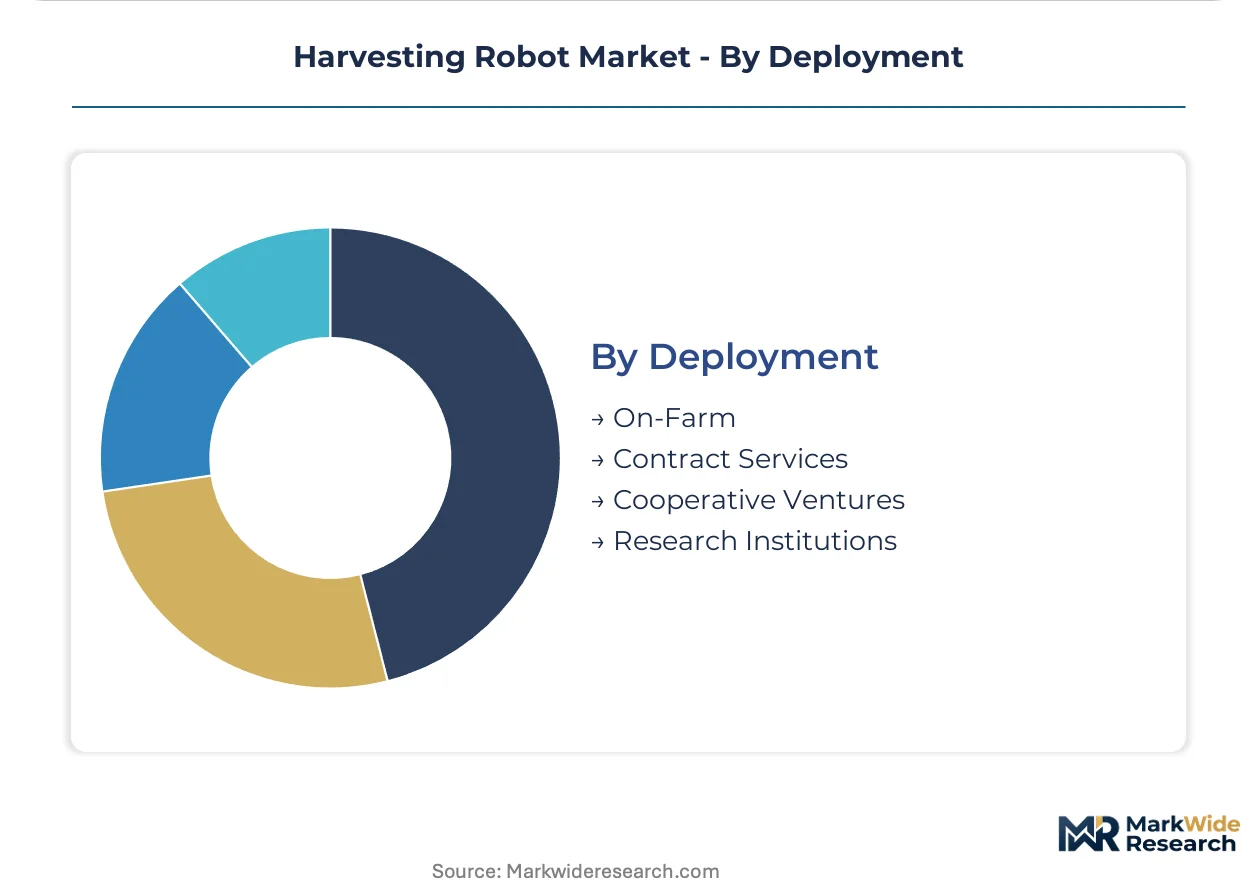
Deployment:
Supply concentration in battery cell manufacturing and mechatronics talent pools shapes which deployment models achieve economic viability. Asset-light strategies gain traction where capital scarcity or technical risk aversion prevails.
- On-Farm:Direct ownership models dominate among commercial growers with sufficient acreage to achieve utilization rates above 60 percent. These operators absorb ISO 18497 compliance costs and maintain in-house maintenance capabilities.
- Contract Services:Third-party harvesting providers deploy robotic fleets across multiple client properties, spreading capital recovery over larger effective acreage. Eastern European grain operations increasingly rely on Polish and Romanian contract harvesters to avoid equipment ownership risk.
- Cooperative Ventures:Shared-ownership structures enable smaller producers to access autonomous platforms through regional machinery rings.
- Research Institutions:University and government experimental stations test prototype systems before commercial scale-up.
On-farm deployment retains the largest installed base; contract services are climbing the fastest on risk-transfer preferences among mid-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli-developed soft-robotic grippers export to California's Central Valley specialty crop belt, while German precision engineering firms supply autonomous navigation stacks to Mediterranean orchard operators across Spain and Italy.
United States
California's Central Valley stone fruit and nut operations drive demand for gentle-handling harvesters as labor scarcity compresses payback periods below three years. EPA Tier 4 Final emissions mandates force powertrain electrification roadmaps for equipment sold nationwide. Fresno and Kern counties anchor the densest concentration of commercial grower deployments, with enterprise automation divisions centralizing procurement authority.
Spain
Greenhouse lettuce and spinach operations in Almería and Murcia adopt third-party depth-sensing modules for retrofitting existing tractor platforms. EU F-Gas Regulation phase-down creates bundled procurement incentives for zero-emission harvesting platforms across Mediterranean orchard belts. Valencia's citrus belt experiences accelerating robotic penetration as seasonal labor availability fluctuates unpredictably.
Germany
Precision engineering clusters around Stuttgart and Munich supply LiDAR-based localization systems and fail-safe actuation architectures for autonomous agricultural machinery. ISO 18497 functional safety certification requirements from German-standard-setting bodies determine market access eligibility across multiple jurisdictions. Bavarian research institutions test prototype stone-fruit harvesters before commercial scale-up.
China
Cathode precursor refining concentration for lithium-ion cells creates input cost volatility for electric platform manufacturers targeting export markets. National agricultural mechanization subsidies under the dual carbon goals framework accelerate domestic adoption of battery-electric harvesters. Shandong Province's industrial machinery corridor hosts component suppliers for articulated manipulator subsystems.
Australia
Murray-Darling Basin specialty crop operations centralize technology vendor selection under dedicated automation divisions, mirroring California procurement patterns. Seasonal harvest worker visa program restrictions intensify capital substitution toward autonomous selective harvesters. Queensland's macadamia and avocado orchards represent emerging demand pockets for RGB-D perception-enabled platforms.
Harvesting Robot Market Competitive Landscape
Player mix skews toward diversified agricultural equipment conglomerates with entrenched dealer networks, though specialized robotics firms occupy defined niches in soft-fruit handling. Three strategic archetypes dominate: legacy manufacturers with captive distribution, open-architecture platform builders integrating third-party perception stacks, and narrow specialists in crop-specific gripper technologies. Competitive moves concentrate on strategic partnerships with sensor fusion developers and geographic expansion through contract harvesting service models rather than direct equipment sales.
Within the legacy equipment tier, Deere & Company and AGCO Corporation exemplify divergent platform strategies—one leveraging closed proprietary ecosystems, the other pursuing interoperability. FFRobotics sits within the specialist archetype, its company name signaling dedicated focus on tree-fruit robotic systems. These three anchors illustrate how competitive positioning fragments across integration depth versus specialization breadth trade-offs.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| Clearpath Robotics Inc. |
| AgEagle Aerial Systems Inc. |
| YANMAR HOLDINGS CO., LTD |
| Kubota Corporation |
| FFRobotics |
| Harvest Automation |
| Harvest CROO Robotics LLC |
| Others |
Pricing and Supply Chain Analysis
ISO 18497 functional safety certification gates market access eligibility while simultaneously stratifying price tiers across autonomous harvesting platforms, forcing buyers to absorb compliance premiums or accept performance-limited alternatives.
Pricing Analysis
Next-generation RGB-D perception stacks command three-to-five-fold premiums over prior-generation camera-only systems, while legacy diesel platforms face accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels separates fully autonomous orchard harvesters with soft-robotic grippers from semi-automated tractor retrofits and basic grain platforms. Price differentiation hinges on ISO 18497 certification tier and after-sales service bundling. Cost compression in mid-tier vegetable harvesters is intensifying because greenhouse operators prioritize component-level procurement over turnkey systems. Family farms exhibit highest price sensitivity, deferring adoption to contract harvesting arrangements.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and cathode precursors dominates inventory strategy as manufacturers buffer against Chinese refining concentration. Component sourcing draws from China for battery cells, Germany for precision actuation systems, and Israel for soft-robotic gripper modules. Critical dependencies include rare-earth magnets for manipulator motors, high-purity silicon for depth sensors, and specialty polymers for gentle-handling end-effectors. Single-source vulnerability in cathode precursor refining creates geopolitical exposure for electric platform roadmaps. Distribution runs through entrenched agricultural equipment dealer networks with captive service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional engineering teams combining computer vision, robotic manipulation, and agricultural domain expertise command compensation premiums that constrain R&D scaling, creating a persistent talent bottleneck across the vendor ecosystem.
For Market Incumbents: Consolidate gripper technology specialists through targeted acquisitions to secure soft-fruit handling IP before niche players achieve escape velocity. Expand captive battery assembly capacity in Poland or Hungary to mitigate Chinese cell supply concentration and satisfy EU carbon border adjustment requirements. Lock in long-term cathode supply agreements with Korean refiners diversifying outside China. For New Entrants and Emerging Players: Lead with greenhouse lettuce and spinach harvesting modules where crop uniformity accelerates machine learning convergence and shrinks development cycles versus variable orchard environments. Contract harvesting service models in Eastern European grain belts transfer capital risk to operators while building fleet utilization data. Partner with Spanish and Italian tractor retrofitters to bypass entrenched dealer channel barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vegetable harvester sub-segments as component-level procurement displaces integrated platform sales. Five-to-ten-year viability favors vendors with recurring software revenue streams over pure hardware plays. Acquisition targets should exhibit proven RGB-D perception integration and existing ISO 18497 certification progress. The signal to watch is contract harvesting fleet utilization rates crossing sustainable economic thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Soft-Robotic Gripper Acquisition | Secures bruise-free handling IP for stone fruit and berry penetration against FFRobotics specialization. |
| Battery Supply Agreement | Locks in Korean or European cell volumes to satisfy EPA electrification roadmaps and EU F-Gas bundled procurement. |
| ISO 18497 Certification Investment | Enables market access across German-standard-setting jurisdictions and reduces liability exposure for autonomous deployments. |
| Greenhouse Retrofit Partnership | Accelerates volume through Almería and Murcia lettuce operations with simplified perception requirements. |
| Subscription Fleet Software Launch | Migrates grain harvester margin pools from transactional hardware to recurring optimization revenue with customer lock-in. |
Research Methodology
A standing panel of commercial grower automation directors, agricultural equipment procurement leads, robotic systems integration engineers, and dealer network operations managers provided ongoing calibration against field deployment realities. Primary interviews combined with secondary validation from EPA Tier 4 Final regulatory filings, EU F-Gas Regulation implementation guidance, SEC 10-K equipment manufacturer disclosures, and agricultural machinery trade association production statistics. Bottom-up unit deployment estimates triangulated against top-down addressable acreage calculations.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler agricultural technology investment disclosures and regional machinery registration databases. The analytical framework modeled segmentation across crop type, autonomy level, propulsion architecture, and operator scale throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to historical mechanization adoption patterns in comparable agricultural equipment categories. Industry-specific inputs included seasonal labor availability indices and carbon border adjustment mechanism implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cost declines or abrupt geopolitical supply disruptions would require recalibration. Forecasts reflect assumptions regarding EPA and EU regulatory trajectory continuity, RGB-D sensor cost reduction curves, and commercial grower consolidation rates. Revision becomes warranted when contract harvesting fleet utilization rates or ISO 18497 certification backlog durations cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Europe Cloud Robotics Market