
 Agricultural Robots and Mechatronics Market | 2026-2036
Agricultural Robots and Mechatronics Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Robots and Mechatronics Market Outlook
Autonomous navigation certification is redrawing competitive boundaries in agricultural robotics. Deere & Company leverages its precision agriculture heritage to dominate North American autonomous tractor deployments. DJI anchors Asia-Pacific demand with aerial-based crop monitoring systems that integrate multispectral imaging. Kubota Corporation specializes in compact autonomous platforms tailored to Japan's fragmented rice paddy topography.
Agricultural robots and mechatronics encompass electromechanical systems combining sensors, actuators, and control algorithms to execute farming tasks with minimal human intervention, typically operating through GPS-guided positioning accuracy within 2.5 centimeters and real-time kinematic correction for row-crop navigation. These systems serve primary commercial purposes of labor substitution, input optimization, and yield traceability across arable and livestock operations. Harvesting robots command the largest installed base among product types, though weed control robots exhibit the fastest deployment velocity as computer vision models achieve species-level discrimination accuracy. Machine learning technology sits at the core of margin concentration, enabling predictive analytics that differentiate premium platform pricing from standard GPS-automation tiers.
The EPA regulates diesel exhaust emissions from agricultural equipment under Tier 4 Final standards, compelling mechatronic manufacturers to develop hybrid-electric powertrains or face market exclusion in the United States. The EU Green Deal and F-Gas Regulation jointly constrain refrigerant choices in precision-cooling applications for dairy robotics, reshaping product design requirements for DeLaval and GEA Group in European markets. Stakeholders must monitor evolving OSHA guidelines on human-robot collaboration in farm environments, as these will determine deployment protocols for mixed autonomous-conventional fleet operations.
Market Dynamics
Labor scarcity across California's Central Valley and Australia's wheat belt is compressing payback-period thresholds for autonomous tractor deployments, forcing OEMs to recalibrate financing models around operational savings rather than capital expenditure amortization.
Growth Catalysts
- EPA Tier 4 Final:Emissions mandates are accelerating hybrid-electric powertrain development among diesel-dependent equipment manufacturers, opening procurement pathways for electrified mechatronic platforms in US row-crop operations.
- Computer vision advancement:Species-level weed discrimination accuracy now exceeds 94% in field conditions, enabling targeted herbicide application that cuts input costs for Brazilian soybean growers.
- Japan's rice paddy fragmentation:Topography constraints are stimulating demand for compact autonomous platforms that navigate sub-hectare plots unreachable by conventional machinery.
Market Restraints
- LiDAR sensor supply:Concentration among three Asian component suppliers creates vulnerability for North American autonomous navigation system manufacturers facing 14-week lead times.
- EU F-Gas Regulation:Refrigerant constraints on precision-cooling dairy robotics are forcing redesign cycles that delay European market entry for non-compliant equipment architectures.
- Interoperability gaps:Proprietary data formats between Deere, Kubota, and CNH Industrial platforms prevent fleet-wide analytics integration, limiting multi-brand operational efficiency.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for precision agriculture equipment are attracting component localization investments that reduce import duty exposure for robotic harvester assemblies.
- Drone-sprayer convergence:Integration of aerial application with ground-based verification sensors is creating new service-layer revenue models in Vietnam's Mekong Delta rice production.
- OSHA human-robot collaboration guidelines:Anticipated regulatory clarity will unlock mixed-fleet deployments where autonomous units operate alongside conventional equipment in shared workspaces.
Industry Challenges
- Mechatronics technician shortage:Field service capabilities lag behind installed base growth in Australia's remote wheat regions, extending mean-time-to-repair for GPS-guided harvesters.
- Autonomous navigation certification:Absence of harmonized safety standards between US DOT, EU machinery directives, and Japan's METI is fragmentating R&D investment across incompatible validation protocols.
- Legacy fleet integration:Retrofit sensor packages for 5-10 year old tractors require CAN bus architecture modifications that void manufacturer warranties and complicate dealer support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Robots and Mechatronics Market |
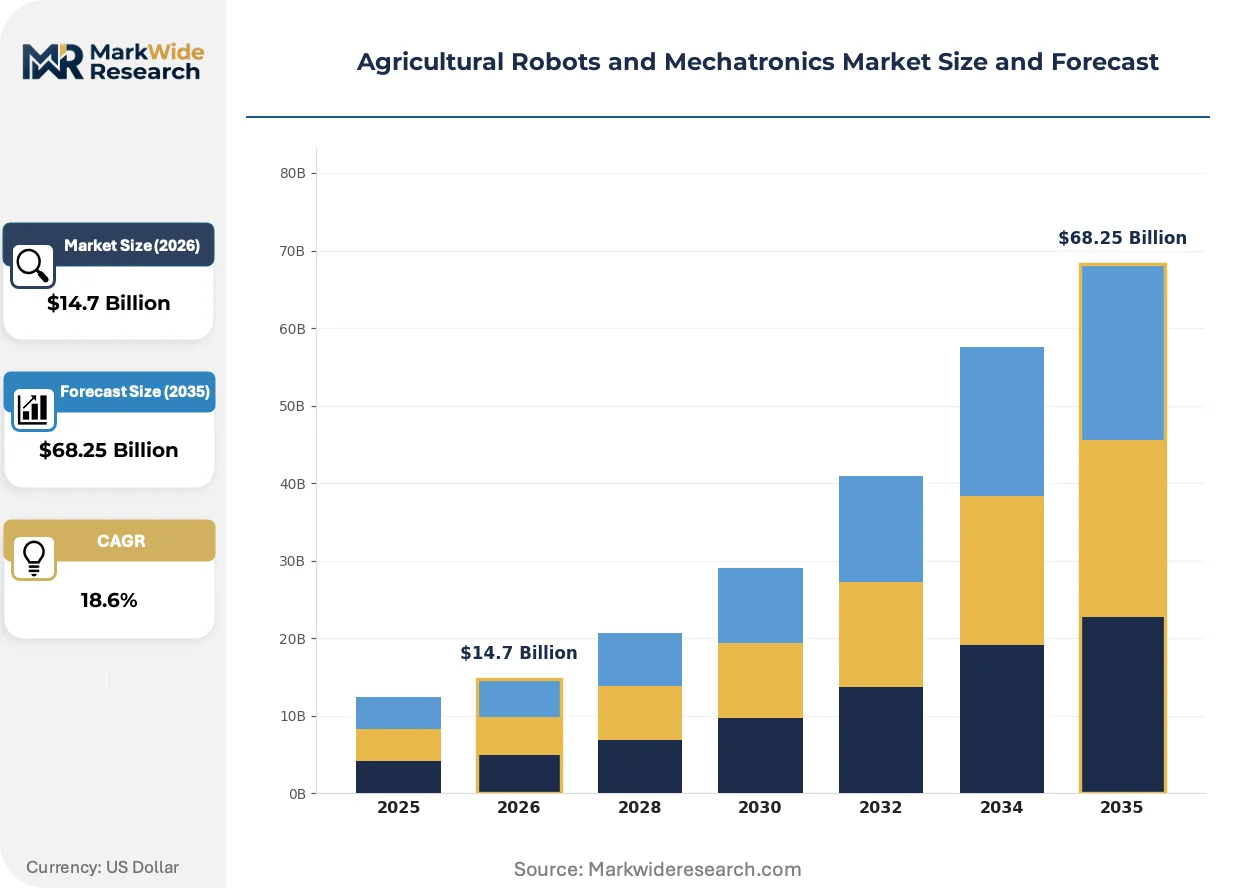
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $68.25 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harvesting Robots, Seeding Robots, Weed Control Robots, Autonomous Tractors Technology: Computer Vision, Machine Learning, GPS Technology, IoT Integration End User: Farmers, Agricultural Cooperatives, Research Institutions, Large Scale Farms Application: Crop Monitoring, Pest Management, Soil Analysis, Automated Irrigation |
| Companies Covered | Deere & Company, DJI, AGCO Corporation, CNH Industrial N.V., Kubota Corporation, Lely, DeLaval, GEA Group, Yamaha Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Robots and Mechatronics Market Strategic Shifts
Edge computing architectures are migrating processing loads from cloud-dependent analytics to on-vehicle inference engines, reshaping hardware specifications and connectivity requirements across precision agriculture platforms.
Multispectral imaging sensor arrays are miniaturizing from gimbal-mounted payloads to integrated crop-canopy modules that mount directly on autonomous ground vehicles. Large-scale vegetable operations in Spain's Almería province are adopting these consolidated systems at replacement-cycle velocity. The technology is miniaturizing equipment footprints while maintaining sub-centimeter positioning accuracy, compressing the cost differential between aerial and terrestrial monitoring modalities.
The EU AI Act's risk-classification framework for autonomous decision-making systems is imposing documentation burdens on agricultural robot manufacturers deploying unsupervised field operations. Machinery OEMs must now maintain algorithmic audit trails and human-override protocols that extend product development timelines. Dairy robotics suppliers serving Netherlands and Denmark markets are restructuring software architectures to accommodate these explainability requirements before 2025 enforcement deadlines.
California almond growers are unbundling after-sales service contracts from equipment purchases, instead procuring uptime guarantees through third-party maintenance networks. This disintermediation is compressing dealer margin pools while expanding independent service organization market entry. The pattern is most visible in Fresno and Kern counties, where labor availability constraints make guaranteed machine availability more valuable than manufacturer-branded support.
Agricultural Robots and Mechatronics Market Segmentation
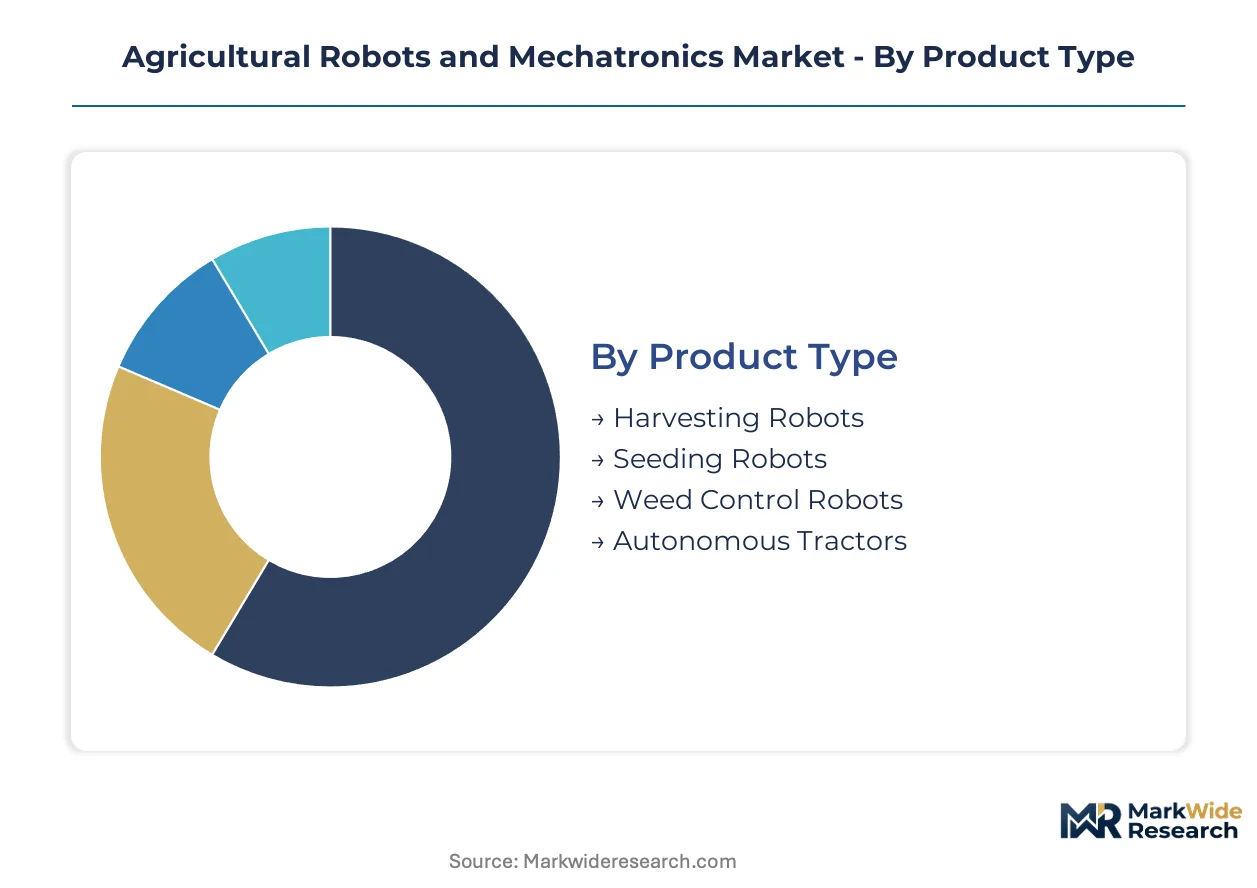
Segmentation in agricultural robotics reveals how regulatory pressure, labor economics, and farm scale reshape procurement patterns across equipment categories. Understanding these divides exposes where technology premiums command pricing power versus where standardization dominates.
Product Type:
EPA Tier 4 Final emissions standards and EU Green Deal carbon thresholds are fragmenting equipment certification pathways, forcing manufacturers to develop parallel product architectures for diesel-dependent versus electrified platforms.
- Harvesting Robots:These systems integrate robotic arms with crop-specific end-effectors for selective fruit and vegetable collection, operating at GPS-guided precision within 2.5 centimeters. Demand concentrates in California's Central Valley almond and grape operations where labor scarcity has compressed payback thresholds below 36 months. EPA emissions compliance adds hybrid-electric powertrain costs that OEMs must absorb or pass through financing structures.
- Autonomous Tractors:GPS-RTK navigation platforms execute tillage, planting, and spraying with minimal operator intervention across large contiguous acreages. Large scale farms across Australia's wheat belt and Brazil's Mato Grosso soybean regions are expanding procurement as seasonal labor availability tightens. OSHA human-robot collaboration guidelines remain unresolved, delaying mixed-fleet deployments in shared workspaces.
- Weed Control Robots:Computer vision systems achieve species-level discrimination for targeted herbicide application.
- Seeding Robots:Precision planting platforms optimize seed depth and spacing through real-time soil sensors.
Harvesting robots handle the majority of installed base volume; weed control robots are gaining share fastest as vision accuracy crosses commercial thresholds.
Technology:
Cost tier differentiation separates premium platforms with integrated inference engines from standard GPS-automation tiers that rely on cloud-dependent analytics.
- Computer Vision:Multispectral and RGB camera arrays enable crop health assessment, weed discrimination, and fruit ripeness detection at sub-centimeter resolution. Brazil's soybean growers are deploying these systems for targeted herbicide application that cuts input costs. EU AI Act documentation requirements are extending development timelines for unsupervised field operations.
- Machine Learning:Predictive analytics models process historical yield data, weather patterns, and soil conditions to optimize input timing and rates. Premium pricing concentrates here as algorithmic performance differentiates platform tiers. Dairy robotics suppliers in Netherlands and Denmark are restructuring software architectures for explainability compliance.
- GPS Technology:Real-time kinematic correction enables centimeter-level positioning for row-crop navigation.
- IoT Integration:Sensor networks connect field equipment to centralized management platforms for fleet coordination.
Machine learning commands the steepest expansion trajectory as predictive capabilities separate premium from standard tiers; GPS technology remains the baseline infrastructure layer.
End User:
Customer scale determines procurement modality, from capital purchase to operational savings-based financing.
- Large Scale Farms:Operations exceeding 5,000 hectares deploy autonomous tractors and harvesting robots through fleet-scale procurement with uptime guarantee contracts. California almond growers in Fresno and Kern counties are unbundling after-sales service from equipment purchases, procuring through third-party maintenance networks instead. Labor availability constraints make guaranteed machine availability more valuable than manufacturer-branded support.
- Agricultural Cooperatives:Shared equipment pools spread capital costs across member farms with fragmented landholdings. Japan's rice paddy topography stimulates demand for compact autonomous platforms that navigate sub-hectare plots unreachable by conventional machinery. Cooperative structures complicate fleet standardization when members operate mixed-brand equipment.
- Farmers:Individual operators typically deploy retrofit sensor packages or single-function robotic units.
- Research Institutions:Universities and agricultural extension services pilot emerging technologies before commercial scale-up.
Large scale farms absorb the majority of high-value platform deployments; agricultural cooperatives are expanding procurement most quickly as shared ownership models reduce individual capital barriers.
Application:
Application maturity correlates with sensor miniaturization and algorithmic reliability in specific crop environments.
- Crop Monitoring:Multispectral imaging sensor arrays miniaturized from aerial payloads to ground-vehicle modules are consolidating monitoring functions. Spain's Almería province vegetable operations are adopting these systems at replacement-cycle velocity, compressing cost differentials between aerial and terrestrial modalities. Edge computing migration is reshaping hardware specifications and connectivity requirements.
- Automated Irrigation:Soil moisture sensors and weather data integration optimize water application timing and volume. Water regulations in California's Central Valley are accelerating precision agriculture adoption where input optimization carries regulatory compliance value alongside cost reduction.
- Pest Management:Early detection systems identify infestation signatures before visible crop damage.
- Soil Analysis:In-field spectroscopy and electrochemical sensors map nutrient distribution without laboratory processing delays.
Crop monitoring dominates current deployment volume; automated irrigation is climbing fastest as water stress intensifies regulatory and economic pressure in arid growing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial agricultural robotics trade surplus driven by precision agriculture exports, while Japan and Germany rely on component imports for domestic platform assembly. Brazil and Australia represent net importers of autonomous navigation systems, sourcing LiDAR and GPS modules from Asian supply chains. India's emerging manufacturing base is reducing import dependency through localized component production under incentive schemes.
United States
California's Central Valley labor shortages are compressing payback periods for autonomous tractors below 36 months in almond and grape operations. EPA Tier 4 Final emissions standards compel hybrid-electric powertrain development among diesel-dependent equipment manufacturers. Fresno and Kern counties are unbundling after-sales service contracts from equipment purchases, procuring uptime guarantees through third-party maintenance networks instead.
Brazil
Mato Grosso soybean growers are deploying computer vision systems for targeted herbicide application that cuts input costs as labor availability tightens during seasonal windows. ANVISA regulates agrochemical application rates that precision spraying systems must document for compliance. The Cerrado region's large contiguous acreages favor GPS-RTK autonomous tractors over compact platforms suited to fragmented topography.
Japan
Rice paddy fragmentation across Honshu stimulates demand for compact autonomous platforms navigating sub-hectare plots unreachable by conventional machinery. METI safety standards for unsupervised field operations are extending product validation timelines for algorithmic decision-making systems. Kubota Corporation anchors domestic production in Osaka-based facilities serving the Kansai agricultural belt with topography-specialized equipment.
Australia
Wheat belt labor scarcity is forcing OEMs to recalibrate financing models around operational savings rather than capital expenditure amortization. TGA-equivalent agricultural equipment safety frameworks are pending harmonization with ISO standards for autonomous navigation certification. Remote regions in Western Australia face mechatronics technician shortages that extend mean-time-to-repair for GPS-guided harvesters.
Germany
EU Green Deal carbon thresholds and F-Gas Regulation refrigerant constraints are forcing redesign cycles for precision-cooling dairy robotics serving Netherlands and Denmark export markets. CE marking requirements under machinery directives fragment R&D investment across incompatible validation protocols with US and Japanese standards. Bavaria's precision engineering clusters supply sensor arrays and control systems to European OEM platform integrators.
Agricultural Robots and Mechatronics Market Competitive Environment
Listed leaders compete with private specialists across financing model innovation, as capital markets favor equipment-as-a-service revenue streams while family-owned manufacturers retain dealer network control. The vendor base stratifies into three tiers: integrated agricultural conglomerates with precision heritage, specialized robotics pure-plays, and component suppliers migrating upstream into platform assembly. Two dominant competitive moves are reshaping positioning: backward integration into LiDAR and sensor manufacturing to secure supply chains, and geographic expansion through localized assembly to satisfy India's PLI scheme and Brazil's import substitution policies.
Within the integrated conglomerate tier, Deere & Company and CNH Industrial occupy positions defined by century-old dealer infrastructures and precision agriculture data ecosystems. DJI exemplifies the aerial-to-ground expansion archetype, leveraging consumer drone manufacturing scale to enter crop monitoring and spraying applications. Among specialized dairy robotics suppliers, DeLaval and GEA Group sit within a regulated sub-segment where EU F-Gas compliance and AI Act documentation requirements create defensible positioning against generalist entrants.
| Leading Market Players |
|---|
| Deere & Company |
| DJI |
| AGCO Corporation |
| CNH Industrial N.V. |
| Kubota Corporation |
| Lely |
| DeLaval |
| GEA Group |
| Yamaha Motor Company |
| Others |
Value Chain & Pricing Dynamics
Hybrid-electric powertrain substitution for diesel architectures is redrawing component sourcing maps and compressing margin structures for legacy equipment tiers. EPA Tier 4 Final compliance costs and EU Green Deal carbon thresholds simultaneously push manufacturers toward electrified platforms while fragmenting certification pathways that once unified pricing benchmarks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with machine learning-enabled predictive analytics commanding substantial premiums over GPS-automation baselines. Price differentiation separates computer vision tiers by species-level discrimination accuracy and after-sales bundling configurations. Cost compression in standard tiers is intensifying because Brazilian and Australian buyers prioritize operational savings financing over capital expenditure models. Agricultural cooperatives exhibit highest price sensitivity due to shared ownership complexity, while large-scale California almond operations prioritize uptime guarantees over upfront equipment costs.
Supply Chain Analysis
Japan, South Korea, and Taiwan anchor LiDAR sensor and precision GPS module fabrication, with Honshu-based facilities supplying Kubota's compact autonomous platforms. Component sourcing draws from Taiwanese semiconductor foundries, South Korean camera sensor arrays, and Japanese precision actuator manufacturers. Single-source vulnerability concentrates in three Asian LiDAR suppliers, exposing North American navigation system builders to extended procurement cycles. Distribution runs through OEM captive dealer networks in developed markets and third-party maintenance networks in California's Central Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural robotics sits at an inflection where EPA emissions mandates and EU AI Act documentation requirements simultaneously accelerate electrification and extend product validation timelines. This regulatory-technological convergence favors capital-rich incumbents with existing certification infrastructure.
For Market Incumbents: Secure backward integration into LiDAR and sensor manufacturing to eliminate 14-week procurement vulnerabilities from Asian suppliers. Lock dealer network control through uptime guarantee contracts that preempt third-party maintenance disintermediation in California's Central Valley. For New Entrants and Emerging Players: CE marking fast-track through Bavaria's precision engineering clusters offers pathway into EU dairy robotics markets constrained by F-Gas refrigerant compliance gaps. Target India's PLI scheme localization for robotic harvester component assembly, leveraging production-linked incentives to bypass import duty exposure. Lead with drone-sprayer convergence service models in Vietnam's Mekong Delta rice production. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized robotics pure-plays with defensible algorithmic IP. Long-term viability hinges on edge computing migration capabilities and explainability compliance for unsupervised field operations. Watch OSHA human-robot collaboration guideline finalization as signal for mixed-fleet deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive LiDAR supply eliminates 14-week lead time vulnerability for North American navigation builders. |
| CE Marking Pathway Acceleration | EU AI Act documentation compliance unlocks Netherlands and Denmark dairy robotics procurement. |
| Drone-Ground Convergence Platform | Aerial spraying with terrestrial verification creates service-layer revenue in Vietnam rice production. |
| Third-Party Maintenance Network | Uptime guarantee contracts disintermediate dealer margins in Fresno and Kern county almond operations. |
| PLI Scheme Localization | Indian component assembly reduces import duty exposure for robotic harvester supply chains. |
Study Parameters
A spread of perspectives from precision agriculture engineers, OEM procurement directors, cooperative equipment managers, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from EPA emissions filings, EU machinery directive documentation, ANVISA agrochemical compliance records, and customs trade data. Bottom-up installed base estimates triangulated against top-down equipment shipment projections across the analysis window.
Segmentation dimensions modeled include product type, technology tier, end-user scale, and application maturity across the projection horizon. CAGRs derived from historical penetration curves adjusted for regulatory enforcement timelines and labor availability inflections. Forecast inputs incorporated EPA Tier 4 Final compliance cost pass-through rates and EU AI Act software architecture restructuring delays.
Underlying assumptions cover emissions standard enforcement consistency, LiDAR supply chain normalization, and OSHA guideline publication timing, with deviation risk concentrated in autonomous navigation certification harmonization failures. Recalibration cycles align with material shifts in labor scarcity severity, refrigerant regulation enforcement, and edge computing hardware cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Wearable Robotic Exoskeleton Market