
 Laboratory Robotics Market | 2026-2036
Laboratory Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Robotics Market Outlook
Polymer-based lightweight frames are displacing traditional aluminum chassis in benchtop robotic arms, which is realigning cost structures for mid-tier automation vendors. Thermo Fisher Scientific leverages its consumables-recurring model to anchor long-term installation contracts. Hudson Robotics specializes in compact workcell configurations for academic core facilities. Tecan Trading AG controls premium positioning in liquid handling through proprietary tip-washing architectures that reduce per-run plastic waste.
Laboratory robotics encompasses electromechanical systems designed to execute repetitive protocols—liquid transfer, sample sorting, plate handling—with positional accuracy typically below 0.1 millimeter and throughput rates exceeding 1,000 wells per hour. These systems eliminate human variability in quantitative assays while enabling 24-hour operation in regulated environments. Automated liquid handlers command the largest installed base among product categories, though chemistry analyzers carry higher per-unit service margins due to reagent lock-in structures. Drug discovery applications absorb the dominant share of capital allocation within the end-use portfolio, while DNA sequencing workflows are expanding fastest as next-generation sequencing pipelines multiply.
FDA 21 CFR Part 11 governs electronic records and signatures for systems deployed in GLP-compliant laboratories, compelling vendors to embed audit-trail functionality at the firmware level. ISO 13485 quality management requirements shape design controls for robotics destined for in-vitro diagnostic workflows in Europe and Asia-Pacific markets. Stakeholders must weigh software automation architectures against evolving cybersecurity frameworks as cloud-connected instruments become standard in multi-site research networks.
Market Dynamics
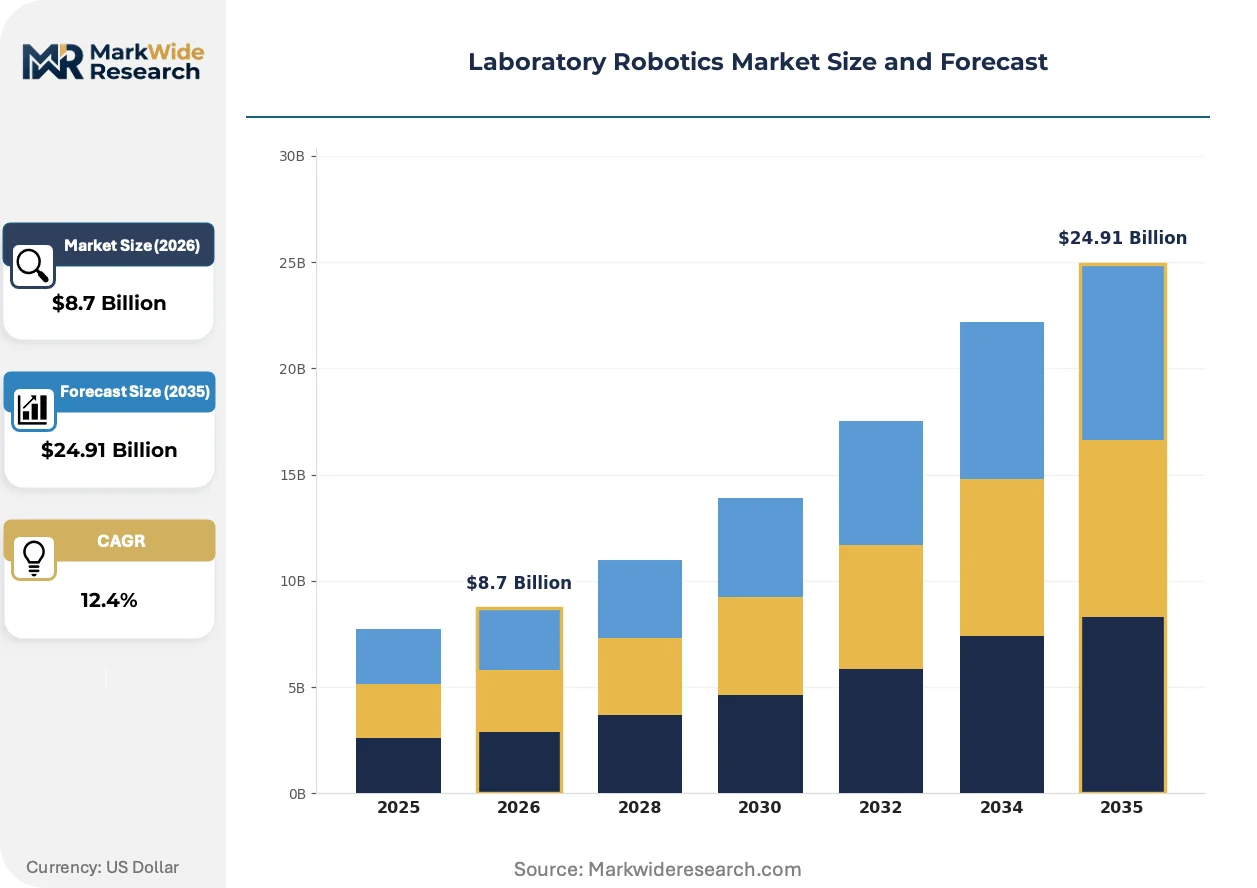
Pharmaceutical firms are compressing assay timelines through fleet expansion of automated liquid handlers, while FDA 21 CFR Part 11 compliance mandates are elevating firmware-level audit-trail requirements across procurement specifications. This dual pressure on speed and validation is restructuring vendor-customer contracting terms.
Growth Catalysts
- NIH Funding Intensity:United States federal research allocations are accelerating capital deployment into Boston and San Diego biotech clusters, concentrating demand for high-throughput screening infrastructure.
- ISO 13485 Harmonization:European quality management requirements for in-vitro diagnostic workflows are standardizing design controls, reducing regulatory friction for cross-border equipment deployment.
- Polymer Frame Substitution:Lightweight chassis materials are reducing per-unit manufacturing costs for mid-tier benchtop robotic arms, expanding addressable markets for academic core facilities.
Market Restraints
- Reagent Lock-in Structures:Chemistry analyzers carry elevated service margins through proprietary consumable dependencies, creating switching costs that limit vendor diversification.
- Precision Component Concentration:Sub-0.1 millimeter positional accuracy requirements concentrate supply of linear actuators and optical encoders among specialized Japanese and German component manufacturers.
- Cybersecurity Framework Gaps:Cloud-connected multi-site instruments face evolving NIST and ISO 27001 compliance burdens that extend validation timelines before commercial deployment.
Strategic Opportunities
- DNA Sequencing Pipeline Expansion:Next-generation sequencing workflows represent underpenetrated automation territory as sample volumes multiply beyond manual processing capacity.
- Academic Core Facility Modernization:Compact workcell configurations are capturing replacement cycles at university research centers previously served by refurbished equipment.
- Tip-Washing Architecture Adoption:Proprietary liquid handling systems that reduce per-run plastic waste align with institutional sustainability procurement criteria.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of firmware-level audit trails with electromechanical systems requires specialized controls engineers that outpace current vocational pipeline output.
- Legacy Equipment Interoperability:Retrofitting 24-hour operation capability into existing laboratory information management systems demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Robotics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Liquid Handlers, Chemistry Analyzers, Robotic Arms, Sample Management Systems End User: Biotechnology Companies, Pharmaceutical Firms, Research Institutions, Hospital Laboratories Application: High-Throughput Screening, DNA Sequencing, Drug Discovery, Cell Culture Technology: Machine Learning, Artificial Intelligence, Vision Systems, Software Automation |
| Companies Covered | Thermo Fisher Scientific Inc., Peak Analysis and Automation, Hudson Robotics, Anton Paar GmbH, AB Controls, Siemens Healthineers AG, Tecan Trading AG, Agilent Technologies, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Robotics Market Strategic Shifts
Automation architectures are converging with cloud connectivity and sustainability mandates, compressing the traditional boundary between hardware procurement and software service layers. Vendors must now embed compliance functionality at the firmware level while demonstrating waste reduction credentials.
Collaborative robotic arms with force-torque sensing are converging with machine vision systems to enable adaptive pipetting in unstructured laboratory environments. Academic medical centers and contract research organizations are piloting these configurations for cell culture workflows. This convergence is converging with cloud-based protocol libraries to compress method development timelines from weeks to days.
EMA's MDR and FDA's evolving cybersecurity guidance for networked medical devices are mandating pre-market submission of software bill of materials. Equipment manufacturers must now document third-party code dependencies and vulnerability management procedures. Liquid handling platforms destined for diagnostic workflows face the steepest compliance burden, with European notified bodies requiring ISO 14971 risk management files.
Research institutions are unbundling after-sales service contracts from capital equipment purchases, preferring time-and-materials arrangements or third-party maintenance providers. This behavior shift disrupts traditional recurring revenue models anchored to proprietary consumables. The pattern is most visible in United States academic core facilities, where reduced indirect cost recovery rates are forcing operational expenditure scrutiny.
Laboratory Robotics Market Segmentation
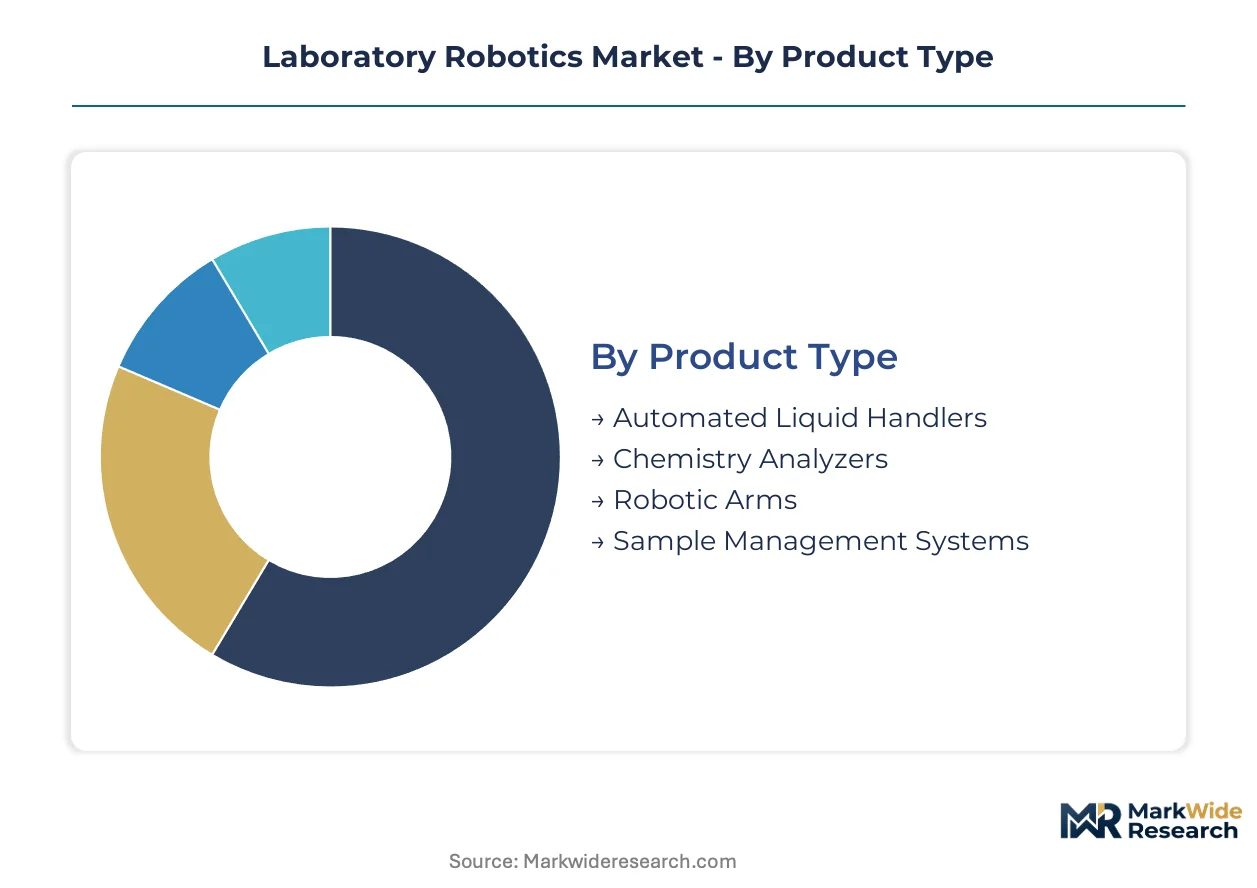
Segmentation in laboratory robotics reveals divergent procurement priorities across buyer types. Pharmaceutical firms prioritize throughput specifications and validation documentation, while academic core facilities emphasize footprint constraints and service flexibility.
Product Type:
Cost tier differentiation separates premium precision systems from mid-tier configurable platforms.
- Automated Liquid Handlers:These systems execute sub-microliter transfers with positional accuracy below 0.1 millimeter, anchoring high-throughput screening infrastructure in Boston and San Diego biotech clusters. Fleet expansion among pharmaceutical firms is compressing assay timelines while elevating firmware-level audit-trail requirements.
- Chemistry Analyzers:Reagent lock-in structures generate elevated service margins through proprietary consumable dependencies, creating switching costs that limit vendor diversification. Demand concentrates in hospital laboratories seeking diagnostic workflow automation.
- Robotic Arms:Polymer-based lightweight frames are displacing traditional aluminum chassis, realigning cost structures for mid-tier automation vendors serving academic core facilities.
- Sample Management Systems:These platforms integrate barcode tracking with environmental monitoring for biorepository applications, capturing replacement cycles at research institutions.
Automated liquid handlers lead volumes today; sample management systems are gaining share fastest.
End User:
Application maturity shapes capital deployment cycles and service contract structures.
- Biotechnology Companies:These firms deploy compact workcell configurations for next-generation sequencing pipelines, with procurement decisions driven by NIH funding intensity and cloud-connected multi-site instrument requirements.
- Pharmaceutical Firms:GLP-compliant laboratories mandate FDA 21 CFR Part 11 firmware functionality, restructuring vendor-customer contracting terms toward outcome-based validation support.
- Research Institutions:Reduced indirect cost recovery rates are forcing operational expenditure scrutiny, with unbundling of after-sales service contracts from capital equipment purchases.
- Hospital Laboratories:ISO 13485 quality management requirements shape design controls for in-vitro diagnostic workflows, with European notified bodies requiring ISO 14971 risk management files.
Pharmaceutical firms anchor current procurement volumes; biotechnology companies show the steepest expansion trajectory.
Application:
Protocol complexity determines automation architecture specifications and integration middleware requirements.
- High-Throughput Screening:Throughput rates exceeding 1,000 wells per hour eliminate human variability in quantitative assays, with 24-hour operation capability demanding custom middleware development for legacy laboratory information management systems.
- DNA Sequencing:Next-generation sequencing workflows represent underpenetrated automation territory as sample volumes multiply beyond manual processing capacity, with collaborative robotic arms and machine vision systems enabling adaptive pipetting.
- Drug Discovery:This application absorbs the dominant share of capital allocation, with EMA's MDR and FDA's evolving cybersecurity guidance mandating pre-market submission of software bill of materials.
- Cell Culture:Academic medical centers and contract research organizations are piloting force-torque sensing configurations for unstructured laboratory environments.
Drug discovery commands the largest installed base; DNA sequencing is climbing the fastest.
Technology:
Software layer integration is compressing the traditional boundary between hardware procurement and service contracts.
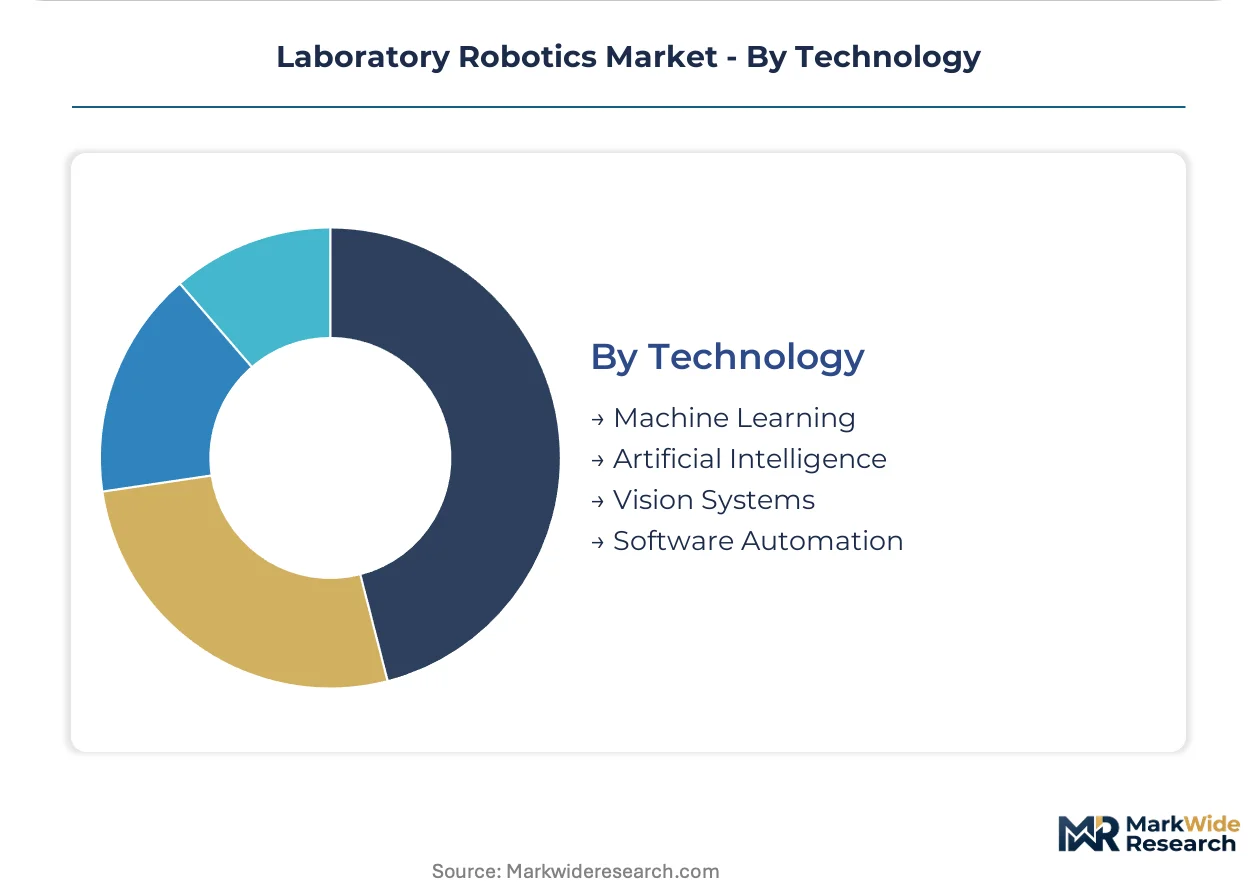
- Machine Learning:Cloud-based protocol libraries compress method development timelines from weeks to days, converging with collaborative robotic architectures in pilot deployments.
- Artificial Intelligence:Adaptive pipetting algorithms enable real-time trajectory adjustment, though mechatronics talent scarcity constrains firmware-audit-trail integration.
- Vision Systems:Machine vision convergence with force-torque sensing supports unstructured environment operation, with NIST and ISO 27001 compliance burdens extending validation timelines.
- Software Automation:Firmware-level audit-trail functionality addresses FDA 21 CFR Part 11 mandates, while third-party code dependencies require vulnerability management documentation for European notified bodies.
Software automation leads current deployment; machine learning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston and San Diego biotech clusters anchor procurement intensity for laboratory robotics infrastructure, with NIH funding concentration driving capital deployment into high-throughput screening systems across multiple continents.
United States
Federal research allocations through NIH and biotech venture density propel automated liquid handler fleet expansion. FDA 21 CFR Part 11 mandates firmware-level audit trails across GLP-compliant procurement. The Boston metropolitan area concentrates drug discovery automation demand, while San Diego anchors next-generation sequencing pipeline investments.
Germany
Precision component manufacturing and in-vitro diagnostic workflow standardization drive chemistry analyzer demand. EMA MDR and ISO 13485 requirements shape design controls for European market entry. The Baden-Württemberg region hosts specialized linear actuator and optical encoder suppliers serving sub-0.1 millimeter accuracy specifications.
China
Domestic pharmaceutical R&D expansion and academic core facility modernization accelerate mid-tier benchtop robotic arm procurement. NMPA regulatory harmonization with international quality standards shapes cross-border equipment validation. The Yangtze River Delta biotech corridor concentrates demand for compact workcell configurations.
Japan
Specialized mechatronics component supply and pharmaceutical quality management excellence sustain premium positioning. METI industrial policy supports precision manufacturing capabilities for linear motion systems. The Kanto region around Tokyo concentrates controls engineering talent for firmware-audit-trail integration.
Switzerland
Pharmaceutical headquarters concentration and diagnostic workflow automation sustain liquid handling platform demand. Swissmedic regulatory requirements align with European MDR frameworks for pre-market submissions. The Basel biopharma cluster drives specification-setting for tip-washing architectures reducing plastic waste.
Laboratory Robotics Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors embed firmware-level compliance functionality and cloud connectivity into multi-year service contracts. The vendor base clusters around three tiers: diversified life science conglomerates with consumables-recurring models, specialized automation houses with compact workcell expertise, and precision component-integrated systems builders. Archetypes include full-stack platform providers, academic-core-focused configurators, and premium liquid-handling specialists. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping market structure.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. exemplifies the consumables-anchored contracting model, while Danaher Corporation occupies a position spanning diagnostic and research workflows. Among specialized automation houses, Hudson Robotics represents the compact workcell configuration archetype targeting academic core facilities. On the premium liquid-handling vector, Tecan Trading AG sits within the tip-washing architecture specialization reducing per-run plastic waste.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Peak Analysis and Automation |
| Hudson Robotics |
| Anton Paar GmbH |
| AB Controls |
| Siemens Healthineers AG |
| Tecan Trading AG |
| Agilent Technologies |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
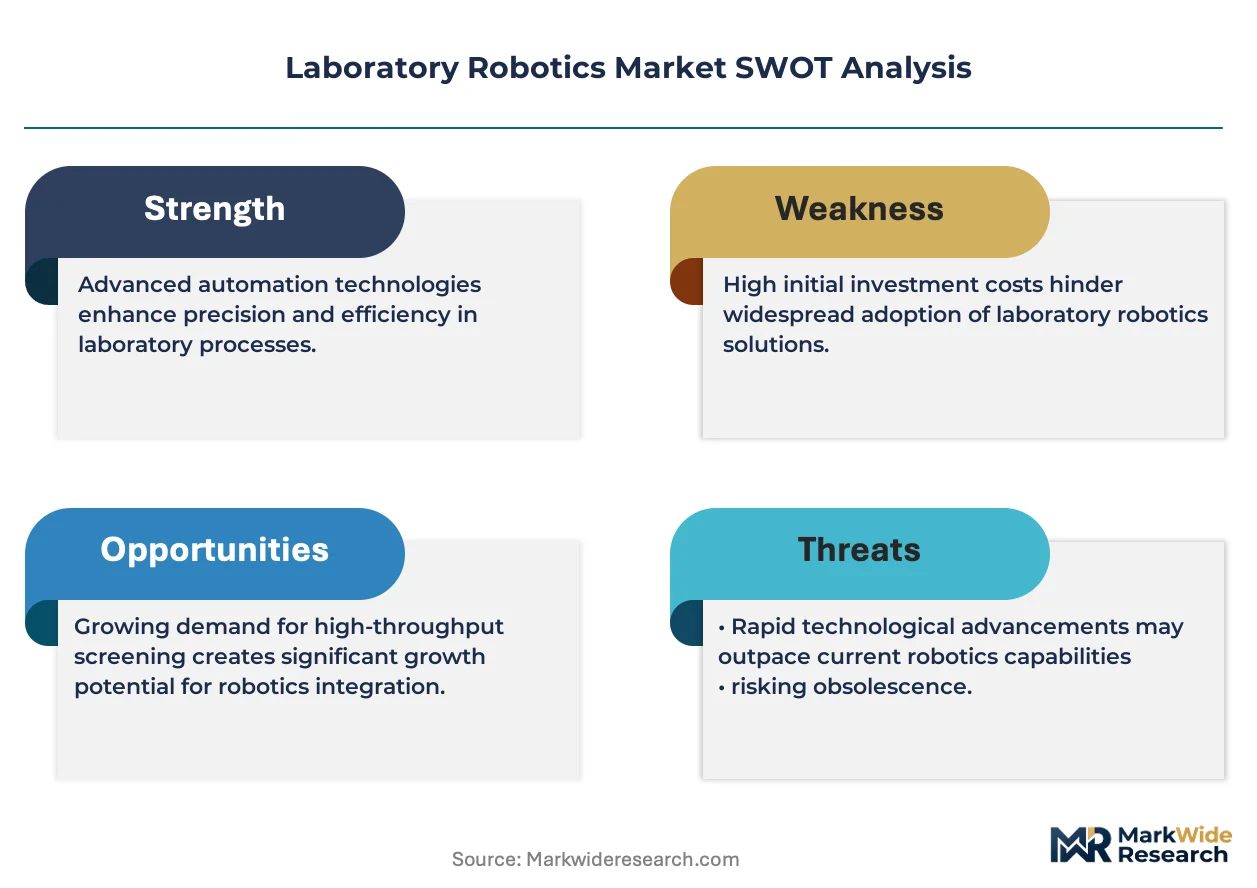
FDA 21 CFR Part 11 firmware mandates are forcing component suppliers to embed audit-trail functionality at the electromechanical level, which concentrates procurement leverage among vendors with in-house controls engineering capabilities and compresses margins for assembly-only integrators.
Pricing Analysis
Linear actuator and optical encoder costs from Japanese and German specialists pass through directly to system pricing, with premium liquid handling platforms commanding three-tier pricing structure across premium, standard, and economy levels based on positional accuracy certification and after-sales bundling. Academic core facilities exhibit highest price sensitivity due to reduced indirect cost recovery rates, while pharmaceutical GLP laboratories prioritize validation documentation over unit economics. Pricing pressure stems from polymer frame substitution lowering mid-tier benchtop robotic arm manufacturing costs.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg, Kanto, and the Yangtze River Delta anchor hub-and-spoke fulfillment for precision mechatronics components. Supply draws from specialized Japanese linear motion manufacturers, German optical encoder producers, and Chinese polymer frame fabricators. Single-source vulnerability concentrates in sub-0.1 millimeter accuracy actuators. Distribution runs through vendor-direct channels for pharmaceutical customers and academic distributors for core facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory robotics functions as a stable compounder anchored by NIH funding intensity and biotech cluster expansion, with recurring consumables revenue providing defensive cash flow visibility through replacement cycles.
For Market Incumbents: To counter unbundling of after-sales service contracts by academic core facilities, anchor long-term installation agreements through consumables-recurring models and deepen backward integration into proprietary tip-washing architectures that reduce per-run plastic waste and create switching costs. For New Entrants and Emerging Players: Academic distributors represent the most accessible channel partner type for compact workcell configurations targeting university research centers previously served by refurbished equipment, with DNA sequencing pipeline automation offering the most penetrable white-space application as sample volumes multiply beyond manual capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized automation houses possessing firmware-audit-trail integration capabilities and compact workcell expertise, with long-term viability hinging on cloud-connected multi-site instrument deployment penetration and the signal to watch being NIST cybersecurity framework adoption rates across pharmaceutical procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Level Compliance Investment | Embedded audit-trail functionality addresses FDA 21 CFR Part 11 mandates for GLP laboratories. |
| Tip-Washing Architecture Development | Proprietary liquid handling systems align procurement criteria with institutional sustainability mandates. |
| Academic Channel Partnership | Compact workcell configurations capture replacement cycles at university core facilities. |
| Cloud Connectivity Integration | Multi-site instrument networking enables protocol library sharing across distributed research networks. |
| Polymer Frame Manufacturing Scale-Up | Lightweight chassis materials expand addressable markets for mid-tier automation vendors. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with laboratory directors, automation procurement managers, regulatory affairs specialists, and core facility operations leads with secondary validation against FDA 510(k) filings, NIH grant disbursement databases, ISO certification registries, and vendor annual disclosures.
Historical trendline analysis of installed base expansion and replacement cycle timing informs the projection framework across product type, end user, application, and technology segmentation dimensions, with CAGRs derived from regression-weighted scenario modeling incorporating NIH funding trajectory assumptions and biotech cluster formation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cybersecurity framework evolution and mechatronics talent pipeline constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Robot Pedestal Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Robotics and Automation Actuators Market