
 Robot As a Service Market | 2026-2036
Robot As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Robot As a Service Market Analytics
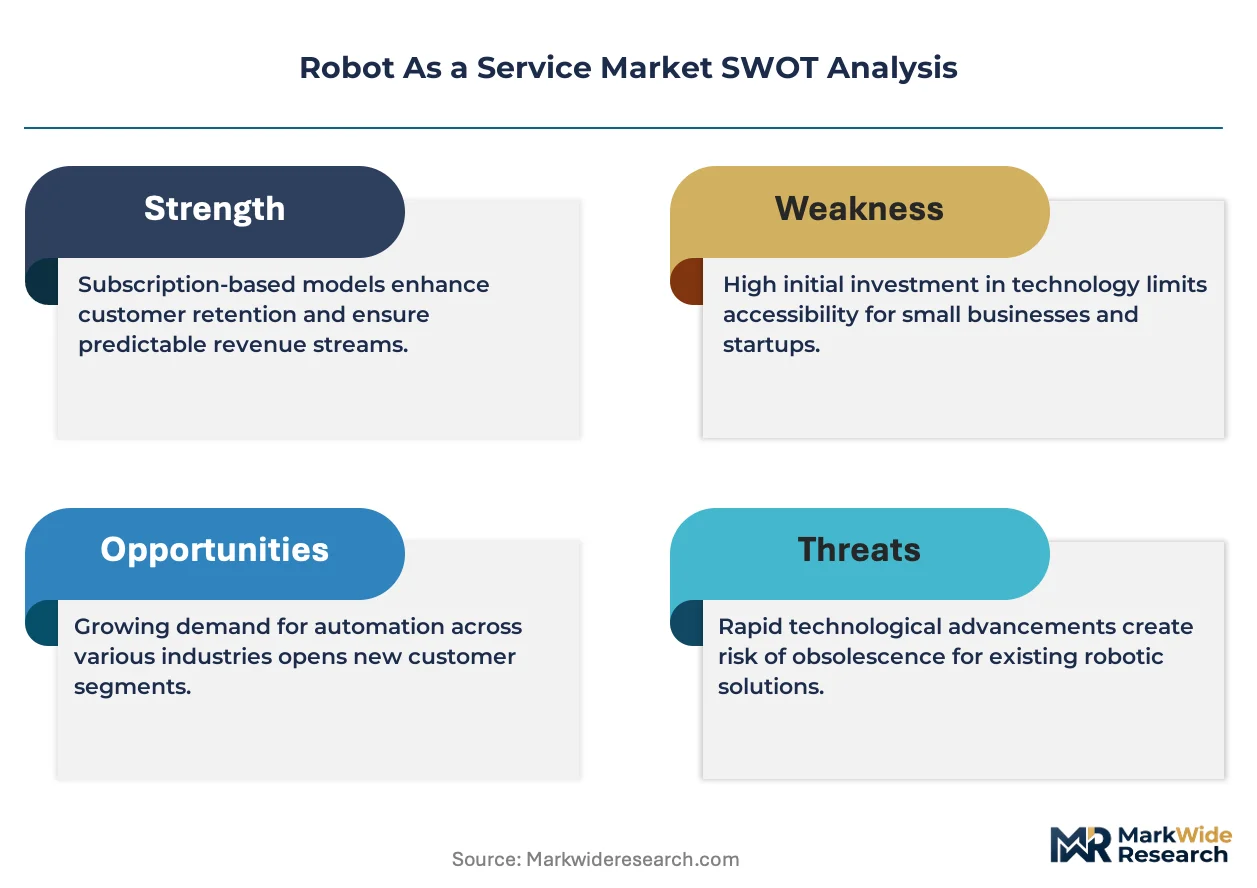
The Robot As a Service sector is consolidating around two distinct performance tiers. Premium offerings integrate real-time fleet analytics, predictive maintenance, and dedicated field engineering, while commodity tiers compete on per-hour rental rates with minimal software overlay. Intuitive Surgical leverages its installed base of surgical systems to anchor high-margin service contracts that bundle training and instrument replenishment. Berkshire Grey specializes in AI-driven warehouse automation, differentiating through vision-guided pick-and-place capabilities that reduce human touchpoints.
Robot As a Service denotes a commercial model where robotic hardware, software, maintenance, and operational support are delivered through recurring subscription or usage-based contracts rather than outright purchase, typically encompassing payload capacities from sub-kilogram delivery bots to multi-ton industrial arms with 0.1-millimeter repeatability. The model shifts capital expenditure to operational expenditure while guaranteeing uptime through vendor-managed servicing and remote diagnostics. Manufacturing and logistics applications lead current deployment volumes, reflecting structural demand for flexible automation that scales with seasonal order fluctuations. Cloud-based deployment models are expanding fastest as edge-to-cloud orchestration enables centralized fleet optimization across distributed facilities.
The U.S. Food and Drug Administration governs surgical and diagnostic robot service offerings through premarket clearance pathways, while the Occupational Safety and Health Administration sets workplace exposure limits that shape collaborative robot design and service liability frameworks. In Europe, the Machinery Directive and CE marking requirements dictate safety integrity levels for rented robotic equipment, creating compliance cost differentials between regional and global service providers. Stakeholders must weigh regulatory divergence against standardization economies when architecting cross-border service platforms.
Market Dynamics
Cloud robotics architectures are compressing deployment timelines from months to weeks, enabling warehousing operators to scale automation incrementally without capital-intensive infrastructure overhauls. This shift from ownership to subscription is restructuring vendor-buyer relationships around uptime guarantees and remote fleet management.
Growth Catalysts
- Labor Shortages in Logistics:Warehousing and logistics operators now represent the fastest-expanding buyer segment as workforce gaps intensify across fulfillment networks.
- CE Marking Harmonization:The Machinery Directive's safety integrity requirements are creating standardized compliance pathways that reduce cross-border service deployment friction for EU-based providers.
- API-First Fleet Management:Open integration protocols are enabling third-party software layers that accelerate multi-vendor robot orchestration without proprietary lock-in.
Market Restraints
- Sensor Cost Volatility:LiDAR and precision vision components remain concentrated among Asian component suppliers, exposing service providers to input price swings.
- Cybersecurity Liability Gaps:Remote diagnostics and cloud-based fleet control create attack surfaces that standard industrial insurance frameworks do not adequately cover.
- Interoperability Standards Lag:Absence of unified communication protocols forces service providers to maintain redundant integration layers across heterogeneous hardware fleets.
Strategic Opportunities
- German Manufacturing Automation:Elevated industrial automation budgets and mature subscription financing infrastructure create favorable conditions for premium service tier expansion.
- Edge-to-Cloud Orchestration:Convergence of 5G private networks and containerized robotics software enables real-time centralized optimization across distributed facilities.
- US Inflation Reduction Act:Domestic production incentives for advanced manufacturing equipment are reducing effective hardware costs for American-based RaaS fleet operators.
Industry Challenges
- Mechatronics Talent Scarcity:Field engineering capabilities for predictive maintenance and emergency repair remain concentrated among a limited pool of specialized technicians.
- OSHA Collaborative Robot Certification:Workplace exposure limit compliance for human-robot interaction requires extended validation cycles that delay service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot As a Service Market |
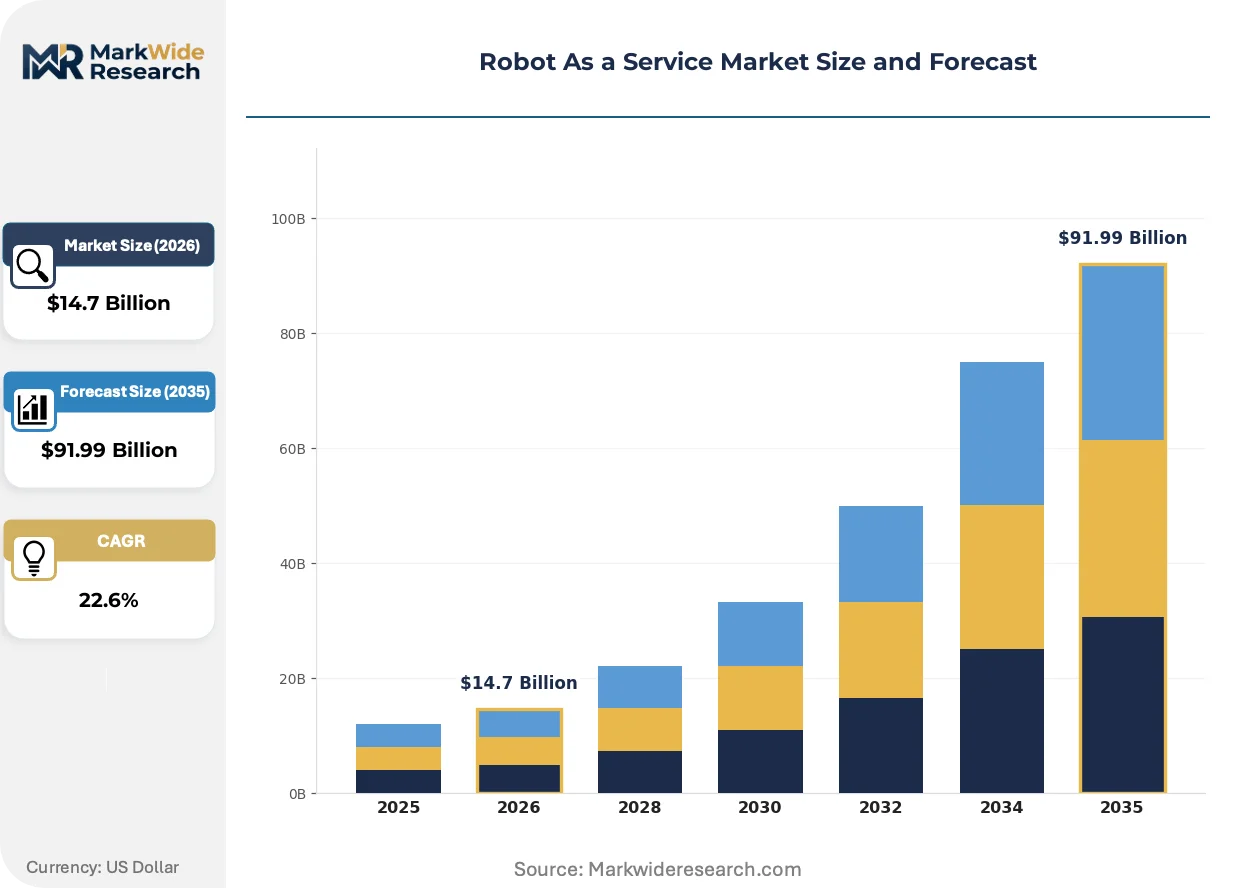
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $91.99 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Delivery, Manufacturing Application: Hospitality, Retail, Logistics, Agriculture End User: Commercial, Residential, Industrial, Educational Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Intuitive Surgical, iRobot Corporation, Berkshire Grey, Aethon, KUKA AG, Daifuku Co., Ltd., inVia Robotics, Locus Robotics, Exotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot As a Service Market Evolving Landscape
Real-time fleet analytics and predictive maintenance capabilities are separating premium service tiers from commodity rental offerings, reshaping how vendors compete for long-term contracts.
Containerized robotics software stacks are consolidating control architectures across previously incompatible hardware platforms. Third-party logistics providers are adopting these unified orchestration layers to mix autonomous mobile robots from multiple vendors within single warehouse footprints. This interoperability is compressing vendor switching costs and enabling multi-supplier fleet strategies that were technically infeasible three years ago.
The EU AI Act's risk classification framework is imposing documentation and human-oversight requirements on autonomous robotic systems deployed in public-facing or safety-critical environments. Manufacturers of collaborative robots must now maintain algorithmic audit trails and performance monitoring dashboards that service providers integrate into subscription offerings. German industrial users are responding by demanding CE-marked AI governance modules as standard contract inclusions.
Subscription financing is displacing capital expenditure models among mid-market manufacturers seeking seasonal automation flexibility. Equipment lessors and specialized RaaS platforms are capturing this demand by offering usage-based contracts with embedded maintenance and upgrade guarantees. This preference for operational expenditure treatment is most pronounced among automotive suppliers in the United States and Japan managing volatile production schedules.
Robot As a Service Market Segmentation
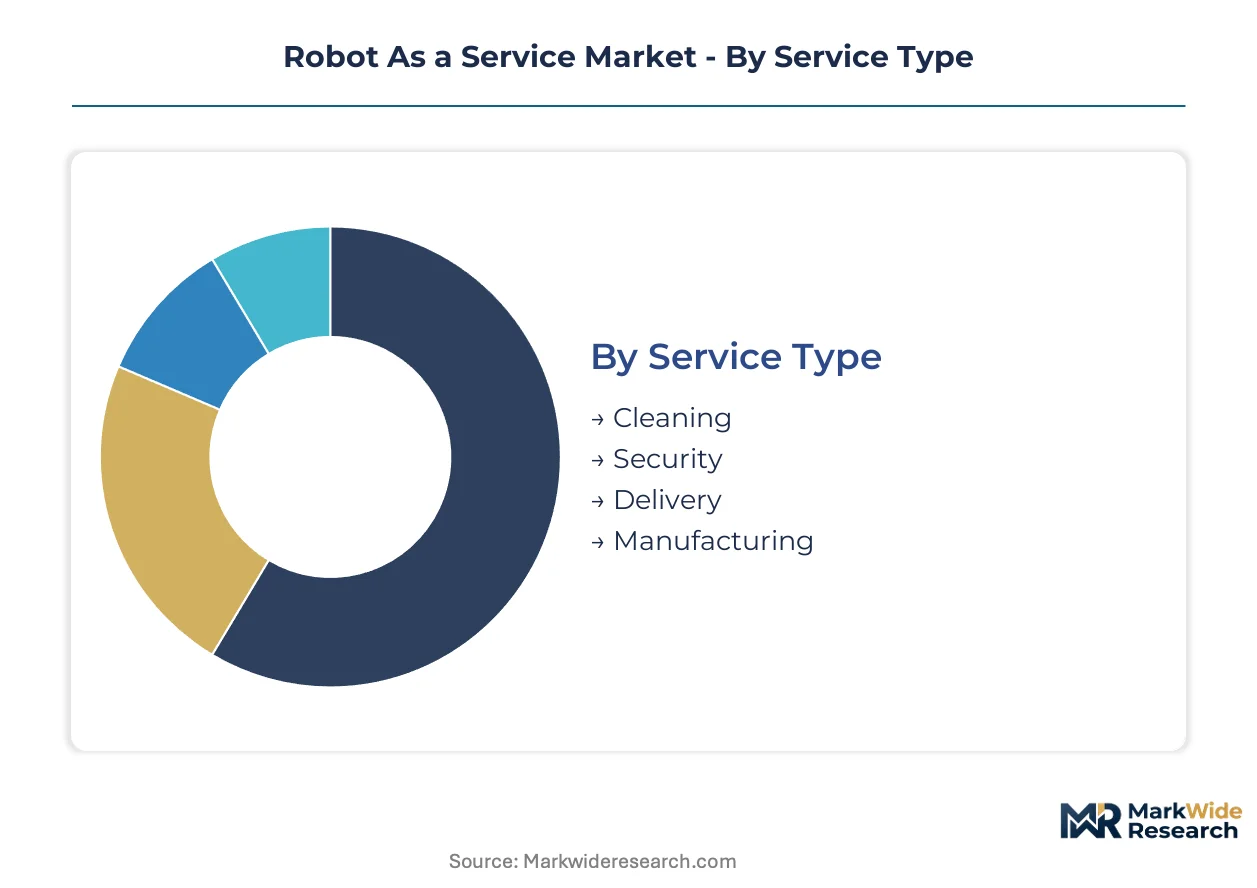
Service differentiation in Robot As a Service hinges on payload specifications, software integration depth, and vendor-managed maintenance intensity. Subscription pricing tiers cluster around these technical boundaries, with premium contracts bundling predictive analytics and dedicated field engineering.
Service Type:
Capital intensity varies sharply across service types, with Manufacturing deployments requiring the heaviest upfront sensor arrays and precision calibration infrastructure.
- Manufacturing:Multi-ton industrial arms with sub-millimeter repeatability dominate this tier. German automotive suppliers and Japanese electronics contract manufacturers anchor demand for these high-precision subscription contracts.
- Logistics:Vision-guided pick-and-place systems reduce human touchpoints in fulfillment networks. Warehousing operators in the United States represent the fastest-expanding buyer segment as labor shortages intensify across distribution centers.
- Cleaning:Autonomous floor-scrubbing units with LiDAR navigation serve commercial facilities. Hospitals and airports in Singapore and Dubai deploy these for overnight sanitation cycles.
- Security:Patrol robots with thermal imaging and acoustic anomaly detection monitor perimeters. Data centers and utility substations in Texas and California specify these for 24-hour coverage.
- Delivery:Sub-kilogram last-mile bots navigate sidewalks and building lobbies. University campuses and corporate parks in Seoul and Stockholm pilot these for internal mail distribution.
Manufacturing absorbs the bulk of installed capacity; Logistics is expanding most quickly.
Application:
Volume concentration follows e-commerce fulfillment density, with Logistics applications pulling the greatest robot-hours per facility.
- Logistics:Third-party fulfillment providers mix autonomous mobile robots from multiple vendors within single warehouse footprints. API-first fleet management platforms compress deployment timelines from months to weeks.
- Retail:Inventory-scanning robots traverse aisles to detect stockouts and pricing errors. Grocery chains in the United Kingdom and France deploy these for overnight shelf auditing.
- Hospitality:Concierge and room-service bots navigate elevator systems and guest corridors. Luxury hotels in Dubai and Las Vegas bundle these into guest experience packages.
- Agriculture:Crop-monitoring drones and autonomous harvesters operate on subscription models. Vineyards in California and olive groves in Spain trial these for seasonal labor replacement.
Logistics commands the greatest fleet density; Retail is climbing the fastest as in-store automation budgets recover.
End User:
Margin profiles diverge by buyer sophistication, with Industrial users demanding the most comprehensive uptime guarantees and field engineering support.
- Industrial:Manufacturing plants and heavy infrastructure operators specify 99.5% uptime SLAs with four-hour emergency response clauses. These contracts bundle training, spare parts, and algorithmic optimization.
- Commercial:Office buildings, hotels, and retail chains prioritize flexible scaling without capital expenditure. Subscription financing displaces outright purchase across mid-market buyers in Japan and Germany.
- Residential:Single-family homes and apartment complexes access lawn-mowing and basic security robots through monthly plans. Penetration remains concentrated in affluent suburbs of Sydney and Toronto.
- Educational:Universities and research institutes rent programmable platforms for robotics curriculum and experimental deployment. These contracts emphasize software access and hardware modularity over production throughput.
Industrial end users generate the highest contract values; Commercial is gaining share fastest as operational expenditure preference spreads.
Deployment Model:
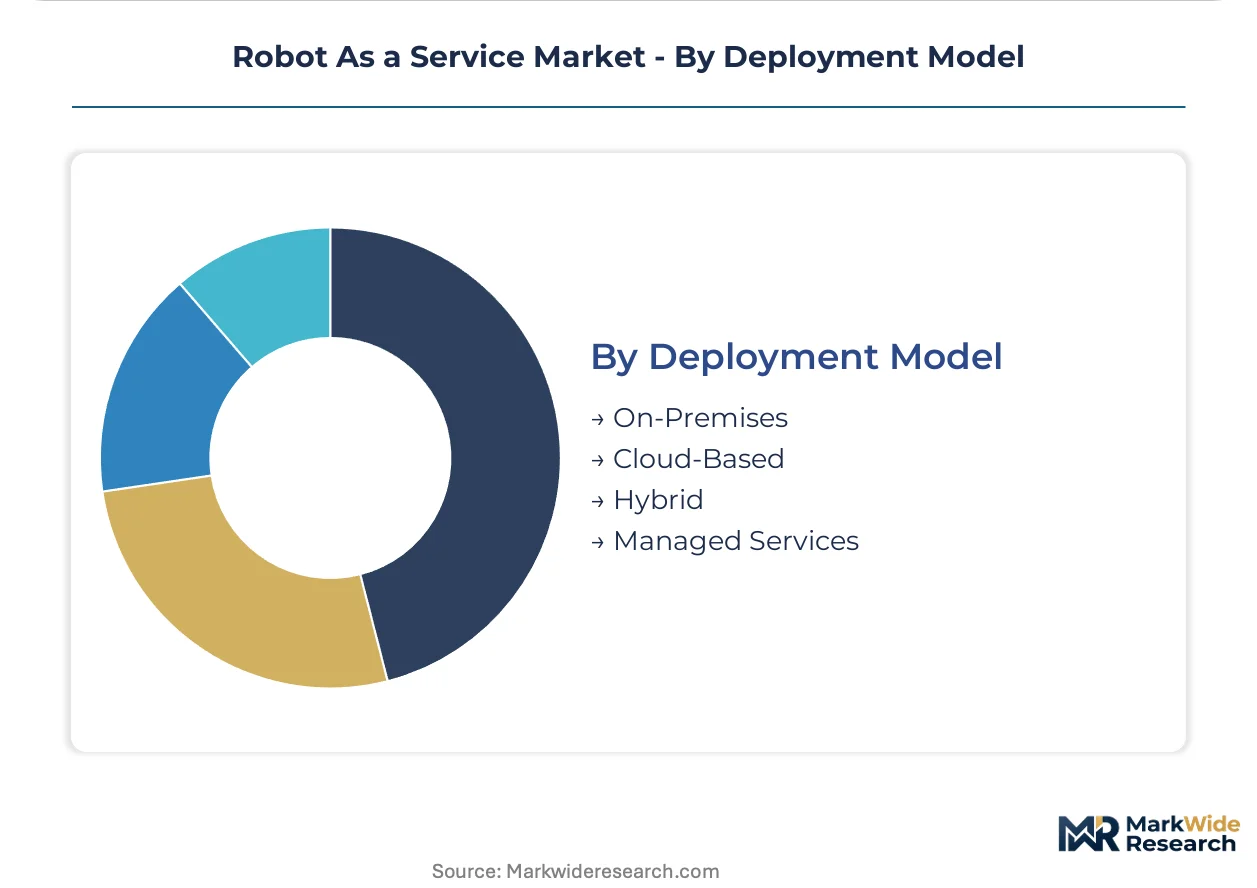
Technical architecture determines vendor lock-in intensity, with Cloud-Based models enabling the most centralized fleet optimization across distributed facilities.
- Cloud-Based:Edge-to-cloud orchestration enables real-time analytics and remote diagnostics. These deployments expand fastest as 5G private networks mature in Germany, Japan, and the United States.
- Managed Services:Vendors assume full operational responsibility including on-site technicians and performance-based billing. Pharmaceutical distributors and cold-chain logistics operators in Switzerland and the Netherlands prefer this hands-off structure.
- Hybrid:Critical control loops run locally while analytics and fleet coordination shift to cloud infrastructure. This architecture addresses cybersecurity liability gaps that standard industrial insurance frameworks do not adequately cover.
- On-Premises:Fully isolated systems satisfy data sovereignty requirements and air-gapped security policies. Defense contractors and nuclear facilities in France and the United Kingdom mandate this deployment mode.
Cloud-Based deployments absorb the greatest investment flow; Managed Services shows the steepest expansion trajectory as buyers seek to offload operational complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the densest concentration of Robot As a Service deployment in Europe, with automotive suppliers clustering around the Baden-Württemberg industrial corridor driving subscription automation adoption.
United States
Third-party logistics providers in Memphis and Louisville fulfillment networks represent the fastest-expanding buyer segment as labor shortages intensify across distribution centers. OSHA workplace exposure limits shape collaborative robot design and service liability frameworks for human-robot interaction. Dallas-Fort Worth data centers deploy security patrol robots with thermal imaging for 24-hour perimeter coverage.
Germany
Automotive suppliers in Stuttgart and Wolfsburg anchor demand for high-precision manufacturing subscription contracts with sub-millimeter repeatability requirements. CE marking requirements under the Machinery Directive dictate safety integrity levels for rented robotic equipment. Bavarian pharmaceutical distributors prefer managed services models with full operational responsibility and performance-based billing structures.
Japan
Electronics contract manufacturers in Osaka and Nagoya drive demand for flexible automation that scales with seasonal production fluctuations. METI industrial policy supports subscription financing infrastructure maturity among mid-market manufacturers. Tokyo Bay warehousing operators compress deployment timelines from months to weeks through API-first fleet management platforms.
Singapore
Changi Airport and public hospital networks deploy autonomous floor-scrubbing units with LiDAR navigation for overnight sanitation cycles. The country's national technology regulator imposes documentation requirements on autonomous systems in public-facing environments. One-North research corridor trials programmable platforms for robotics curriculum and experimental deployment.
South Korea
Seoul university campuses and corporate parks pilot sub-kilogram last-mile delivery bots for internal mail distribution. MFDS governance frameworks extend to diagnostic robot service offerings through premarket clearance pathways. Busan port logistics operators mix autonomous mobile robots from multiple vendors within single warehouse footprints.
Robot As a Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software integration depth and field engineering intensity. The sector consolidates around two distinct performance tiers: vendors bundling real-time fleet analytics and predictive maintenance command higher subscription rates, while competitors fight on per-hour rental rates with minimal software overlay. Three archetypes dominate: surgical system incumbents leveraging installed bases for service contract anchoring, AI-driven warehouse automation specialists, and diversified industrial robot manufacturers extending into subscription models. Competitive moves concentrate on strategic partnerships for API-first orchestration layers and geographic expansion through localized compliance expertise.
Within the precision-manufacturing archetype, KUKA AG and Daifuku Co., Ltd. occupy positions shaped by industrial automation heritage and logistics infrastructure integration respectively. Among warehouse-native specialists, Berkshire Grey exemplifies vision-guided automation differentiation, while Locus Robotics represents the autonomous mobile robot fleet orchestration segment. Intuitive Surgical anchors the medical-device-to-service-contract transition model, leveraging surgical system installed bases for high-margin recurring revenue structures.
| Leading Market Players |
|---|
| Intuitive Surgical |
| iRobot Corporation |
| Berkshire Grey |
| Aethon |
| KUKA AG |
| Daifuku Co., Ltd. |
| inVia Robotics |
| Locus Robotics |
| Exotec |
| Others |
Value Network & Pricing Analysis
Mid-market manufacturers in Germany and Japan anchor Robot As a Service pricing power through their preference for operational expenditure treatment and seasonal scaling flexibility. This buyer concentration reinforces subscription-based contracts with embedded maintenance guarantees over transactional hardware sales.
Pricing Analysis
Uptime-based pricing anchors premium Robot As a Service tiers, with vendors charging against guaranteed availability percentages rather than raw machine-hour rates. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance bundles from bare-metal rentals. Cost compression in commodity tiers intensifies as Asian component suppliers expand LiDAR and vision module production. Industrial end users show lowest price sensitivity due to downtime cost exposure, while commercial buyers in hospitality and retail segments drive hardest per-hour rate negotiations.
Supply Chain Analysis
Reverse-logistics networks for refurbished industrial arms and remanufactured autonomous mobile robots concentrate in Germany, Japan, and the United States where vendor-managed servicing infrastructure is mature. Precision sensor arrays draw from South Korean and Taiwanese semiconductor fabrication, while steel actuators and aluminum chassis feed from Chinese and Mexican metalworking centers. Single-source vulnerability in LiDAR component supply exposes service providers to input price volatility. Distribution runs through direct vendor-customer contracts with embedded field engineering, bypassing traditional industrial equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robot As a Service capacity expansion lags demand acceleration, with mechatronics talent scarcity propping premium-tier pricing and extending contract backlogs for manufacturing applications.
For Market Incumbents: Acquire specialized field engineering capabilities in Stuttgart and Nagoya industrial corridors to tighten predictive maintenance response times. Lock in multi-year LiDAR supply agreements with South Korean component vendors before capacity constraints harden. API-first orchestration layers represent the priority defensive investment against warehouse-native automation specialists eroding manufacturing incumbents' installed base leverage. For New Entrants and Emerging Players: The mid-market logistics gap between premium vision-guided systems and economy rental tiers offers white-space entry for hybrid fleet orchestration platforms. Target third-party fulfillment providers in Dallas-Fort Worth and Memphis distribution clusters where labor shortages intensify fastest. Lead with usage-based billing models that displace capital expenditure treatment without requiring full managed services overhead. For Investors and Strategic Acquirers: The window for entry favors surgical system incumbents transitioning to service-contract anchoring and warehouse-native AI automation specialists with proven vision-pick capabilities. Long-term viability hinges on software overlay depth rather than hardware manufacturing scale. Watch for OSHA collaborative robot certification backlogs as inflection signal—extended validation cycles that delay service launches concentrate pricing power among pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Fleet Orchestration Platform | Enables multi-vendor robot mixing within single warehouse footprints without proprietary lock-in. |
| Backward Integration into Precision Sensor Supply | Reduces LiDAR cost volatility exposure from concentrated Asian component suppliers. |
| CE-Marked AI Governance Module Development | Addresses EU AI Act documentation requirements for autonomous systems in public-facing deployments. |
| 5G Private Network Infrastructure Partnership | Supports edge-to-cloud orchestration for real-time fleet optimization across distributed German facilities. |
| Predictive Maintenance Talent Acquisition | Tightens emergency repair response times for industrial customers demanding 99.5% uptime SLAs. |
Research Methodology
Document review covered SEC 10-K filings, EU Machinery Directive guidance documents, and FDA premarket clearance databases, complemented by interviews with fleet operations directors at third-party logistics providers, predictive maintenance engineers at industrial automation vendors, and procurement managers at German automotive suppliers. Customs trade data, OSHA workplace safety incident reports, and METI industrial policy briefings provided secondary validation. Bottom-up deployment volume estimates triangulated against top-down subscription revenue projections.
Segmentation outputs across service type, application, end user, and deployment model dimensions were generated through the projection horizon. CAGRs were derived from fitted growth curves incorporating labor shortage intensity indices and cloud robotics adoption rates. Forecast inputs included seasonal order fluctuation patterns at Japanese electronics contract manufacturers and 5G private network rollout timelines in Baden-Württemberg industrial corridors.
Inputs from fleet operations directors and predictive maintenance engineers were available through the study window; gaps in real-time pricing data from private RaaS contracts introduce uncertainty bands around tiered subscription estimates. Forecasts reflect assumptions regarding CE marking harmonization progress and OSHA collaborative robot certification velocity. Material deviation in LiDAR component supply concentration or mechatronics training pipeline expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Medical Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Pipetting Robots Market