
 Recombined Milk Market | 2026-2036
Recombined Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Recombined Milk Market Analytics
ISO 22000 certification is bifurcating the recombined milk supplier base into qualified exporters and regional processors locked out of premium channels. Fonterra leverages its integrated ingredient supply chain to dominate bulk skim milk powder sourcing for recombination plants across Southeast Asia. Lactalis sustains European market access through dedicated recombined cream and butter oil facilities calibrated to Codex fat standard thresholds. Yili Group anchors its recombined output to domestic powder reserves, competing on cost against imported recombined liquid brands in China's lower-tier cities.
Recombined milk denotes a product manufactured by reconstituting milk powders—typically skim milk powder and anhydrous milk fat or butter oil—with water to approximate the composition of fresh whole milk, generally targeting standardized fat levels between 3.0% and 3.5% and protein minimums of 2.9% for fluid applications. Its primary commercial purpose is to deliver consistent, shelf-stable dairy supply in regions where local raw milk collection remains seasonal, fragmented, or insufficient for industrial dairy processor demand. Powdered milk and liquid milk represent the dominant product categories, with liquid recombined formats capturing volume leadership in tropical markets where cold chain limitations favor ambient distribution, while condensed milk and evaporated milk retain concentrated margin pools in food manufacturing and bakery segments requiring extended shelf life without refrigeration. Tetra Packs and plastic bottles command packaging type preference, reflecting divergent channel strategies: aseptic cartons for supermarket and wholesaler bulk distribution, blow-molded bottles for convenience store single-serve placement.
FDA standards for dairy identity and labeling, Codex Alimentarius commodity standards for milk fat and protein content, and national food safety regulators in key import markets collectively shape recombined milk formulation, export eligibility, and consumer disclosure requirements. These frameworks compel manufacturers to maintain dual-specification production lines—one calibrated to stricter destination-market standards, another optimized for domestic regulatory tolerance—adding fixed cost complexity that favors scaled operators. Stakeholders must monitor evolving dairy tariff schedules and powder-to-fluid price spreads, as these determine whether recombination economics remain viable against direct fresh milk imports or regional sourcing alternatives.
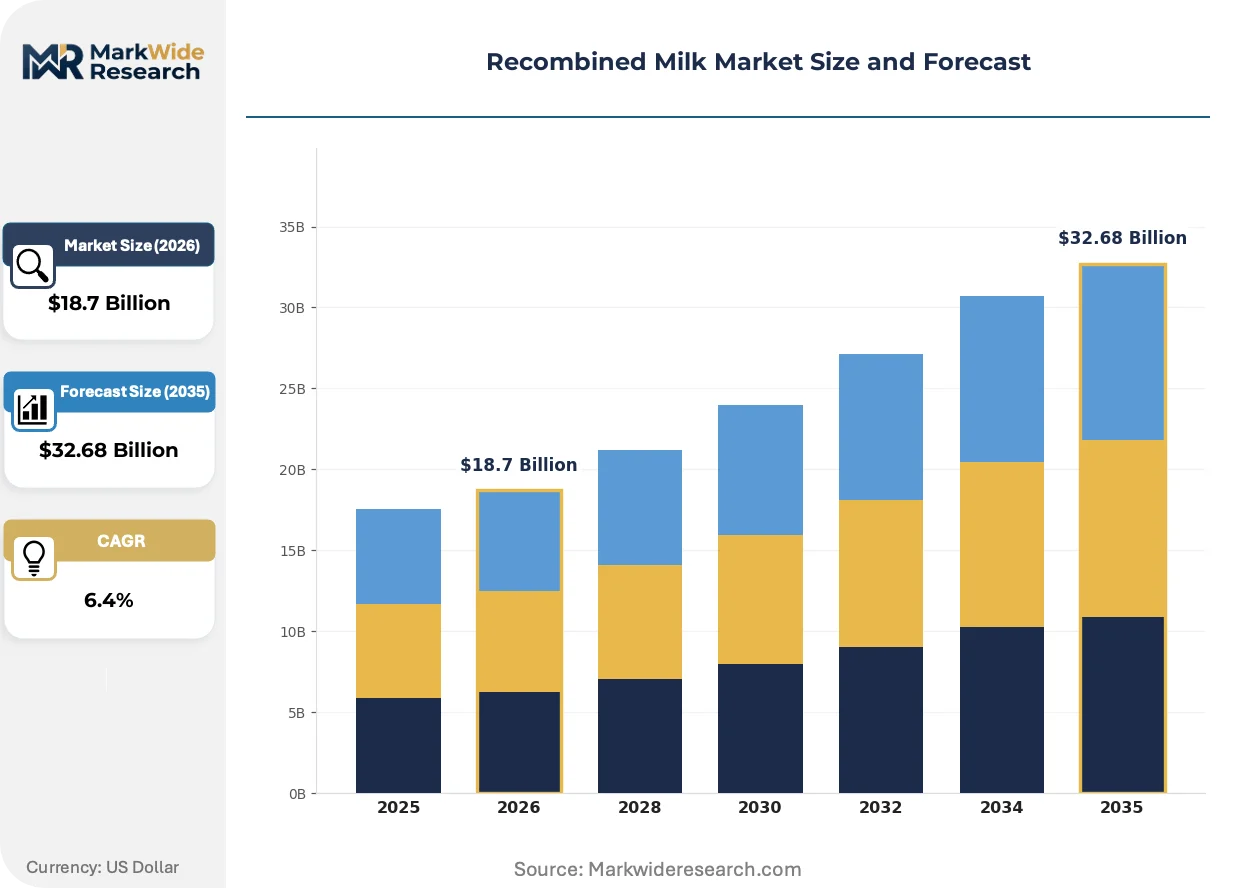
Market Dynamics
Powder-to-fluid price spreads and Codex fat standard tightening are compressing recombination economics, forcing processors to choose between dual-specification production lines or single-market focus.
Growth Catalysts
- Fluid milk deficits in Southeast Asia:Indonesia and Vietnam face structural raw milk shortfalls, pushing dairy processors toward recombined liquid formats to meet ambient distribution demand without cold chain dependency.
- ISO 22000 certification diffusion:Food safety frameworks are creating qualified supplier tiers, enabling certified exporters to capture premium channel access in import-dependent markets.
- Anhydrous milk fat standardization:Butter oil recombination technology allows precise fat content calibration, satisfying bakery and confectionery manufacturers requiring consistent functional dairy ingredients.
Market Restraints
- Skim milk powder price volatility:Global dairy commodity swings directly transmit to recombined milk production costs, eroding margin predictability for regional processors without captive powder reserves.
- Fresh milk import competition:Direct fluid dairy shipments from Australia and New Zealand undercut recombination economics when ocean freight rates compress and seasonal production peaks coincide.
- Dual-line fixed cost burden:Codex-compliant export specifications and domestic regulatory tolerance thresholds force parallel production infrastructure, disadvantaging sub-scale operators.
Strategic Opportunities
- Lower-tier Chinese city penetration:Cost-competitive recombined liquid brands can displace premium imported fresh milk in price-sensitive inland markets where cold chain infrastructure remains underdeveloped.
- Food manufacturing ingredient pivot:Condensed and evaporated recombined formats target bakery and processed food segments seeking extended shelf life without refrigeration dependency.
- Aseptic carton channel expansion:Tetra Pak-compatible packaging formats unlock supermarket and wholesaler bulk distribution in tropical markets where ambient logistics dominate.
Industry Challenges
- Dual-specification technician scarcity:Plants require operators capable of switching between Codex-calibrated export lines and domestic-tolerance systems without cross-contamination or specification drift.
- ISO 22000 audit timeline compression:Certification backlog at accredited bodies delays market entry for regional processors attempting to qualify for premium export channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombined Milk Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Milk, Liquid Milk, Condensed Milk, Evaporated Milk End User: Food Manufacturers, Bakeries, Cafés, Dairy Processors Packaging Type: Tetra Packs, Plastic Bottles, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Nestle S.A., Fonterra, Lactalis, Arla Foods, Dairy Farmers of America, Saputo, FrieslandCampina, Yili Group, Mengniu Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombined Milk Market Evolving Landscape
Recombined milk processing is experiencing technology-driven efficiency gains alongside regulatory calibration pressures and distribution channel fragmentation that favors ambient-stable formats.
High-shear powder reconstitution systems with inline fat homogenization are supplanting traditional batch-tank recombination in Southeast Asian plants. Large-scale dairy processors in Indonesia and Vietnam are adopting continuous-flow technology to reduce hydration time and improve protein solubility. This equipment transition is compressing capital recovery timelines while enabling real-time fat standardization that satisfies Codex thresholds without secondary adjustment.
EU F-Gas Regulation phase-down mandates are accelerating cold chain infrastructure cost inflation across dairy-importing markets. Refrigeration-dependent fresh milk distribution faces escalating compliance expenses, widening the total-cost gap against ambient-stable recombined alternatives. Tropical markets with limited refrigerated logistics capacity are responding by prioritizing aseptic carton formats that bypass mechanical cooling requirements entirely.
Buyer consolidation among Southeast Asian supermarket chains is compressing supplier negotiation cycles and demanding extended payment terms from recombined milk processors. Regional wholesalers that once aggregated fragmented retail demand are losing volume share to direct manufacturer-retailer agreements. This channel restructuring is most visible in Vietnam, where convenience store chains now specify blow-molded single-serve bottles over bulk Tetra Pak configurations for front-of-store placement.
Recombined Milk Market Segmentation
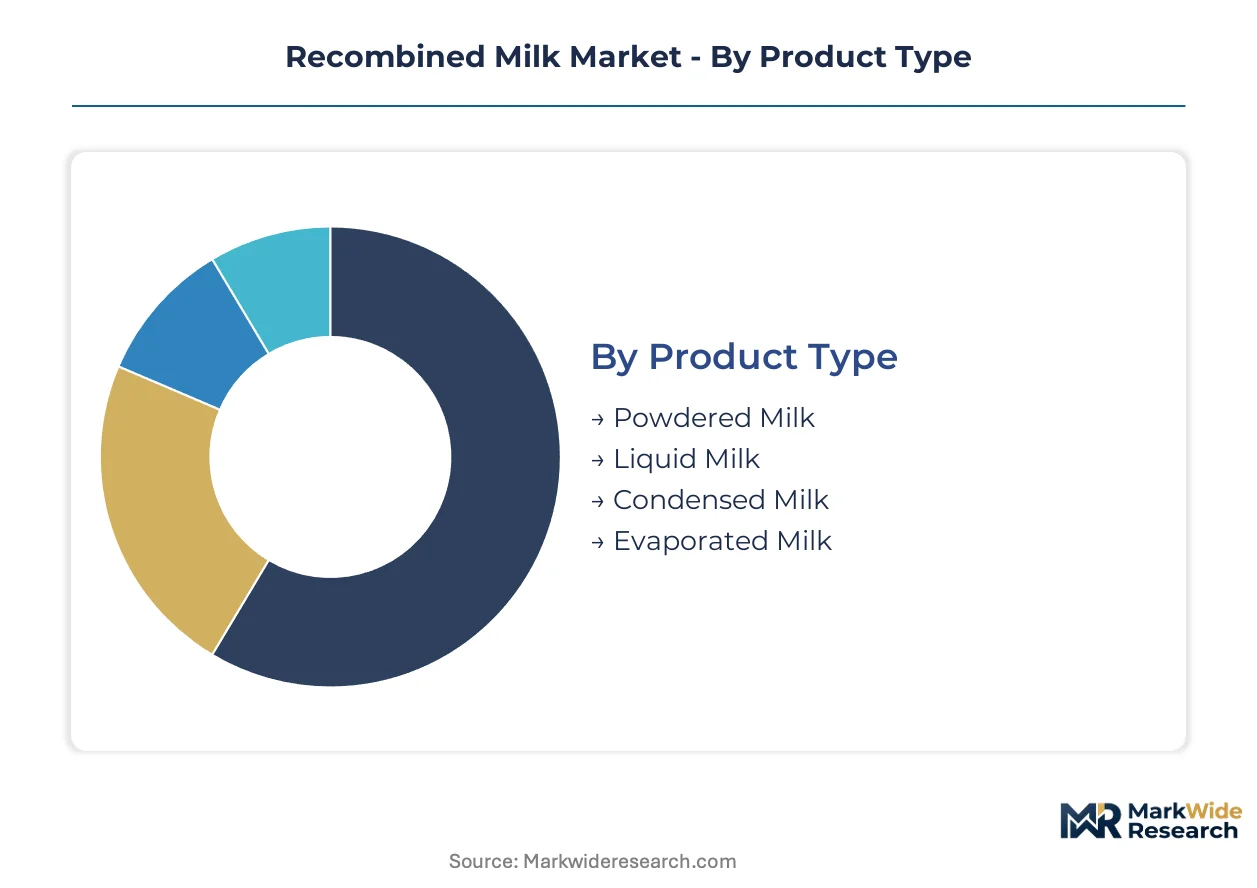
Recombined milk segmentation reflects divergent supply chain economics across tropical and temperate markets. Powder-to-fluid conversion ratios and Codex fat calibration requirements create distinct margin profiles by product format and end-use application.
Product Type:
Liquid recombined formats face the most acute substitution pressure from direct fresh milk imports when ocean freight rates compress and Australian seasonal peaks align.
- Liquid Milk:Reconstituted from skim milk powder and anhydrous milk fat to target 3.0-3.5% fat content, this format dominates ambient distribution in Indonesia and Vietnam where cold chain gaps persist. Convenience store chains in Ho Chi Minh City now specify single-serve bottles for front-of-store placement.
- Powdered Milk:Dry recombined base requiring end-user hydration, this segment anchors industrial dairy processor procurement across Southeast Asia. Dairy processors without captive powder reserves face margin erosion when global commodity swings transmit directly to input costs.
- Condensed Milk:High-solids recombined format targeting bakery and confectionery manufacturers seeking extended shelf stability.
- Evaporated Milk:Concentrated recombined product serving processed food segments requiring consistent functional dairy ingredients without refrigeration dependency.
Liquid milk anchors the volume base while evaporated milk gains share at the steepest rate among food manufacturing ingredient pivots.
End User:
Cost tier stratification separates price-sensitive volume buyers from specification-driven premium accounts.
- Food Manufacturers:Industrial-scale buyers of condensed and evaporated recombined formats for processed food production. These accounts prioritize batch-to-batch consistency and extended shelf life over fresh milk flavor profiles.
- Dairy Processors:Intermediate users recomposing powder into downstream dairy products. Southeast Asian processors expanding procurement to manage volatile fresh milk supply face dual-specification production line investments.
- Bakeries:Mid-tier consumers of recombined cream and butter oil for functional baking applications.
- Cafés:Small-format buyers with limited cold chain capacity favoring ambient-stable liquid recombined for beverage preparation.
Food manufacturers anchor the volume base while dairy processors gain share at the steepest rate through backward integration into powder reserves.
Packaging Type:
Channel fragmentation between supermarket bulk and convenience single-serve drives divergent material specifications.
- Tetra Packs:Aseptic carton formats compatible with ambient logistics dominate supermarket and wholesaler bulk distribution across tropical markets. EU F-Gas Regulation phase-down mandates widen the total-cost gap against refrigeration-dependent alternatives.
- Plastic Bottles:Blow-molded configurations serve convenience store single-serve placement where front-of-store visibility commands premium positioning.
- Cans:Metal packaging for extended-shelf-life condensed and evaporated formats in food manufacturing supply chains.
- Pouches:Flexible film formats for economy-tier powdered milk in price-sensitive emerging markets.
Tetra Packs anchor the volume base while plastic bottles gain share at the steepest rate through convenience store channel consolidation.
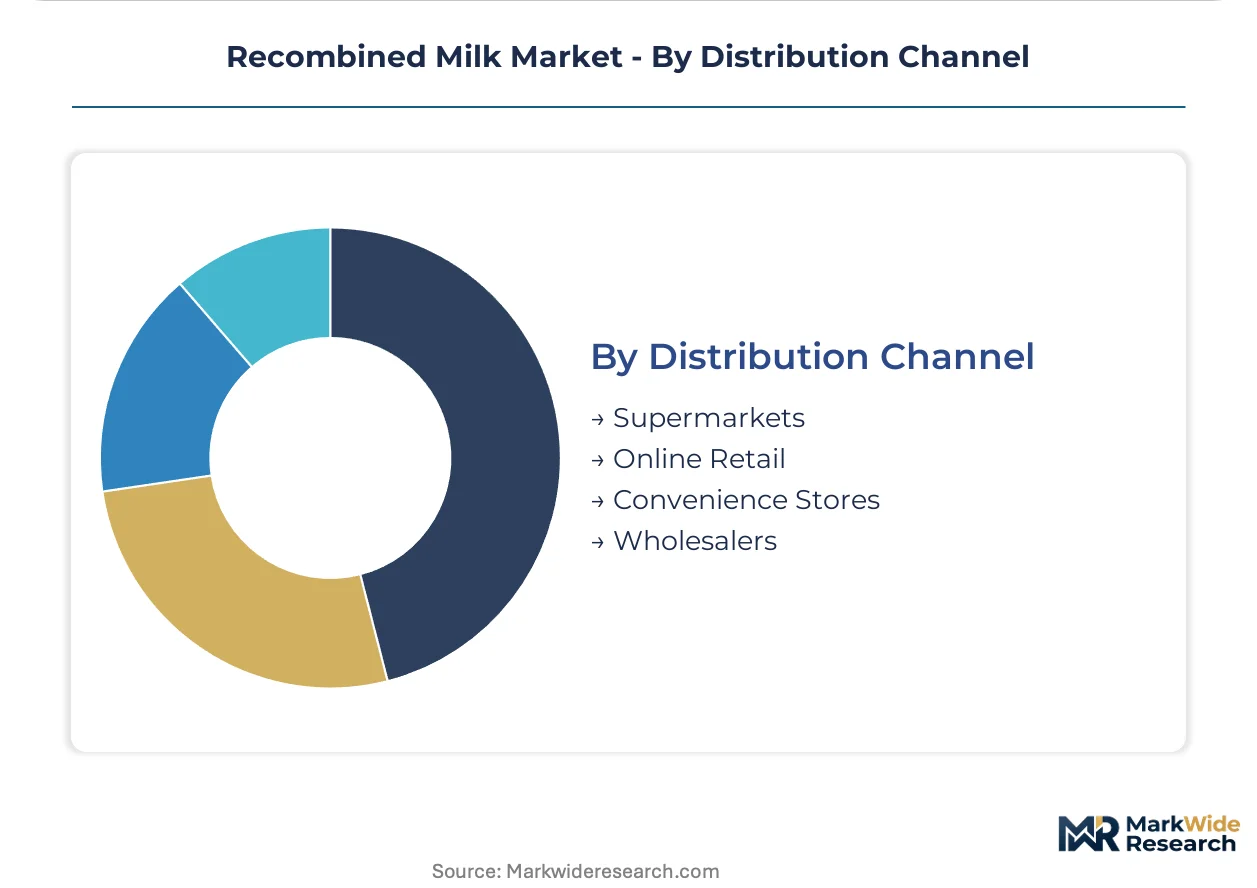
Distribution Channel:
Buyer consolidation is compressing supplier negotiation cycles and demanding extended payment terms across all formats.
- Supermarkets:Direct manufacturer-retailer agreements are displacing regional wholesalers in Vietnam and Indonesia. These accounts specify aseptic carton bulk configurations for ambient distribution efficiency.
- Convenience Stores:Chains now dominate front-of-store placement decisions, driving specification shifts toward single-serve plastic bottles over bulk formats.
- Wholesalers:Traditional aggregators losing volume share to direct distribution, retaining relevance only in fragmented rural catchments.
- Online Retail:Emerging channel for powdered milk subscription and bulk replenishment in urban centers with developed logistics infrastructure.
Supermarkets anchor the volume base while convenience stores gain share at the steepest rate through format specification power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down mandates are accelerating cold chain infrastructure cost inflation across dairy-importing markets, widening the total-cost gap against ambient-stable recombined alternatives. Tropical markets with limited refrigerated logistics capacity are responding by prioritizing aseptic carton formats that bypass mechanical cooling requirements entirely.
Indonesia
Fluid milk deficits in Java and Sumatra push dairy processors toward recombined liquid formats to meet ambient distribution demand without cold chain dependency. The national food safety regulator enforces tightening formulation requirements that compel manufacturers to maintain dual-specification production lines. Dairy processing clusters in West Java province are expanding recombined milk procurement to manage volatile fresh milk supply from fragmented local collection networks.
Vietnam
Convenience store chains in Ho Chi Minh City now specify single-serve plastic bottles for front-of-store placement, displacing bulk Tetra Pak configurations. ISO 22000 certification diffusion creates qualified supplier tiers, enabling certified exporters to capture premium channel access in this import-dependent market. Recombination plants in the Mekong Delta region are adopting high-shear powder reconstitution systems with inline fat homogenization to reduce hydration time.
China
Yili Group anchors its recombined output to domestic powder reserves, competing on cost against imported recombined liquid brands in lower-tier inland cities where cold chain infrastructure remains underdeveloped. SAMR calibration requirements for dairy fat content tighten formulation standards across export-oriented plants. Dairy processing hubs in Heilongjiang province leverage captive skim milk powder reserves to insulate margin predictability against global commodity swings.
Philippines
Condensed and evaporated recombined formats target bakery and processed food segments seeking extended shelf life without refrigeration dependency. The national food safety framework mandates disclosure requirements that shape consumer perception of reconstituted versus fresh milk. Recombination facilities in Metro Manila are pivoting toward food manufacturing ingredient supply as supermarket buyer consolidation compresses supplier negotiation cycles.
Thailand
Anhydrous milk fat standardization technology allows precise fat content calibration, satisfying bakery and confectionery manufacturers requiring consistent functional dairy ingredients. The national regulator aligns dairy commodity standards with Codex thresholds, compelling parallel production infrastructure investments. Processing clusters in the Central Plains region are expanding aseptic carton channel expansion to unlock supermarket and wholesaler bulk distribution.
Recombined Milk Market Competitive Landscape
Listed leaders compete with private specialists across powder reserve access and cold chain bypass capabilities. The supplier base bifurcates between scaled operators with captive ingredient supply chains and regional processors locked out of premium channels by certification barriers. Three archetypes dominate: integrated dairy cooperatives with backward powder control, multinational processors with Codex-calibrated export lines, and domestic cost competitors serving price-sensitive inland markets. Competitive moves center on backward integration into skim milk powder reserves and dual-specification production line investments.
Within the integrated cooperative tier, Fonterra and FrieslandCampina exemplify players leveraging captive ingredient supply chains to dominate bulk skim milk powder sourcing for recombination plants across Southeast Asia. Among Asia-Pacific-based cost competitors, Yili Group and Mengniu Dairy occupy positions anchored to domestic powder reserves, competing on price against imported recombined liquid brands. Nestle S.A. sits within the multinational processor archetype, maintaining production infrastructure calibrated to stricter destination-market standards alongside domestic-tolerance systems.
| Leading Market Players |
|---|
| Nestle S.A. |
| Fonterra |
| Lactalis |
| Arla Foods |
| Dairy Farmers of America |
| Saputo |
| FrieslandCampina |
| Yili Group |
| Mengniu Dairy |
| Others |
Value Network & Pricing Analysis
Ninety-day powder inventory cycles at Southeast Asian recombination plants concentrate pricing power among processors with captive skim milk powder reserves, while spot-market buyers absorb margin volatility from global dairy commodity swings. This inventory asymmetry feeds directly into contract-versus-spot pricing spreads that separate integrated operators from regional processors locked out of premium export channels.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-qualified exporters and domestic-tolerance suppliers, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on Codex fat standard compliance and volume scale, with food manufacturers commanding lowest unit costs through long-term offtake agreements. Pricing pressure stems from fresh milk import competition when Australian seasonal peaks align with compressed ocean freight rates. Dairy processors without backward integration into powder reserves exhibit highest price sensitivity, while integrated cooperatives leverage captive supply to defend margin position.
Supply Chain Analysis
Strategic stockpiling of anhydrous milk fat and skim milk powder dominates over just-in-time approaches, reflecting input price volatility and seasonal production gaps. Supply concentrates in New Zealand, Australia, and the European Union for dairy commodity inputs, with Southeast Asian recombination plants drawing from these origins. Raw material dependencies center on skim milk powder, anhydrous milk fat, and butter oil specifications. Single-source vulnerability from Fonterra's grip on bulk powder sourcing in Oceania creates concentration risk. Distribution runs through ambient logistics networks favoring Tetra Pak-compatible aseptic formats over cold chain-dependent fresh milk alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down mandates are accelerating cold chain infrastructure cost inflation, creating structural advantage for ambient-stable recombined formats against refrigeration-dependent fresh milk alternatives.
For Market Incumbents: Secure captive skim milk powder reserves through backward integration or long-term supply agreements to insulate margin predictability against global commodity volatility. Invest in dual-specification production lines calibrated to both Codex export thresholds and domestic regulatory tolerance, as ISO 22000 certification diffusion threatens to lock sub-scale competitors out of premium channels. For New Entrants and Emerging Players: ISO 22000 fast-track certification programs unlock immediate access to supermarket and wholesaler bulk distribution in Vietnam and Indonesia, the most penetrable geographies given fluid milk deficits and import dependency. Target food manufacturing ingredient supply for condensed and evaporated formats, where bakery and confectionery manufacturers prioritize batch consistency over fresh milk provenance. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational dairy processors seeking to divest non-core recombination assets in Southeast Asia amid portfolio rationalization. Long-term viability favors operators with integrated ingredient supply chains and Codex-calibrated export infrastructure. Watch powder-to-fluid price spreads as the critical inflection signal—when spreads compress below recombination economics thresholds, acquisition premiums for captive powder reserves escalate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Reserves | Captive skim milk powder supply insulates margin predictability against global dairy commodity swings at Indonesian and Vietnamese plants. |
| Dual-Specification Production Line Investment | Parallel Codex-calibrated and domestic-tolerance systems enable simultaneous export and local market access without cross-contamination risk. |
| ISO 22000 Certification Fast-Track | Accelerated audit timelines unlock premium supermarket and wholesaler channels in import-dependent Southeast Asian markets. |
| Aseptic Carton Channel Expansion | Tetra Pak-compatible formats bypass EU F-Gas Regulation compliance costs for refrigerated distribution in tropical ambient logistics networks. |
| Food Manufacturing Ingredient Pivot | Condensed and evaporated recombined formats capture bakery and confectionery demand for extended shelf-life functional dairy ingredients. |
Research Methodology
Cross-validation between primary interviews with dairy processing executives, plant operations managers, and food manufacturing procurement leads and secondary sources including Codex Alimentarius standards, national food safety regulatory filings, and dairy commodity trade data anchors the qualitative findings. Bottom-up volume modeling from recombination plant capacities and powder import flows triangulates against top-down market sizing from dairy processor revenue disclosures and channel distribution audits.
Sensitivity analysis across powder-to-fluid price spread scenarios, freight rate volatility bands, and certification adoption curves tests forecast robustness over the projection horizon. Segmentation dimensions span product format, end-user application, packaging type, and distribution channel, with regional regulatory cluster variations modeled separately. CAGRs derive from compounded annual growth trajectories fitted to historical powder reserve accumulation patterns and ambient distribution infrastructure expansion rates.
Decision-makers should treat outputs as directional under assumptions of continued Codex fat standard tightening and sustained EU F-Gas Regulation phase-down timelines; material deviation would warrant model refresh. Specific risk factors include abrupt skim milk powder price spikes, fresh milk import tariff reductions, and ISO 22000 certification backlog resolution at accredited bodies. Revision becomes warranted when powder-to-fluid price spreads compress below recombination breakeven thresholds for sustained periods.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Dairy Carton Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Low Fat Cheese Market
Dairy Products
United States Casein Market
Dairy Products
Emmental Cheese Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Skimmed Milk Market
Dairy Products
Organic Dairy Products Market