
 Low Fat Cheese Market | 2026-2036
Low Fat Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Cheese Market Intelligence
Portion-controlled slice and shred formats is hardening as the dominant configuration pattern, replacing bulk block purchasing in both retail and food service channels. Kraft Heinz Company leverages its retail shelf-space dominance to anchor multi-format low-fat cheese portfolios across North American supermarkets. Arla Foods specializes in clean-label reduced-fat variants that compete on Nordic dairy heritage credentials. Saputo Inc. extends its private-label manufacturing scale to control cost positioning in shredded and sliced segments.
Low fat cheese denotes dairy products with reduced butterfat content, typically manufactured through skim milk processing, fat-mimetic protein restructuring, or enzymatic modification to achieve 20–50% less fat than standard equivalents while preserving meltability and texture. The primary commercial purpose centers on enabling food manufacturers and food service operators to deliver calorie-reduced menu items and packaged goods without sacrificing functional performance in baking or melting applications. Cheddar and mozzarella command the largest volume positions due to their ubiquity in prepared foods and pizza manufacturing, though cream cheese is registering the fastest growth trajectory as bagel chains and dessert processors reformulate spreads. Shredded packaging dominates institutional procurement because of labor-cost savings in commercial kitchens, while block formats retain margin concentration among artisanal and specialty retail channels.
The USDA maintains grade standards and compositional thresholds that govern fat-content labeling claims across American dairy products, directly influencing permissible "low fat" and "reduced fat" designations. The EU Green Deal and EFSA nutrient profiling criteria are tightening permissible health claims and reformulation targets for reduced-fat dairy sold in European markets. Stakeholders must monitor evolving front-of-pack labeling mandates and protein-standard adjustments that will determine which formulations qualify for premium positioning versus commodity classification.
Market Dynamics
The EU's F-Gas Regulation is forcing dairy processors to overhaul refrigeration-dependent production lines while simultaneously complying with EFSA nutrient profiling criteria that restrict permissible health claims on reduced-fat labels.
Growth Catalysts
- Clean-label protein restructuring:Enzymatic fat-mimetic technologies enable texture parity in reduced-fat cheddar without artificial stabilizers, unlocking premium positioning in German retail chains.
- Institutional menu mandates:US school nutrition standards and healthcare facility procurement guidelines now specify reduced-fat dairy minimums, pulling volume through Sodexo and Compass Group contracts.
- Pizza manufacturing automation:Shredded low-fat mozzarella integrates directly into automated topping lines, cutting labor costs for frozen pizza producers in Italy and the United States.
Market Restraints
- Skim milk powder price volatility:New Zealand and EU dairy auction fluctuations transmit directly to low-fat cheese input costs, compressing processor margins during supply shocks.
- Functional performance ceiling:Fat reduction beyond 50% degrades melt stretch and mouthfeel, limiting reformulation depth for pizza and sauce applications.
- F-Gas compliance capital burden:Retrofitting aging dairy plants with low-GWP refrigeration systems requires 7-figure investments that smaller cooperatives cannot absorb.
Strategic Opportunities
- Plant-forward hybrid formats:Blending dairy protein with oat or almond bases creates reduced-fat spreads that bypass EFSA's strict dairy-only nutrient profiling thresholds.
- Direct-to-foodservice platforms:Specialized distributors like Sysco and US Foods are building private-label low-fat cheese portals that bypass traditional retail slotting fees.
- Precision fermentation derivatives:Casein proteins from microbial fermentation enable fat-free cheese structures with authentic dairy functionality, opening kosher and lactose-free adjacencies.
Industry Challenges
- Refrigeration technician scarcity:F-Gas certified service personnel shortages in France and Germany delay plant upgrades and trigger regulatory non-compliance risks.
- Dual certification complexity:Simultaneous USDA grade standards and EU Protected Designation of Origin requirements for exported parmesan variants extend approval timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Cheese Market |
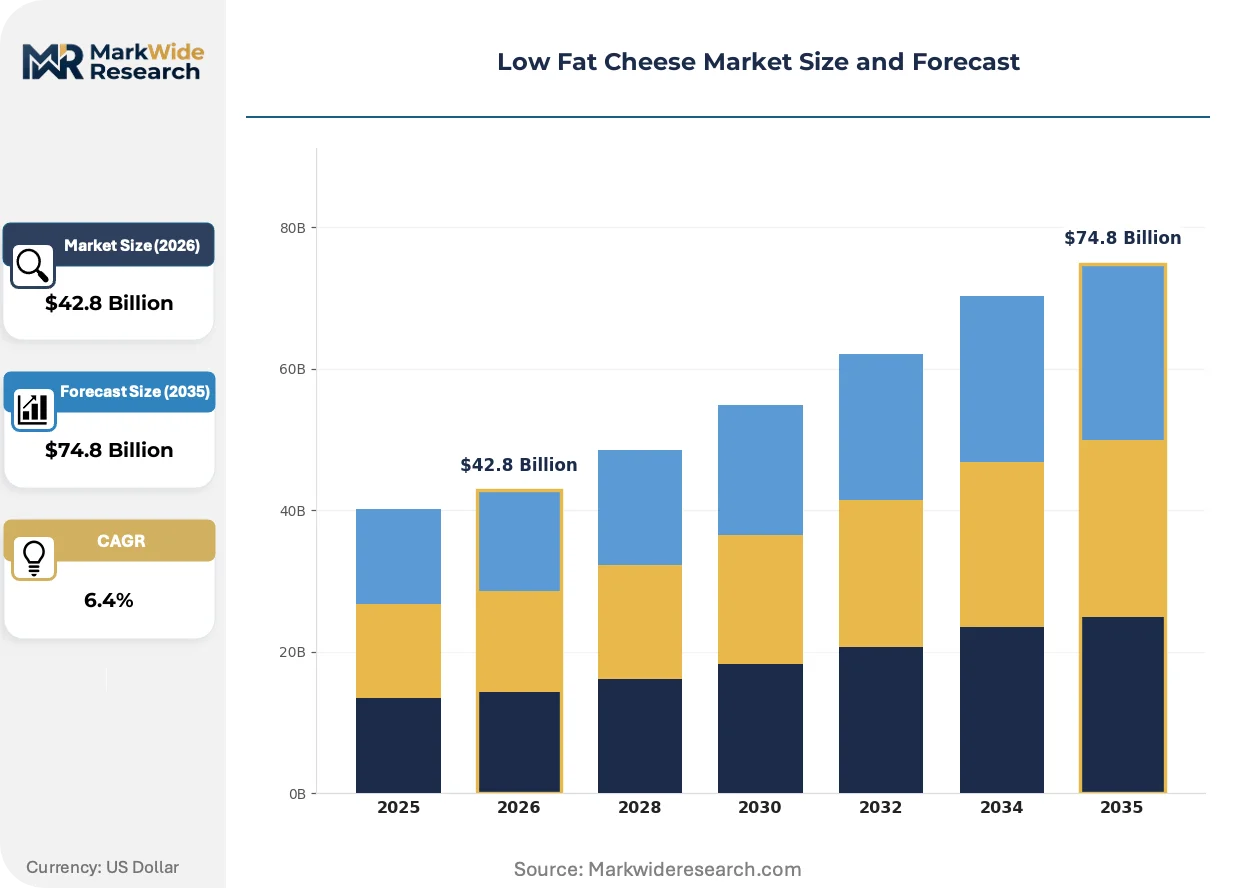
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Cream Cheese, Ricotta End User: Households, Food Service Providers, Manufacturers, Retailers Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Blocks, Slices, Shredded, Spreadable |
| Companies Covered | Sargento Foods Inc., Bel Group, Kraft Heinz Company, Nestlé S.A., Dairy Farmers of America, Arla Foods, Saputo Inc., Danone S.A., Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Cheese Market Strategic Shifts & Innovations
Active culture engineering and membrane filtration advances are collapsing the texture gap between reduced-fat and full-fat cheese, while regulatory tightening on environmental claims reshapes how processors communicate nutritional benefits.
Microfiltration and ultrafiltration concentration is rewriting the economics of skim milk solids recovery. Arla Foods and Saputo are deploying ceramic membrane systems that recover 15% more protein per liter of skim milk than traditional evaporation. This protein yield advantage is rewriting cost structures for shredded mozzarella producers competing on institutional contracts.
The EU Green Deal's Farm to Fork strategy tightens methane reporting obligations for dairy cooperatives supplying reduced-fat cheese into German and French retail. Processors must now document enteric fermentation emissions across their milk supply bases to retain shelf placement. Danish and Dutch producers are responding fastest, integrating carbon accounting into procurement contracts with farmer suppliers.
Bagel chains and quick-service dessert operators are consolidating cheese suppliers around single-source reduced-fat cream cheese providers capable of custom viscosity specifications. Einstein Bros. and Bruegger's have shifted from multi-vendor purchasing to sole-source agreements with processors offering formulation flexibility. This consolidation is most visible in the US Northeast corridor, where regional dairies are acquiring smaller spread manufacturers to secure these anchored contracts.
Low Fat Cheese Market Segmentation
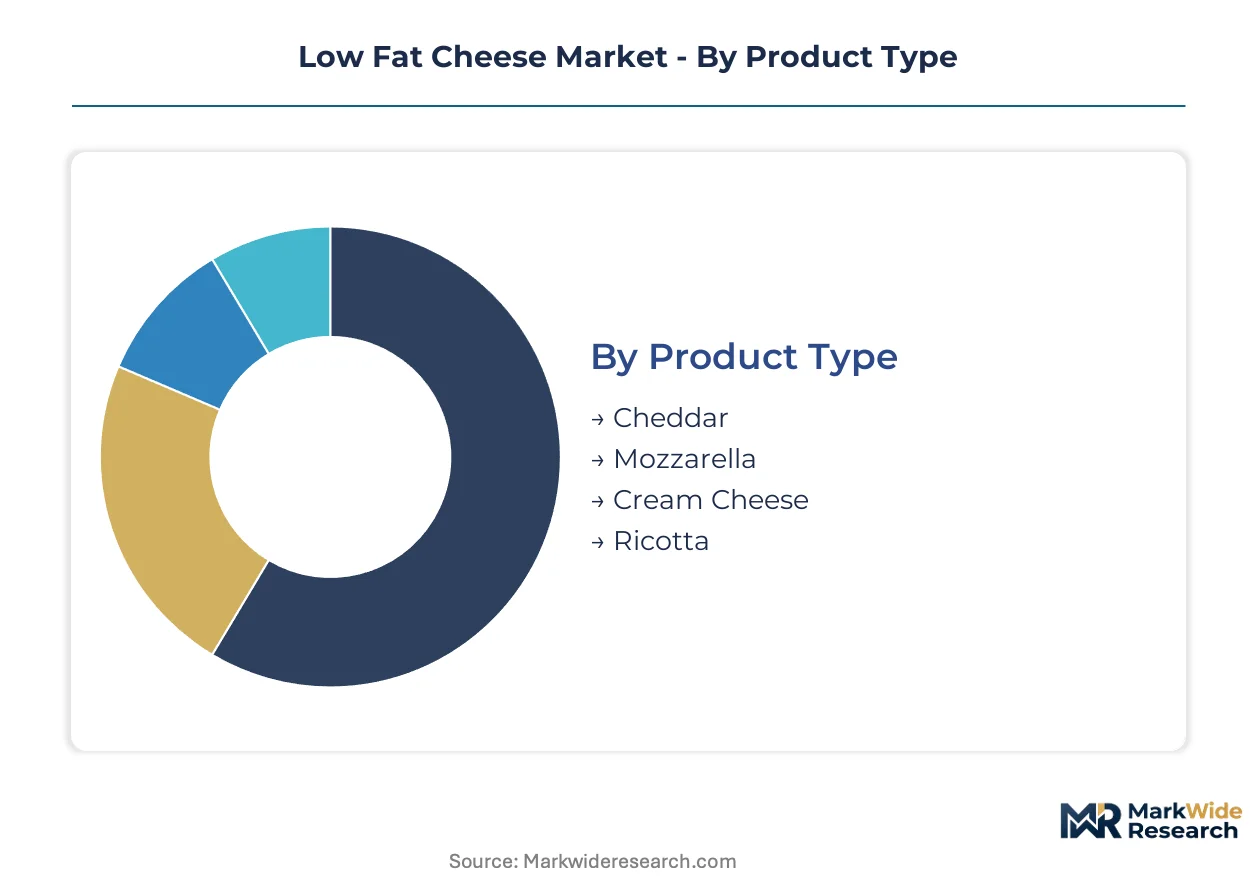
Low-fat cheese processors must align production configurations with divergent buyer priorities across channels. Households demand sensory parity in reduced-fat formats while food service operators prioritize labor efficiency and portion control.
Product Type:
Buyers differentiate primarily by functional application requirements—melt performance for pizza manufacturing versus spreadability for breakfast service.
- Cheddar:Manufactured through skim milk processing with protein restructuring to preserve meltability in reduced-fat formulations. Demand concentrates in frozen prepared meals and institutional food service across the United States, where USDA school nutrition standards mandate reduced-fat dairy minimums.
- Mozzarella:Engineered via enzymatic modification to maintain stretch characteristics at 20-30% fat reduction. Italian frozen pizza producers and US quick-service chains drive procurement, with automated topping lines favoring pre-shredded formats that integrate directly into manufacturing equipment.
- Cream Cheese:Bagel chains and dessert processors in the US Northeast corridor consolidate around sole-source suppliers offering custom viscosity specifications for reduced-fat spreads.
- Ricotta:Niche positioning in health-conscious retail segments and specialty Italian food manufacturing, with limited penetration in mainstream food service channels.
Volume sits with mozzarella; growth tilts toward cream cheese.
End User:
Procurement scale and specification control separate institutional buyers from fragmented household purchasing.
- Food Service Providers:Sodexo and Compass Group contracts specify reduced-fat dairy minimums under US school nutrition and healthcare facility guidelines, pulling high-volume throughput with strict consistency requirements.
- Manufacturers:Frozen pizza and prepared meal producers demand shredded formats compatible with automated production lines, with reformulation depth constrained by fat-reduction ceilings affecting melt performance.
- Households:German retail chains prioritize clean-label reduced-fat cheddar and mozzarella variants, with EFSA nutrient profiling criteria restricting permissible health claims on packaging.
- Retailers:Private-label development focuses on portion-controlled slice and shred formats that replace bulk block purchasing across North American supermarket channels.
Scale concentrates with food service providers; specification complexity climbs fastest among manufacturers.
Distribution Channel:
Cost-to-serve economics and buyer relationship intensity determine channel viability for different product formats.
- Supermarkets:Kraft Heinz leverages shelf-space dominance to anchor multi-format low-fat cheese portfolios, with slotting fee structures favoring established processors over emerging competitors.
- Direct Sales:Sysco and US Foods build private-label portals that bypass traditional retail fees, connecting processors directly to institutional buyers with volume commitments.
- Specialty Stores:Artisanal and clean-label reduced-fat variants from Arla Foods compete on Nordic dairy heritage credentials in premium urban markets.
- Online:Emerging channel for subscription-based specialty cheese delivery, with limited penetration in mainstream low-fat categories due to cold-chain cost structures.
Revenue concentrates in supermarkets; margin expansion tilts toward direct sales.
Packaging Type:
Labor economics and usage occasion specificity drive format selection across buyer segments.
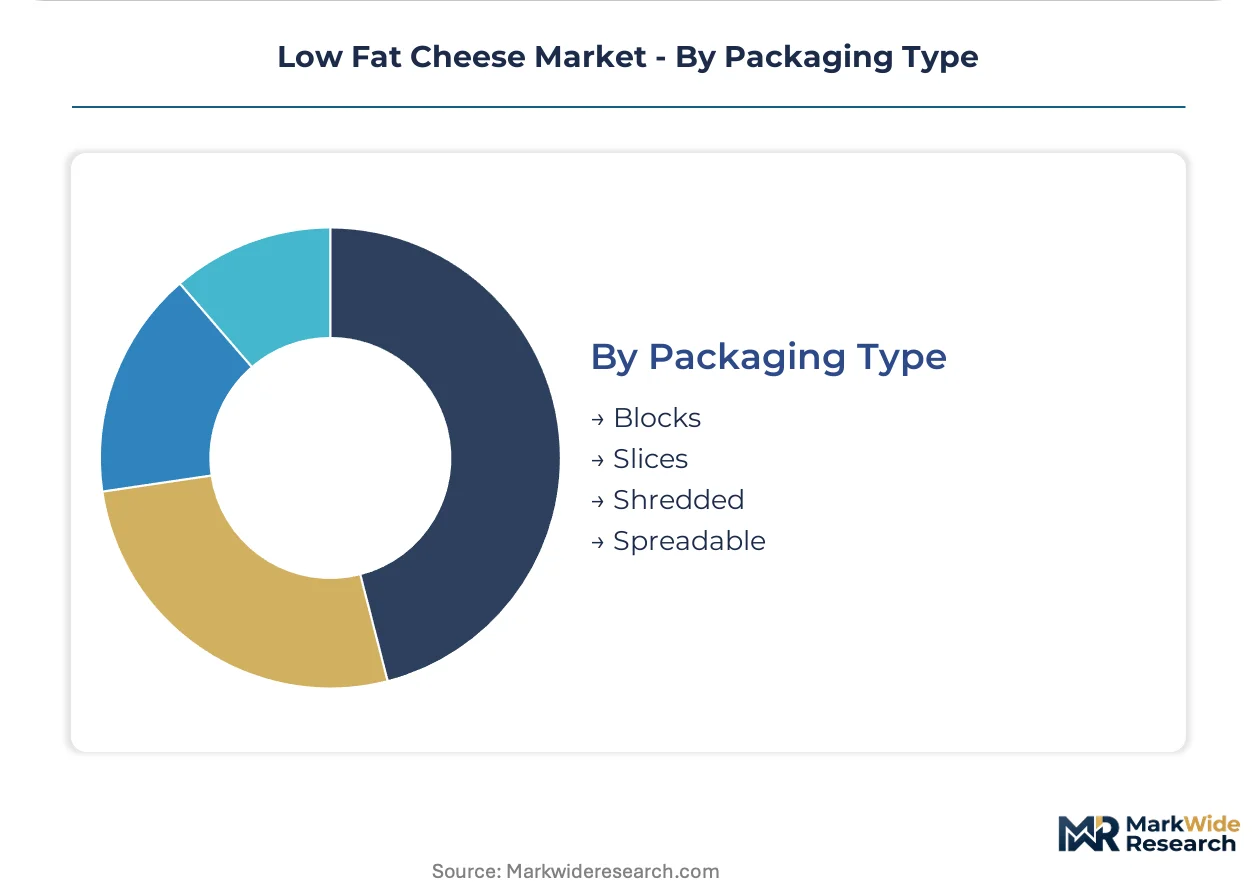
- Shredded:Dominates institutional procurement through labor-cost savings in commercial kitchens and direct integration into automated pizza manufacturing lines in Italy and the United States.
- Slices:Portion-controlled formats harden as dominant configuration in retail and food service, replacing bulk purchasing with standardized serving sizes for healthcare and school nutrition programs.
- Blocks:Retains margin concentration in artisanal retail channels and specialty applications where buyers prioritize cutting flexibility and perceived freshness.
- Spreadable:Custom viscosity specifications anchor sole-source agreements with Einstein Bros. and Bruegger's in the US Northeast corridor, consolidating supplier relationships around formulation flexibility.
Procurement volume sits with shredded; premium positioning tilts toward spreadable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States and European dairy belts while consumption spreads across developed markets with health-conscious retail sectors. Germany and France process significant volumes of reduced-fat variants for domestic retail and export. Italian mozzarella producers supply automated pizza manufacturing lines across Southern Europe and North America.
United States
USDA school nutrition standards and healthcare facility procurement guidelines mandate reduced-fat dairy minimums, institutional buyers like Sodexo and Compass Group pulling high-volume throughput. The FDA governs fat-content labeling claims that determine permissible "low fat" and "reduced fat" designations. Wisconsin and California dairy cooperatives dominate mozzarella production for frozen pizza manufacturers operating automated topping lines.
Germany
Retail chains and institutional buyers prioritize reduced-fat dairy portfolios, with clean-label cheddar and mozzarella variants commanding shelf placement. The EU's F-Gas Regulation and EFSA nutrient profiling criteria tighten permissible health claims and reformulation targets. Bavarian and North Rhine-Westphalia processors retrofit aging plants with low-GWP refrigeration systems to maintain compliance.
Italy
Frozen pizza producers drive shredded low-fat mozzarella procurement for automated manufacturing equipment, labor-cost savings dictating format preferences. REACH and EU Green Deal methane reporting obligations force dairy cooperatives to document enteric fermentation emissions across milk supply bases. Lombardy and Emilia-Romagna cheese processors integrate carbon accounting into farmer procurement contracts.
France
Food service operators and retail distributors seek portion-controlled slice formats for healthcare and school nutrition programs. ANSM and CNIL oversight intersects with EFSA front-of-pack labeling mandates reshaping permissible nutritional communications. The Paris Basin and Auvergne-Rhône-Alpes clusters face refrigeration technician shortages that delay F-Gas certified plant upgrades.
Canada
Health Canada and PMRA standards govern dairy product compositional thresholds, with private-label development accelerating across supermarket channels. Saputo extends manufacturing scale to control cost positioning in shredded and sliced segments. Ontario and Quebec dairy processors supply cross-border food service contracts while navigating dual USDA-Canadian certification complexity for exported parmesan variants.
Low Fat Cheese Market Key Industry Players
The competitive structure tilts toward diversified dairy conglomerates with multi-format portfolios and private-label manufacturing scale. Tier-one processors leverage retail shelf-space dominance and institutional contract volume to anchor market position. Strategic archetypes include clean-label heritage specialists, scale-driven private-label manufacturers, and retail-brand conglomerates with cross-category dairy presence. Dominant competitive moves center on membrane filtration technology licensing and direct-to-foodservice platform development bypassing traditional retail slotting fees.
Among North American dairy conglomerates, Kraft Heinz Company and Saputo Inc. exemplify scale-driven archetypes with multi-format low-fat cheese portfolios spanning shredded, sliced, and block configurations. Arla Foods represents the clean-label heritage specialist, competing on Nordic dairy credentials in premium urban markets. Sargento Foods Inc. occupies a position within the portion-control innovation tier, while Bel Group and Lactalis Group anchor European-origin competitive presence with diversified reduced-fat dairy portfolios across retail and food service channels.
| Leading Market Players |
|---|
| Sargento Foods Inc. |
| Bel Group |
| Kraft Heinz Company |
| Nestlé S.A. |
| Dairy Farmers of America |
| Arla Foods |
| Saputo Inc. |
| Danone S.A. |
| Lactalis Group |
| Others |
Cost & Logistics Intelligence
F-Gas certified refrigeration technician scarcity in France and Germany widens pricing-tier spreads as labor-cost differentials between compliant and non-compliant plants force three-tier pricing structure across premium, standard, and economy levels. Buyers with USDA school nutrition contracts absorb premium tier costs while commodity shredded mozzarella purchasers face margin compression from input volatility.
Pricing Analysis
Margin tightening in economy-tier shredded mozzarella reflects New Zealand and EU dairy auction volatility transmitting directly to skim milk powder input costs. Pricing stratifies across premium, standard, and economy tiers based on clean-label certification status and membrane filtration technology deployment. Cost-down pressure on block formats accelerates because artisanal retail channels resist portion-controlled conversion. Food service providers exhibit lowest price sensitivity due to institutional contract anchoring, while private-label retail buyers drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-foodservice channels through Sysco and US Foods bypass traditional supermarket slotting fees for institutional volume commitments. Supply concentrates in Wisconsin and California for mozzarella, Bavaria and North Rhine-Westphalia for clean-label cheddar, and Lombardy for pizza-grade shredded formats. Raw material flows draw from New Zealand skim milk powder auctions, Nordic membrane filtration equipment, and domestic fluid milk cooperatives. Single-source vulnerability sits with F-Gas certified refrigeration component suppliers delaying plant upgrades. Distribution runs through cold-chain logistics networks with temperature-validated last-mile delivery to bagel chains and frozen pizza manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where membrane filtration technology licensing and captive skim milk solids recovery determine cost positioning. Players pursuing upstream protein yield advantages through ceramic membrane deployment will outcompete commodity processors on institutional contract margins.
For Market Incumbents: Deploy membrane filtration scale-up in Wisconsin and Bavarian processing clusters to defend against precision fermentation entrants threatening fat-free cheese adjacencies. Lock in sole-source agreements with Einstein Bros.-type bagel chains through custom viscosity specification capabilities. Absorb F-Gas compliance capital burden before smaller cooperatives exit, consolidating procurement share in German retail chains.
For New Entrants and Emerging Players: Capture plant-forward hybrid spread opportunities blending dairy protein with oat bases to bypass EFSA's strict dairy-only nutrient profiling thresholds. Target US Northeast corridor cream cheese consolidation through formulation flexibility offers. Build direct-to-foodservice platforms with Sysco private-label portals avoiding retail slotting fee barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with ceramic membrane-equipped mid-cap processors given protein yield advantages rewriting shredded mozzarella economics. Five-to-ten year viability favors facilities with integrated carbon accounting for EU Green Deal methane reporting compliance. Watch for F-Gas certified technician training program announcements as inflection signal for upgrade-ready asset bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Arla and Saputo deployments recover 15% more protein per liter, collapsing cost structures for institutional contracts. |
| Direct-to-Foodservice Platform Development | Sysco and US Foods portals bypass retail slotting fees, connecting processors to Sodexo and Compass Group volume. |
| F-Gas Compliance Retrofit Programs | Bavarian and North Rhine-Westphalia plants secure regulatory continuity while smaller cooperatives face exit pressure. |
| Precision Fermentation Casein Investment | Microbial-derived proteins enable kosher and lactose-free fat-free cheese structures with authentic dairy functionality. |
| Carbon Accounting Integration | Danish and Dutch producers document enteric fermentation emissions to retain German and French retail shelf placement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across dairy processing executives, food service procurement directors, membrane filtration technology suppliers, F-Gas certification auditors, and retail category managers. USDA grade standards documentation, EU F-Gas Regulation implementation reports, EFSA nutrient profiling criteria updates, and New Zealand dairy auction price series provided compositional and cost benchmarks. Bottom-up volume modeling across product types and end-user segments triangulated against top-down market sizing from trade association aggregates.
Segmentation granularity operated at product type, end user, distribution channel, packaging format, and regional production cluster levels across the analysis window. CAGRs derived from trend extrapolation of membrane filtration adoption rates, institutional contract growth patterns, and clean-label certification penetration curves. Forecast inputs incorporated F-Gas compliance timelines, EU Green Deal methane reporting phase-ins, and precision fermentation technology readiness assessments without year-specific milestone assumptions.
The model holds under stable skim milk powder auction volatility and F-Gas technician training program expansion; deviation in New Zealand drought frequency or EU refrigerant supply chain disruption would shift volume and value trajectories. Forecasts reflect documented assumptions about membrane filtration yield improvements and institutional procurement guideline stability. Periodic stress-testing of base assumptions is recommended against dairy commodity price shock scenarios and regulatory enforcement intensity variations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Dairy Protein Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
North America Condensed Milk Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
India Milk Protein Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
GCC Cheese Market
Dairy Products
Cheddar Cheese Market