
 Emmental Cheese Market | 2026-2036
Emmental Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Emmental Cheese Market Foresight
Foodservice applications for melted-cheese dishes and premium sandwiches is realigning procurement patterns across the value chain. Emmi Group leverages its Swiss heritage and protected-origin sourcing to sustain price premiums in European foodservice channels. Arla Foods amba anchors its competitive position through cooperative-scale milk collection and controlled ripening facilities across Denmark and Sweden. Lactalis Group dominates retail distribution in France through deep supermarket relationships and private-label capacity.
Emmental denotes a hard, cooked-curd cheese with characteristic walnut-sized eyes, produced from cow's milk using propionic acid bacteria fermentation at temperatures between 22°C and 25°C during a three-to-four-month aging period; its primary commercial purpose centers on slicing, melting, and table-cheese applications across retail and foodservice channels. Traditional Emmental occupies the mature volume base, with margin pools concentrating in aged wheels bearing AOP or AOC designation. Organic Emmental registers the fastest structural expansion, driven by German and Swiss retail chains reformulating private-label lines. The grated and sliced packaging formats capture disproportionate foodservice demand as kitchen-labor costs rise across European restaurant chains.
EU food safety frameworks through EFSA and national regulators such as France's DGCCRF enforce strict pathogen limits and labeling rules for raw-milk aged cheeses, directly shaping market access for non-EU suppliers. The EU Green Deal's Farm to Fork targets on methane reduction and feed sustainability are forcing dairy cooperatives to document herd-level emissions or risk losing retail listings. Stakeholders must monitor how carbon-border adjustments on imported dairy protein reshape cost structures for New Zealand and South American competitors seeking European shelf space.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is forcing dairy processors to restructure feed sourcing and document herd-level methane emissions, compressing margins for non-compliant suppliers while advantaging cooperatives with integrated sustainability tracking.
Growth Catalysts
- Propionic acid bacteria optimization:Controlled fermentation protocols at 22-25°C are shortening aging cycles without compromising eye formation, allowing processors to release working capital faster.
- German retail chain reformulation:Rewe, Edeka and Aldi Süd are expanding organic-certified Emmental SKUs across standard and premium private-label tiers, creating pull-through for certified milk suppliers.
- Fondue and premium burger expansion:Swiss and French foodservice operators are specifying aged-wheel Emmental for melting applications, locking in volume commitments with designated-origin producers.
Market Restraints
- Raw milk price volatility:Swiss and French farmgate milk prices fluctuate with fodder costs and Alpine weather patterns, compressing processor margins during drought cycles.
- Protected designation enforcement:Swiss AOP and French AOC regulations restrict "Emmental" labeling to territorial production, blocking non-European suppliers from premium positioning.
- Plant-based cheese substitution:Oat and cashew-based melting alternatives are capturing shelf space in Scandinavian and Benelux retail, particularly among flexitarian households.
Strategic Opportunities
- Carbon-neutral certification:The EU Green Deal's methane reduction targets create first-mover advantage for cooperatives achieving net-zero herd emissions and securing retail listings.
- Grated and sliced format expansion:Labor cost pressures across French and German restaurant chains are driving foodservice procurement toward pre-processed formats with extended shelf stability.
- Swiss gastronomy tourism:Fondue-themed hospitality experiences in Gruyère and Emmental regions are creating direct-to-consumer channels bypassing traditional retail markups.
Industry Challenges
- Affineur skill scarcity:Traditional wheel-turning and eye-development expertise is concentrated among aging specialists in Jura and Savoie, with limited apprenticeship pipeline replacement.
- EFSA pathogen compliance timelines:Raw-milk aged cheese testing protocols for Listeria and E.coli extend batch release cycles, tying up inventory and testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emmental Cheese Market |
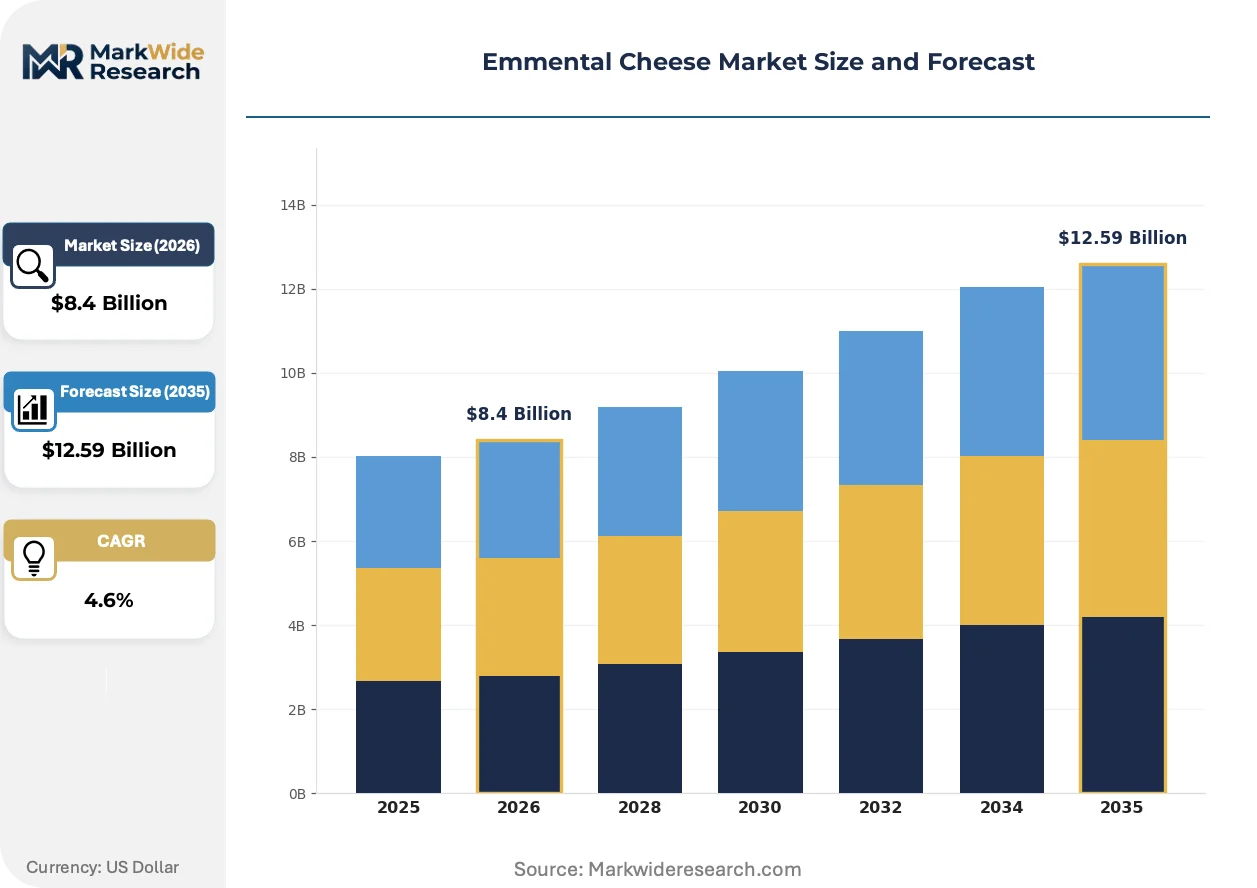
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Emmental, Organic Emmental, Reduced-Fat Emmental, Flavored Emmental Application: Culinary Use, Snacks, Sandwiches, Cheese Boards Distribution Channel: Retail Stores, Online Stores, Specialty Cheeses, Food Services Packaging Type: Blocks, Slices, Grated, Cubes |
| Companies Covered | Lactalis Group, The Kraft Heinz Company, Emmi Group, Savencia Fromage & Dairy, DMK Deutsches Milchkontor GmbH, Arla Foods amba, Koninklijke FrieslandCampina N.V., Bel S.A., Hochland SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emmental Cheese Market Shifts & Advancements
Digital monitoring systems and sustainability verification protocols are restructuring how Emmental producers manage ripening, traceability, and buyer relationships across European supply chains.
Computer-vision eye-formation monitoring is absorbing quality-control functions previously executed by master affineurs. Danish and Swedish controlled-ripening facilities are deploying camera arrays to track propionic acid bacteria activity in real time. This technology is absorbing subjective judgment from wheel assessment, compressing the skill premium traditionally commanded by regional specialists.
The EU Green Deal's Farm to Fork methane reduction mandates are reshaping feed procurement across Alpine cooperatives. France's DGCCRF and Switzerland's Federal Food Safety and Veterinary Office are aligning inspection protocols with documented carbon intensity per kilogram of milk. AOP-designated producers in Franche-Comté and Emmental are responding by locking multi-year contracts with regenerative fodder suppliers.
Foodservice buyers are consolidating cheese procurement through centralized distribution platforms rather than direct affineur relationships. German and Austrian restaurant chains are routing Emmental orders through Metro AG and Transgourmet's digital portals, displacing traditional regional broker networks. This concentration is most visible in Bavaria and Baden-Württemberg, where multi-unit operators prioritize invoice consolidation over provenance storytelling.
Emmental Cheese Market Segmentation
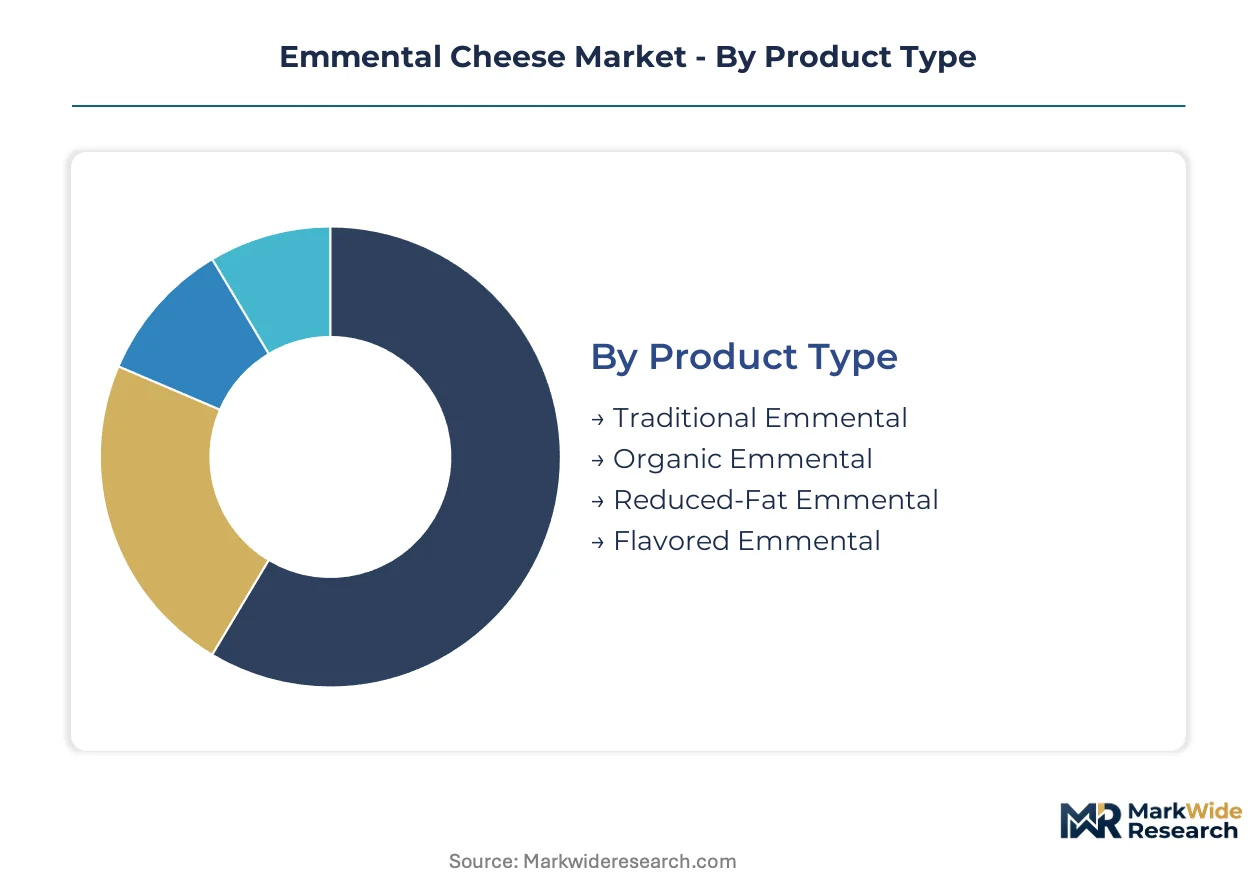
Emmental cheese procurement patterns diverge sharply across buyer types, from industrial foodservice operators optimizing kitchen labor to Alpine tourism operators seeking provenance credentials. Segmentation reveals how aging specifications, format convenience, and certification status command discrete price premiums and distribution channels.
Product Type:
Buyers in this category separate on willingness to pay for certification tier and production method, with foodservice chains prioritizing melt consistency while retail organic shoppers prioritize feed documentation.
- Traditional Emmental:Aged wheels produced under Swiss AOP or French AOC protocols using raw cow's milk and propionic acid bacteria fermentation at 22-25°C over three to four months. Volume concentrates in French and Swiss foodservice channels where fondue houses and premium burger chains specify designated-origin wheels for melting performance. Protected designation enforcement blocks non-European suppliers from this tier, insulating margin pools for Jura and Emmental region cooperatives.
- Organic Emmental:Certified production requiring documented regenerative feed sourcing and restricted antibiotic use, with full herd-level methane tracking under EU Green Deal compliance frameworks. German retail chains Rewe, Edeka, and Aldi Süd are expanding organic SKUs across private-label tiers, creating pull-through demand for certified Alpine milk suppliers. This tier captures the steepest expansion trajectory as sustainability verification becomes a retail listing requirement.
- Reduced-Fat Emmental:Modified curd processing achieves lower fat content while maintaining eye formation, targeting health-conscious retail segments in Scandinavia and Benelux.
- Flavored Emmental:Wheels infused with herbs, spices, or smoke during aging, occupying specialty cheese counter positioning in French and Swiss gourmet retail.
Volume sits with Traditional Emmental; growth tilts toward Organic Emmental.
Application:
End-use concentration determines format specifications and procurement scale, with industrial buyers driving pre-processing demand while experience retail commands whole-wheel aging.
- Culinary Use:Melting applications for fondue, gratins, and sauce bases require consistent fat-protein ratios and reliable eye distribution. Swiss and French foodservice operators are locking multi-year volume commitments with designated-origin producers as Alpine tourism expands fondue-themed hospitality experiences in Gruyère and Emmental regions.
- Sandwiches:Deli and quick-service operators specify pre-sliced formats with extended shelf stability to compress kitchen labor costs. German and Austrian restaurant chains route procurement through Metro AG and Transgourmet digital portals, consolidating orders away from traditional affineur relationships.
- Snacks:Portion-controlled cubes and string formats target convenience retail in urban Swiss and German markets.
- Cheese Boards:Aged wheels with pronounced eye patterns and rind integrity command direct-to-consumer channels and specialty retail markup in French gastronomy tourism corridors.
Procurement scale favors Culinary Use; margin expansion concentrates in Cheese Boards.
Distribution Channel:
Channel selection reflects buyer sophistication tier, with centralized platforms absorbing mid-market volume while specialty affineurs retain premium positioning.
- Food Services:Institutional and chain restaurant buyers prioritize invoice consolidation and format standardization over provenance storytelling. Bavarian and Baden-Württemberg multi-unit operators have shifted volume to Metro AG and Transgourmet portals, displacing regional broker networks across southern Germany.
- Retail Stores:French supermarket operators Carrefour and Intermarché dominate volume through private-label capacity and deep supplier relationships with Lactalis Group processing facilities.
- Specialty Cheeses:Affineur-curated selections in Jura and Savoie maintain price premiums through wheel-turning expertise and direct producer relationships.
- Online Stores:Direct-to-consumer platforms bypass retail markups for Alpine tourism visitors seeking souvenir-aged wheels.
Transaction volume concentrates in Food Services; margin retention favors Specialty Cheeses.
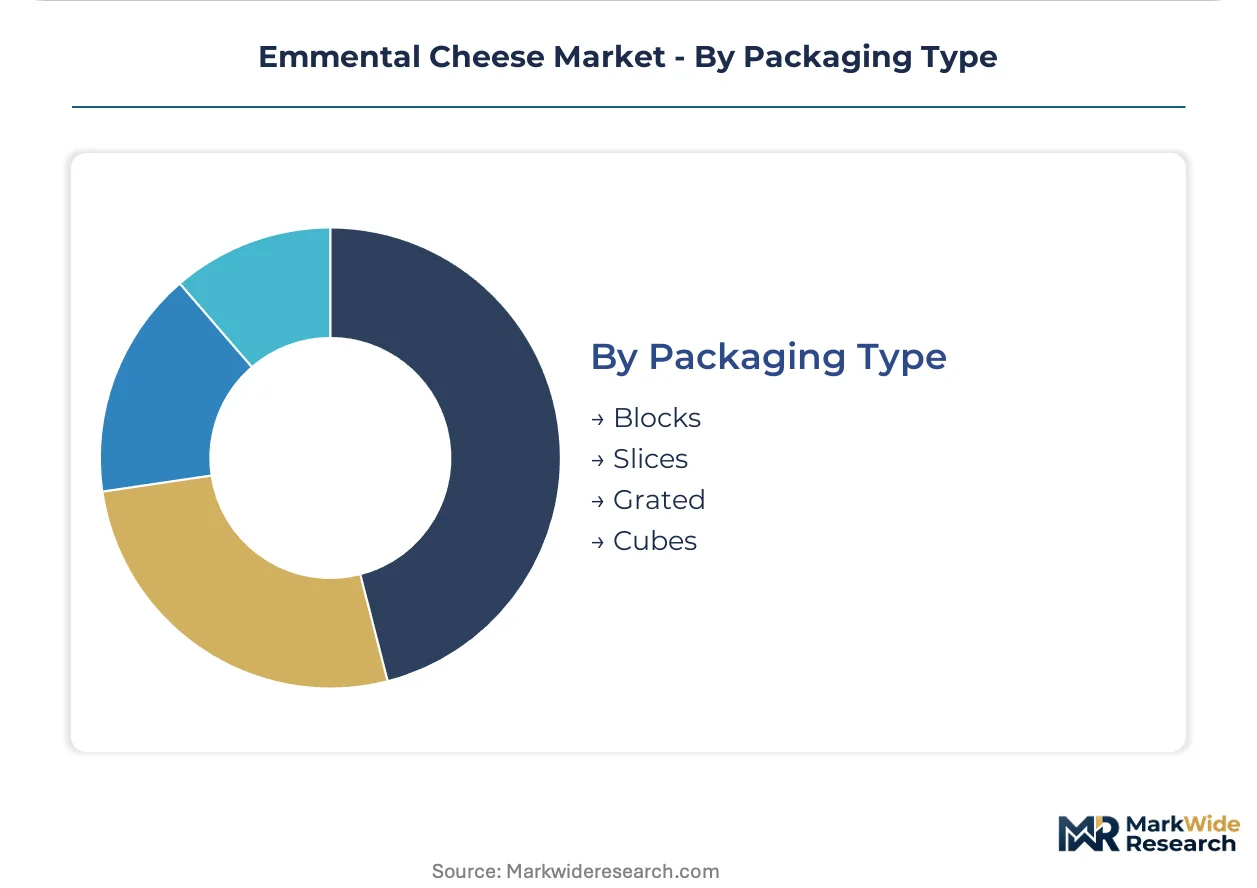
Packaging Type:
Labor cost pressures and shelf-life requirements differentiate buyer preferences, with foodservice chains driving pre-processing adoption while traditional retail maintains block formats.
- Grated:Pre-shredded formats with anti-caking treatment target industrial kitchens and frozen food manufacturers seeking consistent melt performance without downstream processing investment.
- Slices:Individually wrapped portions serve quick-service sandwich assembly lines across German and Austrian chain networks.
- Blocks:Whole or partial wheels retain moisture control and aging flexibility for affineur-managed ripening in Franche-Comté and Emmental region cellars.
- Cubes:Snack-portion formats target convenience retail and airline catering contracts in Swiss and Benelux markets.
Format innovation concentrates in Grated and Slices; traditional volume remains with Blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's Emmental AOP zone and France's Franche-Comté AOC belt concentrate heritage production capacity. German retail consolidation and Austrian foodservice digitization reshape distribution economics across adjacent markets.
Switzerland
Swiss fondue tourism and premium burger chains drive aged-wheel procurement from Emmental region cooperatives. The Federal Food Safety and Veterinary Office enforces AOP labeling integrity and methane documentation under Farm to Fork alignment. Affineurs in Burgdorf and Langnau manage extended ripening for gastronomy direct-to-consumer channels.
France
French foodservice operators specify AOC-designated wheels for melting applications in Alpine hospitality concepts. DGCCRF enforces raw-milk pathogen testing protocols that extend batch release cycles for Jura producers. Cellars in Poligny and Lons-le-Saunier concentrate traditional wheel-turning expertise for export-grade selection.
Germany
Rewe, Edeka and Aldi Süd chains expand organic-certified private-label SKUs, pulling certified milk through Bavarian and Baden-Württemberg cooperatives. The Federal Ministry of Food and Agriculture implements Farm to Fork feed sustainability verification for retail listing eligibility. Dairy processors in Allgäu and Upper Bavaria scale grated and sliced format capacity for restaurant chain procurement.
Austria
Viennese and Salzburg restaurant chains route Emmental procurement through Metro AG and Transgourmet digital portals, displacing regional broker networks. The Austrian Agency for Health and Food Safety aligns inspection protocols with EU Green Deal methane tracking requirements. Foodservice distributors in Lower Austria consolidate invoice processing for multi-unit operators.
Emmental Cheese Market Competitive Landscape
Top-tier vendors anchor protected-origin heritage production, while mid-scale cooperatives and private-label processors compete on format convenience and sustainability certification. Market structure reflects tiered access to AOP/AOC designation, with ripening expertise and retail chain relationships determining margin capture. Strategic archetypes include Alpine heritage cooperatives, pan-European dairy conglomerates with affineur networks, and German retail-centric private-label specialists. Dominant competitive moves center on carbon-neutral herd certification and pre-processed format expansion for foodservice labor cost compression.
Among Swiss heritage anchors, Emmi Group represents AOP-protected origin positioning, while Lactalis Group exemplifies retail distribution scale across French supermarket networks. Arla Foods amba occupies the cooperative-scale tier with controlled-ripening infrastructure across Nordic markets.
| Leading Market Players |
|---|
| Lactalis Group |
| The Kraft Heinz Company |
| Emmi Group |
| Savencia Fromage & Dairy |
| DMK Deutsches Milchkontor GmbH |
| Arla Foods amba |
| Koninklijke FrieslandCampina N.V. |
| Bel S.A. |
| Hochland SE |
| Others |
Supply & Pricing Matrix
German retail chain procurement concentration anchors Emmental pricing dynamics, with Rewe, Edeka and Aldi Süd leveraging volume commitments to compress supplier margins while demanding organic certification premiums. This buyer archetype dominance forces processors to absorb feed cost volatility or risk delisting, creating a contract-plus-spot hybrid model where long-term private-label agreements secure baseline volume and spot sales capture weather-driven milk price spikes.
Pricing Analysis
Short lead-time premiums command substantial markups in Swiss foodservice channels, where fondue houses and premium burger chains pay above-contract rates for designated-origin wheels released from affineur cellars on compressed timelines. Pricing stratifies across AOP-designated heritage tiers, organic-certified retail lines, and commodity-grade industrial inputs, with certification grade and volume scale as the primary differentiation levers. Cost compression in organic feed sourcing is intensifying because Alpine cooperatives face regenerative fodder contract escalation, while German retail buyers exhibit highest price sensitivity and Swiss gastronomy tourism operators show lowest elasticity.
Supply Chain Analysis
Raw milk supply rests on Swiss, French and German Alpine cooperative networks, with propionic acid bacteria cultures and regenerative fodder inputs as critical dependencies. Swiss AOP and French AOC regulations enforce geographic sourcing restrictions that tether production to Jura, Emmental and Franche-Comté terroirs, creating single-source vulnerability for heritage-grade wheels. Distribution runs through Metro AG and Transgourmet digital portals for foodservice consolidation, while retail volume flows through Lactalis Group processing facilities and Carrefour private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emmental cheese manufacturing is consolidating around carbon-neutral certification compliance, with EU Green Deal methane documentation requirements forcing non-compliant processors toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from plant-based cheese substitution in Scandinavian retail by locking multi-year regenerative fodder contracts and accelerating grated-format capacity expansion in Bavarian processing facilities. Affineur skill scarcity in Jura and Savoie demands apprenticeship pipeline investment or automated eye-formation technology deployment to defend heritage-tier positioning against Danish controlled-ripening facilities.
For New Entrants and Emerging Players: Direct-to-consumer platforms offer the most penetrable route, targeting Alpine tourism souvenir channels and online specialty cheese subscriptions with carbon-neutral certified wheels that bypass established retail markups. White-space concentration sits in Austrian foodservice digitization and Swiss gastronomy hospitality experiences, with provenance storytelling as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors cooperatives with integrated sustainability tracking and AOP/AOC designation rights, as carbon-border adjustments reshape competitive economics for imported dairy protein. Acquisition targets should display documented herd-level methane reduction and established relationships with German retail chain private-label programs. Watch EU Green Deal feed sustainability verification timelines as the inflection signal for retail listing eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Herd Certification | EU Green Deal methane targets create first-mover retail listing advantage for compliant cooperatives. |
| Grated and Sliced Format Expansion | German restaurant chain labor cost pressures drive procurement toward pre-processed convenience formats. |
| Regenerative Fodder Contract Lock | Multi-year supply agreements with Alpine hay producers secure feed cost predictability under Farm to Fork. |
| Digital Distribution Portal Integration | Metro AG and Transgourmet consolidation displaces regional brokers across Bavarian foodservice networks. |
| Affineur Apprenticeship Pipeline Investment | Traditional wheel-turning expertise scarcity in Jura threatens heritage-grade production capacity. |
Research Methodology
Document review covered EU dairy trade statistics, EFSA pathogen compliance filings, and Alpine cooperative annual reports, complemented by interviews with cheese affineurs, German retail category buyers, French foodservice procurement directors, and Swiss dairy processing executives. Secondary validation drew from Farm to Fork Strategy implementation documents, DGCCRF inspection protocols, and Federal Food Safety and Veterinary Office enforcement records. Bottom-up volume modeling triangulated against top-down retail channel estimates across the analysis window.
Cross-referencing historical production data against expert panel input shaped the analytical framework, with segmentation dimensions spanning product type, application, distribution channel, and packaging format throughout the forecast period. CAGRs emerged from trend extrapolation moderated by regulatory compliance cost assumptions, with propionic acid bacteria optimization timelines and organic certification adoption curves as cheese-specific forecast inputs.
The model holds under stable EU Green Deal implementation timelines; deviation in methane reduction target acceleration or carbon-border adjustment scope would shift competitive cost structures. Forecasts reflect documented feed sustainability verification requirements and pathogen testing protocol durations. A small set of triggers—Swiss AOP enforcement tightening, German retail chain consolidation pace, and plant-based substitution rates in Benelux—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Paneer Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
White Cheese Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Ghee Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Kefir Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Ricotta Market
Dairy Products
Europe Yogurt Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Dairy Blends Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market