
 Germany Milk Protein Market | 2026-2036
Germany Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Milk Protein Market Foresight
Capital-intensity divergence between spray-drying asset owners and toll-dependent processors is bifurcating competitive returns in Germany. Lactoprot Deutschland GmbH leverages captive whey fractionation capacity across northern federal states. MEGGLE GmbH & Co.KG sustains specialized casein production lines serving pharmaceutical-grade contracts. Royal FrieslandCampina N.V. anchors bulk ingredient supply through Rotterdam-German corridor logistics.
Germany milk protein encompasses whey and casein fractions extracted via ultrafiltration, microfiltration, and ion exchange, yielding protein concentrates with 34-89% protein content by dry weight for nutritional fortification and functional food binding. Whey protein dominates volume flows into sports nutrition applications where margin pools deepen around isolate grades. Casein protein occupies slower-growing but defensible positions in infant formula and medical nutrition where regulatory barriers protect incumbent suppliers. Powder form leads all delivery formats due to stability advantages in German distribution networks.
Bundesministerium für Ernährung und Landwirtschaft (BMEL) enforces dairy labeling standards under the Lebensmittel- und Futtermittelgesetzbuch, while EU REACH and EFSA novel food assessments govern protein hydrolysate approvals and sustainability claims. KBA and state-level environmental agencies in Bavaria and Lower Saxony scrutinize dairy processing emissions under national climate targets. Stakeholders must monitor whether EU Green Deal methane reduction mandates will force herd-size constraints that tighten raw milk supply chains before alternative protein technologies mature.
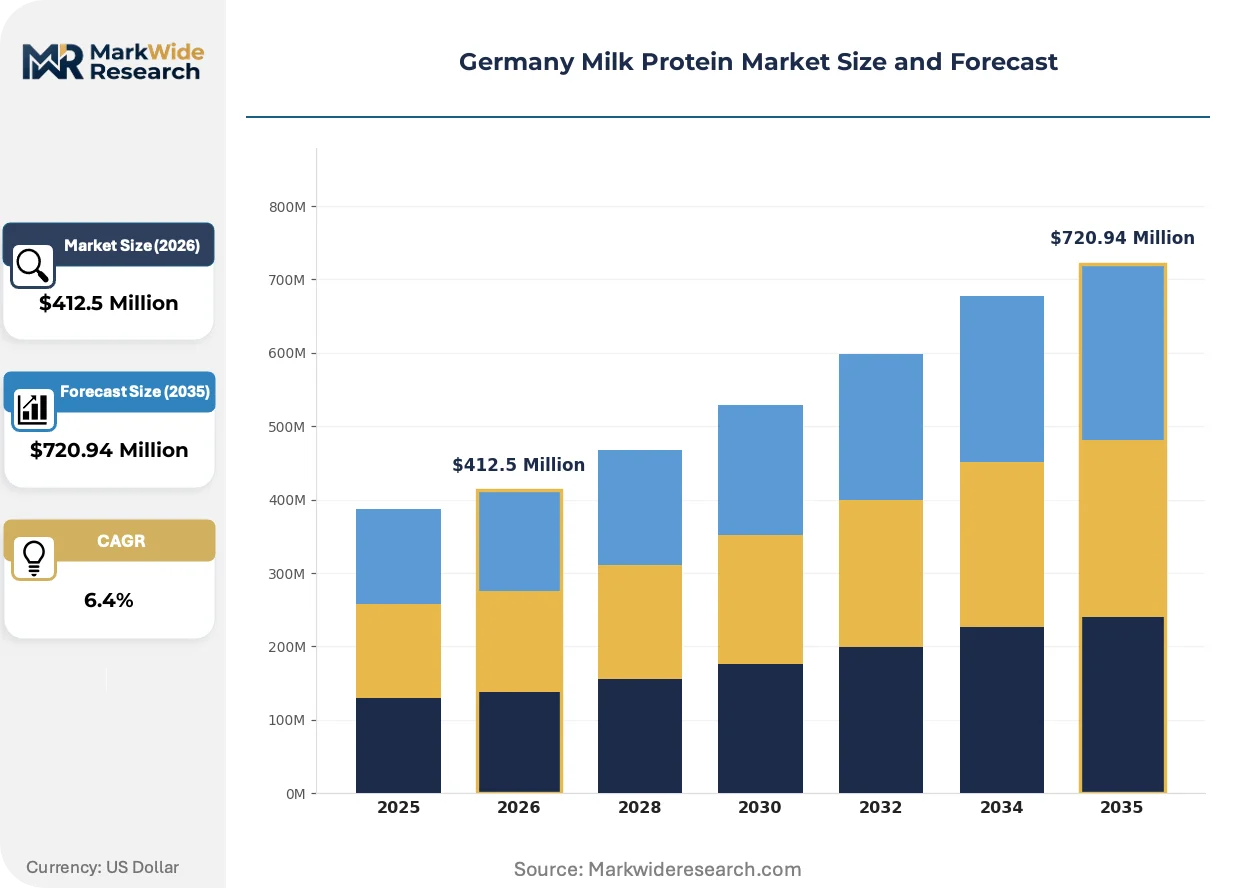
Market Dynamics
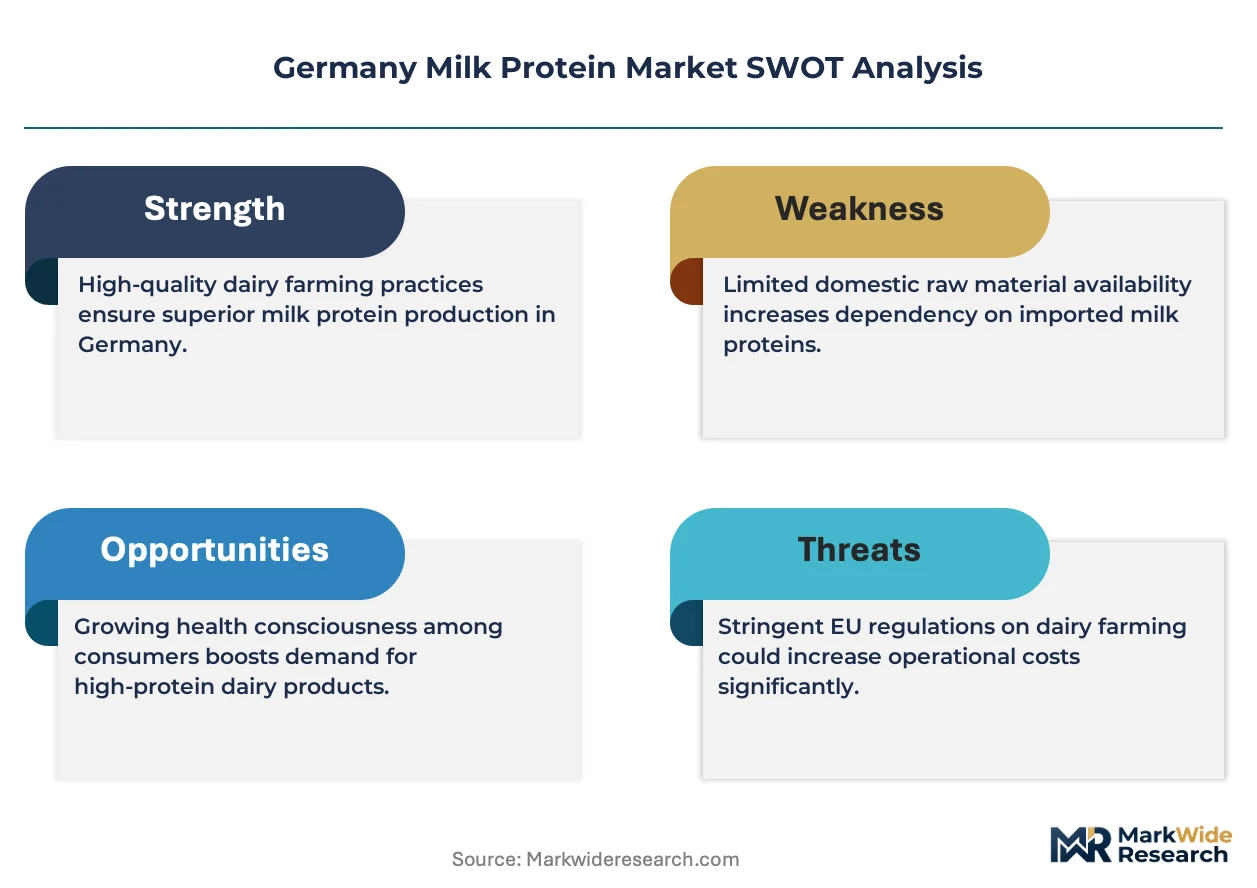
The EU Green Deal's methane reduction mandates are forcing German dairy processors to secure alternative protein feedstocks before herd-size constraints tighten raw milk availability.
Growth Catalysts
- EU Farm to Fork Strategy:Sustainability certification requirements under the European Green Deal are accelerating demand for traceable whey protein fractions in sports nutrition formulations.
- Bavaria's dairy processing corridor:Concentrated ultrafiltration capacity around Munich and Landshut is reducing logistics costs for isolate-grade protein distribution.
- Medical nutrition expansion:EFSA novel food assessments for protein hydrolysates are opening pharmaceutical-grade casein applications in clinical settings.
Market Restraints
- Raw milk supply concentration:Dependence on Lower Saxony and Bavaria dairy cooperatives creates regional weather and feed-cost vulnerability.
- Energy-intensive spray-drying:Natural gas price volatility directly compresses margins for powder-form protein processors.
- Precision fermentation substitutes:Alternative protein technologies from Dutch and Israeli biotech firms threaten long-term whey protein demand.
Strategic Opportunities
- North Rhine-Westphalia underpenetration:Industrial food manufacturing clusters around Cologne-Düsseldorf lack localized fractionation capacity.
- Direct-to-athlete channels:Subscription-based protein delivery models bypass traditional sports nutrition retail intermediaries.
- CSRD-aligned sustainability reporting:Mandatory corporate sustainability disclosures create premium pricing for carbon-audited milk protein.
Industry Challenges
- Fractionation engineering talent:Specialized ultrafiltration and ion exchange operators remain scarce in German technical universities.
- EFSA approval timelines:Novel protein hydrolysate certifications require 18-24 month evaluation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Milk Protein Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate Application: Infant Nutrition, Sports Nutrition, Dietary Supplements, Bakery Ingredients, Beverages Form: Powder, Liquid, Concentrate, Granules End User: Dairy Processors, Nutraceutical Manufacturers, Food & Beverage Producers, Personal Care Companies |
| Companies Covered | Lactoprot Deutschland GmbH, MEGGLE GmbH & Co.KG, Royal FrieslandCampina N.V, Agrial Group, Fonterra Co-operative Group Limited, Savencia Fromage & Dairy, Morinaga Milk Industry Co., Ltd., LAÏTA, Hoogwegt Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Milk Protein Market Shifts & Advancements
Membrane filtration advances and regulatory sustainability mandates are reshaping how German processors extract and position milk protein fractions across nutrition applications.
Cross-flow microfiltration systems with ceramic membranes are bifurcating competitive positioning between capital-heavy asset owners and toll-dependent processors. Sports nutrition brands in Bavaria are adopting isolate-grade whey at accelerated rates. This technology is compressing margins for processors lacking captive fractionation capacity.
REACH chemical safety assessments and EFSA novel food frameworks are tightening purity documentation requirements for protein hydrolysates. German exporters must now submit expanded toxicological data packages for third-country shipments. Infant formula manufacturers are responding by consolidating supplier relationships with vertically integrated fractionators.
Athlete and clinical nutrition buyers are consolidating procurement around certified-sustainable suppliers with blockchain-traceable farm origins. Traditional ingredient distributors in Frankfurt and Hamburg are losing share to direct processor partnerships. This pattern concentrates in premium sports nutrition brands sourcing isolate grades for professional team contracts.
Germany Milk Protein Market Segmentation
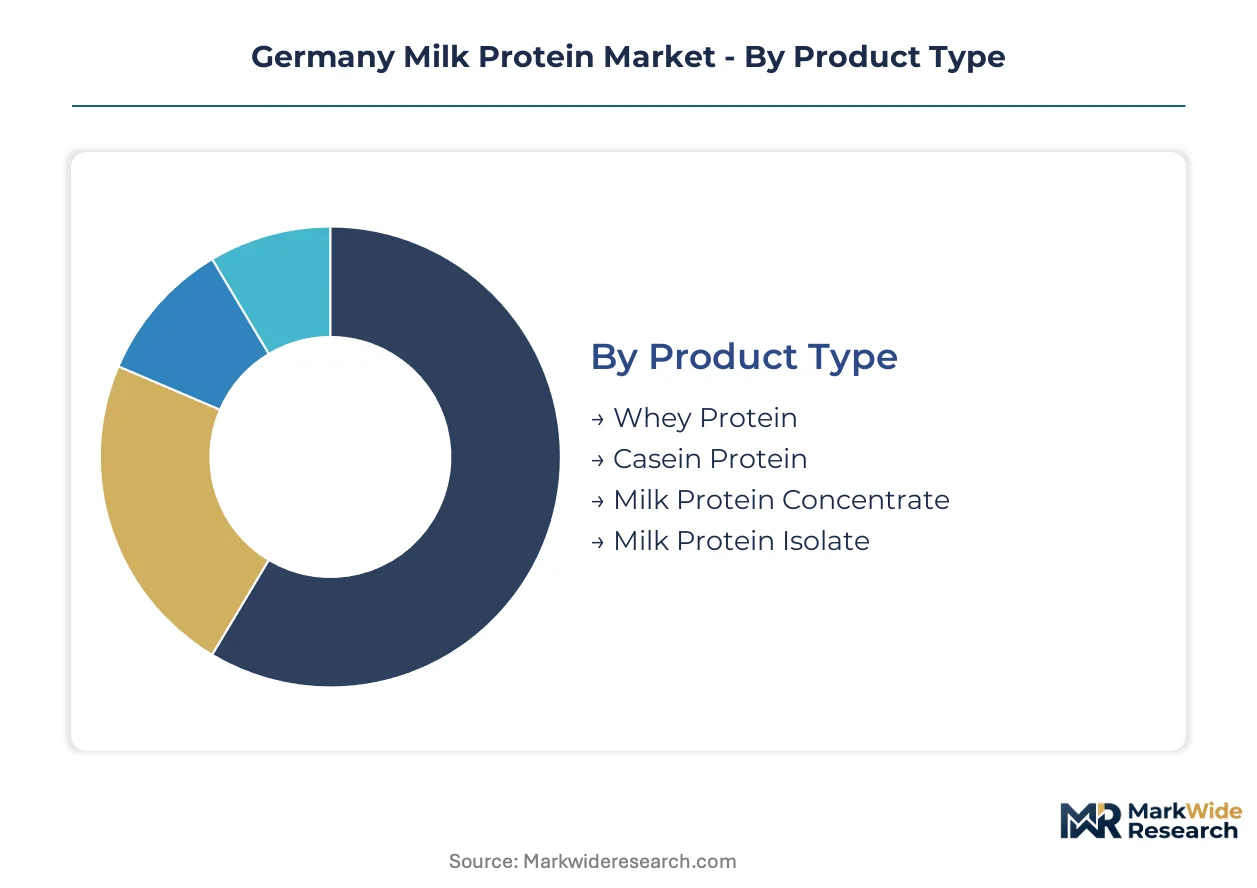
Milk protein fractionation in Germany follows distinct demand curves across product chemistry, end-use specifications, and delivery formats. Each segment faces differential pressure from precision fermentation substitutes and plant-based alternatives reshaping procurement priorities.
Product Type:
Precision fermentation startups in the Netherlands and Israel are targeting whey protein fractions first, forcing casein suppliers to defend their medical nutrition positioning while concentrate grades absorb the steepest price competition.
- Whey Protein:Fast-absorbing fractions with 34-89% protein content by dry weight, produced via ultrafiltration and ion exchange. Sports nutrition brands in Bavaria's Munich-Landshut corridor are accelerating isolate-grade procurement for professional athlete contracts. EFSA novel food assessments for hydrolysates are compressing approval timelines for functional variants.
- Casein Protein:Slow-digesting micellar structures extracted through microfiltration, prized for sustained amino acid release. Infant formula manufacturers in Lower Saxony are consolidating supplier relationships around pharmaceutical-grade contracts where regulatory barriers protect incumbent fractionators. Medical nutrition applications in clinical settings sustain premium positioning against substitute threats.
- Milk Protein Concentrate:Intermediate protein grades serving cost-sensitive bakery and beverage fortification. German dairy processors leverage captive spray-drying assets to defend margin positions.
- Milk Protein Isolate:Highest purity fractions above 90% protein content, commanding premium pricing in specialized clinical applications. Toll-dependent processors struggle against capital-intensive asset owners.
Whey protein anchors the volume base while milk protein isolate gains share at the steepest rate.
Application:
Cost tier differentiation separates pharmaceutical-grade contracts from commodity sports nutrition, with infant formula occupying the most defensible margin position against regulatory scrutiny.
- Infant Nutrition:EFSA novel food frameworks and REACH chemical safety assessments mandate expanded toxicological documentation. Vertically integrated fractionators with captive dairy supply chains dominate procurement relationships.
- Sports Nutrition:Isolate-grade whey demand concentrates in Bavaria's processing corridor. Subscription-based direct-to-athlete channels are bypassing traditional Frankfurt and Hamburg distributors.
- Dietary Supplements:Powder-form protein dominates stability advantages in German distribution networks. Blockchain-traceable farm origins are becoming mandatory for premium positioning.
- Bakery Ingredients:Functional binding properties drive milk protein concentrate adoption. Energy-intensive spray-drying costs are compressing margins for natural gas-dependent processors.
- Beverages:Ready-to-drink formulations require liquid concentrate compatibility. North Rhine-Westphalia's Cologne-Düsseldorf manufacturing cluster lacks localized fractionation capacity.
Infant nutrition sustains the most defensible margins while sports nutrition expands most quickly.
Form:
Supply concentration in Bavaria and Lower Saxona favors powder stability, while liquid formats face logistics constraints that granule technologies are beginning to address.
- Powder:Dominant delivery format leveraging stability advantages across German distribution networks. Spray-drying asset owners in northern federal states capture premium logistics efficiency.
- Liquid:Concentrated protein suspensions for beverage manufacturing. Cold-chain requirements limit geographic reach from dairy processing corridors.
- Concentrate:Intermediate viscosity products for industrial food manufacturing. KBA and state environmental agencies scrutinize processing emissions under national climate targets.
- Granules:Emerging instant-dissolve formats targeting convenience-driven sports nutrition. Ceramic membrane filtration advances are enabling new texture specifications.
Powder form commands the installed production base while granules climb the fastest.
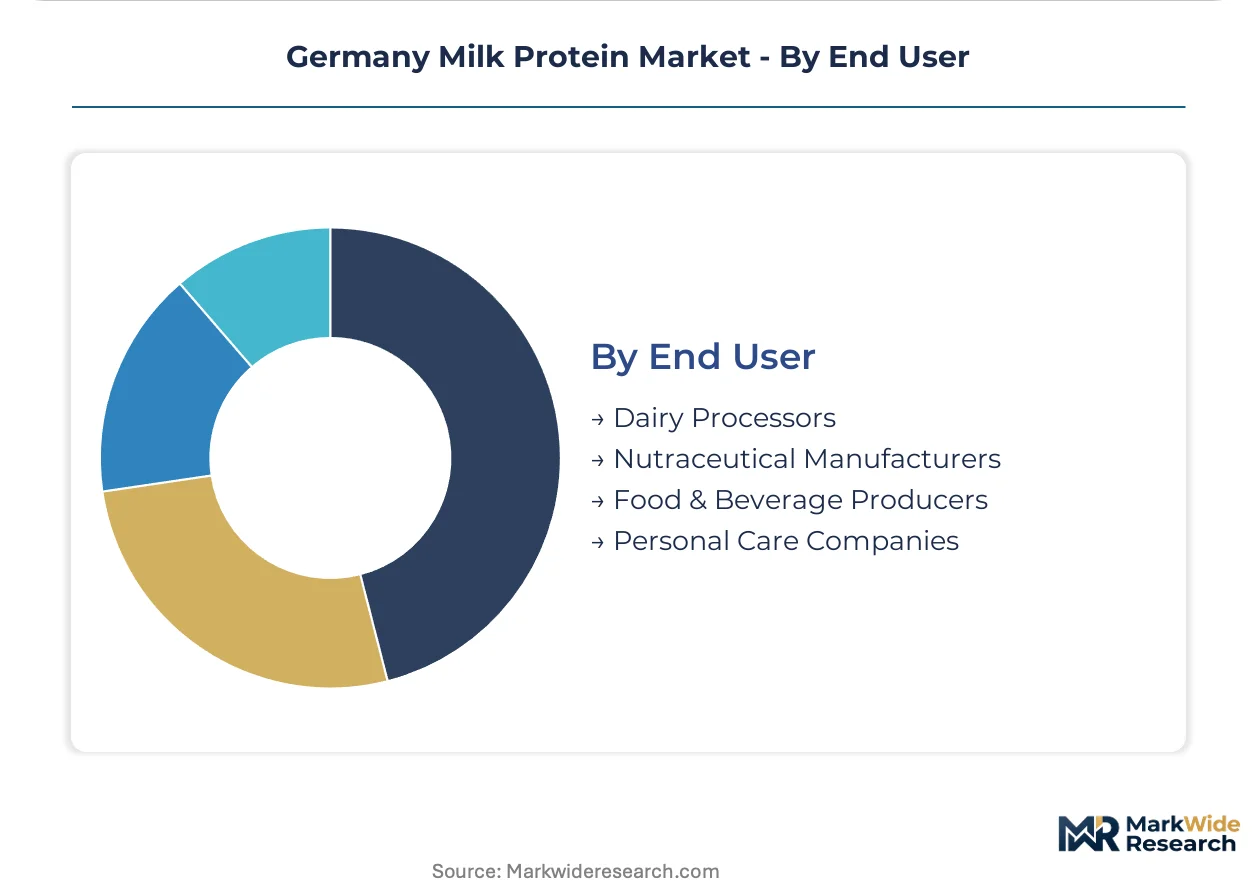
End User:
Customer type maturity separates established dairy processors with captive fractionation from nutraceutical entrants dependent on toll manufacturing relationships.
- Dairy Processors:Incumbents with ultrafiltration and ion exchange capacity across northern federal states. Lactoprot Deutschland GmbH leverages backward integration into whey fractionation.
- Nutraceutical Manufacturers:Specialized casein production lines serve pharmaceutical-grade contracts. MEGGLE GmbH & Co.KG sustains defensible positioning through technical expertise scarcity.
- Food & Beverage Producers:Bulk ingredient procurement through Rotterdam-German corridor logistics. Royal FrieslandCampina N.V. anchors supply security for industrial accounts.
- Personal Care Companies:Hydrolyzed protein fractions for cosmetic applications. EFSA approval timelines of 18-24 months delay product launch cycles.
Dairy processors anchor supply security while nutraceutical manufacturers deepen margin capture fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German milk protein consumption concentrates in sports nutrition corridors while medical nutrition clusters favor casein fractions, creating a geography-driven demand split absent in neighboring markets. Federal state specialization shapes procurement patterns more than national aggregates suggest.
Bavaria
Professional athlete contracts and sports nutrition brand headquarters drive isolate-grade whey demand through the Munich-Landshut processing corridor. KBA and state environmental agencies scrutinize dairy processing emissions under national climate targets. Ultrafiltration capacity concentration reduces logistics costs for isolate distribution to southern German markets.
Lower Saxony
Infant formula manufacturers anchor pharmaceutical-grade casein procurement around dairy cooperative supply chains. BMEL enforces dairy labeling standards under the Lebensmittel- und Futtermittelgesetzbuch. MEGGLE GmbH & Co.KG sustains specialized production lines serving medical nutrition contracts from facilities in this northern dairy belt.
North Rhine-Westphalia
Industrial food manufacturing clusters around Cologne-Düsseldorf lack localized fractionation capacity, creating procurement inefficiencies for bakery and beverage fortification. EU REACH chemical safety assessments govern protein hydrolysate approvals for exporters. This underpenetration represents expansion opportunity for processors with captive spray-drying assets.
Hamburg
Traditional ingredient distributors lose share to direct processor partnerships as athlete and clinical nutrition buyers consolidate procurement. Rotterdam-German corridor logistics anchor bulk ingredient supply security. Royal FrieslandCampina N.V. leverages this northern port access for industrial account servicing.
Baden-Württemberg
Precision engineering suppliers for membrane filtration systems cluster around Stuttgart, enabling ceramic membrane technology adoption. State-level environmental agencies coordinate with federal climate targets on processing emissions. Cross-flow microfiltration system deployment from this region supports fractionation advances across German dairy processors.
Germany Milk Protein Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive fractionation capacity separating margin capture from toll-dependent processors. Three strategic archetypes dominate: northern federal state processors with backward integration into whey supply, pharmaceutical-grade casein specialists serving regulated medical nutrition, and Rotterdam-corridor bulk suppliers anchoring industrial procurement. Competitive moves center on membrane filtration capacity expansion and direct-to-brand partnership structures that bypass traditional distribution.
Within the integrated processor tier, Lactoprot Deutschland GmbH represents captive whey fractionation positioning across northern federal states. MEGGLE GmbH & Co.KG exemplifies the pharmaceutical-grade specialist archetype through its GmbH structure and technical focus. Royal FrieslandCampina N.V. anchors the bulk supply vector, with its N.V. designation indicating Dutch corporate origins and Rotterdam-German corridor logistics access. These three entities occupy positions reflecting the market's tripartite segmentation between sports nutrition volume, medical nutrition premium, and industrial commodity supply.
| Leading Market Players |
|---|
| Lactoprot Deutschland GmbH |
| MEGGLE GmbH & Co.KG |
| Royal FrieslandCampina N.V |
| Agrial Group |
| Fonterra Co-operative Group Limited |
| Savencia Fromage & Dairy |
| Morinaga Milk Industry Co., Ltd. |
| LAÏTA |
| Hoogwegt Group |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day raw milk inventory cycles at Bavarian ultrafiltration facilities concentrate pricing power among asset owners with captive whey fractionation, while spot-dependent processors absorb margin volatility from natural gas-linked spray-drying costs.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade casein procurement, locking in eighteen to twenty-four month price bands for infant formula manufacturers. Three-tier pricing structure across isolate, concentrate, and hydrolysate grades separates premium medical nutrition from commodity sports nutrition. Cost compression in concentrate tiers intensifies because Dutch precision fermentation startups erode whey protein pricing benchmarks. Industrial food manufacturers exhibit highest price sensitivity, while clinical nutrition buyers prioritize EFSA certification tiers over unit economics.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on the Rhine-German corridor elevate inbound logistics costs for membrane filtration equipment imports. Raw material sourcing draws from Dutch dairy cooperatives, New Zealand whey powder exporters, and domestic Bavarian milk pools. Single-source vulnerability concentrates in ceramic membrane supply from Baden-Württemberg precision engineering clusters. Distribution runs through direct processor partnerships that displace traditional Frankfurt and Hamburg ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-traceable farm origin platforms are reshaping procurement interoperability between dairy processors and sports nutrition brands, creating network-effects advantages for early standard-setters.
For Market Incumbents: Secure backward integration into whey fractionation capacity across northern federal states before herd-size constraints tighten under EU Green Deal methane mandates. Deepen pharmaceutical-grade casein certification investments to defend margin positions against Israeli precision fermentation substitutes. For New Entrants and Emerging Players: Lead with direct-to-athlete subscription channels in North Rhine-Westphalia's underpenetrated Cologne-Düsseldorf manufacturing cluster. Target bakery and beverage fortification applications where localized ultrafiltration capacity gaps create procurement inefficiencies for industrial food producers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because membrane filtration engineering talent scarcity and EFSA approval timeline barriers protect incumbent returns. Monitor Dutch and Israeli alternative protein technology maturation as the critical inflection signal for traditional whey protein demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Cross-flow microfiltration deployment from Baden-Württemberg engineering suppliers compresses toll-dependent processor margins. |
| Direct-to-Athlete Channel Launch | Subscription models bypass Frankfurt and Hamburg distributors to capture premium isolate-grade procurement relationships. |
| EFSA Novel Food Certification Investment | Eighteen to twenty-four month approval timelines for protein hydrolysates protect pharmaceutical-grade casein positioning. |
| Blockchain Traceability Platform Integration | Farm-origin verification aligns with CSRD-mandated sustainability disclosures for premium sports nutrition contracts. |
| Backward Integration into Whey Supply | Captive fractionation capacity in Lower Saxony and Bavaria insulates against raw milk cooperative concentration risks. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Dairy processing executives, sports nutrition procurement leads, EFSA regulatory affairs specialists, and membrane filtration engineering directors provided operational data. Secondary sources include BMEL enforcement records, EU REACH chemical safety assessments, EFSA novel food approval databases, and Dutch dairy cooperative export statistics. Bottom-up volume modeling triangulates against top-down expenditure estimates across the projection horizon.
Sensitivity analysis on natural gas price volatility and alternative protein technology adoption rates shapes the forecast framework. Segmentation dimensions span product chemistry tiers, end-use applications, delivery formats, and federal state production clusters. CAGRs derive from iterative modeling of isolate-grade demand acceleration and casein medical nutrition defensibility. Industry-specific inputs incorporate EU Green Deal methane reduction compliance costs and ceramic membrane filtration yield improvements.
Forecasts assume regulatory continuity in EU REACH, EFSA novel food, and BMEL dairy labeling regimes; material policy shifts would require re-modeling. Precision fermentation cost parity timelines and Bavarian environmental agency emission enforcement intensity represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Yogurt Powder Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Butter Concentrate Market
Dairy Products
Recombined Milk Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Halal Cheese Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Organic Milk Powder Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Dairy Blends Market
Dairy Products
Flavoured Milk Market