
 Recombined Milk Products Market | 2026-2036
Recombined Milk Products Market Size, Share, and Industry Trends Forecast 2026-2036
Recombined Milk Products Market Analytics
Southeast Asia is rewriting regional supply dynamics through new recombined milk processing installations in Vietnam and Thailand. Fonterra leverages its New Zealand milk powder supply base to anchor ingredient flows into these facilities. Nestlé sustains competitive density through backward integration into dairy powder sourcing across multiple origins. Lactalis dominates European recombined cheese and milk formulations through controlled channel access in retail and food service.
Recombined milk products are manufactured by reconstituting milk powders—typically skim milk powder and anhydrous milk fat—with water to achieve standardized fat and solids-not-fat content, then subjecting the mixture to homogenization and heat treatment to match fresh milk functionality. The primary commercial purpose is to deliver consistent, cost-stable dairy nutrition in regions with limited fresh milk availability or seasonal supply gaps. Powdered milk formulations occupy the largest volume share within the product type dimension, driven by extended shelf stability and lower logistics costs in tropical climates. UHT liquid recombined milk represents the fastest-expanding segment, as food service chains and beverage companies in climate-stressed markets prioritize ambient distribution. Infant nutrition applications command premium positioning due to stringent compositional standards and formulation complexity.
FSSAI in India mandates specific fat and solids-not-fat thresholds for recombined milk sold domestically, directly shaping product standardization investments by manufacturers targeting this market. Codex Alimentarius guidelines, referenced by WHO member states, establish international benchmarks for recombined dairy identity that facilitate or constrain cross-border trade flows. The EU F-Gas Regulation and REACH chemical safety protocols influence processing equipment selection and packaging material compliance for recombined milk operations serving European destinations. Stakeholders must monitor evolving national fortification mandates and powder origin traceability requirements as these criteria increasingly determine market access eligibility across major dairy-importing jurisdictions.
Market Dynamics
EU F-Gas Regulation phase-down protocols are forcing cold-chain operators across Europe toward ambient-stable UHT formats, fundamentally altering processing equipment procurement and packaging material specifications for recombined milk operations.
Growth Catalysts
- Indonesia's import substitution mandate:Local dairy processors are scaling recombined milk output to reduce dependency on foreign fresh milk supplies, creating captive demand for milk powder ingredients.
- REACH chemical safety protocols:European processors investing in compliant packaging materials are unlocking premium channel access for recombined cheese and milk formulations.
- Tea and coffee food service expansion:Southeast Asian beverage chains are standardizing recombined milk procurement for consistency across tropical climates with limited cold-chain reach.
Market Restraints
- Skim milk powder price volatility:Global dairy commodity swings compress margin predictability for recombined milk processors locked into annual supply contracts.
- New Zealand supply concentration:Fonterra's dominance in milk powder sourcing creates single-origin vulnerability for Southeast Asian recombination facilities.
- Anhydrous milk fat technical limitations:Reconstitution challenges in achieving precise fat globule distribution limit finished product mouthfeel equivalence to fresh milk.
Strategic Opportunities
- Vietnam processing capacity gaps:New recombination installations offer first-mover positioning in a market transitioning from direct powder consumption to value-added liquid formats.
- FSSAI fortification mandates:India's micronutrient enrichment requirements for recombined milk create formulation service opportunities for ingredient technology providers.
- Direct-to-ho.re.ca. channel convergence:Digital procurement platforms are bypassing traditional dairy distributors to connect recombined milk processors with restaurant and café chains.
Industry Challenges
- Homogenization engineering talent scarcity:Specialized technicians capable of optimizing high-pressure systems for recombined milk texture remain concentrated in European and Oceania dairy hubs.
- Infant nutrition certification timelines:Codex Alimentarius compliance documentation for recombined-based formula products extends product development cycles by 18-24 months.
- Legacy cold-chain asset stranding:Southeast Asian distributors face write-down pressure as ambient UHT formats displace refrigerated recombined milk distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombined Milk Products Market |
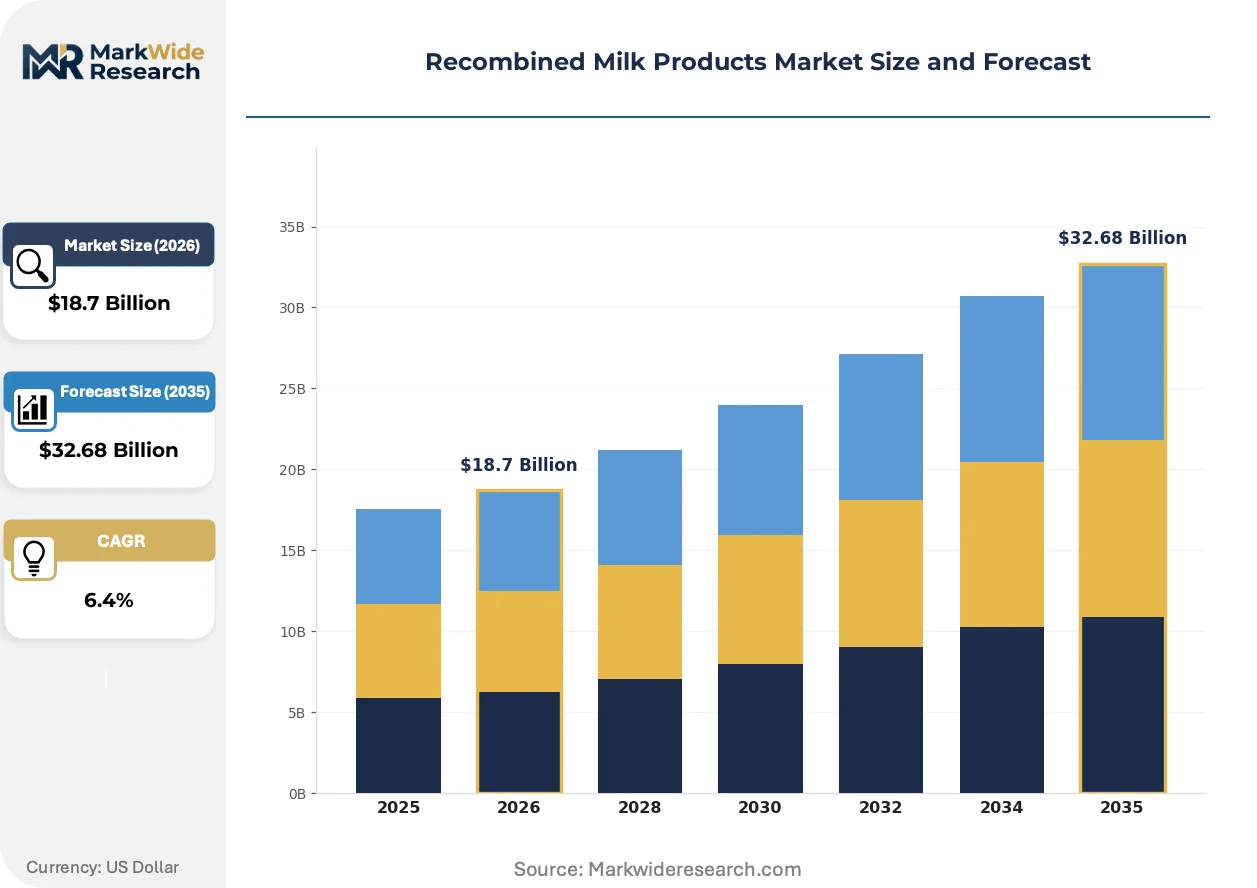
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Milk, Liquid Milk, UHT Milk, Condensed Milk End User: Households, Food Service, Dairy Manufacturers, Beverage Companies Form: Liquid, Powder, Concentrate, Frozen Application: Infant Nutrition, Bakery Products, Dairy Alternatives, Processed Foods |
| Companies Covered | Nestlé, Lactalis, Fonterra, Arla Foods, Dairy Farmers of America, Saputo, FrieslandCampina, Yili Group, Mengniu Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombined Milk Products Market Evolving Landscape
Processing technology and regulatory chemistry are converging to reshape how recombined milk achieves functional parity with fresh dairy, with implications for equipment selection and geographic production placement.
Membrane filtration technology is migrating from whey protein concentration into recombined milk standardization, enabling processors to modulate protein ratios beyond powder reconstitution limits. Mid-scale dairy operations in Thailand and Vietnam are piloting ceramic membrane systems to reduce reliance on imported protein-adjusted powders. This shift is compressing the premium gap between recombined and fresh milk in food service applications.
EU F-Gas Regulation hydrofluorocarbon phase-down schedules are accelerating adoption of transcritical CO2 refrigeration in recombined milk cold storage and transport. Equipment manufacturers serving European dairy processors must now certify compatibility with low-global-warming-potential refrigerants. UHT recombined milk formats are capturing displaced refrigerated volume as distributors confront retrofit costs.
Food service chains are consolidating supplier relationships around single-source recombined milk contracts with embedded quality auditing. Large-format coffee and tea operators in Indonesia and Malaysia are displacing fragmented local dairy procurement with centralized powder-to-liquid recombination agreements. This concentration is visible in Jakarta and Bangkok metropolitan beverage markets where chain penetration exceeds independent outlet growth.
Recombined Milk Products Market Segmentation
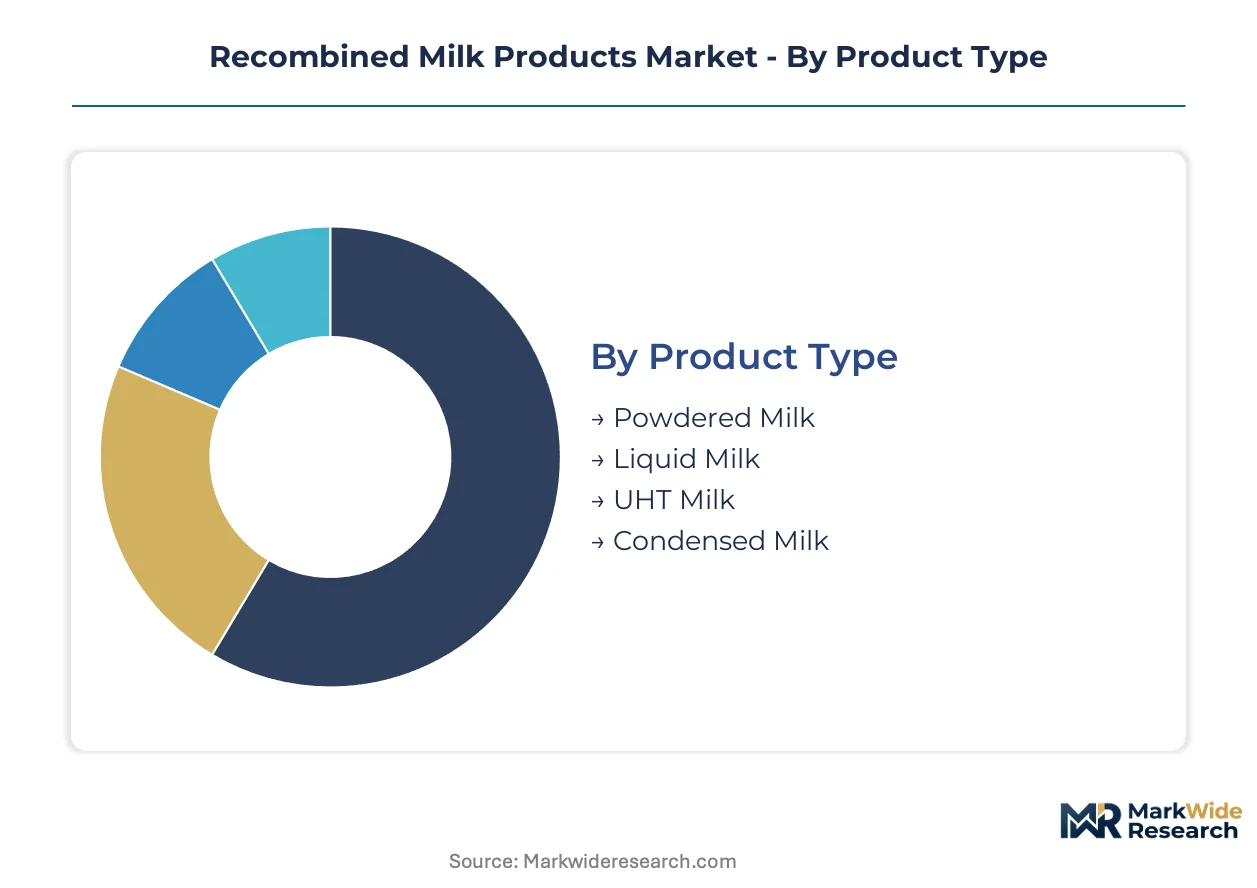
Recombined milk processors configure production lines around distinct product specifications, each demanding specialized homogenization parameters and heat treatment protocols. Segmentation clarity enables equipment vendors and ingredient suppliers to align technical capabilities with end-use performance requirements across tropical and temperate distribution environments.
Product Type:
After-sales service intensity varies sharply across product type categories, with UHT liquid formats requiring continuous technical support for aseptic packaging systems versus powder operations with simpler maintenance cycles.
- Powdered Milk:Extended shelf stability and reduced logistics costs dominate procurement decisions in tropical climates with limited cold-chain infrastructure. Demand concentrates in Indonesia and Vietnam, where local recombination facilities source bulk skim milk powder to displace direct consumer powder sales.
- UHT Milk:Ambient distribution compatibility addresses EU F-Gas Regulation pressures on refrigerated transport, with food service chains in Southeast Asia standardizing procurement for tea and coffee applications. This format is climbing the fastest as distributors confront cold-chain retrofit costs.
- Liquid Milk:Refrigerated recombined liquid serves fresh milk substitution in urban retail channels, though volume is plateauing amid ambient format displacement.
- Condensed Milk:Sugar-stabilized concentrates retain niche positioning in bakery and confectionery manufacturing, particularly among ASEAN processors.
By volume, Powdered Milk leads. By growth pace, UHT Milk is ahead.
End User:
Margin structures diverge across end user categories, with food service contracts commanding premium pricing for consistency guarantees versus household segments competing on unit economics.
- Food Service:Chain beverage operators in Jakarta and Bangkok metropolitan areas consolidate procurement around single-source recombined milk agreements with embedded quality auditing. Tea and coffee standardization drives volume concentration.
- Beverage Companies:Ready-to-drink dairy beverage manufacturers in Vietnam and Thailand anchor recombined milk demand for flavored milk and probiotic drinks, with membrane filtration technology enabling protein ratio modulation.
- Households:Retail recombined milk consumption persists in price-sensitive segments, though growth is moderating amid fresh milk availability improvements in select urban corridors.
- Dairy Manufacturers:Ingredient sourcing for processed cheese and yogurt production utilizes recombined milk as cost-stable base material, particularly in European operations navigating REACH packaging compliance.
Food Service captures the highest value per liter. Beverage Companies are expanding most quickly.
Form:
Supply chain configuration determines form selection, with powder dominating import-dependent markets and liquid formats requiring proximate recombination infrastructure.
- Powder:Skim milk powder and anhydrous milk fat blends enable flexible reconstitution at destination, reducing transport weight and refrigeration burden across Southeast Asian archipelago logistics.
- Liquid:Pre-recombined liquid milk serves food service and retail channels where local processing capacity exists, with UHT variants displacing refrigerated distribution.
- Concentrate:Evaporated and condensed forms retain concentrated solids for industrial bakery and confectionery applications, with lower water content reducing shipping expenditure.
- Frozen:Blast-frozen recombined cream and specialty fats serve premium ice cream and dessert manufacturers requiring precise fat globule structure control.
Powder dominates cross-border trade volumes. Liquid is gaining share fastest in domestic processing markets.
Application:
Regulatory certification intensity shapes application tiering, with infant nutrition demanding Codex Alimentarius compliance documentation extending development cycles substantially.
- Infant Nutrition:Recombined-based formula products require stringent compositional standardization and micronutrient fortification, with FSSAI mandates in India creating formulation service opportunities for technology providers.
- Bakery Products:Recombined milk solids provide consistent protein and fat functionality in industrial bread and pastry manufacturing, with condensed milk concentrates serving traditional recipe requirements.
- Processed Foods:Sauces, soups, and prepared meals incorporate recombined dairy for creaminess and nutritional labeling, particularly in European operations navigating EFSA additive restrictions.
- Dairy Alternatives:Hybrid formulations blending recombined milk with plant proteins address flexitarian positioning, though this remains experimental in mainstream recombination facilities.
Infant Nutrition commands premium positioning. Bakery Products anchor volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tanjung Priok Port expansion underwrites Indonesia's role as Southeast Asia's recombined milk processing hub, enabling bulk skim milk powder imports to feed domestic recombination facilities serving Jakarta's food service corridor.
Indonesia
Tea and coffee chain standardization drives recombined milk procurement concentration in Jakarta and Surabaya metropolitan markets. FSSAI-equivalent national standards enforced by the national food and drug agency shape local fortification requirements for domestic sales. West Java's Cikarang industrial zone hosts new recombination installations scaling output to reduce fresh milk import dependency.
Vietnam
Beverage manufacturers in Ho Chi Minh City anchor demand for UHT recombined milk in ready-to-drink dairy applications. The country's national standards body mandates specific protein thresholds for recombined liquid milk sold through modern trade channels. Dong Nai province's processing corridor attracts investment in membrane filtration-equipped recombination facilities serving southern Vietnam.
Thailand
Food service operators in Bangkok standardize recombined milk procurement for tropical climate distribution without cold-chain dependency. REACH-aligned chemical safety protocols influence packaging material selection for European-bound condensed milk exports. Pathum Thani's dairy processing cluster concentrates recombination capacity serving Greater Bangkok's retail and food service channels.
India
FSSAI fortification mandates for vitamin A and D in recombined milk create formulation complexity for processors targeting domestic retail. The national dairy development board's cooperative procurement networks channel skim milk powder into regional recombination plants. Gujarat's Anand district and Karnataka's Bangalore rural district concentrate cooperative-owned recombination capacity serving western and southern markets.
Germany
EU F-Gas Regulation phase-down protocols force cold-chain operators toward ambient UHT recombined milk formats, altering equipment procurement specifications. ECHA REACH compliance requirements govern packaging material selection for recombined cheese formulations. Bavaria's dairy processing belt maintains recombination facilities serving central European retail and food service distribution.
Recombined Milk Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in powder sourcing and processing technology supply. The market structures around three tiers: multinational dairy conglomerates with backward integration into milk powder origins, regional recombination specialists with captive food service contracts, and equipment-technology providers enabling membrane filtration and aseptic packaging upgrades. Consolidation pressure concentrates among powder-origin suppliers, while recombination processing remains fragmented across Southeast Asian markets. Dominant competitive moves include strategic partnerships between New Zealand-origin suppliers and Southeast Asian processors, plus capacity expansion in Vietnam and Indonesia to capture import-substitution demand.
Among Oceania-origin powder suppliers, Fonterra anchors ingredient flows into Southeast Asian recombination facilities. Nestlé occupies a position exemplifying multinational backward integration into multi-origin dairy powder sourcing. Lactalis represents the European archetype dominating recombined cheese and milk formulations through controlled retail and food service channel access.
| Leading Market Players |
|---|
| Nestlé |
| Lactalis |
| Fonterra |
| Arla Foods |
| Dairy Farmers of America |
| Saputo |
| FrieslandCampina |
| Yili Group |
| Mengniu Dairy |
| Others |
Value Network & Pricing Analysis
New Zealand's milk powder export concentration anchors ingredient cost structures for Southeast Asian recombination facilities, translating Fonterra's auction price movements directly into margin compression or expansion for downstream processors in Indonesia and Vietnam.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure for recombined milk products serving European destinations, with REACH-compliant packaging materials commanding premium positioning against standard-tier formulations. Three-tier pricing structure across premium, standard, and economy levels separates infant nutrition certification grades from food service bulk contracts and retail private-label offerings. Pricing pressure stems from skim milk powder commodity volatility, with annual contract lock-ins exposing processors to margin squeeze when auction prices spike. Food service chains exhibit lowest price sensitivity due to consistency requirements, while household retail segments compete aggressively on unit economics.
Supply Chain Analysis
Skim milk powder feedstock draws from New Zealand, the European Union, and the United States as the three dominant origins for Southeast Asian recombination facilities. Anhydrous milk fat and protein-adjusted powders constitute critical secondary inputs, with membrane filtration technology reducing dependence on pre-standardized blends. Single-source vulnerability concentrates in Fonterra's auction platform dominance, creating disruption risk from weather events or policy shifts in Oceania. Distribution runs through bulk port terminals at Tanjung Priok and Cai Mep for powder imports, with finished liquid formats deploying ambient UHT logistics to bypass cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based dairy alternatives threaten recombined milk's cost-advantage positioning in Southeast Asian food service, forcing incumbents to defend through functional parity investments and supply security guarantees.
For Market Incumbents: Build captive supply moats through backward integration into milk powder sourcing across multiple origins to dilute New Zealand concentration risk. Anchor food service contracts with embedded quality auditing and technical service bundling that oat and almond milk suppliers cannot replicate. Prioritize membrane filtration capability acquisition to compress the premium gap versus fresh milk in tea and coffee applications.
For New Entrants and Emerging Players: Vietnam's southern processing corridor offers underpenetrated white-space for UHT recombined milk serving ready-to-drink beverage manufacturers. Target India's FSSAI fortification compliance services as a formulation technology entry point before scaling to full recombination capacity. Deploy direct-to-ho.re.ca. digital procurement platforms to bypass legacy dairy distributor networks concentrated in Jakarta and Bangkok.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Southeast Asian recombination specialists holding captive food service contracts but lacking powder-origin backward integration. Five-to-ten year viability hinges on successful ambient format transition and import substitution policy tailwinds in Indonesia and Vietnam. Watch Fonterra auction price volatility as the inflection signal for margin compression cycles affecting processor valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Sourcing | Multi-origin supply bases reduce Fonterra auction exposure for Southeast Asian processors. |
| Membrane Filtration Technology Deployment | Ceramic systems enable protein ratio modulation beyond powder reconstitution limits in Thai facilities. |
| UHT Format Capacity Expansion | Ambient distribution compatibility addresses EU F-Gas Regulation phase-down pressures on refrigerated logistics. |
| FSSAI Fortification Compliance Services | Micronutrient enrichment capabilities unlock premium channel access in India's regulated retail environment. |
| Direct-to-Ho.Re.Ca. Platform Launch | Digital procurement bypasses fragmented distributor networks serving Jakarta and Bangkok metropolitan chains. |
Research Methodology
A standing panel of recombination plant managers, dairy powder procurement leads, food service chain beverage directors, and membrane filtration equipment engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against Fonterra GlobalDairyTrade auction data, ASEAN customs import records, FSSAI regulatory filings, and EU REACH compliance databases. Bottom-up volume modeling from individual facility capacities triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting powder price volatility bands and regulatory implementation timelines. Segmentation dimensions modeled include product type, end user category, form factor, and application tier, with geographic production clusters and fortification mandate compliance status as industry-specific overlays. CAGRs derived from fitted growth curves applied to normalized base-year volumes, with infant nutrition certification timelines and cold-chain retrofit cost curves as specific forecast inputs.
Practitioners should monitor Fonterra auction price spikes, EU F-Gas Regulation enforcement acceleration, and Indonesia import substitution policy shifts for early signals of forecast revision. Cross-checking against dairy commodity futures curves and ASEAN dairy trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Fluid Milk Market
Dairy Products
Germany Milk Protein Market
Dairy Products
United States Casein Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Butter Powder Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Halal Cheese Market
Dairy Products
Green Tea Butter Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Dairy Based Dressings Market