
 Milk Alternatives Market | 2026-2036
Milk Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Alternatives Market Intelligence
A capital-intensity divergence between multinational beverage conglomerates and specialist oat or almond pure-plays is bifurcating competitive dynamics. Danone S.A. leverages its dairy-rooted cold-chain infrastructure to sustain refrigerated distribution dominance. Oatly Group AB anchors brand identity in barista-grade foaming performance. Blue Diamond Growers competes through captive almond supply across California's Central Valley.
Milk alternatives comprise plant-derived liquid or powdered extracts formulated to mimic the functional properties of bovine milk, typically achieving protein content between one and eight grams per serving through enzymatic processing of oats, almonds, or soybeans. These products serve commercial and retail channels requiring emulsion stability, neutral flavor profiles, and foamability for beverage applications. Oat milk leads volume momentum in beverages and coffee creamer applications where its lipid profile enables microfoam formation without allergen labeling burdens. Almond milk occupies mature retail shelf positioning in North American supermarkets though margin compression intensifies as private-label entrants multiply. Soy milk dominates infant nutrition formulations where its complete amino acid profile meets pediatric dietary standards.
FDA nutrition labeling requirements and USDA organic certification standards govern product claims and ingredient disclosure in the United States, while EU Green Deal farm-to-fork targets pressure suppliers to document carbon intensity across oat and almond sourcing. EFSA novel food assessments create entry barriers for emerging protein bases such as hemp or fermented formulations. Stakeholders must monitor evolving allergen threshold regulations and carbon border adjustment mechanisms that will reshape sourcing geography and formulation economics.
Market Dynamics
EU Green Deal farm-to-fork carbon accounting mandates are forcing reformulation investments across oat and almond supply chains, while coffee chain procurement consolidation reshapes volume allocation between refrigerated and shelf-stable formats.
Growth Catalysts
- Barista-grade foaming specifications:Coffee chains now require microfoam stability above 60°C, pulling enzymatically processed oat lipids into formulation pipelines.
- FDA nutrition labeling modernization:Updated serving-size definitions for plant-based beverages clarify protein disclosure standards, reducing consumer confusion at point-of-sale.
- German retail shelf expansion:Discounters and full-range grocers in Germany have allocated 40% more linear meters to plant-based beverages since EU Green Deal announcement.
Market Restraints
- Almond water intensity:California Central Valley drought cycles expose processors to input cost volatility exceeding 30% season-to-season.
- EFSA novel food assessment timelines:Hemp protein and fermented bases face 18-24 month approval delays, freezing pipeline diversification.
- Soy allergen labeling thresholds:Pending EU threshold reductions would trigger reformulation costs across infant nutrition formulations.
Strategic Opportunities
- Carbon border adjustment preparation:EU importers documenting upstream oat emissions gain first-mover advantage against 2026 compliance deadlines.
- Direct-to-foodservice distribution:Bypassing retail slotting fees, specialist oat processors are building captive supply relationships with independent coffee roasters.
- Pediatric amino acid fortification:Soy's complete protein profile positions it for expansion into clinical nutrition beyond infant formula.
Industry Challenges
- Enzymatic process engineering talent:Lipid hydrolysis optimization for foam stability requires scarce food biochemists, compressing R&D throughput at mid-scale processors.
- Cold-chain retrofitting capex:Refrigerated distribution expansion demands fleet and warehouse investments that strain balance sheets below $500M revenue.
- Organic certification timeline compression:USDA three-year transition windows for oat sourcing conflict with quarterly procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Alternatives Market |
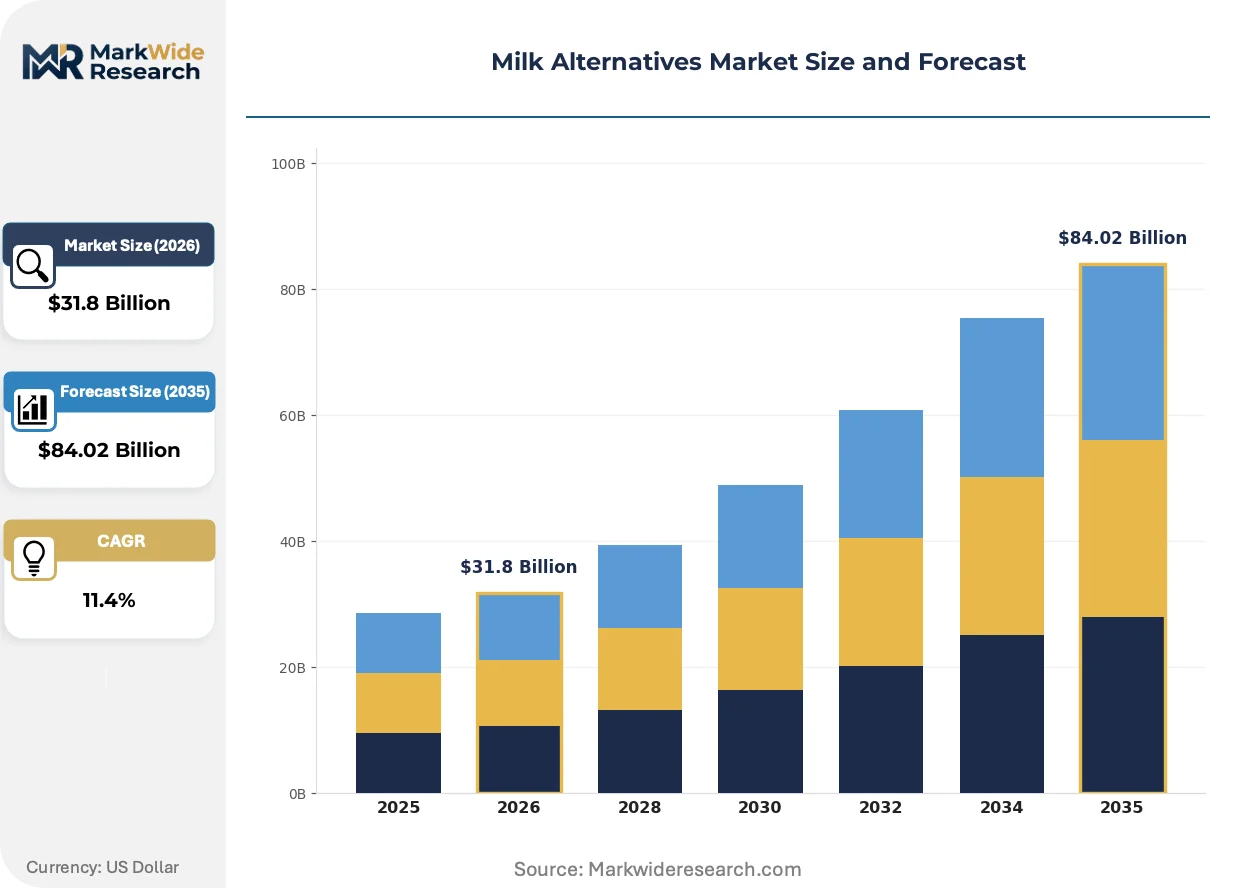
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $84.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
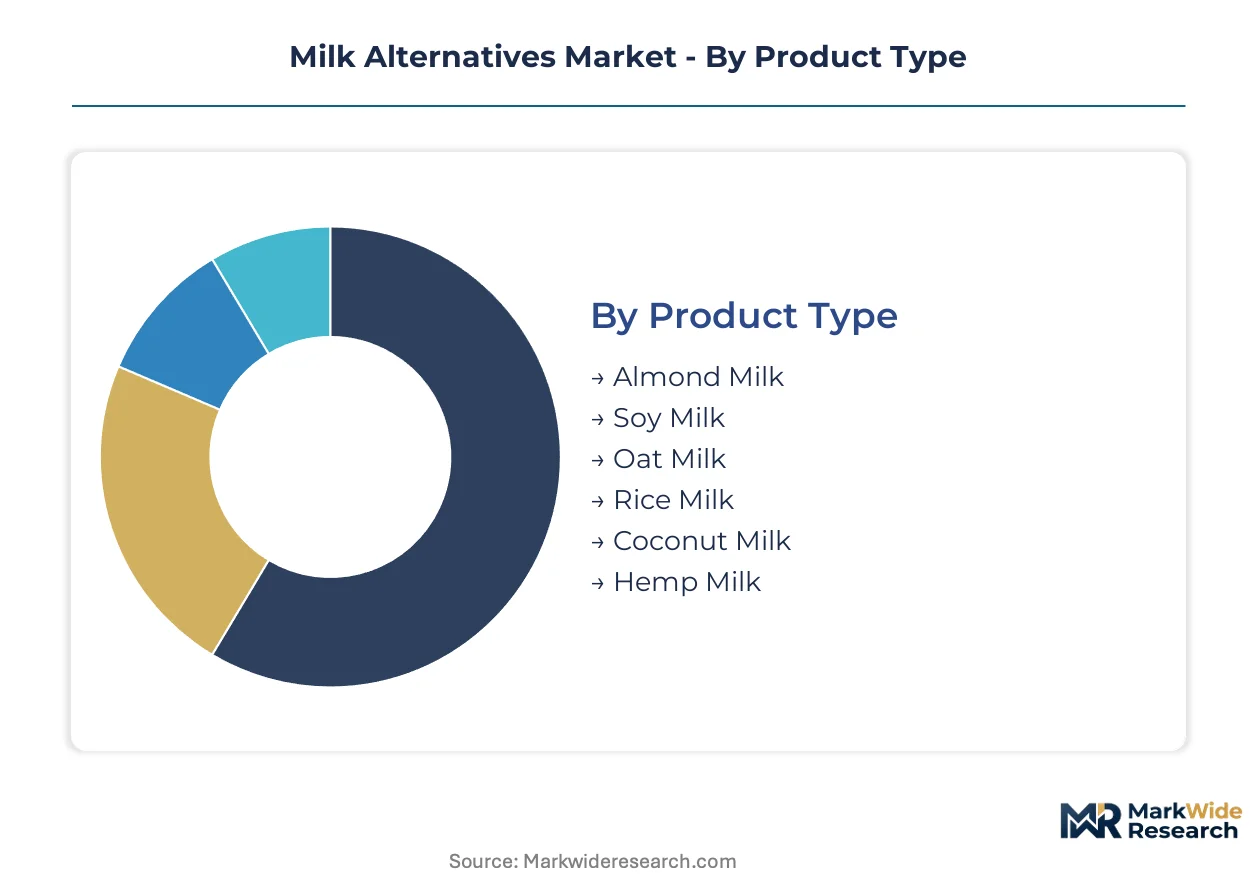
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Rice Milk, Coconut Milk, Hemp Milk Form: Liquid, Powder, Concentrate, Cultured, Flavored Application: Beverages, Baking, Cooking, Infant Nutrition, Coffee Creamer End User: Foodservice Providers, Retail Consumers, Health Food Stores, Specialty Retailers |
| Companies Covered | Unilever PLC, Califia Farms, Danone S.A., Vitasoy International Holdings, The Hain Celestial Group Inc., Oatly Group AB, Nestlé S.A., SunOpta Inc., Blue Diamond Growers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Alternatives Market Strategic Shifts & Innovations
Enzymatic lipid modification and precision fermentation are splitting the market between commodity-grade processors and functional-performance specialists, with regulatory carbon accounting layering compliance complexity onto technical differentiation.
Fermented protein bases utilizing precision fermentation technology are bifurcating competitive positioning between legacy extrusion processors and biotech-integrated startups. Specialty coffee chains and premium creamer manufacturers are adopting these bases for neutral flavor profiles and reduced allergen risk. The technology is bifurcating R&D investment allocation, compressing margins at conventional oat processors while enabling premium pricing at fermentation-capable facilities.
EU Green Deal carbon intensity disclosure requirements are mandating farm-level emissions tracking across oat and almond sourcing geographies. Processors must now document nitrogen fertilizer application rates and irrigation energy inputs to maintain retail access. German and Dutch retail buyers are enforcing these standards earliest, excluding non-compliant suppliers from private-label bidding.
Foodservice procurement consolidation is compressing supplier rosters as coffee chains centralize oat milk purchasing through dedicated procurement teams. Independent roasters and regional café groups are losing direct supplier relationships, replaced by national distribution agreements with beverage conglomerates. This pattern concentrates most visibly in United States metropolitan markets where chain penetration exceeds 60% of coffee occasions.
Milk Alternatives Market Segmentation
Segmentation in milk alternatives reveals how formulation specifications, distribution channels, and end-use requirements fragment procurement patterns. Coffee chains, infant nutrition manufacturers, and retail grocers each impose distinct technical demands that reshape supplier economics and R&D allocation.
Product Type:
Channel flows diverge sharply by base ingredient: oat milk dominates foodservice procurement through coffee chain contracts, while almond and soy milk split between retail shelf placement and specialized nutrition applications.
- Oat Milk:Enzymatic lipid processing delivers barista-grade microfoam stability above 60°C, the specification now mandatory in coffee chain tenders. German discounters and United States metropolitan café groups anchor volume procurement, with EU Green Deal carbon accounting forcing farm-level emissions documentation.
- Almond Milk:California Central Valley captive supply chains sustain North American retail dominance, though drought-induced input volatility compresses margins seasonally. Private-label entrants multiply in United States supermarkets, eroding branded shelf positioning.
- Soy Milk:Complete amino acid profile meets pediatric dietary standards for infant nutrition formulations. FDA nutrition labeling requirements govern protein disclosure standards.
- Rice Milk:Hypoallergenic positioning serves restricted-diet consumers in European retail channels.
- Coconut Milk:Tropical sourcing geography limits carbon accounting transparency under EU Green Deal thresholds.
- Hemp Milk:EFSA novel food assessment timelines freeze pipeline commercialization across European markets.
By volume, almond milk leads. By growth pace, oat milk is ahead.
Form:
Cost tier stratification separates premium refrigerated formats from economy shelf-stable and powder concentrates, with margin structures dictating which processors invest in cold-chain infrastructure.
- Liquid:Refrigerated distribution demands fleet and warehouse investments that strain balance sheets below $500M revenue. Coffee chains in United States metropolitan markets specify chilled delivery for foam performance.
- Powder:Extended shelf life enables export economics for processors lacking cold-chain coverage. Infant nutrition manufacturers in Germany source bulk powder for amino acid fortification pipelines.
- Concentrate:Reduced shipping volumes attract foodservice distributors managing logistics costs.
- Cultured:Precision fermentation technology enables premium pricing at biotech-integrated facilities.
- Flavored:Vanilla and chocolate variants occupy impulse-purchase positioning in retail checkout zones.
Refrigerated liquid commands the highest unit margins. Powder concentrates are climbing the fastest as export demand accelerates.
Application:
Volume concentration varies by performance specification: foam stability requirements in beverages pull enzymatically processed oat lipids, while amino acid completeness in infant nutrition locks in soy procurement.
- Beverages:Direct consumption formats require neutral flavor profiles and emulsion stability. German retail buyers enforce EU Green Deal carbon intensity disclosure across oat sourcing.
- Coffee Creamer:Microfoam specifications above 60°C dominate chain procurement tenders. United States metropolitan café penetration exceeds 60% of coffee occasions.
- Infant Nutrition:Soy's complete protein profile meets pediatric dietary standards. Pending EU allergen threshold reductions threaten reformulation costs.
- Baking:Functional properties focus on moisture retention and fat replacement.
- Cooking:Heat stability requirements vary by regional cuisine applications.
Coffee creamer applications show the steepest expansion trajectory. Beverages retain the largest volume base.
End User:
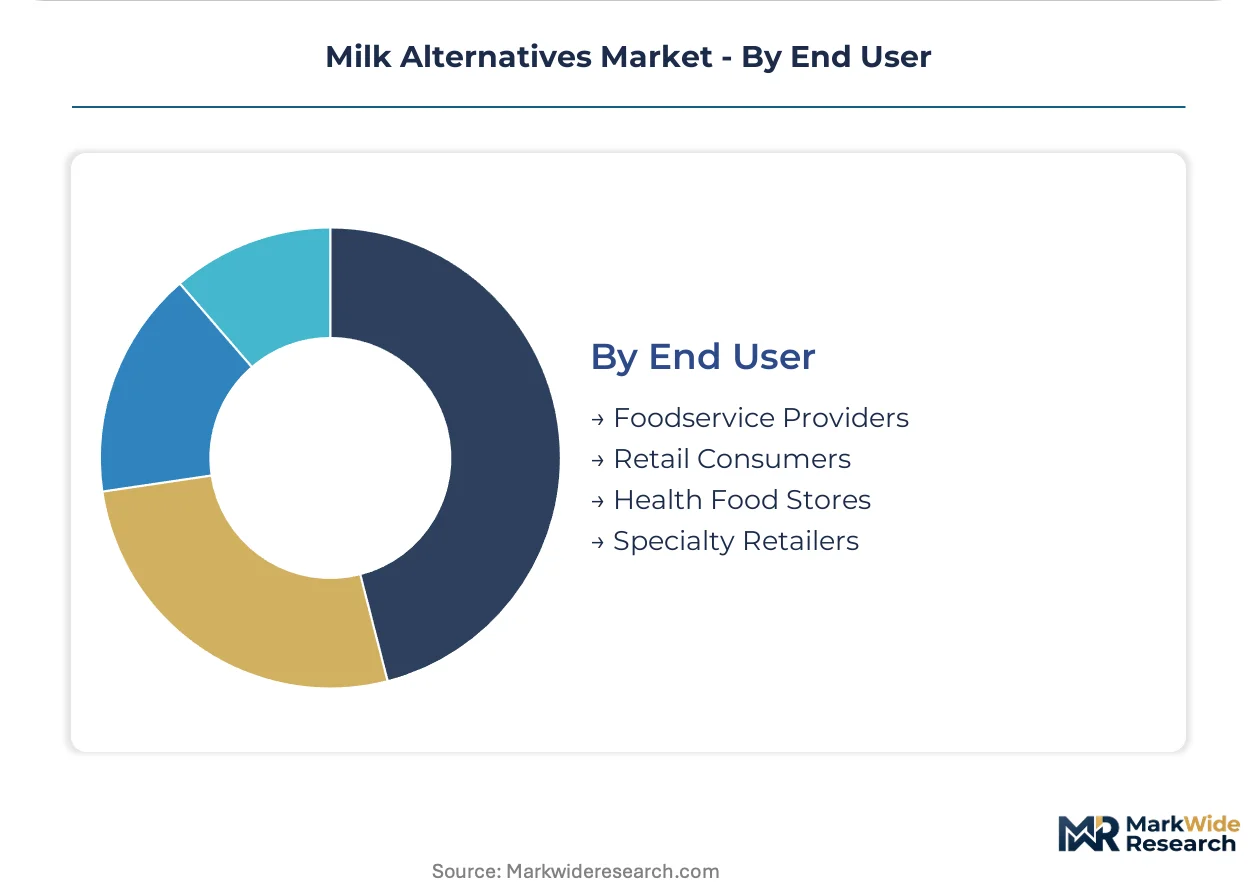
Customer type determines contract structure: foodservice procurement consolidation compresses supplier rosters, while retail consumers fragment across discounters, specialty channels, and health food stores with divergent certification demands.
- Foodservice Providers:Coffee chains centralize oat milk purchasing through dedicated procurement teams, replacing independent roaster relationships with national distribution agreements. United States chain penetration reshapes volume allocation.
- Retail Consumers:Supermarket shelf space expansion in Germany allocates 40% more linear meters to plant-based beverages since EU Green Deal announcement.
- Health Food Stores:USDA organic certification standards govern product claims and ingredient disclosure.
- Specialty Retailers:Premium positioning supports fermented protein bases and precision fermentation technology adoption.
Foodservice channels concentrate procurement fastest. Retail consumer volumes remain largest in absolute terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in the United States by roughly 20% due to stricter EU Green Deal compliance requirements and concentrated retail buyer consolidation. This asymmetry reshapes investment allocation across oat and almond supply chains.
United States
Metropolitan café penetration exceeding 60% of coffee occasions pulls enzymatically processed oat lipids into formulation pipelines. FDA nutrition labeling modernization clarifies protein disclosure standards for plant-based beverages. California's Central Valley anchors captive almond supply chains though drought cycles induce 30% season-to-season input cost volatility.
Germany
Discounters and full-range grocers have allocated 40% more linear meters to plant-based beverages since the EU Green Deal announcement. EFSA novel food assessments create entry barriers for emerging protein bases such as hemp or fermented formulations. Berlin and Hamburg concentrate foodservice procurement consolidation as coffee chains centralize oat milk purchasing through dedicated teams.
United Kingdom
Specialty coffee chains and premium creamer manufacturers drive demand for barista-grade microfoam stability above 60°C. UK organic certification standards govern product claims alongside EU farm-to-fork carbon accounting mandates. London anchors the steepest retail shelf expansion for refrigerated liquid formats.
China
Soy milk dominates infant nutrition formulations where complete amino acid profiles meet pediatric dietary standards. SAMR and GB standards govern food safety and ingredient disclosure for plant-derived beverages. Yangtze River Delta processing clusters concentrate precision fermentation technology adoption for neutral flavor profiles.
Australia
Export economics for powder concentrates attract processors lacking cold-chain coverage across Asia-Pacific markets. TGA and FSANZ regulations align with evolving allergen threshold standards. Sydney and Melbourne concentrate health food store distribution for USDA organic-certified oat and almond products.
Milk Alternatives Market Key Industry Players
Concentration sits with multinational beverage conglomerates leveraging dairy-rooted cold-chain infrastructure against specialist oat or almond pure-plays competing on enzymatic process engineering. The vendor base splits between refrigerated distribution dominators and barista-grade functional-performance specialists. Strategic archetypes include scale-driven conglomerates, captive-supply almond processors, and fermentation-capable biotech integrators. Dominant competitive moves span M&A for cold-chain assets and strategic partnerships bypassing retail slotting fees through direct-to-foodservice distribution.
Within the scale-driven tier, Danone S.A. and Nestlé S.A. exemplify multinational beverage conglomerates with dairy-rooted infrastructure. Oatly Group AB anchors the specialist oat pure-play archetype. Blue Diamond Growers represents captive-supply almond processors with California Central Valley sourcing concentration. These three occupy positions across the competitive spectrum without overlapping strategic territory.
| Leading Market Players |
|---|
| Unilever PLC |
| Califia Farms |
| Danone S.A. |
| Vitasoy International Holdings |
| The Hain Celestial Group Inc. |
| Oatly Group AB |
| Nestlé S.A. |
| SunOpta Inc. |
| Blue Diamond Growers |
| Others |
Cost & Logistics Intelligence
EU Green Deal farm-to-fork carbon accounting mandates gate both supplier qualification and price differentiation simultaneously, forcing processors to document upstream emissions before retail buyers grant shelf access or premium positioning. This regulatory filter compresses margins at non-compliant suppliers while rewarding documented low-carbon oat and almond sourcing with 20% pricing power advantages in German retail channels.
Pricing Analysis
The customization-premium spread separates enzymatically processed barista-grade oat formulations from commodity shelf-stable alternatives, with coffee chain procurement tenders commanding price multiples for microfoam stability above 60°C. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—USDA organic and EU carbon-labeled products anchor the top tier—while private-label entrants drive cost compression in North American almond milk retail. Pricing pressure stems from drought-induced input volatility in California's Central Valley, where season-to-season almond cost swings exceed 30%. Discounter retail consumers in Germany exhibit highest price sensitivity; foodservice procurement teams at coffee chains show lowest sensitivity, prioritizing functional performance over unit cost.
Supply Chain Analysis
Inventory lead times for enzymatically processed oat lipids stretch 8-12 weeks due to specialized fermentation equipment constraints, while shelf-stable almond milk maintains 2-3 week turnaround from California processing. Supply concentrates in the United States, Germany, and China: California's Central Valley anchors captive almond supply, German discounters drive oat procurement consolidation, and Yangtze River Delta clusters host precision fermentation capacity. Raw material dependencies include nitrogen fertilizer for oat cultivation, irrigation energy for almond orchards, and food-grade enzymes for lipid hydrolysis. Single-source vulnerability concentrates in California almond supply chains exposed to drought cycles. Distribution runs through refrigerated fleets for barista-grade formats and ambient logistics for powder concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Milk alternatives sit in early-cycle expansion as coffee chain procurement consolidation and EU carbon accounting mandates accelerate adoption beyond niche health-food positioning into mainstream beverage infrastructure.
For Market Incumbents: Compound cold-chain infrastructure advantages by retrofitting dairy-rooted refrigerated distribution networks for oat milk volume capture, while investing in enzymatic process engineering talent to defend against precision fermentation startups. Threat from biotech-integrated entrants with neutral-flavor fermented bases demands accelerated R&D in lipid hydrolysis optimization. Vertical integration into California almond supply or Scandinavian oat sourcing secures input cost stability. For New Entrants and Emerging Players: Lead with direct-to-foodservice distribution bypassing retail slotting fees, targeting independent coffee roasters and regional café groups displaced by chain procurement consolidation. White-space opportunity concentrates in pediatric amino acid fortification beyond infant formula, where soy's complete protein profile meets clinical nutrition standards. Germany offers most penetrable geography given 40% shelf space expansion and early EU Green Deal enforcement. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward processors with documented upstream emissions tracking. Five-to-ten year viability favors fermentation-capable facilities and captive-supply almond processors over commodity extrusion players. Signal to watch: EFSA novel food assessment timeline compression for hemp protein and fermented bases as inflection indicator for pipeline diversification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Engineering Investment | Secures barista-grade microfoam specifications required by coffee chain procurement tenders. |
| Farm-Level Emissions Documentation | Enables EU Green Deal compliance and access to German retail buyer private-label bidding. |
| Direct-to-Foodservice Distribution Buildout | Bypasses retail slotting fees and captures independent roaster relationships. |
| Precision Fermentation Technology Integration | Unlocks premium pricing for neutral-flavor protein bases with reduced allergen risk. |
| Cold-Chain Infrastructure Retrofit | Extends refrigerated distribution dominance against shelf-stable commodity entrants. |
Research Approach
Operator-level perspectives from oat processing plant managers, coffee chain procurement directors, German retail category buyers, and infant nutrition formulation scientists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA nutrition labeling filings, EFSA novel food assessment registers, EU Green Deal carbon accounting documentation, and Nielsen retail audit data for plant-based beverage shelf space metrics. Bottom-up volume modeling triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across enzyme cost volatility scenarios, drought-induced almond input swings, and EU carbon border adjustment implementation timing. Segmentation dimensions modeled include base ingredient type, form factor, application specification, and end-user channel. CAGRs derived from trend extrapolation of coffee chain procurement volumes, German retail expansion trajectories, and precision fermentation capacity buildout. Industry-specific inputs incorporated enzymatic lipid hydrolysis yield rates and organic certification transition timelines.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement consistency, California water supply stability, or coffee chain procurement consolidation pace would require recalibration. Forecasts reflect documented assumptions regarding carbon accounting adoption curves and allergen threshold regulatory evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Germany Dairy Alternatives Market