
 Dairy Carton Market | 2026-2036
Dairy Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Carton Market Outlook
The gap between premium aseptic cartons and commodity gable-top formats is expanding as retailers demand longer shelf life alongside cost controls. Tetra Pak International S.A. leverages its aseptic technology leadership to command premium positioning in extended-shelf-life dairy. SIG Combibloc Group AG competes through scalable filling equipment partnerships that reduce converter capital burdens. Elopak AS specializes in renewable paperboard sourcing that aligns with retailer sustainability procurement criteria.
Dairy cartons are multi-layer liquid packaging containers, typically combining paperboard with polyethylene and aluminum barriers, engineered to protect fluid milk and cultured products from light, oxygen, and microbial contamination while enabling efficient cold-chain distribution. Aseptic cartons dominate margin pools due to their technical complexity and brand loyalty among ultra-high-temperature milk processors, while gable-top formats retain volume leadership in short-shelf-life fresh milk channels where cost sensitivity prevails. Composite materials command growing R&D attention as converters seek to eliminate aluminum layers without sacrificing barrier performance.
The EU Green Deal and F-Gas Regulation constrain hydrocarbon blowing agents in foam-based insulated distribution, while FDA food-contact substance notifications govern polyethylene and adhesive migrations in US dairy packaging. BIS certification requirements in India mandate specific paperboard grammages and seal integrity standards for ambient dairy distribution. Stakeholders must monitor evolving extended producer responsibility frameworks that will reshape material recovery economics and converter compliance investments.
Market Dynamics
EU Green Deal packaging waste directives are forcing dairy carton converters to reengineer multi-layer barrier structures while maintaining cost parity with legacy aluminum-dependent formats. This regulatory compression is reshaping material R&D priorities and supplier qualification timelines across the value chain.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany's Verpackungsgesetz mandates minimum recycled content thresholds, creating pull-through demand for fiber-based packaging with certified circularity credentials.
- Ultra-high-temperature milk processors:Aseptic filling technology adoption is accelerating in India's ambient dairy distribution networks as cold-chain infrastructure gaps persist.
- Renewable paperboard sourcing:Forest Stewardship Council chain-of-custody certification is becoming a non-negotiable procurement filter for European supermarket private-label buyers.
Market Restraints
- Aluminum layer dependency:Oxygen barrier performance requirements currently prevent full elimination of aluminum foil in extended-shelf-life formats, constraining material circularity claims.
- Polyethylene price volatility:Fossil-derived sealant layers constitute 20-30% of carton mass, exposing converters to naphtha-cracker output fluctuations without viable bio-based alternatives at scale.
- Converter concentration in Nordic regions:Liquid packaging board production clusters in Sweden and Finland create single-source vulnerability for Asian and Latin American dairy brands.
Strategic Opportunities
- Poland's organized retail expansion:Discount grocery chains are penetrating secondary cities, creating demand for cost-optimized gable-top formats with shorter supply lines from regional converters.
- Digital printing integration:Variable-data decoration enables micro-batch customization for regional dairy cooperatives, collapsing minimum order quantities that previously favored national brands.
- Bio-based barrier coatings:Polyhydroxyalkanoate and polylactic acid formulations are approaching commercial viability for oxygen-sensitive cultured products, opening patent whitespace outside incumbent polymer portfolios.
Industry Challenges
- Multi-layer delamination expertise:Separating polyethylene, aluminum, and paperboard fractions for high-purity recycling requires capital-intensive specialized equipment that most municipal waste systems lack.
- F-Gas Regulation compliance timelines:Foam-insulated distribution equipment using hydrofluorocarbon blowing agents must phase out by 2030, forcing cold-chain logistics providers into accelerated capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Carton Market |
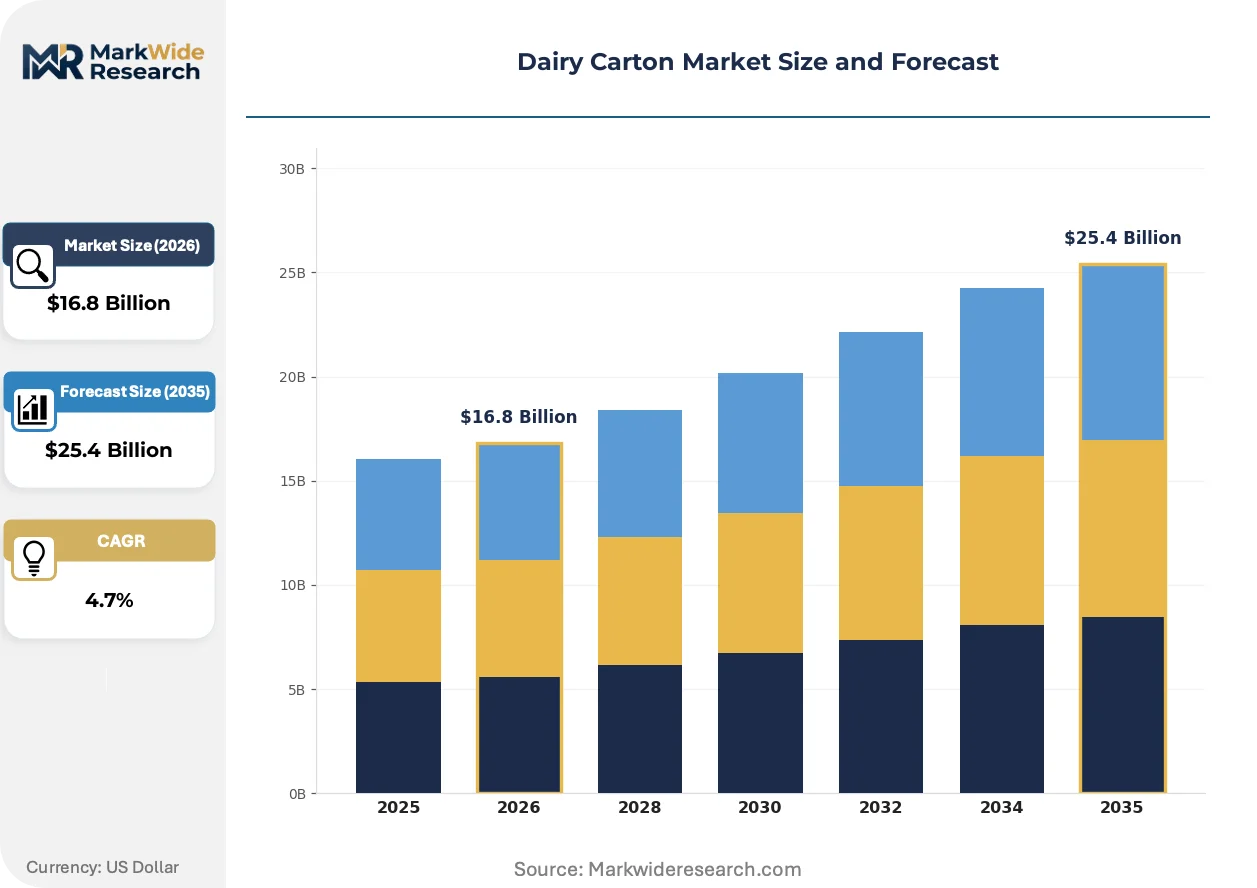
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.4 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carton, Gable-Top, Aseptic, Liquid Material: Paperboard, Plastic, Aluminum, Composite End User: Retail, Food Service, Household, Institutions Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group AG, Elopak AS, Mondi plc, Greatview Aseptic Packaging Company Limited, WestRock Company, Nippon Paper Industries Co., Ltd., Evergreen Packaging LLC, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Carton Market Strategic Shifts
Barrier material science is undergoing forced evolution as regulators and brand owners simultaneously demand aluminum elimination and shelf-life extension. Three interconnected developments are compressing traditional converter-advantage timelines.
Polymer-grade paperboard surface treatments are decentralizing oxygen barrier functionality from discrete aluminum layers into distributed coating architectures. Mid-sized dairy processors in the Netherlands and Denmark are piloting these substrates for ESL fresh milk, collapsing the technical moat that previously protected aseptic carton specialists. The shift is compressing R&D amortization periods and opening supplier qualification to non-traditional substrate converters.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from dairy lid stocks and spout assemblies. European carton converters are reformulating polyethylene extrusion layers to compensate for lost oil-repellency, extending product development cycles by 12-18 months. Organic dairy SKUs with shorter shelf-life requirements are absorbing the transition costs first, creating a two-speed compliance landscape.
Retailer sustainability scorecards are hardcoding packaging circularity into supplier retention decisions. German and French supermarket chains now weight recyclability metrics at 15-20% of total procurement scoring, displacing pure unit-cost optimization. This behavioral shift is most visible in private-label fluid milk, where brands without fiber-certification face delisting risk regardless of price competitiveness.
Dairy Carton Market Segmentation
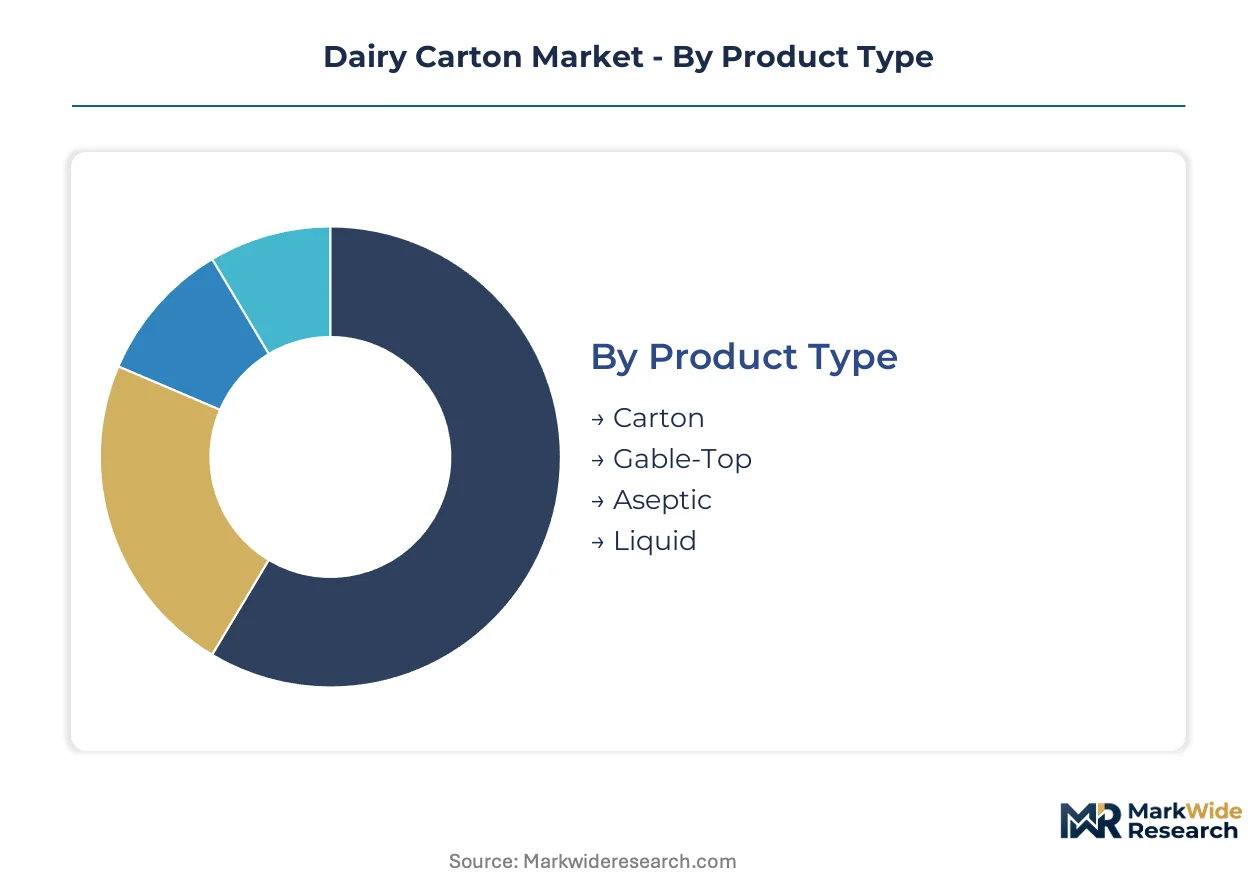
Dairy carton segmentation reveals how shelf-life requirements, barrier performance needs, and retail channel specifications fragment converter capabilities across incompatible technical specifications. Each dimension creates distinct procurement filters that reshape supplier qualification and R&D investment priorities.
Product Type:
Buyers differentiate primarily by shelf-life extension needs versus cold-chain infrastructure maturity in their target markets.
- Aseptic:Multi-layer laminated structures with aluminum oxygen barriers enable ambient distribution without refrigeration. Demand concentrates among ultra-high-temperature milk processors in India where cold-chain gaps persist, driven by Tetra Pak's filling equipment lock-in and SIG Combibloc's scalable partnership models.
- Gable-Top:Single-use paperboard with polyethylene sealant layers requires continuous refrigeration but offers lower unit economics. German discount grocery chains favor these formats for private-label fresh milk where cost sensitivity dominates procurement decisions.
- Carton:Generic term encompassing multiple structural configurations without standardized barrier specifications.
- Liquid:Broad category capturing non-dairy applications including plant-based beverages and functional drinks.
Gable-Top leads volumes today; Aseptic is gaining share fastest.
Material:
Converter selection hinges on circularity credentials and regulatory compliance timelines rather than pure performance optimization.
- Paperboard:Forest Stewardship Council-certified fiber substrates constitute the structural backbone of all major formats. German supermarkets mandate chain-of-custody documentation, making certification a non-negotiable procurement filter regardless of price positioning.
- Aluminum:Thin foil layers provide oxygen barrier functionality in extended-shelf-life applications. EU Green Deal packaging waste directives are forcing substitution investments as aluminum elimination becomes a prerequisite for circularity claims.
- Plastic:Polyethylene sealant and extrusion layers enable heat-sealing and moisture resistance.
- Composite:Multi-material laminates combining fiber, polymer, and metal barriers in integrated structures.
Paperboard dominates mass composition; Aluminum faces the steepest substitution pressure.
End User:
Volume concentration and margin capture diverge sharply between organized retail procurement and fragmented food service distribution.
- Retail:Supermarket private-label buyers drive standardization through sustainability scorecards weighting recyclability at 15-20% of total scoring. French and German chains are delisting suppliers without fiber-certification regardless of unit cost competitiveness.
- Food Service:Institutional cafeterias and quick-service restaurants prioritize portion control and dispensing efficiency over barrier sophistication.
- Household:Direct-to-consumer formats emphasize convenience features like resealable spouts and ergonomic handling.
- Institutions:Schools, hospitals, and military procurement operates through centralized tender processes with extended contract durations.
Retail commands margin concentration; Food Service offers volume scale at lower conversion yields.
Distribution Channel:
Channel selection determines format flexibility requirements and minimum order quantity economics for dairy processors.
- Supermarkets:Organized retail chains in Poland's expanding discount sector are penetrating secondary cities, creating demand for cost-optimized gable-top formats with regional converter supply lines. Digital printing integration enables micro-batch customization that collapses previous minimum order thresholds.
- Online:E-commerce fulfillment requires enhanced structural integrity for last-mile handling without temperature excursions.
- Convenience Stores:Smaller format sizes and impulse-oriented merchandising drive single-serve packaging specifications.
- Wholesalers:Bulk distribution to independent retailers and food service operators emphasizes palletization efficiency and case-level traceability.
Supermarkets anchor volume throughput; Online is climbing the fastest as direct-to-consumer dairy subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter engineering talent clusters in Sweden and Finland anchor liquid packaging board production, creating specialized workforce dependencies that shape supply security calculations for dairy brands worldwide.
Germany
Discount grocery chains penetrating secondary cities drive demand for cost-optimized gable-top formats. The Verpackungsgesetz mandates minimum recycled content thresholds, pulling through fiber-based packaging with certified circularity credentials. Converter operations concentrate in North Rhine-Westphalia, where regional supply lines shorten logistics burdens for fresh milk distribution.
India
Ambient dairy distribution networks expand as cold-chain infrastructure gaps persist, accelerating aseptic filling technology adoption. BIS certification requirements mandate specific paperboard grammages and seal integrity standards for dairy packaging. Mumbai and Delhi processing hubs anchor demand concentration for extended-shelf-life formats among ultra-high-temperature milk processors.
United States
FDA food-contact substance notifications govern polyethylene and adhesive migrations in dairy packaging, extending product qualification timelines. Retailer sustainability procurement criteria concentrate in California and Northeast corridor markets, where private-label buyers weight recyclability metrics heavily. Converter partnerships with regional dairy cooperatives enable micro-batch customization through digital printing integration.
France
Supermarket chains hardcode packaging circularity into supplier retention decisions, with recyclability metrics weighted at 15-20% of total procurement scoring. REACH restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from dairy lid stocks, forcing polyethylene extrusion layer reformulation. The Île-de-France region hosts concentrated dairy processing capacity serving organized retail channels.
Netherlands
Polymer-grade paperboard surface treatments pilot in Dutch dairy processing facilities, decentralizing oxygen barrier functionality from aluminum layers. Forest Stewardship Council chain-of-custody certification operates as a non-negotiable procurement filter for supermarket private-label buyers. Rotterdam-area logistics clusters facilitate efficient cold-chain distribution across Benelux retail networks.
Dairy Carton Market Competitive Environment
Top-tier vendors anchor aseptic technology leadership, while mid-scale converters compete through renewable sourcing partnerships and regional supply line optimization. The market structure reflects tiered specialization: incumbents with filling equipment ecosystems command premium positioning, substrate specialists leverage fiber certification advantages, and emerging players target cost-optimized gable-top segments. Strategic moves concentrate on scalable equipment partnerships and bio-based barrier coating development.
Within the premium technology tier, Tetra Pak International S.A. and SIG Combibloc Group AG exemplify contrasting approaches to equipment lock-in versus partnership flexibility. Elopak AS occupies a position emphasizing renewable paperboard sourcing alignment with retailer sustainability criteria. These three entities represent the dominant archetypes: integrated filling technology providers, scalable partnership models, and fiber-certification specialists.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Elopak AS |
| Mondi plc |
| Greatview Aseptic Packaging Company Limited |
| WestRock Company |
| Nippon Paper Industries Co., Ltd. |
| Evergreen Packaging LLC |
| Stora Enso Oyj |
| Others |
Value Chain & Pricing Dynamics
Naphtha-cracker output fluctuations cascade through polyethylene sealant costs into three distinct pricing tiers that separate aseptic carton specialists from regional gable-top converters. Converter concentration in Nordic regions amplifies freight cost pass-throughs to Asian and Latin American dairy brands.
Pricing Analysis
Equipment-versus-material bundling splits the market into integrated technology providers and standalone substrate converters. Three-tier pricing structure across premium, standard, and economy levels reflects aseptic filling equipment lock-in, Forest Stewardship Council certification grade, and volume scale. Cost compression in standard-tier gable-top formats is intensifying because German discount grocery chains are consolidating procurement across secondary cities. Small-scale dairy cooperatives exhibit highest price sensitivity, while ultra-high-temperature milk processors in India prioritize shelf-life performance over unit economics.
Supply Chain Analysis
Freight cost differentials between Nordic liquid packaging board mills and Asian dairy processing hubs favor regional converter partnerships over direct sourcing. Supply concentrates in Sweden, Finland, and Germany for structural paperboard; polyethylene sealant layers draw from naphtha-cracker output in the Netherlands and Belgium. Single-source vulnerability in Nordic pulp supply creates exposure to forest product trade policy shifts. Distribution runs through organized retail chains in Germany and France, with wholesale channels serving fragmented food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy carton market functions as a stable compounder anchored by EU Green Deal compliance deadlines that force recurring material reengineering investments across the installed base.
For Market Incumbents: Acquire bio-based barrier coating patents before polylactic acid and polyhydroxyalkanoate formulations exit pilot phase. Tetra Pak and SIG Combibloc should deepen upstream control over Forest Stewardship Council-certified fiber supply to lock out emerging substrate specialists. Aluminum substitution timelines represent the critical threat vector; certification investment in circularity credentials operates as the primary defensive lever. For New Entrants and Emerging Players: Begin with Poland's discount grocery expansion into secondary cities, where cost-optimized gable-top demand outpaces regional converter capacity. Digital printing integration for micro-batch customization collapses minimum order quantities that previously protected national brands. Target dairy cooperatives in the Netherlands piloting polymer-grade paperboard surface treatments as the most penetrable white-space segment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing renewable sourcing partnerships and regional supply line optimization capabilities. The five-to-ten year viability window favors fiber-certification specialists over equipment-integrated incumbents facing R&D amortization compression. Watch for BIS certification requirement tightening in India as the inflection signal indicating aseptic format acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Fiber Supply | Forest Stewardship Council chain-of-custody certification secures procurement retention in German and French supermarket scorecards. |
| Bio-Based Barrier Coating Development | Polyhydroxyalkanoate formulations eliminate aluminum dependency while satisfying EU Green Deal circularity mandates. |
| Digital Printing Capability Expansion | Variable-data decoration enables micro-batch economics for regional dairy cooperatives previously excluded by volume thresholds. |
| Regional Converter Partnership in Poland | Proximity to discount grocery expansion reduces logistics burdens for fresh milk distribution in secondary cities. |
| Aseptic Filling Equipment Scale-Up | Technology partnerships with Indian ultra-high-temperature processors capture ambient distribution growth as cold-chain gaps persist. |
Study Parameters
Direct dialogue with converter procurement directors, dairy processor operations managers, supermarket category buyers, and regulatory compliance officers grounded the qualitative assessment. Secondary validation drew from EU Green Deal directive texts, BIS certification standards, FDA food-contact substance notifications, Forest Stewardship Council chain-of-custody databases, and liquid packaging board trade flow data. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to anchor volume projections.
Bottom-up analysis traced carton consumption through end-use channels including organized retail, food service, and institutional procurement across the projection horizon. Segmentation dimensions spanned product type, material composition, end-user category, and distribution channel. CAGRs were derived from installed base replacement cycles, regulatory compliance investment trajectories, and cold-chain infrastructure maturity differentials. Aseptic filling equipment deployment rates and gable-top format cost optimization curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt polyethylene price spikes, unilateral aluminum tariff impositions, and accelerated F-Gas Regulation phase-out timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Spicy Dairy Products Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
China Milk Protein Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Donkey Milk Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Global Goat Cheese Market