
 Fat-Filled Milk Powder Market | 2026-2036
Fat-Filled Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Fat-Filled Milk Powder Market Analysis
Multi-source procurement for vegetable fat inputs is broadening as manufacturers seek supply resilience against dairy commodity volatility. Fonterra Co-operative Group Limited leverages its New Zealand milk pool to sustain cost-advantaged fat-filled powder production. FrieslandCampina anchors European supply through integrated dairy and vegetable oil sourcing networks. Lactalis Group competes on manufacturing scale across multiple processing sites.
Fat-filled milk powder combines dairy proteins—typically skim milk solids—with vegetable oils to replicate whole milk powder functionality at lower cost, with fat content ranging from 15% to 50% depending on application requirements. The formulation serves as an economical substitute in UHT milk recombination, confectionery coatings, and processed cheese manufacture where full dairy fat is not technically mandatory. Creamy product variants command margin premiums in ice cream and dessert applications where mouthfeel replication proves most challenging. Bulk packaging dominates industrial procurement channels, while pouches and tins capture branded retail positioning in emerging markets.
EFSA maintains compositional standards for dairy analogues sold within the European Union, while India's FSSAI enforces labeling distinctions between dairy and non-dairy fat blends to protect consumer transparency. BIS certification requirements for milk powder variants in India create compliance barriers that favor established processors with testing infrastructure. Stakeholders must monitor evolving regulatory definitions of dairy identity as plant-based alternatives pressure traditional classification frameworks.
Market Dynamics
EU Green Deal carbon accounting rules and EFSA compositional standards are forcing simultaneous reformulation investments and supply chain reconfiguration across fat-filled milk powder manufacturing networks.
Growth Catalysts
- EFSA dairy analogue standards:Clear compositional thresholds for vegetable fat blends reduce regulatory uncertainty for manufacturers expanding into EU markets.
- India PLI scheme incentives:Domestic dairy processing capacity subsidies under the Production Linked Incentive program attract capital toward fat-filled powder lines.
- Bakery sector procurement:Commercial bread and pastry manufacturers in emerging economies are substituting whole milk powder with cost-advantaged fat-filled alternatives.
Market Restraints
- Palm oil price volatility:Vegetable fat inputs represent 35-45% of variable production costs, exposing margins to commodity swings in Southeast Asian supply.
- BIS certification barriers:India's Bureau of Indian Standards testing infrastructure requirements favor established processors and block informal entrants.
- Whole milk powder substitution:Premium dairy fat retains technical advantages in infant nutrition and certain confectionery applications where mouthfeel standards are rigid.
Strategic Opportunities
- Sub-Saharan Africa retail channels:Pouch and tin packaging formats for household consumers remain underdeveloped relative to industrial bulk supply.
- EU Green Deal carbon border adjustments:Early alignment with embedded emissions accounting creates competitive positioning for low-carbon vegetable oil sourcing.
- Ice cream mouthfeel replication:High-fat variants (40-50% fat content) command margin premiums in frozen dessert applications where technical performance gaps persist.
Industry Challenges
- FSSAI labeling compliance timelines:India's food safety authority mandates distinct dairy and non-dairy fat blend classifications requiring packaging redesign and distribution channel re-education.
- Skilled dairy technologist scarcity:Formulation expertise spanning protein stabilization, vegetable oil emulsification, and spray-drying optimization concentrates among aging specialist cohorts.
- Legacy recombination equipment compatibility:UHT milk processors face capital decisions when integrating modified powder specifications into existing hydration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat-Filled Milk Powder Market |
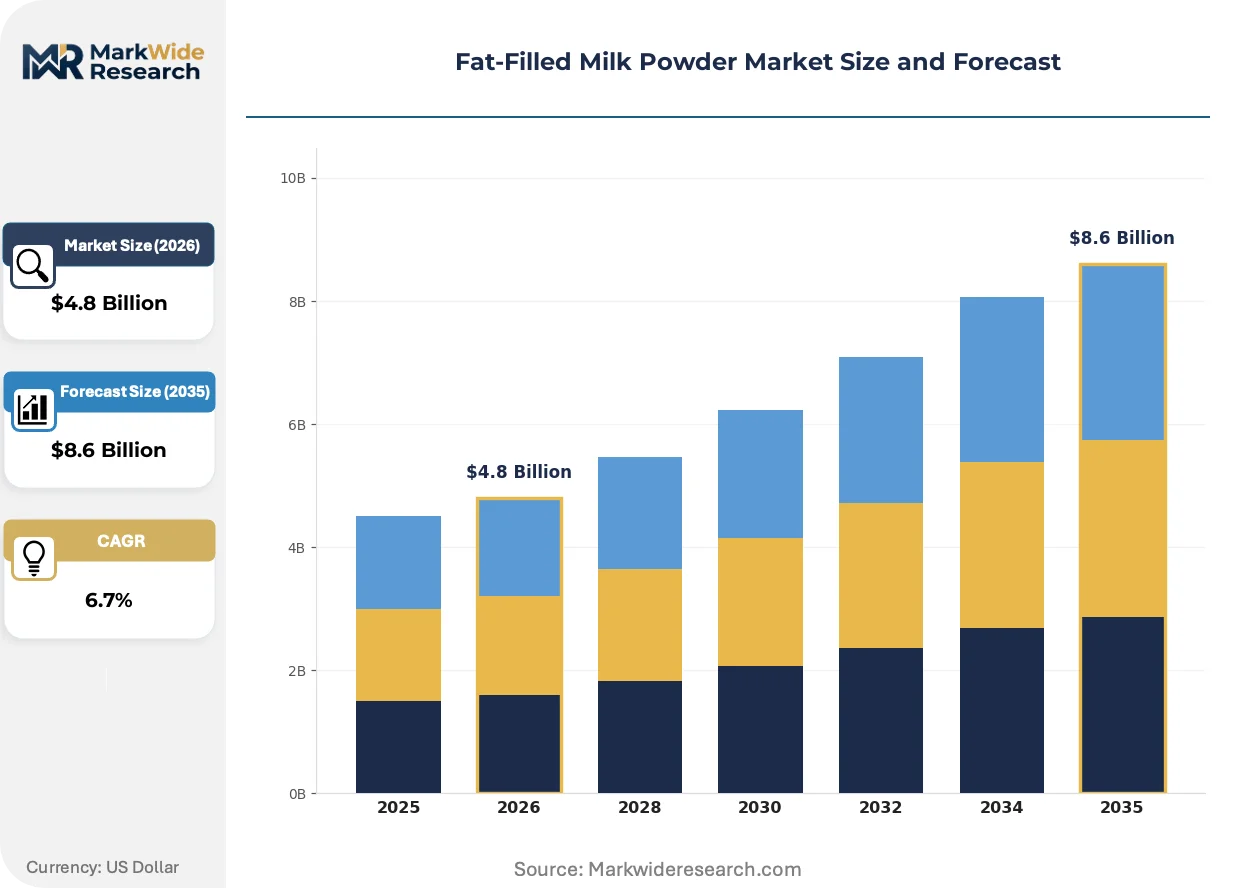
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skimmed, Whole, Creamy, Low-Fat End Use: Dairy Products, Bakery, Confectionery, Ice Cream Packaging Type: Bags, Tins, Pouches, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Nestlé S.A., Fonterra Co-operative Group Limited, FrieslandCampina, Danone S.A., Lactalis Group, Arla Foods, Vreugdenhil Dairy Foods, Saputo Inc., Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat-Filled Milk Powder Market Emerging Trajectories
Micro-encapsulation and lipid structuring technologies are fragmenting the traditional tradeoff between cost reduction and functional performance in dairy fat replacement.
Spray-drying control systems with real-time moisture and particle-size feedback loops are decentralizing quality assurance from centralized laboratories to production lines. Mid-scale dairy processors in India and Brazil are adopting these sensor arrays to reduce batch rejection rates. Distributed quality control is compressing the cost advantage previously held by large integrated manufacturers with captive testing infrastructure.
EU Green Deal farm-to-fork sustainability frameworks are mandating supply chain traceability documentation for vegetable oil inputs. EFSA-aligned processors must now verify deforestation-free palm oil sourcing through satellite monitoring and supplier audits. Bakery and confectionery manufacturers in Germany, France, and the Netherlands are prioritizing certified-sustainable fat-filled powders in procurement specifications.
Industrial buyers are consolidating supplier relationships and demanding technical service bundling beyond commodity supply. Large food manufacturers in India are negotiating multi-year contracts incorporating formulation support and application testing. This concentration of procurement decision-making is squeezing spot-market traders and fragmenting the vendor base into technical partners versus transactional suppliers.
Fat-Filled Milk Powder Market Segmentation
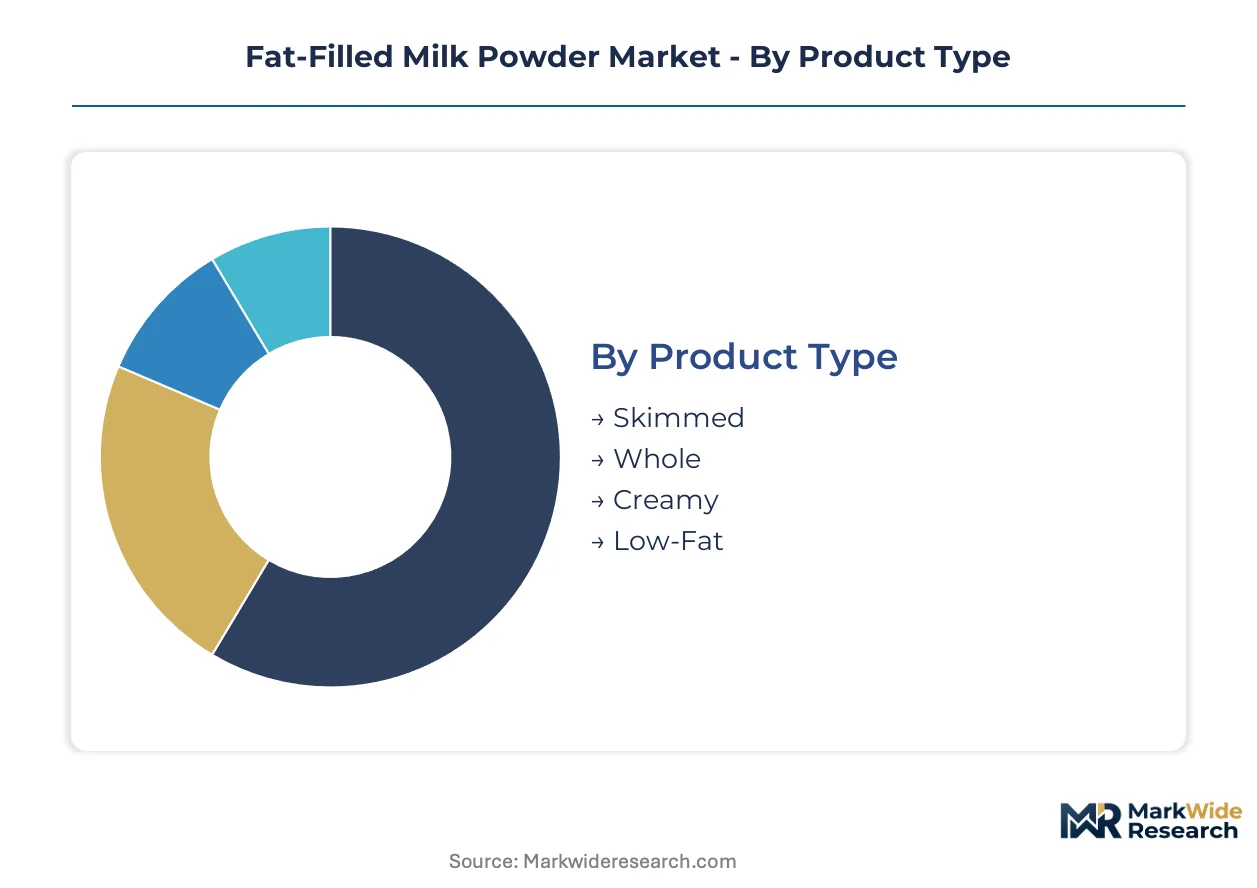
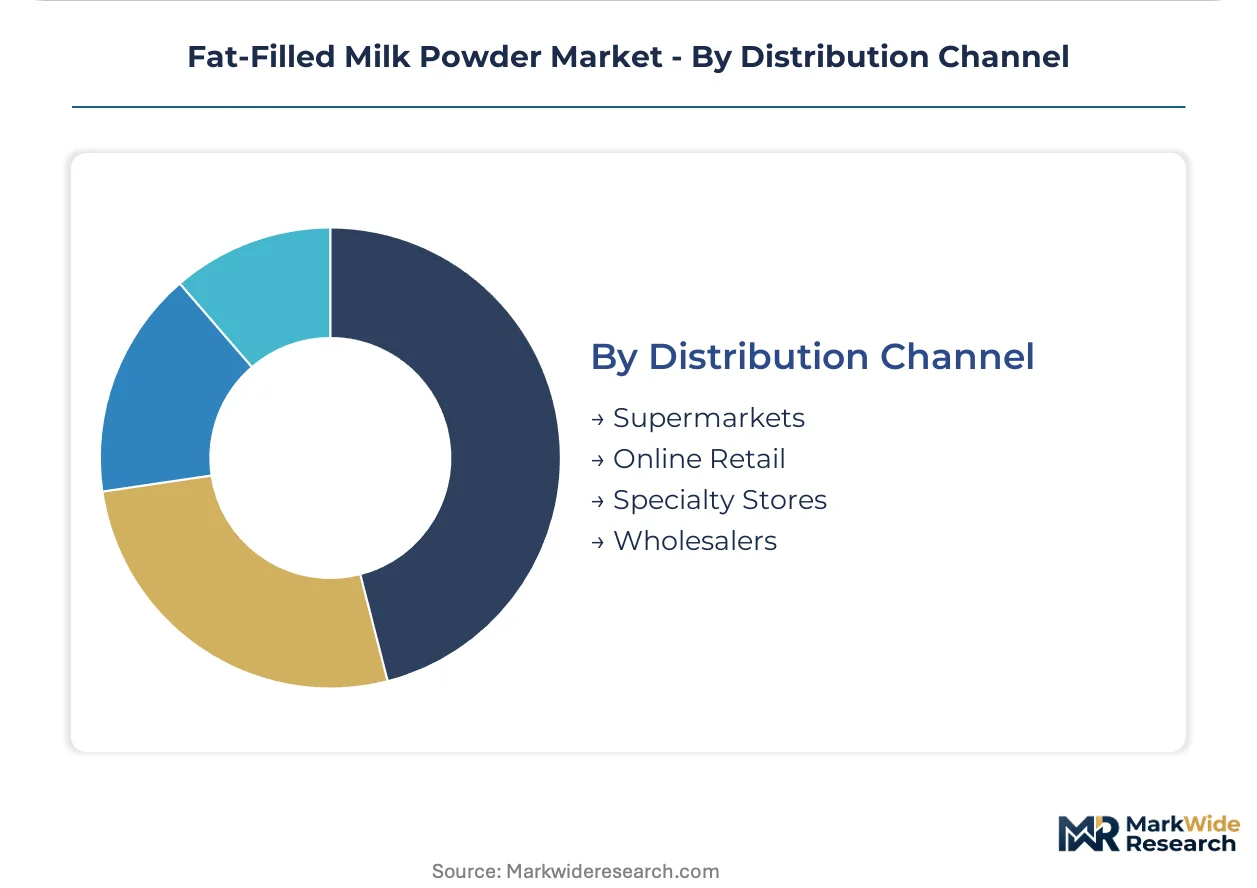
Segmentation in fat-filled milk powder reveals how formulation flexibility, packaging economics, and channel access determine competitive positioning. Manufacturers must align production assets with the technical requirements of each product tier while navigating divergent regulatory and customer expectations across end-use applications.
Product Type:
Capital intensity varies sharply across this dimension, with spray-drying equipment configuration and fat-handling infrastructure driving differential upfront investment requirements.
- Creamy:High-fat formulations (40-50% vegetable oil content) demand specialized emulsification systems and precise lipid structuring to replicate whole milk powder mouthfeel. Demand concentrates in premium ice cream manufacturing across Germany, France, and the Netherlands where EFSA-aligned sustainability documentation commands procurement priority.
- Whole:Standard fat-filled variants (26-28% fat) balance cost reduction with functional equivalence in UHT milk recombination. India's commercial dairy processors under FSSAI jurisdiction represent the densest demand cluster, driven by PLI scheme capacity subsidies and BIS certification requirements that favor established testing infrastructure.
- Skimmed:Low-fat formulations (15-20% fat) serve cost-sensitive bakery applications where protein functionality matters more than fat replication.
- Low-Fat:Reduced-fat positioning targets health-conscious retail segments with modified nutritional labeling.
Most installed capacity flows through Whole variants. Expansion is steepest in Creamy.
End Use:
Application-driven formulation requirements create distinct margin tiers, with technical service bundling most advanced in segments demanding mouthfeel precision.
- Ice Cream:Frozen dessert manufacturers require high-fat powders with specific melting profiles and aeration stability. German and Dutch confectionery houses now mandate deforestation-free palm oil certification through EU Green Deal traceability frameworks, compressing margins for non-compliant suppliers.
- Bakery:Bread and pastry manufacturers in emerging economies substitute whole milk powder with cost-advantaged fat-filled alternatives for dough conditioning and browning. India's commercial baking sector under FSSAI labeling rules drives the largest volume procurement, though BIS testing barriers restrict vendor participation.
- Confectionery:Chocolate coatings and filled products demand precise fat crystallization behavior.
- Dairy Products:Processed cheese and recombined milk applications prioritize protein functionality and hydration rates.
Volume concentrates in Bakery. Value capture is highest in Ice Cream.
Packaging Type:
Packaging economics segment the market between industrial efficiency and retail accessibility, with format selection determining distribution reach and working capital intensity.
- Bulk:Industrial totes and flexible intermediate bulk containers dominate commercial food manufacturing procurement, minimizing per-unit packaging cost. Sub-Saharan African dairy processors represent the fastest-expanding demand node as regional recombination capacity scales.
- Pouches:Flexible retail formats capture household demand in emerging markets where cold chain infrastructure remains limited. Indian urban consumers through modern trade channels drive pouch volume, with FSSAI-mandated dairy versus non-dairy labeling requiring packaging redesign investment.
- Tins:Metal canisters command shelf-stable positioning premiums in gift and export segments.
- Bags:Multi-wall paper and plastic bags serve mid-scale food service and institutional buyers.
Bulk formats absorb the majority of production tonnage. Pouch formats are climbing the fastest.
Distribution Channel:
Channel selection determines customer intimacy versus scale tradeoffs, with technical service integration most pronounced in direct wholesale relationships.
- Wholesalers:Industrial distributors aggregate demand from mid-scale food manufacturers and institutional buyers across India, Brazil, and Nigeria. Large Indian food manufacturers now negotiate multi-year contracts incorporating formulation support and application testing, squeezing spot-market traders.
- Supermarkets:Modern retail chains in urban India and Southeast Asia stock branded pouches and tins for household consumers. EU Green Deal carbon accounting requirements are filtering into private-label procurement specifications.
- Specialty Stores:Ethnic food retailers and dairy-focused independents serve diaspora communities and artisan producers.
- Online Retail:E-commerce platforms capture trial purchases and bulk replenishment in digitally mature markets.
Wholesalers move the greatest volume. Supermarkets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's commercial dairy processing corridor between Mumbai and Delhi anchors global fat-filled milk powder procurement intensity. Bakery sector expansion and PLI scheme subsidies are concentrating new capacity in Gujarat and Maharashtra. Regulatory divergence between EFSA-aligned European markets and FSSAI-governed Indian channels is fragmenting formulation standards.
India
Commercial bread manufacturers in Mumbai and Pune are substituting whole milk powder with cost-advantaged fat-filled alternatives for dough conditioning. FSSAI mandates distinct dairy versus non-dairy fat blend classifications on all retail packaging. The Anand-Gujarat dairy cluster hosts expanding spray-drying capacity as PLI scheme incentives attract capital toward domestic processing infrastructure.
Germany
Premium ice cream manufacturers in Hamburg and Berlin require high-fat powders with deforestation-free palm oil certification. EU Green Deal carbon accounting rules force supply chain traceability documentation for all vegetable oil inputs. The Lower Saxony dairy processing belt is reconfiguring sourcing networks to verify sustainability credentials through satellite monitoring systems.
Netherlands
Confectionery houses in Amsterdam and Rotterdam prioritize EFSA-aligned fat-filled powders with embedded emissions transparency. REACH-compliant emulsifier sourcing is reshaping procurement specifications for chocolate coating applications. The Friesland dairy technology corridor maintains integrated vegetable oil and dairy protein sourcing networks for continental supply.
Brazil
Mid-scale bakery chains in São Paulo and Minas Gerais are adopting sensor-equipped spray-drying systems to reduce batch rejection rates. ANVISA food additive regulations govern vegetable fat emulsifier approvals for dairy analogue formulations. The Campinas industrial dairy zone is consolidating technical service relationships with multi-year contract structures.
Nigeria
Household consumers in Lagos and Kano are driving pouch format demand as cold chain infrastructure remains limited. The country's national food safety authority enforces labeling standards for imported dairy alternatives. Sub-Saharan African dairy processors are scaling recombination capacity with bulk-format procurement from established trading networks.
Fat-Filled Milk Powder Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue technical service bundling and sustainability certification as differentiation vectors. The vendor base concentrates around integrated dairy cooperatives with captive vegetable oil sourcing and mid-scale regional processors with distributed quality control. Three archetypes dominate: scale-driven cooperatives with backward integration into milk pools, formulation specialists with application testing capabilities, and commodity traders pivoting toward technical partnership models. Competitive intensity manifests through multi-year contract negotiations incorporating formulation support and carbon footprint documentation.
Within the cooperative archetype, Fonterra Co-operative Group Limited and FrieslandCampina exemplify scale advantages through integrated milk pool and vegetable oil networks. Lactalis Group occupies a position representing manufacturing scale distributed across multiple processing sites. These three entities anchor the competitive structure by demonstrating how geographic sourcing breadth and technical service integration create barriers against spot-market traders.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Fonterra Co-operative Group Limited |
| FrieslandCampina |
| Danone S.A. |
| Lactalis Group |
| Arla Foods |
| Vreugdenhil Dairy Foods |
| Saputo Inc. |
| Glanbia plc |
| Others |
Supply Flow & Price Mechanics
Spray-drying control systems with real-time moisture feedback are compressing quality assurance costs and redistributing pricing power from large integrated manufacturers toward mid-scale regional processors in India and Brazil. This technological shift simultaneously erodes the historical premium commanded by captive testing infrastructure while intensifying margin pressure on commodity traders lacking formulation support capabilities.
Pricing Analysis
Vegetable oil pass-through dominates variable cost structures, with palm oil and coconut oil fluctuations transmitting directly to contract renegotiations within 60-90 day windows. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-aligned sustainability-certified powders from FSSAI-compliant domestic grades and unbranded bulk supply. Cost compression in standard tiers is intensifying because Indian bakery manufacturers are consolidating procurement into multi-year technical service contracts. Small-scale confectionery houses remain most price-sensitive; premium ice cream manufacturers least so due to mouthfeel performance requirements.
Supply Chain Analysis
Dual-sourcing mandates from EU confectionery manufacturers now require qualified backup suppliers for both New Zealand dairy proteins and Southeast Asian vegetable oils. Geographic supply concentrates in India, New Zealand, and the Netherlands, with spray-drying capacity expansion accelerating in Gujarat and Maharashtra under PLI scheme incentives. Raw material dependencies rest on skim milk solids, palm oil fractions, and specialized emulsifiers subject to REACH compliance verification. Single-source vulnerability persists in deforestation-free palm oil certification streams tracked through satellite monitoring. Distribution runs through industrial wholesalers aggregating demand from mid-scale food manufacturers across India, Brazil, and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fat-filled milk powder market has entered a late-cycle quality phase where EFSA-aligned sustainability documentation and mouthfeel replication precision command procurement priority over pure cost reduction. German and Dutch ice cream manufacturers now mandate embedded emissions transparency as a baseline qualification, not a premium add-on.
For Market Incumbents: To counter distributed quality control adoption by mid-scale Indian and Brazilian processors, deepen captive vegetable oil sourcing networks through backward integration into certified-sustainable palm oil supply streams. Anchor multi-year contracts with technical service bundling spanning formulation support and application testing to lock in bakery sector procurement consolidation. For New Entrants and Emerging Players: FSSAI labeling compliance timelines in India open a window for packaging redesign specialists and distribution channel educators serving informal processors blocked by BIS certification barriers. Target pouch format retail positioning in Nigerian household channels where cold chain gaps persist and modern trade penetration remains shallow. Lead with carbon footprint documentation to capture EU Green Deal-aligned procurement specifications from sustainability-conscious confectionery houses. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity traders pivoting toward technical partnership models without established formulation capabilities. Long-term viability over the next decade hinges on spray-drying asset ownership in geographies with PLI-style capacity subsidies and access to deforestation-free vegetable oil certification streams. Watch for inflection when Indian dairy processors begin mandating real-time moisture feedback systems as baseline equipment specifications rather than competitive differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified-Sustainable Vegetable Oils | Secures deforestation-free palm oil streams required by EU Green Deal procurement specifications from German confectionery houses. |
| Multi-Year Technical Service Contracting | Locks in Indian bakery sector demand through bundled formulation support and application testing beyond commodity supply. |
| Real-Time Spray-Drying Sensor Deployment | Reduces batch rejection rates for mid-scale Brazilian processors competing with large integrated manufacturers' quality infrastructure. |
| Pouch Format Retail Expansion | Captures Nigerian household demand where cold chain limitations favor shelf-stable packaging and modern trade remains underdeveloped. |
| EFSA-Aligned Carbon Footprint Documentation | Creates competitive positioning for EU market access as embedded emissions accounting filters into private-label procurement specifications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing plant managers, procurement leads at commercial bakery chains, vegetable oil sourcing specialists, and FSSAI regulatory compliance officers with secondary validation. Customs data on milk powder trade flows, BIS certification registries, EFSA compositional standard filings, and EU Green Deal supply chain traceability documentation anchored the quantitative foundation. Bottom-up capacity assessments across Indian dairy clusters triangulated against top-down demand modeling from bakery and confectionery sector procurement patterns.
Segment-weighting approaches distributed value and volume projections across product type tiers, end-use applications, packaging formats, and distribution channels throughout the forecast period. Fat content gradations, emulsification system requirements, and sustainability certification levels provided industry-specific segmentation dimensions. CAGRs were derived from installed capacity trajectories, PLI scheme incentive uptake rates, and substitution elasticity estimates between whole milk powder and fat-filled alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under palm oil price volatility spikes or abrupt BIS certification requirement changes. Deviation in EU Green Deal carbon border adjustment implementation timelines would shift the outlook materially for EFSA-aligned processors competing against lower-cost uncertified supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Non-Fat Milk Market
Dairy Products
Dairy Foods Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
India Dairy Market
Dairy Products
US Cheese Market
Dairy Products
Natural Cheese Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Goat Milk Products Market
Dairy Products
Global Lipolyzed Butter Fat Market