
 Middle East and Africa Flavored Milk Market | 2026-2036
Middle East and Africa Flavored Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Flavored Milk Market Foresight
Aftermarket cold-chain service revenue is rewriting profit allocation across the Middle East and Africa flavored milk value chain, shifting margin capture from production toward logistics partners who guarantee shelf-life compliance in ambient-dominant retail environments. Almarai leverages its captive distribution network across Saudi Arabia, Bahrain, and Jordan to sustain temperature-controlled delivery density that competitors cannot match. FrieslandCampina anchors West African supply through Nigerian processing partnerships, while Danone competes via specialized pediatric and school-channel formulations that navigate divergent national fortification standards.
Flavored milk denotes pasteurized or UHT-treated dairy beverages incorporating food-grade flavoring systems, stabilizers, and typically six to twelve percent milk solids non-fat, manufactured through either in-line flavor injection or batch blending followed by homogenization at 150-200 bar to prevent fat separation during ambient distribution. Chocolate formulations occupy the largest volume share across Middle East and Africa retail due to established child-targeted positioning, though health-conscious consumer segments are accelerating demand for reduced-sugar vanilla variants fortified with vitamins A and D. Tetra Pak aseptic cartons dominate packaging type selection where electricity intermittency constrains refrigerated supply chains, while pouches gain traction in Nigerian and Kenyan informal retail where unit economics favor lower per-serve price points.
Saudi Arabia's SFDA enforces dairy fortification mandates and sugar-labeling transparency that shape product formulation decisions for manufacturers distributing across Gulf Cooperation Council markets, while South Africa's Department of Health coordinates school nutrition procurement specifications that directly determine volume allocation for participating processors. Nigeria's National Agency for Food and Drug Administration and Control regulates dairy import quotas and local content requirements, creating compliance complexity for brands relying on skim milk powder imports. Stakeholders must monitor evolving pan-African harmonization of dairy standards through the African Continental Free Trade Area implementation bodies, as tariff-phase commitments will reshape competitive access for Egyptian, South African, and Kenyan production bases serving cross-border demand.
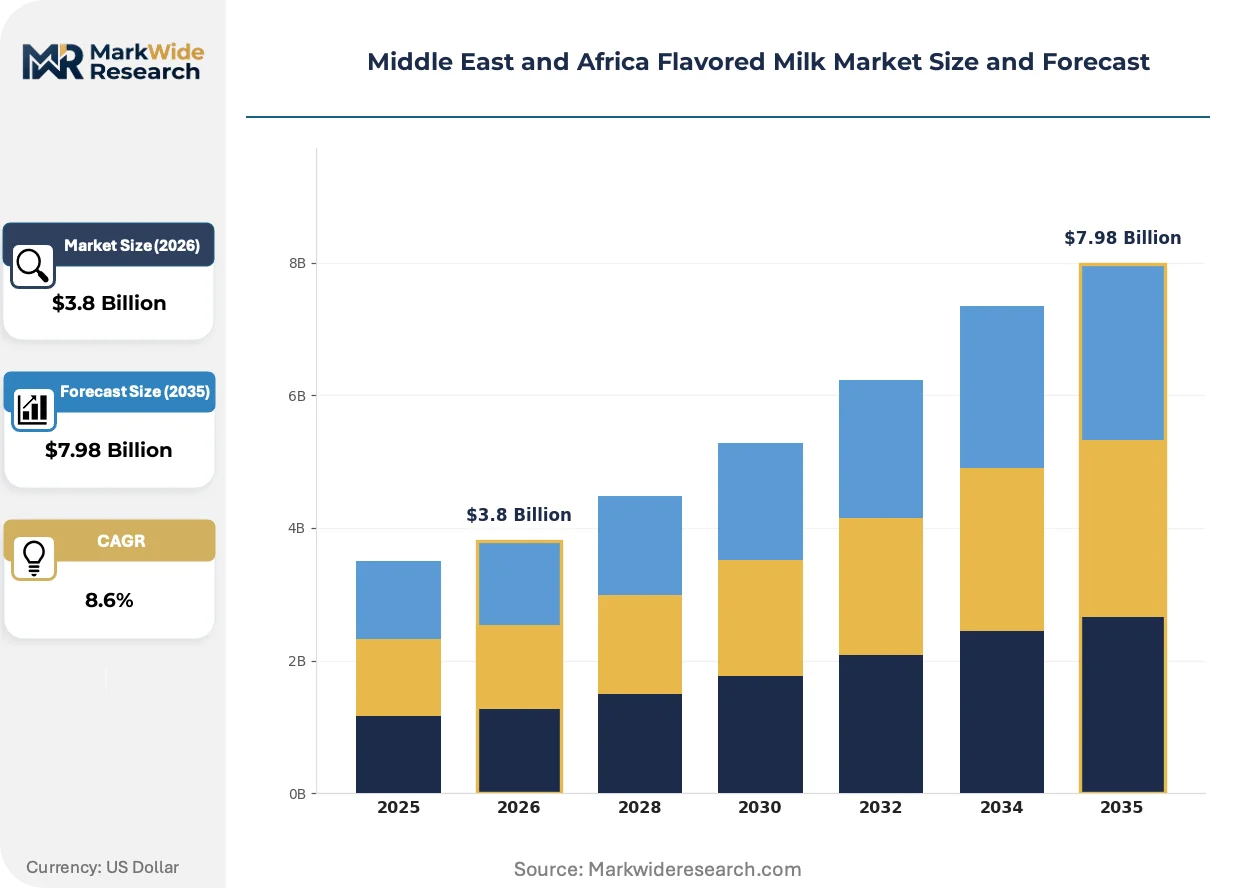
Market Dynamics
Aftermarket cold-chain service revenue is rewriting profit allocation across the Middle East and Africa flavored milk value chain, shifting margin capture from production toward logistics partners who guarantee shelf-life compliance in ambient-dominant retail environments.
Growth Catalysts
- School nutrition procurement:South Africa's Department of Health coordinates feeding program specifications that directly determine volume allocation for processors supplying student-targeted single-serve cartons.
- Urban retail modernization:Nigeria's Lagos-Ibadan corridor is concentrating demand as cold-chain expansion enables branded flavored milk penetration into traditional trade channels previously served by ambient-stable alternatives.
- Fortification mandates:Saudi Arabia's SFDA enforces dairy fortification requirements that shape product formulation decisions for manufacturers distributing across Gulf Cooperation Council markets.
Market Restraints
- Skim milk powder import dependency:Nigeria's National Agency for Food and Drug Administration and Control regulates dairy import quotas and local content requirements, creating compliance complexity for brands reliant on imported inputs.
- Electricity intermittency:Refrigerated supply chain gaps across much of sub-Saharan Africa constrain distribution reach and force reliance on higher-cost aseptic packaging formats.
- Sugar-labeling transparency requirements:Saudi Arabia's tightened dairy labeling standards for added sugars are pushing reformulation investments that compress margin structures for mass-market positioning.
Strategic Opportunities
- Reduced-sugar vanilla fortification:Health-conscious consumer segments are accelerating demand for variants fortified with vitamins A and D, opening premium positioning above chocolate-dominant mass market.
- African Continental Free Trade Area harmonization:Evolving pan-African dairy standard alignment through AfCFTA implementation bodies will reshape competitive access for Egyptian, South African, and Kenyan production bases.
- Pouch format penetration:Unit economics favoring lower per-serve price points are driving packaging innovation in Nigerian and Kenyan informal retail where Tetra Pak cartons face cost barriers.
Industry Challenges
- Temperature-controlled delivery density:Competitors struggle to match captive distribution network coverage that sustains shelf-life compliance across Saudi Arabia, Bahrain, and Jordan.
- Divergent national fortification standards:Pediatric and school-channel formulations must navigate incompatible regulatory requirements across West African, East African, and Gulf markets.
- Cold-chain technician scarcity:Maintenance and monitoring capabilities for ambient-dominant retail environments lag expansion of refrigerated last-mile infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Flavored Milk Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Strawberry, Vanilla, Coffee Packaging Type: Bottles, Tetra Packs, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice End User: Children, Teens, Adults, Health-Conscious Consumers |
| Companies Covered | Arla Foods, Clover, Danone, SADAFCO, Almarai, Nestlé, Lactalis, Najran Dairy Co. Ltd, FrieslandCampina, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Flavored Milk Market Shifts & Advancements
Product formulation and packaging technology are converging to address the fundamental tension between shelf-stable distribution economics and clean-label positioning demands across electricity-constrained retail environments.
Aseptic carton technology is hybridizing with in-line flavor injection systems to enable precise batch control while maintaining ambient distribution viability. Mid-scale processors in Kenya and Egypt are adopting hybrid aseptic-pouch lines that preserve UHT sterility while reducing per-unit packaging costs. This convergence is compressing the traditional trade-off between shelf-life security and price accessibility in informal retail channels.
Saudi Arabia's SFDA has tightened dairy labeling requirements for added sugars and fortification claims, forcing reformulation investments that reshape competitive positioning. Manufacturers distributing across Gulf Cooperation Council markets must now navigate transparent sugar disclosure mandates that disadvantage legacy formulations. Chocolate variants targeting child positioning face particular pressure as reduced-sugar alternatives gain shelf space in Saudi and UAE retail.
Urban retail procurement patterns in Nigeria's Lagos-Ibadan corridor are fragmenting as traditional trade channels modernize cold-chain capabilities. Branded flavored milk is displacing ambient-stable alternatives in open-air markets where refrigeration units now reach previously excluded zones. This channel evolution is most visible in student feeding initiatives and convenience-oriented household purchasing.
Middle East and Africa Flavored Milk Market Segmentation
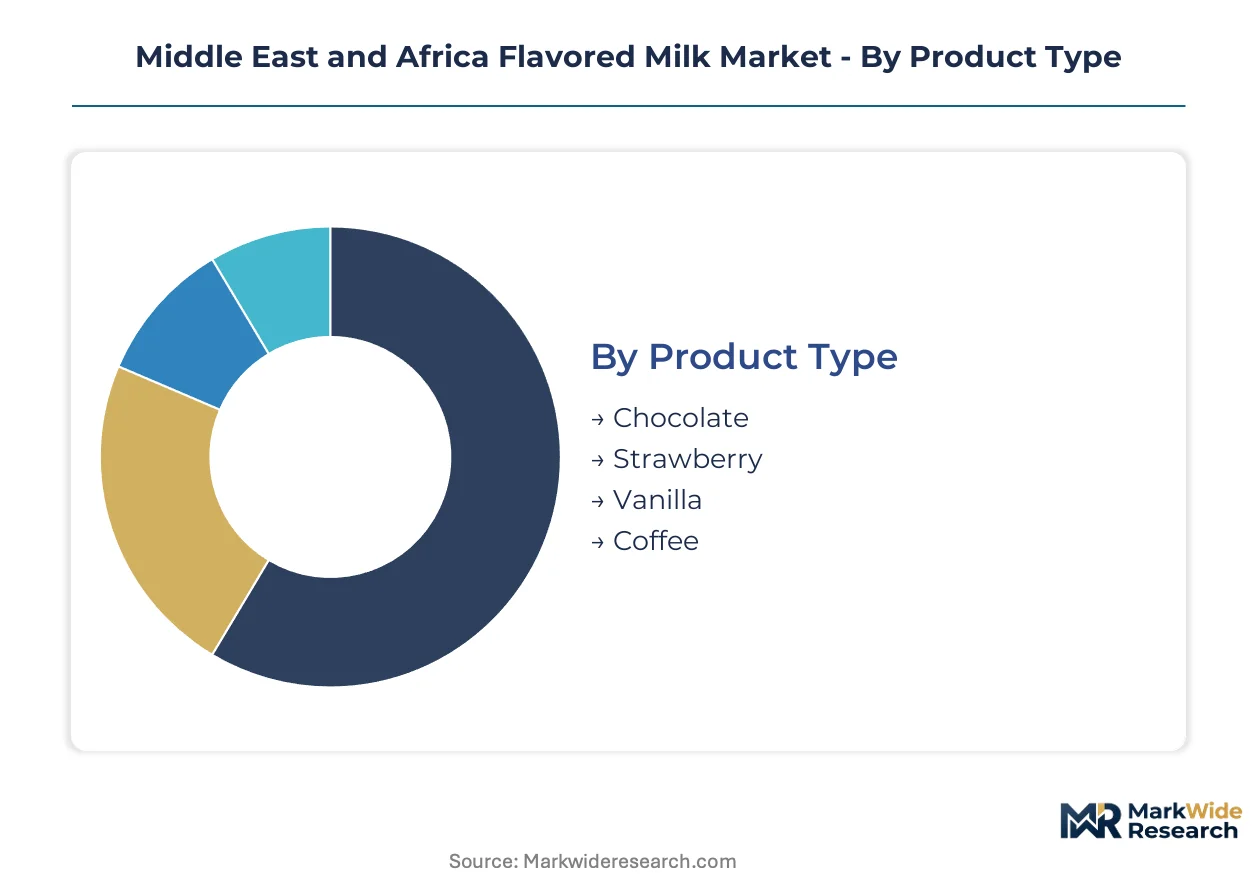
Segmentation in Middle East and Africa flavored milk reveals how formulation choices, packaging economics, and channel access determine competitive viability across divergent retail infrastructures. Product positioning must reconcile ambient distribution constraints with evolving consumer expectations for fortification and sugar transparency.
Product Type:
Mature chocolate formulations dominate volume, while emerging reduced-sugar variants are capturing premium positioning as regulatory pressure intensifies across Gulf markets.
- Chocolate:Pasteurized or UHT-treated dairy with cocoa-based flavoring systems, stabilizers, and six to twelve percent milk solids non-fat. Demand concentrates in South African school nutrition procurement and Nigerian urban retail, where child-targeted positioning drives single-serve carton volumes despite tightening sugar-labeling requirements from Saudi Arabia's SFDA.
- Vanilla:Dairy beverages incorporating natural or artificial vanilla flavoring, increasingly formulated with reduced sugar and vitamins A and D fortification. Health-conscious segments in Saudi Arabia and UAE retail are accelerating adoption, opening premium shelf space above mass-market chocolate alternatives as SFDA mandates reshape competitive positioning.
- Strawberry:Fruit-flavored dairy variants with anthocyanin-based color stability systems for ambient distribution.
- Coffee:Caffeinated dairy beverages targeting adult consumption occasions in Gulf Cooperation Council convenience retail.
Chocolate handles the majority of throughput; vanilla is the fastest mover on share.
Packaging Type:
Cost tier stratification separates premium temperature-controlled formats from economy-oriented ambient-stable alternatives in electricity-constrained markets.
- Tetra Packs:Aseptic carton technology enabling UHT sterility with twelve-month ambient shelf life, manufactured through in-line flavor injection and homogenization at 150-200 bar. Dominates Nigerian and Kenyan retail where electricity intermittency forces reliance on non-refrigerated distribution, though per-unit economics limit penetration in informal trade channels.
- Pouches:Flexible film packaging with UHT compatibility and reduced material costs, increasingly adopted by mid-scale processors in Kenya and Egypt through hybrid aseptic-pouch production lines. Unit economics favoring lower per-serve price points are driving penetration in Nigerian and Kenyan informal retail where Tetra Pak cartons face cost barriers.
- Bottles:HDPE or PET formats requiring cold-chain integrity, concentrated in Gulf markets with reliable refrigeration infrastructure.
- Cartons:Gable-top refrigerated formats with shorter shelf life, positioned for premium household consumption in South African urban retail.
Tetra Packs handle the majority of throughput; pouches are gaining share fastest in informal retail expansion.
Distribution Channel:
Customer type differentiation separates institutional procurement from household purchasing across modernizing traditional trade corridors.
- Supermarkets:Formal retail with refrigeration infrastructure, concentrated in South African urban centers and Saudi Arabia's organized retail sector.
- Convenience Stores:Small-format retail with ambient-dominant inventory, primary channel for single-serve flavored milk in Nigeria's Lagos-Ibadan corridor.
- Foodservice:Institutional procurement including school nutrition programs, where South Africa's Department of Health coordinates feeding program specifications that directly determine volume allocation for processors supplying student-targeted cartons.
- Online Retail:E-commerce platforms with cold-chain fulfillment requirements, emerging in UAE and Saudi urban centers.
Convenience stores handle the majority of throughput; foodservice is climbing fastest on institutional procurement expansion.
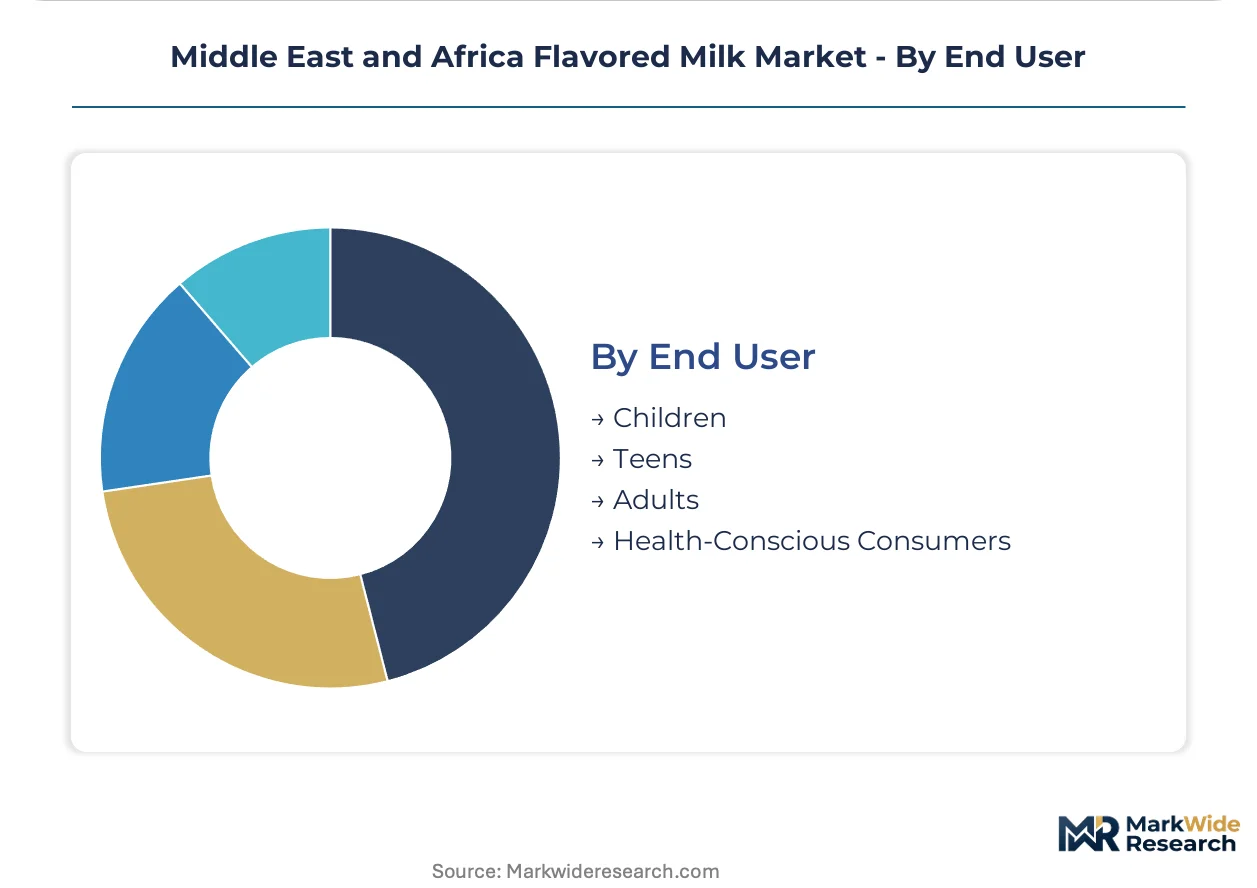
End User:
Application focus separates pediatric fortification requirements from adult wellness positioning across divergent national regulatory frameworks.
- Children:Core target segment for chocolate formulations, concentrated in school feeding initiatives and household purchasing across South Africa and Nigeria.
- Teens:Adolescent consumers with independent purchasing power, targeted through convenience store availability and on-the-go packaging formats.
- Adults:Coffee-flavored and functional variants for workplace consumption occasions in Gulf urban centers.
- Health-Conscious Consumers:Demanding reduced-sugar vanilla with vitamins A and D fortification, concentrated in Saudi Arabia and UAE retail where SFDA labeling transparency is reshaping product availability.
Children handle the majority of throughput; health-conscious consumers are expanding most quickly on regulatory and wellness trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes flavored milk primarily through temperature-controlled retail channels, while Nigeria and Kenya rely on ambient-stable formats due to electricity constraints. South Africa blends both models through formal retail and school feeding programs. This consumption-mix differential shapes manufacturing investments and distribution partnerships across the region.
Saudi Arabia
SFDA fortification mandates and sugar-labeling transparency are forcing reformulation investments among processors serving Gulf Cooperation Council markets. Riyadh and Jeddah retail corridors concentrate demand for premium reduced-sugar vanilla variants. Almarai leverages captive distribution networks to sustain cold-chain density that competitors cannot match across the kingdom.
South Africa
School nutrition procurement through the Department of Health directly determines volume allocation for student-targeted single-serve cartons. Urban retail in Johannesburg and Cape Town supports both refrigerated gable-top formats and ambient Tetra Pak distribution. Clover anchors domestic supply through processing capacity serving institutional and household channels simultaneously.
Nigeria
NAFDAC regulates dairy import quotas and local content requirements, creating compliance complexity for brands reliant on skim milk powder inputs. The Lagos-Ibadan corridor concentrates demand as cold-chain expansion enables branded penetration into traditional trade channels. FrieslandCampina anchors West African supply through Nigerian processing partnerships.
Kenya
Mid-scale processors are adopting hybrid aseptic-pouch production lines that preserve UHT sterility while reducing per-unit packaging costs. Nairobi's urban retail modernization is fragmenting procurement patterns across formal supermarkets and informal open-air markets. Tetra Pak cartons face cost barriers in informal trade where pouch unit economics dominate.
Egypt
African Continental Free Trade Area implementation is positioning Egyptian production bases for cross-border supply to East African markets. Cairo and Alexandria processing clusters are upgrading to hybrid aseptic-pouch lines for price-accessible export formats. Regulatory alignment through AfCFTA bodies will reshape competitive access against South African and Kenyan rivals.
Middle East and Africa Flavored Milk Market Competitive Landscape
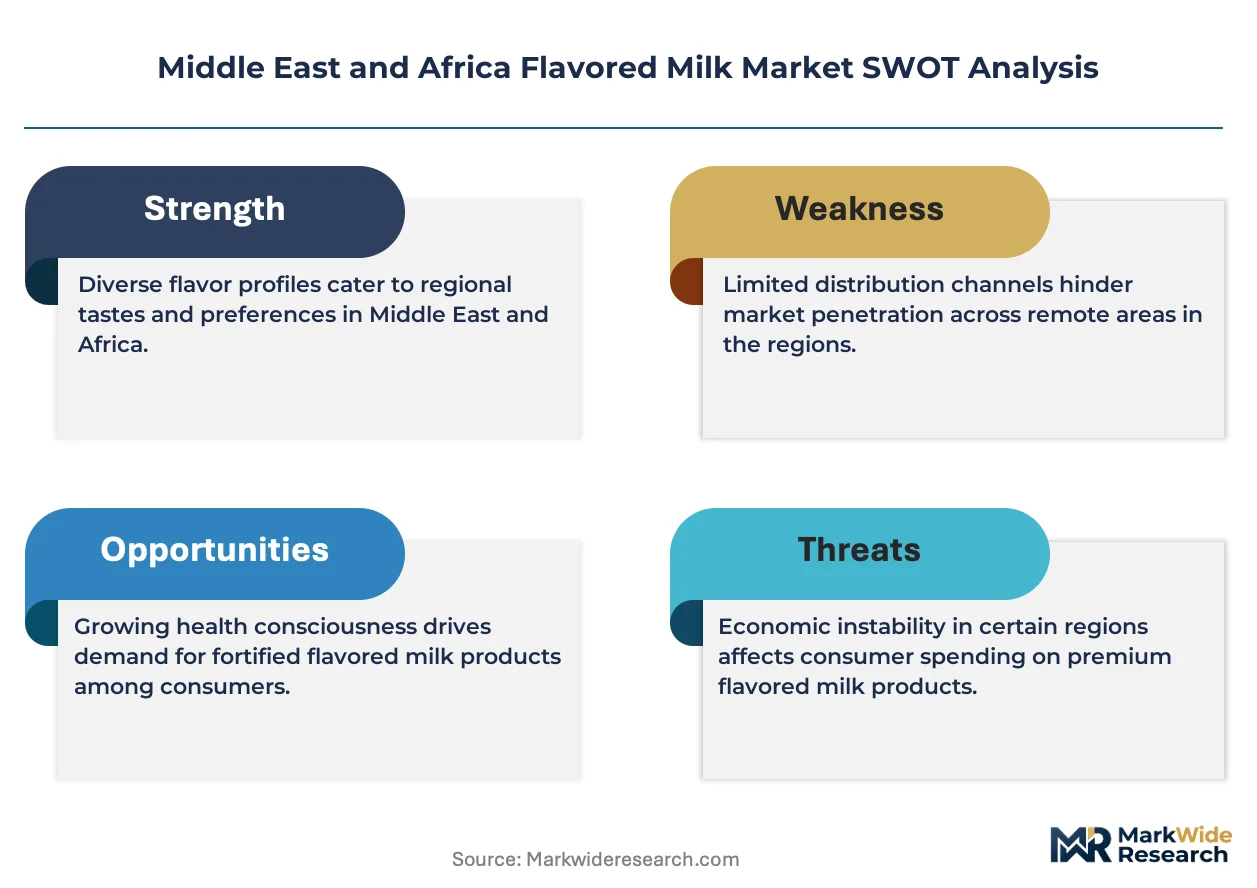
Capability concentration sits with logistics-intensive operators; scale advantage sits with multinational dairy conglomerates. The market structures around three tiers: Gulf-based processors with captive cold-chain networks, European multinationals with pediatric formulation expertise, and African regional players with informal trade penetration. Dominant competitive moves include strategic partnerships with aftermarket cold-chain service providers and portfolio diversification into reduced-sugar fortified variants.
Among Gulf-based integrated processors, Almarai and SADAFCO exemplify the logistics-captive archetype through temperature-controlled distribution density. European multinationals Danone and FrieslandCampina occupy positions emphasizing specialized pediatric and school-channel formulations. Arla Foods and Nestlé represent the diversified global dairy conglomerate tier with regional adaptation capabilities.
| Leading Market Players |
|---|
| Arla Foods |
| Clover |
| Danone |
| SADAFCO |
| Almarai |
| Nestlé |
| Lactalis |
| Najran Dairy Co. Ltd |
| FrieslandCampina |
| Others |
Supply & Pricing Matrix
Nairobi's processing cluster anchors East African UHT capacity expansion, with hybrid aseptic-pouch line investments compressing per-unit production costs and transmitting downstream pricing power to informal retail channels previously excluded from branded participation.
Pricing Analysis
Long-term offtake contracts between Nigerian processors and school nutrition programs anchor volume commitments that stabilize input procurement against skim milk powder import quota volatility. Three-tier pricing structure across premium fortified, standard chocolate, and economy pouch levels separates health-conscious Gulf consumers from price-sensitive East African households. Pricing pressure stems from Saudi Arabia's SFDA sugar-labeling transparency mandates forcing reformulation investments. Institutional buyers in South African school feeding programs exhibit lowest price sensitivity; informal traders in Kenyan open-air markets show highest.
Supply Chain Analysis
Contract manufacturing concentration sits with Tetra Pak's regional filling equipment partners and Egyptian hybrid line specialists serving mid-scale Kenyan and Nigerian processors. Geographic supply concentration centers on Saudi Arabia, South Africa, and Nigeria as primary production bases. Raw material dependencies include skim milk powder imports, cocoa flavoring systems, and vitamin premix fortification inputs. Single-source vulnerability runs through cold-chain logistics partnerships guaranteeing shelf-life compliance. Distribution runs through captive networks in Gulf markets and fragmented traditional trade in sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as cold-chain infrastructure penetration enables branded flavored milk displacement of ambient-stable alternatives in Nigeria's Lagos-Ibadan corridor and comparable urban corridors.
For Market Incumbents: Entrench through captive distribution network density investments sustaining temperature-controlled delivery coverage that competitors cannot replicate across Saudi Arabia, Bahrain, and Jordan. Prioritize backward integration into skim milk powder processing to mitigate NAFDAC import quota exposure. Secure pediatric formulation certifications ahead of divergent national fortification standard harmonization through AfCFTA implementation bodies. For New Entrants and Emerging Players: Pursue white-space opportunity in Kenyan informal retail through hybrid aseptic-pouch production lines that undercut Tetra Pak carton economics. Target health-conscious consumer segments in Saudi Arabia and UAE with reduced-sugar vanilla fortification positioned above mass-market chocolate alternatives. Deploy direct-to-traditional-trade distribution partnerships bypassing supermarket margin capture. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors logistics-intensive operators with cold-chain service revenue streams and formulation capabilities navigating multi-jurisdictional fortification mandates. Long-term viability hinges on portfolio diversification into reduced-sugar fortified variants and regional processing consolidation ahead of AfCFTA tariff-phase commitments. Monitor NAFDAC local content requirement enforcement and SFDA labeling standard expansion as inflection indicators for input cost and reformulation investment trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Aseptic-Pouch Line Deployment | Reduces per-unit packaging costs by 30-40% for Kenyan and Nigerian mid-scale processors serving informal retail. |
| Captive Cold-Chain Network Expansion | Almarai's temperature-controlled delivery density across Saudi Arabia, Bahrain, and Jordan creates unmatched shelf-life compliance. |
| Reduced-Sugar Vanilla Fortification | SFDA sugar-labeling transparency mandates open premium positioning above chocolate-dominant mass market in Gulf retail. |
| School Nutrition Procurement Lock-In | South Africa's Department of Health feeding program specifications directly determine volume allocation for participating processors. |
| Backward Integration into Skim Milk Powder | Mitigates NAFDAC import quota volatility and local content requirement compliance complexity for Nigerian operations. |
Research Methodology
A spread of perspectives from dairy processing executives, cold-chain logistics operators, school nutrition procurement officers, and retail channel managers converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through Saudi SFDA regulatory filings, NAFDAC import quota records, South African Department of Health procurement specifications, and Tetra Pak packaging equipment deployment data. Bottom-up facility capacity assessments and top-down consumption pattern triangulation anchored segmentation-level outputs.
Demand-supply-balance framing modeled flavored milk consumption across product type, packaging format, distribution channel, and end-user segments throughout the forecast period. CAGRs derived from trajectory fitting to historical procurement data and projected cold-chain infrastructure expansion. Industry-specific inputs included school nutrition program budget allocations, electricity intermittency indices affecting refrigerated distribution reach, and fortification premix cost curves.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity prices, currency volatility affecting skim milk powder import costs, or Gulf Cooperation Council fiscal consolidation would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and infrastructure investment cadence. Quarterly review of NAFDAC enforcement patterns, SFDA labeling standard expansion, and AfCFTA tariff-phase announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Low Fat Butter Market
Dairy Products
Japan Dairy Market
Dairy Products
India Milk Protein Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Ghee Market
Dairy Products
Organic Milk Powder Market