
 UAE Data Center Construction Market | 2026-2036
UAE Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Data Center Construction Market Insights
The UAE is fragmenting across multiple concurrent mega-projects as sovereign wealth-backed zones compete for hyperscale tenant commitments. Jacobs Engineering Group leverages its program management footprint across Dubai South and Masdar City to sustain large-scale delivery timelines. Arup Gulf Limited anchors specialized MEP and resilience engineering for Tier III and Tier IV certifications. AECOM competes on integrated design-build contracts that compress commissioning schedules for cloud operators entering the Emirates.
Data center construction encompasses the civil, mechanical, electrical, and structural build-out of mission-critical facilities engineered to maintain 99.999% uptime with power densities exceeding 30 kW per rack. Primary purpose centers on creating controlled environments with N+1 or 2N redundancy for compute, storage, and networking infrastructure. Hyperscale deployments dominate capital allocation as cloud service providers demand campuses exceeding 100 MW of IT capacity, while modular technology segments attract enterprises seeking phased expansion with factory-integrated power and cooling. Tier III classifications capture the largest project volume given their balance of redundancy cost and operational assurance for financial and telecommunications buyers.
MOHAP facility licensing, TDRA telecommunications infrastructure codes, and Emirates Authority for Standardization and Metrology cooling efficiency benchmarks collectively shape design specifications and commissioning protocols. Compliance with these frameworks determines market access for contractors and influences long-term operational expenditure profiles for facility owners. Stakeholders must monitor evolving carbon intensity thresholds as the Emirates advances its net-zero pathway and hyperscale tenants embed sustainability requirements into procurement criteria.
Market Dynamics
Hyperscale cloud operators are compressing commissioning timelines from 24 months to 14 months, forcing contractors to restructure delivery models around parallel-track MEP installation and pre-fabricated structural components.
Growth Catalysts
- MOHAP facility licensing:New healthcare data localization mandates require dedicated Tier III infrastructure, pulling hospital systems and health-tech platforms into purpose-built colocation.
- Liquid cooling adoption:Power densities exceeding 50 kW per rack are rendering air-cooled designs obsolete, creating replacement demand across legacy facilities in Dubai Internet City.
- Masdar City sustainability clustering:Carbon-neutral campus requirements are concentrating hyperscale investment in Abu Dhabi, leveraging solar PPA structures and district cooling integration.
Market Restraints
- Copper and electrical steel volatility:Transformer and busbar input costs swing 15-30% on commodity cycles, eroding fixed-price EPC margins.
- Specialized MEP contractor concentration:Tier IV certification capability sits with fewer than six regional firms, creating bid-queue bottlenecks for 100 MW-plus projects.
- TDRA telecommunications code friction:Cross-connect and fiber infrastructure permitting adds 90-120 days to commissioning schedules.
Strategic Opportunities
- Ras Al Khaimah and Fujairah expansion:Secondary emirates offer land cost arbitrage and submarine cable landing proximity for latency-sensitive financial workloads.
- Modular factory integration:Pre-fabricated power modules and cooling skids are compressing on-site labor requirements by 40%.
- Emirates Authority for Standardization cooling efficiency benchmarks:Stricter PUE thresholds are retrofitting older facilities and accelerating replacement cycles.
Industry Challenges
- Tier IV commissioning engineer scarcity:Uptime Institute certification requires specialized commissioning protocols that fewer than 200 regional technicians can execute.
- Legacy facility integration complexity:Brownfield expansions must maintain 99.999% uptime during live MEP cutovers, constraining construction windows to maintenance periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Data Center Construction Market |
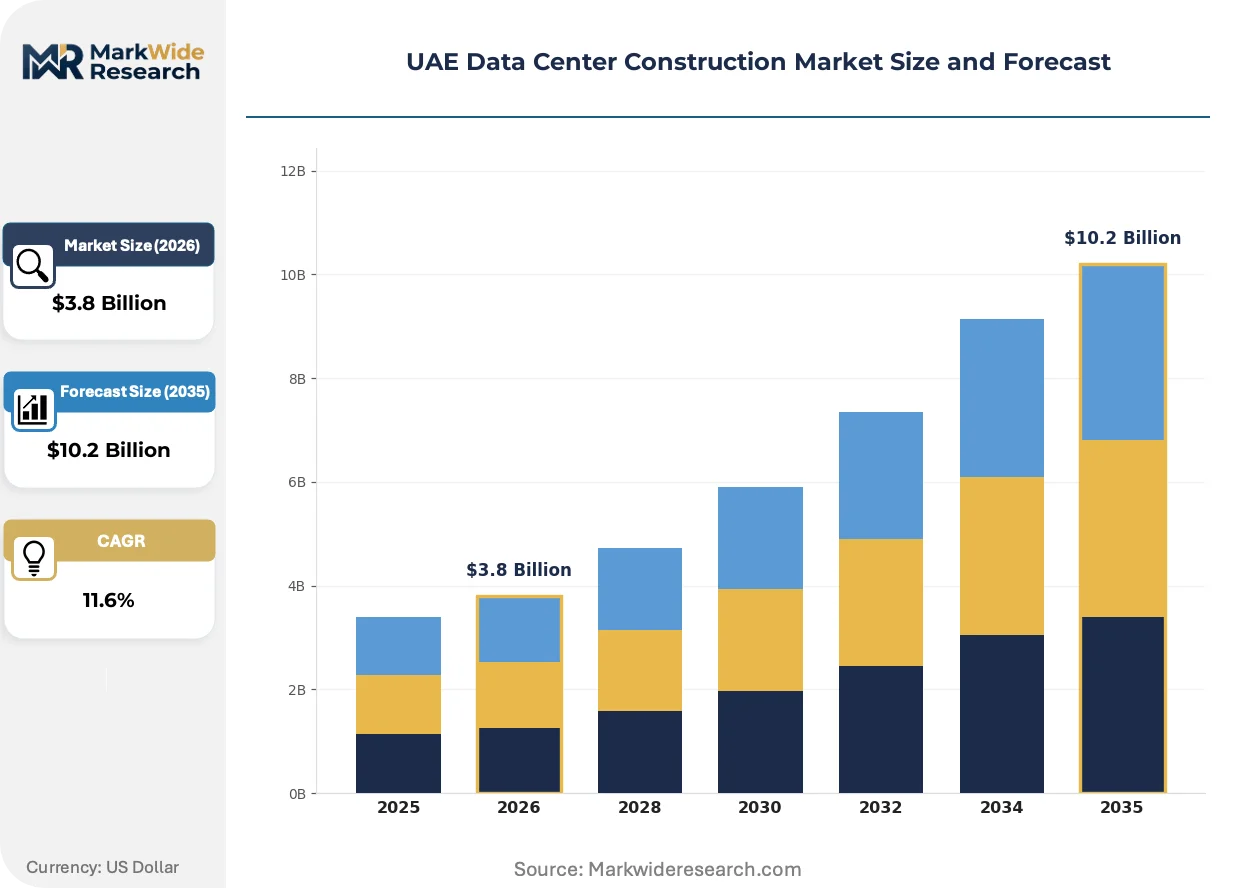
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tier 1, Tier 2, Tier 3, Tier 4 Technology: Modular, Containerized, Hyperscale, Traditional End User: Telecommunications, Cloud Service Providers, Enterprises, Government Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Jacobs Engineering Group, Arup Gulf Limited, AECOM, Turner and Townsend, Aurecon Group Pty Ltd, Laing O'Rourke, McLaren Construction Group PLC, AtkinsRéalis, Gilbane, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Data Center Construction Market Trends and Innovations
Cooling architecture and power delivery systems are converging around factory-integrated modular designs that compress on-site construction risk. This shift is redefining contractor specialization requirements and procurement evaluation criteria across the Emirates.
Direct liquid cooling is hybridizing air and water thermal management for GPU-intensive AI training clusters. Hyperscale operators in Dubai South are specifying cold plate manifolds for 30% of new rack positions. This technology is hybridizing traditional CRAH redundancy with in-row coolant distribution, reducing mechanical infrastructure footprint by 25%.
TDRA telecommunications infrastructure codes are mandating diverse fiber entry points and meet-me-room security protocols for all new facilities. These requirements are adding 8-12% to structural costs but enabling multi-tenant revenue models. Financial services and cloud exchange segments are absorbing these premiums to satisfy cross-border data sovereignty requirements.
Enterprise buyers are consolidating vendor relationships under single-source design-build contracts rather than fragmented EPC procurement. This pattern is displacing traditional general contractor bidding in favor of integrated program managers with in-house MEP capability. Abu Dhabi government and sovereign wealth-backed developments are driving this consolidation most aggressively.
UAE Data Center Construction Market Segmentation
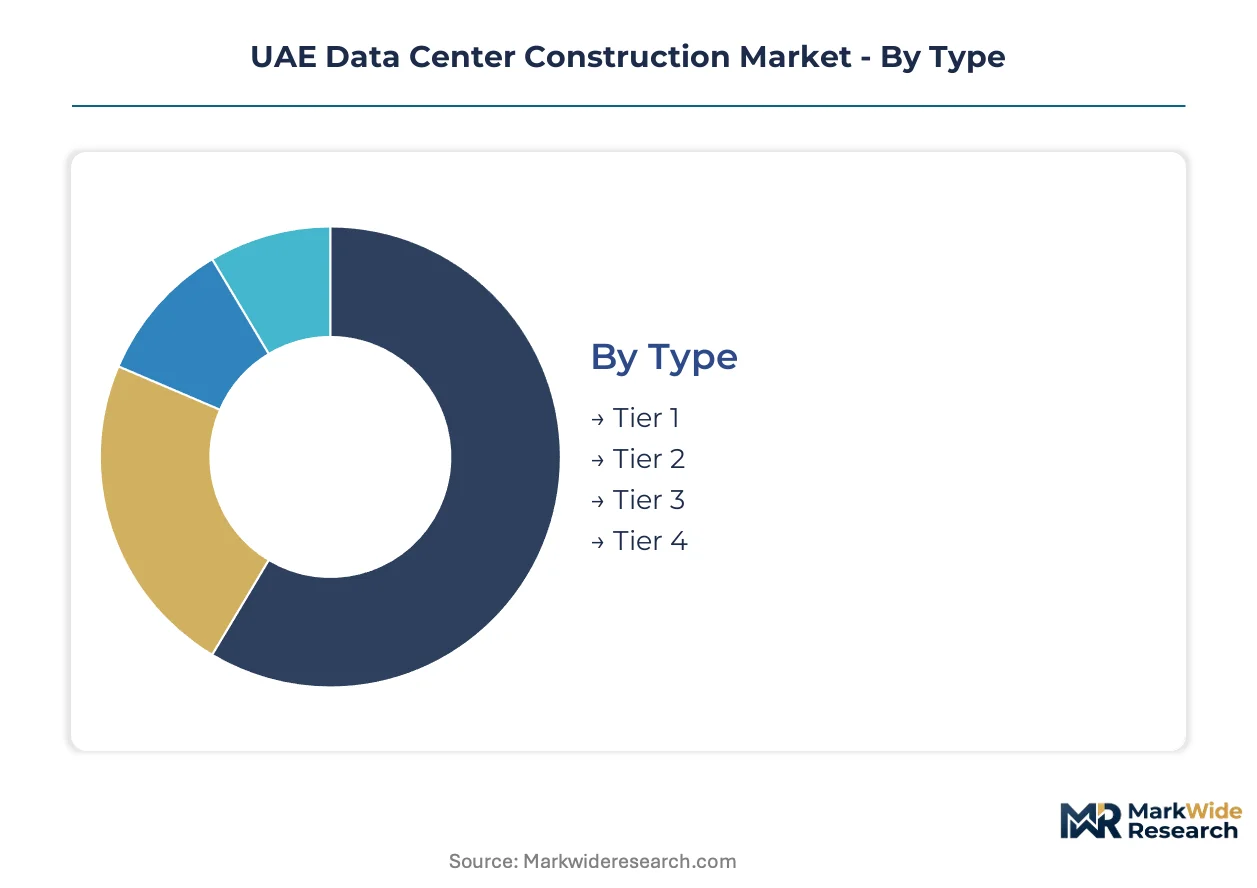
Segmentation in UAE data center construction reveals how certification tiers, power densities, and deployment architectures align with distinct procurement budgets and operational risk profiles across the Emirates. Each dimension carries different after-sales service intensity, from Tier IV facilities requiring dedicated commissioning engineers to modular systems demanding remote monitoring support.
Type:
After-sales service intensity escalates dramatically with redundancy tier, as Tier IV facilities require 24/7 specialized maintenance contracts and Uptime Institute recertification protocols that Tier I operators rarely purchase.
- Tier 3:N+1 redundancy configurations balance capital efficiency with operational assurance for financial services and healthcare workloads. Dubai Internet City and Abu Dhabi Global Market host the majority of new Tier III builds as cloud operators seek cost-optimized uptime guarantees. MOHAP facility licensing mandates are pulling hospital systems into certified colocation, tightening commissioning windows.
- Tier 4:2N+1 fault-tolerant designs with physically isolated distribution paths command premium construction costs for sovereign wealth and hyperscale anchor tenants. Fewer than six regional contractors hold active Tier IV certification capability, creating bid-queue bottlenecks for 100 MW-plus campus developments in Masdar City.
- Tier 1:Basic infrastructure with single distribution paths serves non-critical enterprise storage and development environments with minimal redundancy investment.
- Tier 2:Partial redundancy configurations occupy a narrowing middle market as buyers consolidate toward Tier III standards or accept Tier I economics for disaster recovery sites.
Tier III holds the largest share; momentum sits with Tier IV as hyperscale operators embed fault tolerance into procurement criteria.
Technology:
Cost tier separation between factory-integrated modular systems and site-built traditional construction is compressing delivery timelines and reshaping contractor specialization requirements.
- Hyperscale:Purpose-built campuses exceeding 100 MW of IT capacity feature dedicated substations and centralized cooling plants engineered for single-tenant cloud operators. Dubai South and Khalifa Industrial Zone are concentrating these deployments as AWS, Microsoft, and Google anchor regional availability zones.
- Modular:Pre-fabricated power modules and cooling skids reduce on-site labor requirements by 40% while enabling phased capacity expansion for enterprises with uncertain growth trajectories. Ras Al Khaimah and Fujairah are attracting modular deployments seeking land cost arbitrage.
- Containerized:ISO-standard enclosures with integrated power and cooling serve edge computing and temporary capacity needs with rapid deployment cycles.
- Traditional:Stick-built construction with field-integrated MEP systems retains relevance for complex brownfield expansions requiring custom structural adaptation.
Hyperscale captures the largest share; containerized systems are gaining share fastest among edge computing deployments.
End User:
Customer type determines procurement complexity, with cloud service providers consolidating vendor relationships under single-source design-build contracts while government buyers fragment across sovereign wealth-backed zones.
- Cloud Service Providers:Hyperscale operators demand integrated program management with in-house MEP capability, compressing commissioning schedules from 24 months to 14 months through parallel-track installation. These buyers are displacing traditional general contractor bidding across Dubai South developments.
- Telecommunications:Etisalat and du are expanding Tier III infrastructure to support 5G core network virtualization and edge computing nodes, with TDRA telecommunications infrastructure codes mandating diverse fiber entry points.
- Enterprises:Financial services and healthcare buyers are consolidating toward colocation as MOHAP facility licensing tightens operational standards for self-managed facilities.
- Government:Abu Dhabi government and sovereign wealth-backed developments are driving integrated procurement consolidation most aggressively, favoring contractors with program management footprints across multiple zones.
Cloud service providers hold the largest share; government segment is climbing the fastest on sovereign digital infrastructure investment.
Power Rating:
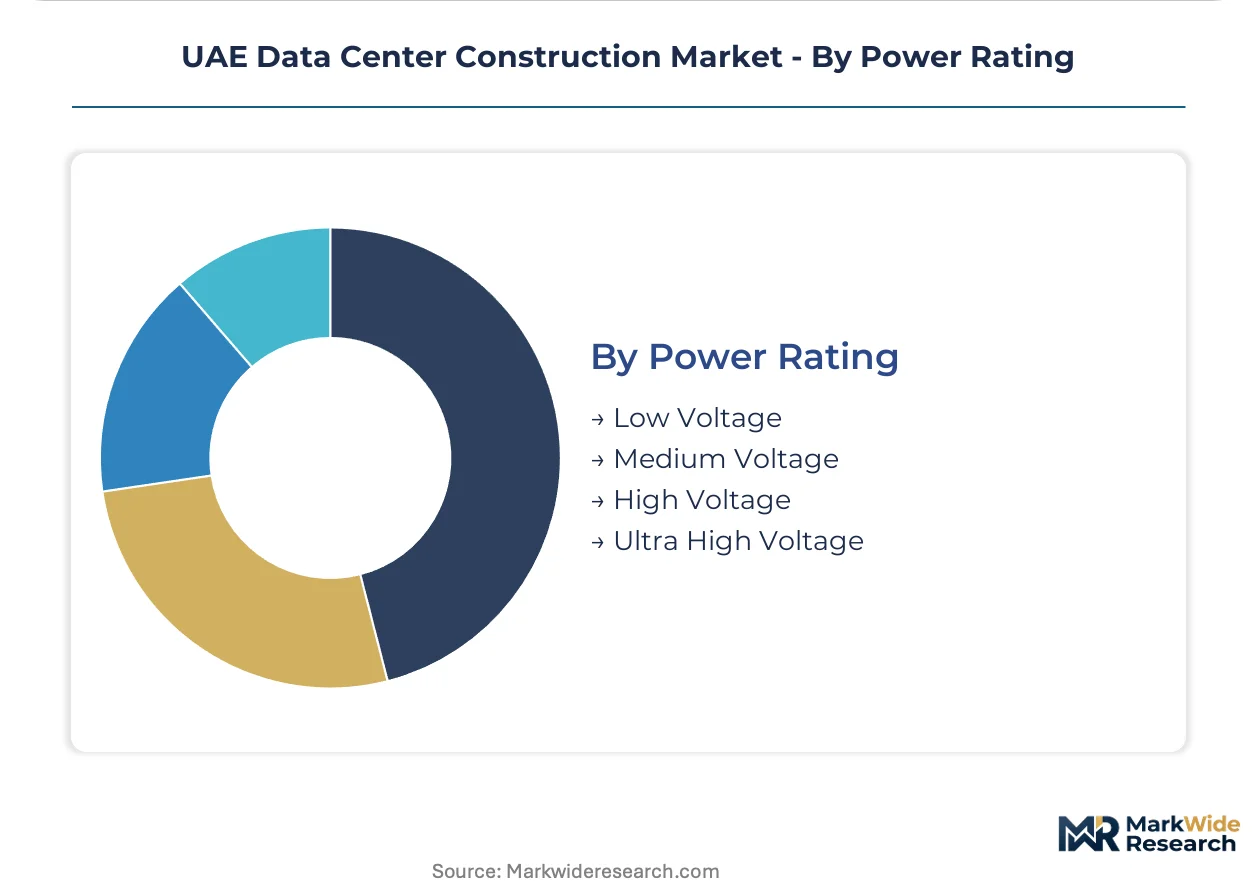
Application-criticality separates voltage tiers, with high and ultra-high voltage infrastructure serving AI training clusters above 50 kW per rack while low voltage systems support legacy enterprise workloads.
- Medium Voltage:11-33 kV distribution architectures dominate new hyperscale campuses in Dubai and Abu Dhabi, balancing transmission efficiency with switchgear capital costs. These systems integrate with DEWA and ADDC grid interconnection standards for 100 MW-plus developments.
- High Voltage:66-132 kV substations serve density-intensive AI training facilities where power requirements exceed 30 kW per rack, with liquid cooling adoption rendering air-cooled designs obsolete.
- Low Voltage:400V-1 kV systems persist in legacy facility retrofits and small-scale enterprise deployments with conventional rack densities.
- Ultra High Voltage:220 kV and above transmission infrastructure anchors regional mega-campus developments with dedicated grid connections.
Medium voltage holds the largest share; high voltage is expanding most quickly on AI workload concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction demand concentrates differently across Emirates, with Dubai and Abu Dhabi commanding hyperscale campuses while secondary emirates compete on land cost and cable landing proximity for latency-sensitive workloads.
Dubai
Hyperscale cloud operators anchor mega-campus developments in Dubai South, drawn by DEWA grid interconnection standards and integrated free zone incentives. MOHAP facility licensing mandates pull hospital systems into certified colocation, tightening commissioning windows for Tier III infrastructure. Dubai Internet City hosts legacy facility retrofits as liquid cooling adoption renders air-cooled designs obsolete.
Abu Dhabi
Masdar City sustainability clustering concentrates investment through carbon-neutral campus requirements and solar PPA structures. ADDC grid standards support 100 MW-plus developments with dedicated substations and district cooling integration. Sovereign wealth-backed zones compete aggressively for hyperscale tenant commitments through integrated program management procurement.
Sharjah
Industrial zone expansion offers land cost arbitrage for modular deployments seeking phased capacity growth. Emirates Authority for Standardization cooling efficiency benchmarks shape design specifications for facilities targeting enterprise buyers. Sharjah Research Technology and Innovation Park anchors specialized MEP contractor presence for mid-scale developments.
Northern Emirates
Ras Al Khaimah and Fujairah leverage submarine cable landing proximity for financial workloads demanding low-latency connectivity. Secondary emirate positioning attracts modular factory-integrated systems reducing on-site labor requirements. TDRA telecommunications infrastructure codes add permitting complexity but enable multi-tenant revenue models for cross-border data sovereignty compliance.
UAE Data Center Construction Market Competitive Landscape
Capability concentration sits with specialized MEP and resilience engineering firms; scale advantage sits with integrated program managers commanding multi-zone delivery footprints. Fewer than six regional contractors hold active Tier IV certification capability, creating bid-queue bottlenecks for fault-tolerant campus developments. Strategic archetypes separate Tier III/Tier IV certification specialists from design-build integrators and sovereign-backed zone developers. Dominant competitive moves center on parallel-track MEP installation methodologies and pre-fabricated structural component sourcing.
Among engineering-led specialists, Jacobs Engineering Group, Arup Gulf Limited, and AECOM occupy distinct positioning vectors within the capability hierarchy. Jacobs exemplifies program management scale across Dubai South and Masdar City mega-projects. Arup represents specialized MEP and Tier III/Tier IV certification anchoring. AECOM sits within integrated design-build contracting, compressing commissioning schedules for cloud operators entering the Emirates.
| Leading Market Players |
|---|
| Jacobs Engineering Group |
| Arup Gulf Limited |
| AECOM |
| Turner and Townsend |
| Aurecon Group Pty Ltd |
| Laing O'Rourke |
| McLaren Construction Group PLC |
| AtkinsRéalis |
| Gilbane |
| Others |
Pricing and Supply Chain Analysis
Dubai South contractor clustering concentrates specialized MEP capacity, amplifying pricing power for Tier IV certification holders while compressing margins for generalist firms competing on Tier III volume. This geographic concentration of technical capability feeds directly into bid-queue premiums and fixed-price EPC risk allocation across the Emirates.
Pricing Analysis
Price spreads between Abu Dhabi and Ras Al Khaimah run 18-25% for equivalent Tier III specifications, reflecting land cost arbitrage and DEWA versus SEWA grid interconnection standards. Three-tier pricing structure across Tier IV fault-tolerant, Tier III N+1, and Tier II partial redundancy levels separates sovereign wealth anchor tenants from cost-optimized cloud operators. Cost compression in Tier III segments is intensifying because copper and electrical steel volatility swings transformer input costs 15-30%. Cloud service providers exhibit lowest price sensitivity, absorbing premiums for 14-month commissioning compression; enterprise colocation buyers in Sharjah demonstrate highest sensitivity, favoring phased modular expansion.
Supply Chain Analysis
Pre-fabricated power module manufacturing concentrates in Germany, China, and South Korea, with Siemens, Schneider Electric, and Huawei dominating factory-integrated skid supply for UAE hyperscale deployments. Data center construction draws from copper rod and electrical steel sheet, precision cooling compressors, and fiber optic cable assemblies as critical input tiers. Single-source vulnerability sits with liquid cooling cold plate manifolds, where fewer than three global suppliers meet 50 kW-plus rack density specifications. Distribution runs through EPC contractors with in-house MEP capability, displacing fragmented general contractor bidding across Dubai and Abu Dhabi mega-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning and certification services represent the fastest-expanding recurring-revenue layer, as Tier IV facilities demand 24/7 specialized maintenance contracts and Uptime Institute recertification protocols that outpace hardware installation cycles.
For Market Incumbents: Pre-empt modular technology displacement by acquiring factory-integration capabilities or exclusive distribution partnerships with German and Chinese power skid manufacturers. Lock in Tier IV commissioning engineer pipelines through technical training joint ventures with regional polytechnics, defending against scarcity-driven wage inflation. Cement program management relationships across sovereign wealth-backed zones before single-source procurement consolidation hardens. For New Entrants and Emerging Players: Pursue Tier IV certification capability as the most penetrable competitive moat, given fewer than six regional contractors currently hold active credentials. Target Ras Al Khaimah and Fujairah for modular deployments seeking land cost arbitrage and submarine cable landing proximity. Lead with liquid cooling MEP specialization as GPU-intensive AI training clusters render air-cooled designs obsolete across legacy Dubai Internet City facilities. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-services compounding play because hyperscale tenant commitments generate 15-20 year lease revenue visibility with inflation-linked escalators. Acquisition target archetype: specialized MEP contractors with active Tier III/Tier IV certification and established relationships with DEWA or ADDC grid interconnection teams. Monitor hyperscale capex announcement velocity as the inflection signal for construction backlog expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel-Track MEP Installation | Compresses commissioning from 24 months to 14 months for AWS and Microsoft campus commitments. |
| Pre-Fabricated Structural Component Sourcing | Reduces on-site labor requirements 40% while mitigating copper volatility exposure through fixed-price factory contracts. |
| Tier IV Certification Investment | Creates bid-queue scarcity premium as fewer than six regional contractors meet Uptime Institute fault-tolerant standards. |
| Liquid Cooling Capability Acquisition | Captures GPU-intensive AI training demand as power densities exceed 50 kW per rack in Dubai South. |
| Sovereign Wealth Zone Partnership | Locks in integrated program management procurement across Masdar City and Khalifa Industrial Zone developments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center program managers, MEP commissioning engineers, DEWA grid interconnection officers, and hyperscale cloud procurement leads; and secondary validation through DEWA and ADDC regulatory filings, Uptime Institute certification databases, EPC contractor project announcements, and Emirates Authority for Standardization cooling efficiency benchmarks. Bottom-up project pipeline aggregation triangulated against top-down capital expenditure tracking across cloud operator regional availability zone commitments.
Forecast inputs considered certification tier adoption curves, power density migration from air-cooled to liquid cooling architectures, and sovereign wealth infrastructure allocation patterns across the projection horizon. Segmentation dimensions modeled include redundancy tier, deployment technology, end-user vertical, power rating architecture, and emirate-level geographic clustering. CAGRs derived from capacity-weighted average of announced mega-project timelines and historical commissioning velocity benchmarks.
Sensitivities concentrate around hyperscale tenant commitment delays, copper and electrical steel commodity cycles, and TDRA telecommunications code permitting friction. Forecasts reflect assumptions on modular technology penetration rates and Tier IV certification pipeline expansion. Quarterly review of hyperscale capex announcements, MOHAP licensing issuance velocity, and specialized MEP contractor hiring activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
APAC Green Data Center Market