
 Automatic Number Plate Recognition (ANPR) Market | 2026-2036
Automatic Number Plate Recognition (ANPR) Market Size, Share, and Industry Trends Forecast 2026-2036
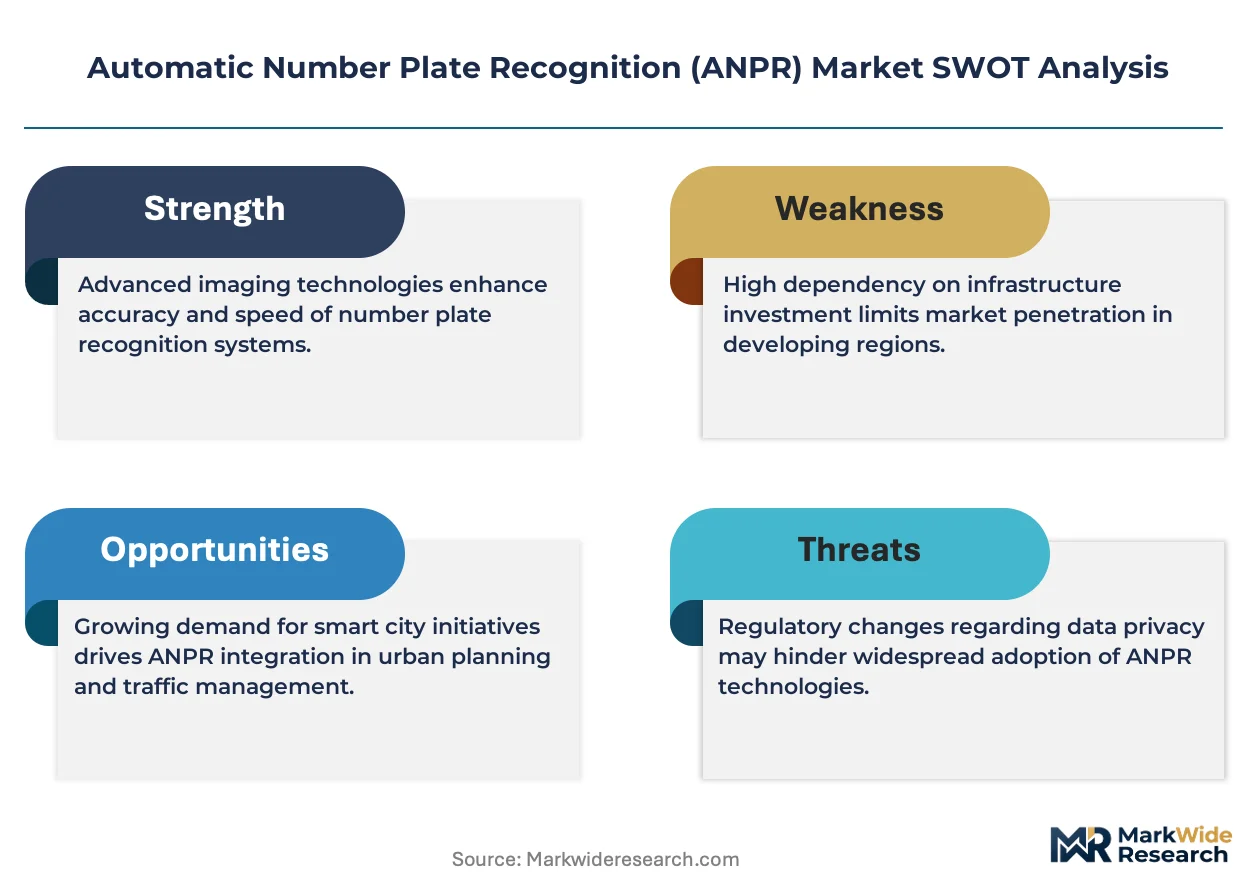
Automatic Number Plate Recognition (ANPR) Market Analysis
The capital-intensity divergence between full-stack hardware manufacturers and pure-play software vendors is redrawing competitive boundaries in the ANPR landscape. Kapsch TrafficCom AG leverages its integrated tolling and traffic management portfolio to sustain large-scale deployment contracts across European transport corridors. Hikvision Digital Technology Co., Ltd. anchors its position through captive manufacturing of specialized cameras and edge processors, while Genetec Inc. differentiates via open-architecture software that navigates multi-vendor environments.
Automatic Number Plate Recognition comprises electro-optical systems that capture vehicle license plate images using infrared or visible-spectrum cameras operating at shutter speeds below 1/1000 second, then apply optical character recognition algorithms to extract alphanumeric data for real-time identification and database matching. The technology serves primarily to automate vehicle tracking, access control, and regulatory enforcement across transportation and security infrastructure. Camera-based systems dominate current revenue as municipalities prioritize fixed-site installations with all-weather imaging capability, while software packages represent the fastest-expanding margin pool as customers decouple analytics from hardware procurement. Cloud services adoption is accelerating among parking operators and private enterprises seeking subscription-based scalability without on-premise server maintenance.
The Federal Communications Commission regulates wireless spectrum allocation for mobile ANPR units in the United States, while the European Union's General Data Protection Law and AI Act impose strict limits on biometric data retention and algorithmic transparency for traffic monitoring systems. The UK's Surveillance Camera Commissioner and the Information Commissioner's Office jointly enforce proportionality standards that shape product design requirements for vendors seeking public sector contracts. Stakeholders must monitor evolving data governance frameworks to determine whether compliance investments or geographic portfolio rebalancing offers the more sustainable path to margin protection.
Market Dynamics
Edge computing architectures are collapsing the traditional hardware-software boundary in ANPR deployments, forcing vendors to restructure pricing models and service delivery around real-time inference capabilities rather than capital equipment sales.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European municipalities face binding algorithmic transparency requirements for traffic monitoring, accelerating replacement cycles for opaque legacy systems with auditable AI-powered alternatives.
- Smart city infrastructure budgets:United States Department of Transportation grants channel federal funds toward integrated mobility platforms in cities including Los Angeles, Chicago, and Houston, embedding ANPR into multimodal corridor management.
- Infrared camera miniaturization:Advances in solid-state sensor fabrication reduce unit costs for low-light imaging modules, expanding addressable markets to smaller parking operators and private campus security teams.
Market Restraints
- Semiconductor supply concentration:Specialized image signal processors for ANPR edge devices depend on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, exposing procurement timelines to geopolitical disruption.
- GDPR data retention limits:European Union restrictions on biometric storage duration compress the useful life of cloud-archived plate databases, forcing customers toward higher-cost on-premise retention architectures.
- License plate standardization variance:Non-uniform plate dimensions, reflective materials, and character fonts across Indian states, Canadian provinces, and Middle Eastern jurisdictions inflate software training costs for multi-territory deployments.
Strategic Opportunities
- India's National Highways Authority toll modernization:FASTag integration creates demand for hybrid RFID-optical verification systems at 600+ toll plazas undergoing digitization through 2027.
- Electric vehicle charging access control:ANPR-linked payment authentication for curbside and garage charging points represents an emerging application as EV penetration rises in Germany, Norway, and California.
- 5G private network deployment:Ultra-reliable low-latency connectivity enables mobile ANPR units to stream uncompressed 4K video for centralized processing, opening subscription-based managed service models for mid-size municipal fleets.
Industry Challenges
- Edge AI firmware engineering scarcity:Vendors compete for embedded systems talent capable of optimizing neural network inference on thermal-constrained camera SoCs, inflating R&D compensation costs.
- Multi-vendor system integration complexity:Open-architecture software procurement from Genetec and Milestone requires custom middleware development to synchronize third-party cameras with legacy access control databases.
- FCC equipment authorization timelines:New radio configurations for wireless ANPR backhaul face 12-18 month certification queues, delaying product launches for US-focused hardware manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Number Plate Recognition (ANPR) Market |
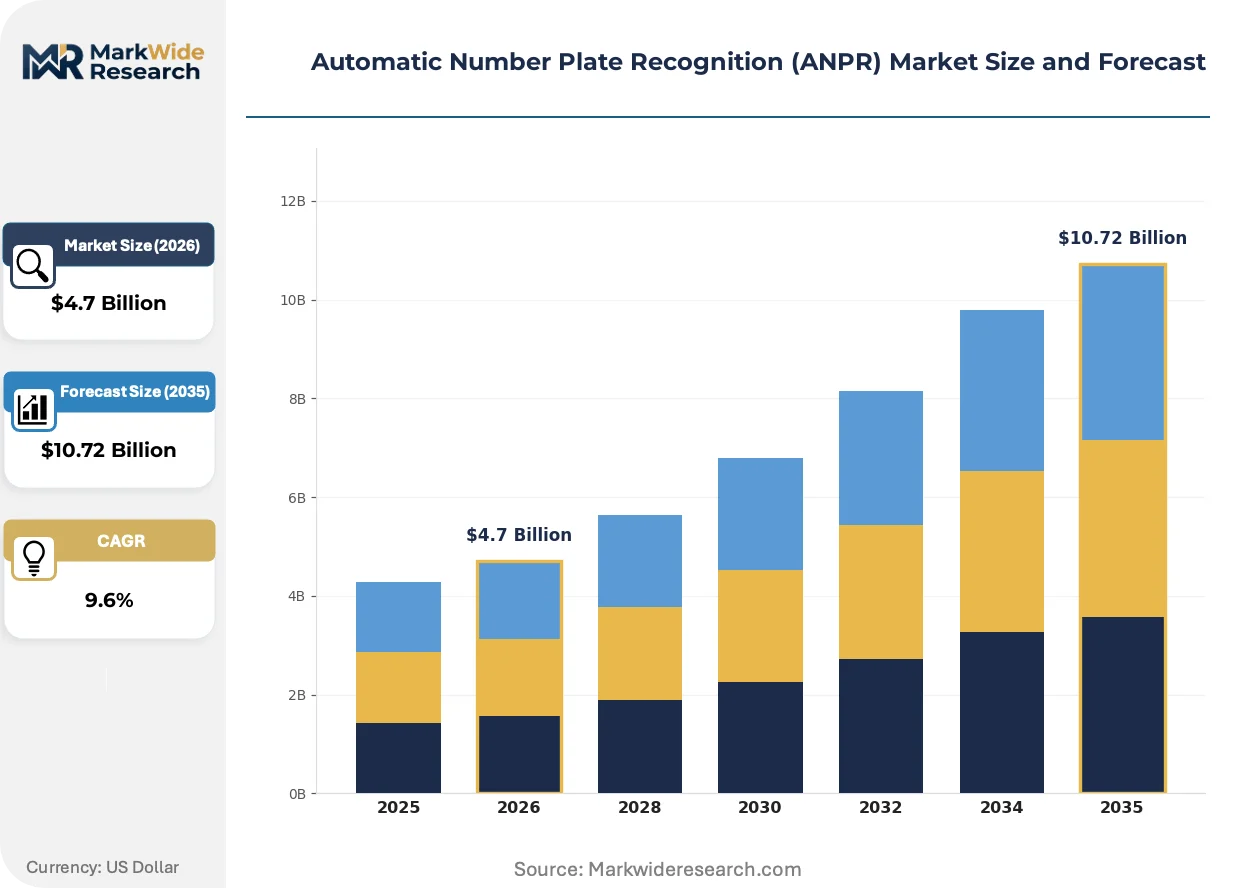
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera-Based Systems, Sensor Solutions, Software Packages, Cloud Services Application: Toll Collection, Traffic Management, Law Enforcement, Parking Control End User: Government, Transportation Agencies, Parking Operators, Private Enterprises Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Siemens AG, Kapsch TrafficCom AG, Hikvision Digital Technology Co., Ltd., Genetec Inc., Jenoptik Group, Axis Communications AB, Nedap N.V., Q-Free ASA, Conduent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Number Plate Recognition (ANPR) Market Emerging Trajectories
Deep learning model compression and federated learning protocols are redistributing computational workloads between camera edge nodes and centralized servers, collapsing the traditional performance-cost tradeoff that favored heavy on-premise infrastructure.
Transformer-based optical character recognition is fragmenting the historical dominance of convolutional neural networks in plate reading accuracy. Parking operators in the United Kingdom and Netherlands are piloting these architectures for degraded plate reconstruction at extreme angles. The technology is fragmenting vendor roadmaps, forcing incumbents to retrain engineering teams on attention mechanisms or risk accuracy deficits in next-generation tenders.
The EU AI Act's risk classification system for biometric identification in public spaces imposes conformity assessment obligations on ANPR vendors serving law enforcement. Manufacturers must document training data provenance and model performance across demographic subgroups. European public procurement frameworks now embed these requirements as mandatory technical specifications, filtering non-compliant suppliers from national police and transport authority contracts.
Municipal buyers are unbundling hardware procurement from analytics subscriptions, treating camera infrastructure as depreciable capital while purchasing recognition software through annual SaaS licenses. This bifurcation is most pronounced in Germany and France, where public accounting rules favor operational expenditure classification for cloud-hosted identification services. Channel partners including systems integrators and IT resellers are capturing margin previously retained by full-stack manufacturers.
Automatic Number Plate Recognition (ANPR) Market Segmentation
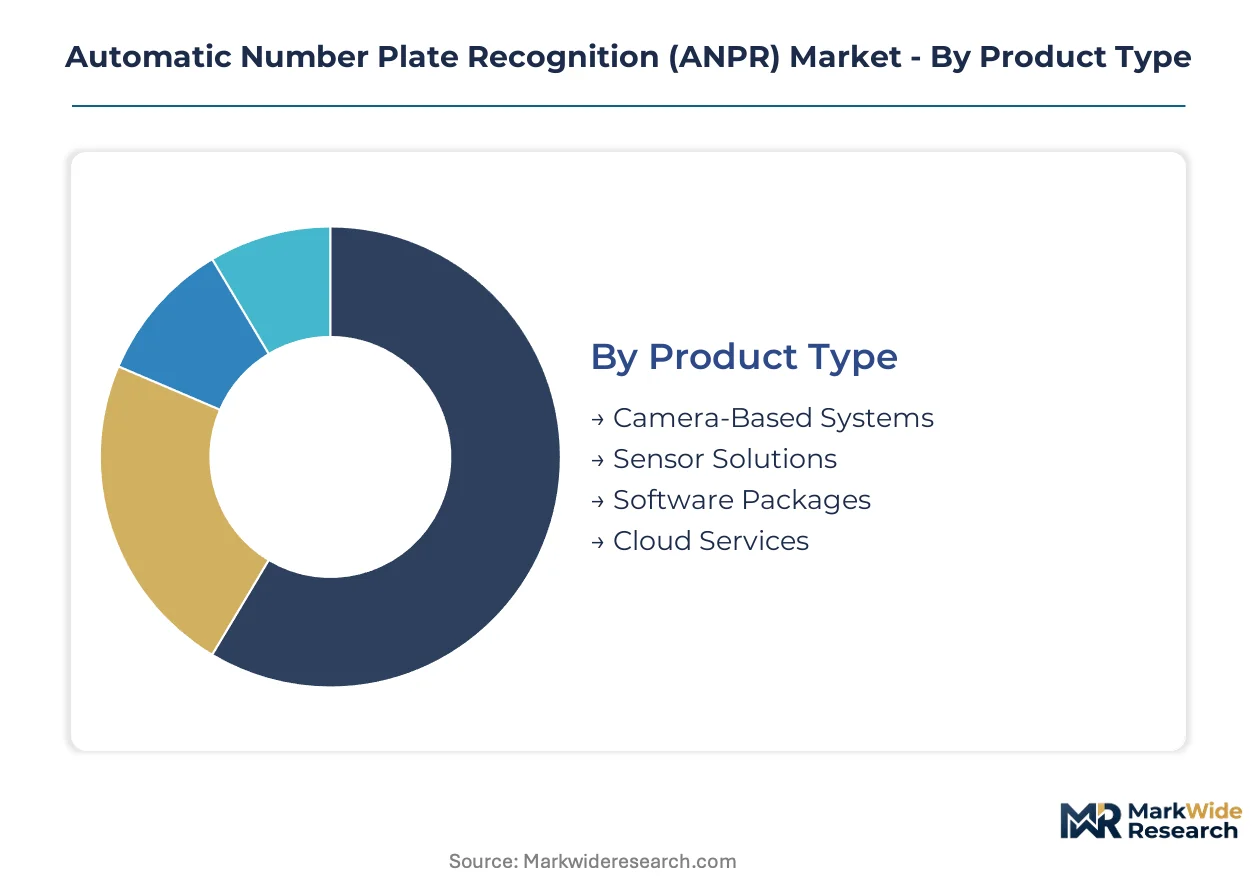
ANPR procurement patterns diverge sharply between public infrastructure mandates and private operational budgets. Regulatory compliance requirements in Europe and procurement flexibility in North America reshape how vendors structure product portfolios across hardware, software, and service tiers.
Product Type:
GDPR algorithmic transparency rules and FCC equipment authorization timelines create divergent compliance burdens across hardware and software categories.
- Camera-Based Systems:Infrared and visible-spectrum cameras with shutter speeds below 1/1000 second form the hardware backbone of fixed-site installations. United States municipalities in Los Angeles, Chicago, and Houston prioritize all-weather imaging capability for multimodal corridor management under Department of Transportation grant programs.
- Software Packages:Optical character recognition algorithms extract alphanumeric plate data for real-time database matching. German and French public accounting rules favor SaaS licensing models that classify analytics as operational expenditure rather than capital equipment.
- Sensor Solutions:Solid-state infrared modules and specialized image signal processors enable low-light capture without external illumination.
- Cloud Services:Subscription-based scalability eliminates on-premise server maintenance for parking operators.
Established volume favors Camera-Based Systems; emerging adoption favors Cloud Services.
Application:
End-use economics range from revenue-generating toll systems to cost-center enforcement operations with distinct procurement cycles.
- Traffic Management:Integrated mobility platforms embed ANPR into corridor optimization across smart city infrastructure. United Kingdom and Netherlands pilots deploy transformer-based OCR for degraded plate reconstruction at extreme angles.
- Law Enforcement:Real-time identification and database matching supports vehicle tracking and regulatory enforcement. EU AI Act risk classification imposes conformity assessment obligations and training data documentation requirements on vendors serving European police authorities.
- Toll Collection:India's National Highways Authority FASTag integration drives hybrid RFID-optical verification demand at 600-plus toll plazas.
- Parking Control:Access automation and payment authentication for curbside and garage facilities.
Traffic Management captures the largest installed base; Law Enforcement faces the steepest compliance-driven replacement cycle.
End User:
Customer procurement authority determines contract structure, with government tenders favoring capital equipment and private buyers preferring subscription models.
- Government:National and local authorities mandate fixed-site installations with multi-year depreciation schedules. UK Surveillance Camera Commissioner and Information Commissioner's Office joint enforcement shapes product design requirements for public sector contracts.
- Transportation Agencies:Corridor operators integrate ANPR into tolling and traffic flow optimization across European transport corridors.
- Parking Operators:Commercial garage and curbside facility managers prioritize subscription-based scalability.
- Private Enterprises:Campus security and logistics facilities deploy access control with customized integration requirements.
Government and Transportation Agencies dominate capital expenditure; Parking Operators are expanding most quickly through SaaS adoption.
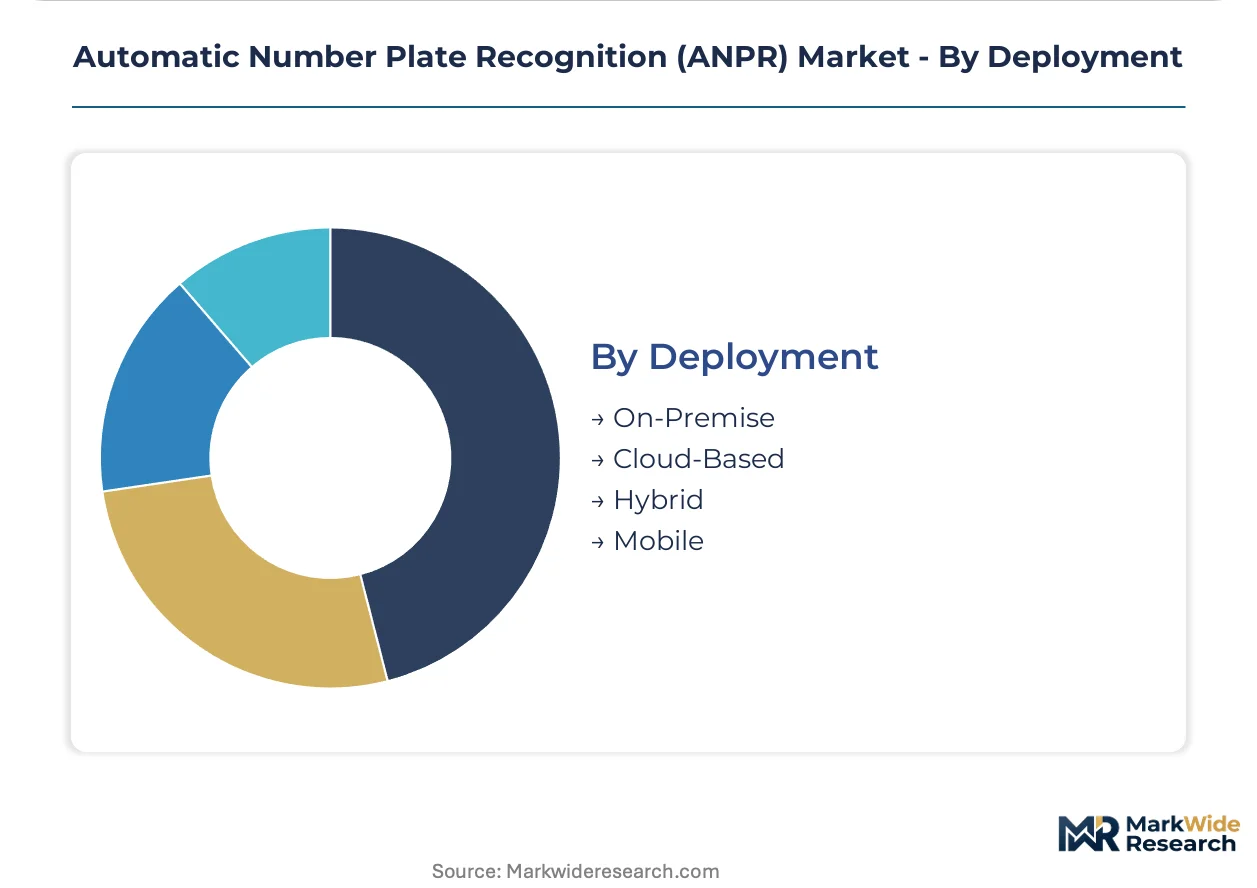
Deployment:
Architecture choice trades latency, data sovereignty, and infrastructure ownership against operational flexibility and upfront investment.
- On-Premise:Local server infrastructure retains biometric data within customer-controlled environments. GDPR data retention limits on cloud-archived plate databases force European customers toward higher-cost retention architectures.
- Cloud-Based:Centralized processing enables rapid scaling without hardware procurement cycles. 5G private network deployment allows mobile units to stream uncompressed 4K video for centralized processing.
- Hybrid:Edge inference with cloud aggregation balances real-time performance and archival analytics.
- Mobile:Vehicle-mounted units serve temporary enforcement and event traffic management.
On-Premise retains structural share in Europe; Cloud-Based gains share fastest among mid-size municipal fleets deploying 5G backhaul.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANPR deployment patterns diverge sharply by governance model: European municipalities prioritize algorithmic auditability under GDPR and the EU AI Act, while United States procurement emphasizes throughput capacity and federal grant integration. Asian markets concentrate on toll modernization and highway digitization at scale.
United States
Department of Transportation grants channel federal funds toward integrated mobility platforms in Los Angeles, Chicago, and Houston, embedding ANPR into multimodal corridor management. FCC equipment authorization timelines of 12-18 months for wireless backhaul configurations delay product launches for hardware manufacturers. The Southwest corridor from Texas to Arizona anchors mobile ANPR deployment for border enforcement and temporary traffic management.
Germany
Public accounting rules favor SaaS licensing models that classify analytics as operational expenditure rather than capital equipment, accelerating software unbundling from hardware procurement. The EU AI Act's risk classification system imposes conformity assessment obligations and training data documentation requirements on vendors serving police authorities. Bavaria and Baden-Württemberg concentrate smart city infrastructure budgets for toll and traffic corridor optimization.
United Kingdom
The Surveillance Camera Commissioner and Information Commissioner's Office jointly enforce proportionality standards that reshape product design requirements for public sector contracts. Transformer-based OCR pilots in the Netherlands and United Kingdom deploy degraded plate reconstruction at extreme angles. London and the Southeast corridor dominate capital expenditure for fixed-site installations with all-weather imaging capability.
India
The National Highways Authority FASTag integration creates demand for hybrid RFID-optical verification systems at 600-plus toll plazas undergoing digitization through 2027. Central Electricity Authority and Telecom Regulatory Authority of India frameworks shape spectrum allocation for mobile enforcement units. Maharashtra and Gujarat anchor manufacturing clusters for solid-state infrared modules serving domestic and export markets.
United Arab Emirates
Smart city infrastructure investments in Dubai and Abu Dhabi prioritize integrated traffic management with real-time identification for access control and regulatory enforcement. Ministry of Health and Prevention data governance guidelines influence biometric retention architectures for parking and security applications. The Dubai-Abu Dhabi corridor anchors deployment of edge computing architectures for low-latency plate recognition at scale.
Automatic Number Plate Recognition (ANPR) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack hardware manufacturers competing against pure-play software vendors for margin capture in decoupled procurement environments. The market structure rewards captive manufacturing of specialized cameras and edge processors alongside open-architecture software that navigates multi-vendor environments. Two strategic archetypes dominate: integrated tolling and traffic management portfolio holders, and open-platform software specialists. Competitive moves concentrate on geographic portfolio rebalancing to escape compliance cost concentration and on restructuring pricing models around real-time inference capabilities rather than capital equipment sales.
Within the integrated systems tier, Kapsch TrafficCom AG and Hikvision Digital Technology Co., Ltd. occupy positions that exemplify divergent approaches to hardware-software bundling, while Genetec Inc. represents the open-architecture software archetype navigating multi-vendor procurement environments. These three anchors illustrate how competitive boundaries redraw around edge computing capabilities and regulatory compliance positioning rather than traditional product category definitions.
| Leading Market Players |
|---|
| Siemens AG |
| Kapsch TrafficCom AG |
| Hikvision Digital Technology Co., Ltd. |
| Genetec Inc. |
| Jenoptik Group |
| Axis Communications AB |
| Nedap N.V. |
| Q-Free ASA |
| Conduent, Inc. |
| Others |
Supply Flow & Price Mechanics
FCC equipment authorization timelines for wireless ANPR backhaul configurations gate both vendor qualification and price differentiation simultaneously, compressing margins for US-focused hardware manufacturers while rewarding pre-certified suppliers with premium positioning in federal procurement channels. This regulatory bottleneck reshapes how vendors structure contract terms and geographic prioritization across hardware tiers.
Pricing Analysis
Long-term offtake agreements dominate municipal procurement in Germany and France, where public accounting rules classify SaaS analytics as operational expenditure rather than depreciable capital. Three-tier pricing structure across premium, standard, and economy levels separates full-stack integrated systems from open-architecture software licenses and commodity camera hardware. Cost compression in the standard tier intensifies as channel partners capture margin previously retained by manufacturers. Parking operators exhibit highest price sensitivity due to subscription-based budget constraints, while transportation agencies prioritize performance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor specialized image signal processor fabrication for ANPR edge devices, with TSMC and Samsung foundry capacity feeding neural network inference optimization. Solid-state infrared sensors, edge-computing SoCs, and precision optical assemblies draw from concentrated East Asian manufacturing clusters. Single-source vulnerability in advanced node semiconductor supply exposes procurement timelines to geopolitical disruption. Distribution runs through systems integrators and IT resellers who intermediate between full-stack manufacturers and end-user municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing architectures are collapsing traditional hardware-software boundaries, creating a high-growth disruption window as real-time inference capabilities displace capital equipment sales models. The EU AI Act's risk classification system for biometric identification accelerates this inflection by mandating auditable AI alternatives.
For Market Incumbents: Fortify compliance positioning through documented training data provenance and model performance across demographic subgroups to satisfy EU AI Act conformity assessments. Backward integration into specialized camera and edge processor manufacturing protects margin erosion from channel intermediation. Prioritize Bavaria and Baden-Württemberg smart city budgets where integrated toll and traffic corridor optimization contracts concentrate. For New Entrants and Emerging Players: Lead with parking control SaaS offerings where subscription scalability attracts mid-size municipal fleets seeking operational expenditure classification. India's FASTag toll modernization presents the most penetrable geography, with 600-plus plaza digitization creating demand for hybrid RFID-optical verification. Deploy direct-to-transportation-agency sales models bypassing incumbent channel structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-play software vendors as customers unbundle analytics from hardware procurement. Five-to-ten year viability favors open-architecture specialists with federated learning capabilities and transformer-based OCR roadmaps. Acquisition target archetype: embedded systems teams optimizing neural network inference on thermal-constrained camera SoCs. Signal to watch: 5G private network deployment pace enabling mobile ANPR managed service models.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Conformity assessment obligations filter non-compliant suppliers from European police and transport authority contracts. |
| Edge AI Firmware Optimization | Neural network inference on thermal-constrained camera SoCs reduces latency for real-time plate recognition. |
| 5G Private Network Deployment | Ultra-reliable low-latency connectivity enables mobile ANPR units to stream uncompressed 4K video for centralized processing. |
| Transformer-Based OCR Development | Attention mechanisms fragment historical convolutional neural network dominance in degraded plate reconstruction accuracy. |
| Channel Partner Margin Capture | Systems integrators and IT resellers intermediate between manufacturers and municipal buyers in unbundled procurement environments. |
Methodological Framework
Operator-level perspectives from traffic management directors, parking facility managers, law enforcement procurement officers, and smart city infrastructure planners anchored the qualitative base. Primary interview insights combined with secondary validation from FCC equipment authorization databases, EU AI Act implementation guidance, National Highways Authority FASTag integration records, and municipal procurement disclosures. Bottom-up segment sizing triangulated against top-down infrastructure budget allocations across the analysis window.
Sensitivity analysis tested forecast robustness across deployment architecture shifts, regulatory compliance cost trajectories, and semiconductor supply disruption scenarios. Segmentation dimensions modeled include product type, application, end user, and deployment mode alongside edge computing capability tier and geographic regulatory cluster. CAGRs derived from installed base evolution, replacement cycle acceleration, and emerging application penetration. Industry-specific inputs encompassed smart city infrastructure budget flows and toll modernization program timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal grant funding levels, stable East Asian semiconductor supply, or consistent GDPR enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and procurement rule evolution. Specific risks that could revise projections include FCC authorization timeline extensions, EU AI Act risk classification expansion, or geopolitical disruption to image signal processor supply. Recalibration cycles align with material shifts in regulatory enforcement patterns and infrastructure budget appropriations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Drain Camera Market
Sensors
Smart Beacon Market
Sensors
Asset Tracking Market
Sensors
Gesture Recognition in Retail Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
India Asset Tracking Market
Sensors
Eye Tracking Solutions Market
Sensors
Mobile Laser Scanning Market
Sensors
Heat Stress Meter Market
Sensors
Voice Sounders Market
Sensors
Lidar Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Europe RFID Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Indoor Location Market