
 Sweden E-Commerce Market | 2026-2036
Sweden E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden E-Commerce Market Outlook
Swedish logistics talent scarcity is unwinding fulfillment capacity expansion across the e-commerce sector. Elgiganten leverages its nationwide electronics retail footprint to anchor same-day delivery in urban clusters. Ikea competes through vertical control over its flat-pack supply chain, sustaining cost advantages in home goods distribution. Zalando dominates fashion e-commerce with proprietary logistics technology that differentiates delivery speed across Nordic markets.
Sweden e-commerce denotes digitally mediated retail transactions conducted through web-based platforms and mobile applications, typically integrating encrypted payment gateways, real-time inventory systems, and algorithmic recommendation engines to match buyers with sellers across geographical boundaries. The primary commercial purpose centers on disintermediating traditional retail to reduce transaction costs while expanding consumer choice beyond physical store constraints. Apparel and electronics categories lead transaction volumes, though home goods generates disproportionate margin pools due to higher average order values and lower return rates. Subscription pricing models are gaining structural prominence among working professionals seeking predictable replenishment cycles, while direct-to-consumer channels capture growing share as brands bypass marketplace fees.
Swedish e-commerce operators navigate compliance obligations under the EU Digital Services Act, national implementations of GDPR, and the Swedish Consumer Agency's distance-selling regulations. The EU AI Act will impose algorithmic transparency requirements on recommendation systems that currently drive product discovery. Stakeholders must monitor how forthcoming EU packaging waste directives reshape last-mile material standards and fulfillment economics.
Market Dynamics
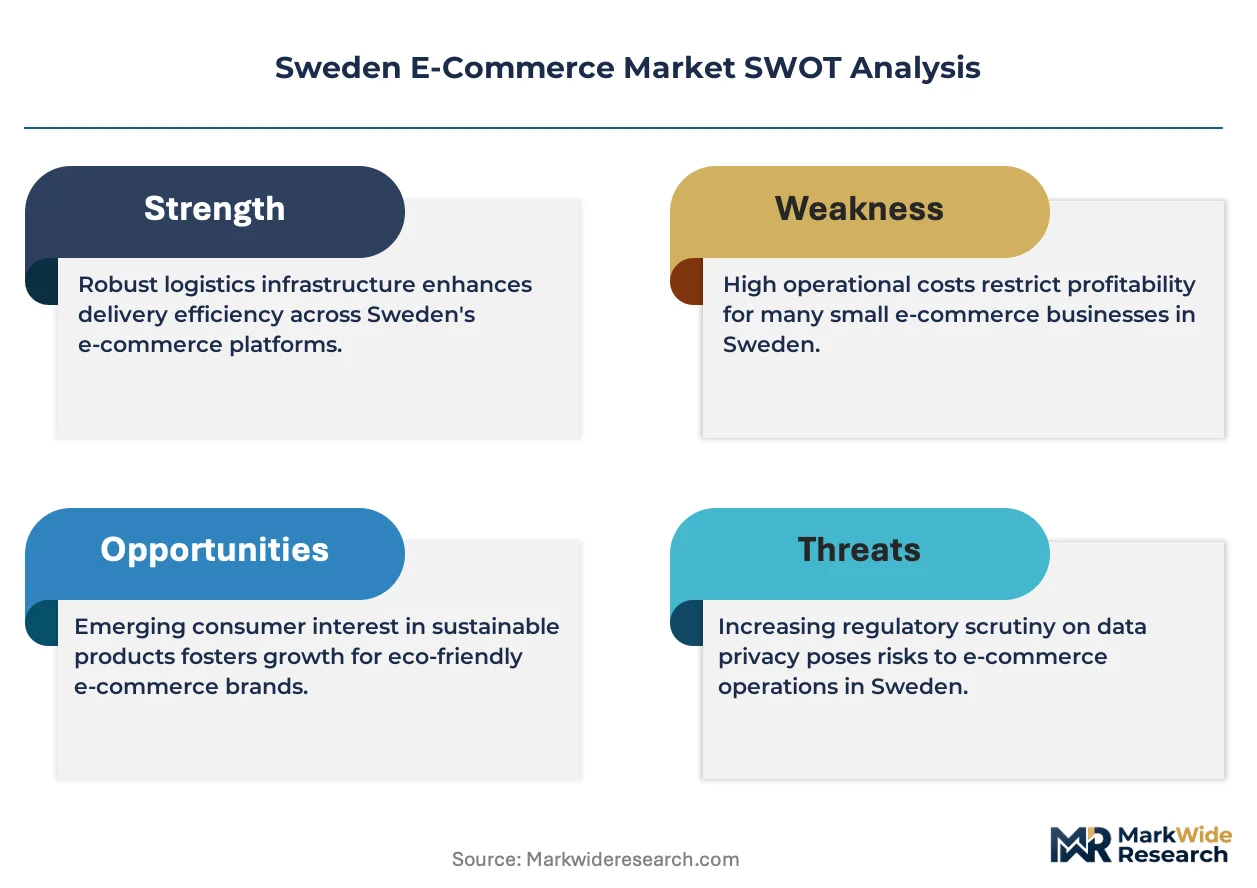
Swedish logistics talent scarcity is compressing fulfillment capacity expansion while Stockholm's metropolitan corridor concentrates demand density that strains last-mile infrastructure.
Growth Catalysts
- EU Digital Services Act:Platform compliance obligations are standardizing cross-border transaction frameworks, reducing regulatory fragmentation for Swedish operators serving Nordic markets.
- Same-day delivery infrastructure:Urban logistics density in Stockholm, Gothenburg, and Malmö enables rapid order fulfillment that locks in consumer switching costs.
- Subscription replenishment models:Working professionals in Sweden's metropolitan clusters are adopting predictable consumption cycles that stabilize inventory planning for grocery and personal care categories.
Market Restraints
- Last-mile labor scarcity:Sweden's tight logistics labor market is inflating wage costs for delivery fleet operators and warehouse automation technicians.
- GDPR compliance friction:Cross-border data processing requirements create operational overhead for Swedish platforms expanding personalized recommendation engines.
- Packaging material cost volatility:Kraft paper and corrugated fiberboard input prices fluctuate with pulp commodity cycles, squeezing margin on low-value shipments.
Strategic Opportunities
- Direct-to-consumer channel expansion:Swedish brands are bypassing marketplace commission structures by building proprietary web storefronts with integrated payment gateways.
- EU packaging waste directive alignment:Early compliance with forthcoming material standards creates first-mover positioning for sustainable fulfillment packaging.
- AI-driven demand forecasting:Machine learning convergence with real-time inventory systems is enabling dynamic pricing and stock positioning in fashion and electronics verticals.
Industry Challenges
- Algorithmic transparency mandates:The EU AI Act will require Swedish platforms to document recommendation system logic, complicating proprietary product discovery engines.
- Legacy ERP integration:Mid-market retailers face technical debt when connecting modern e-commerce stacks to decades-old inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden E-Commerce Market |
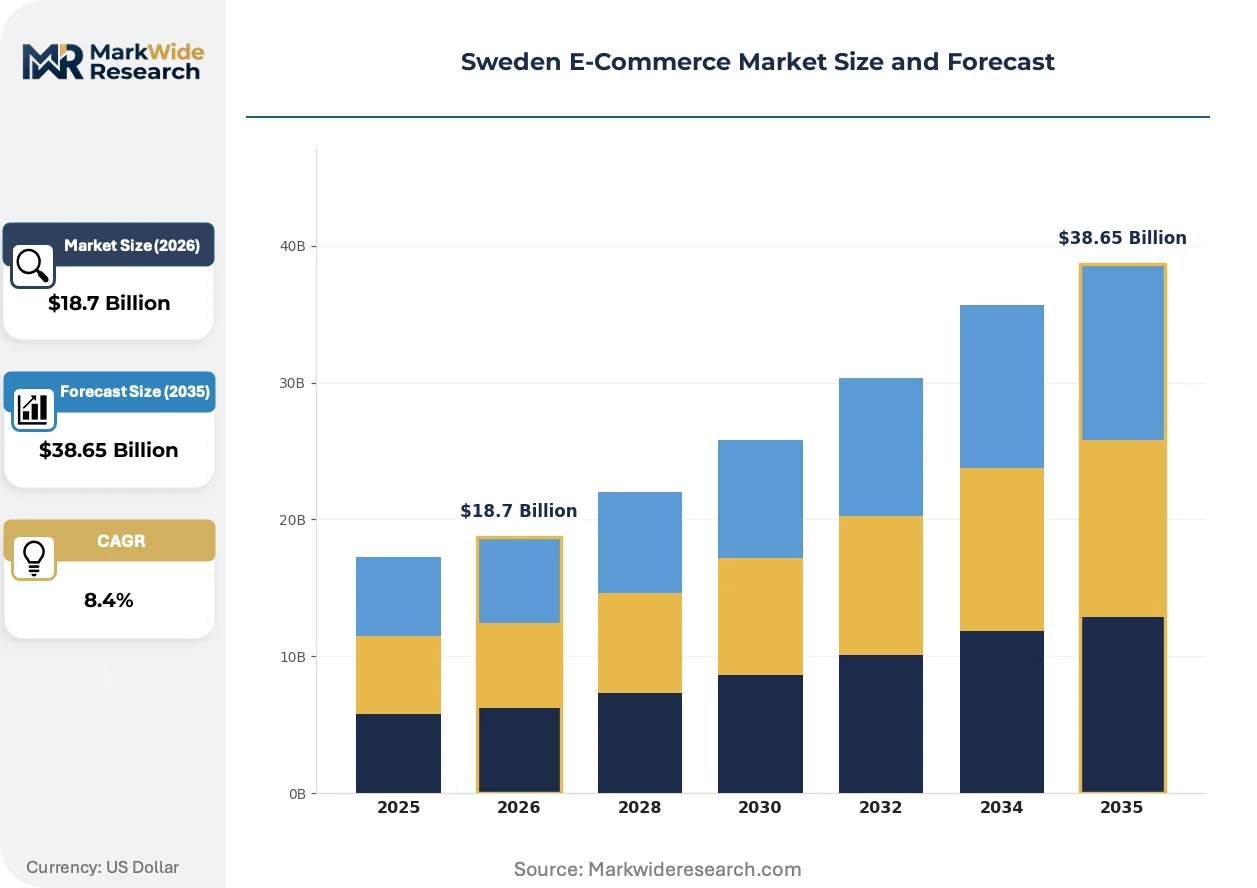
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Beauty Products Customer Type: Millennials, Gen Z, Working Professionals, Retirees Pricing Model: Subscription, Pay-Per-Use, Freemium, One-Time Purchase Distribution Channel: Direct-to-Consumer, Marketplaces, Social Media, Affiliate |
| Companies Covered | Apotea, H&M, Elgiganten, Zalando, Apple, Ikea, Net on Net, Apoteket, CDON, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden E-Commerce Market Strategic Shifts
Swedish e-commerce infrastructure is compressing fulfillment timelines while regulatory frameworks reshape platform architecture and consumer data governance.
Micro-fulfillment centers are miniaturizing warehouse footprints for urban proximity. Swedish grocery operators are deploying automated storage and retrieval systems in converted retail spaces. This topology is miniaturizing delivery radii to under 10 kilometers, enabling sub-hour replenishment cycles in Stockholm's inner suburbs.
GDPR enforcement through Sweden's national data protection authority is tightening consent mechanisms for behavioral tracking. E-commerce platforms must now implement granular opt-in architectures for recommendation algorithms. Fashion and electronics marketplaces face the steepest compliance costs as personalized discovery drives conversion.
Consolidated delivery subscriptions are displacing per-transaction shipping fees. Swedish consumers are bundling purchases across retailers to unlock fixed monthly logistics costs. This pattern concentrates order volume with platforms offering membership programs, particularly visible among urban professional households in Malmö and Uppsala.
Sweden E-Commerce Market Segmentation
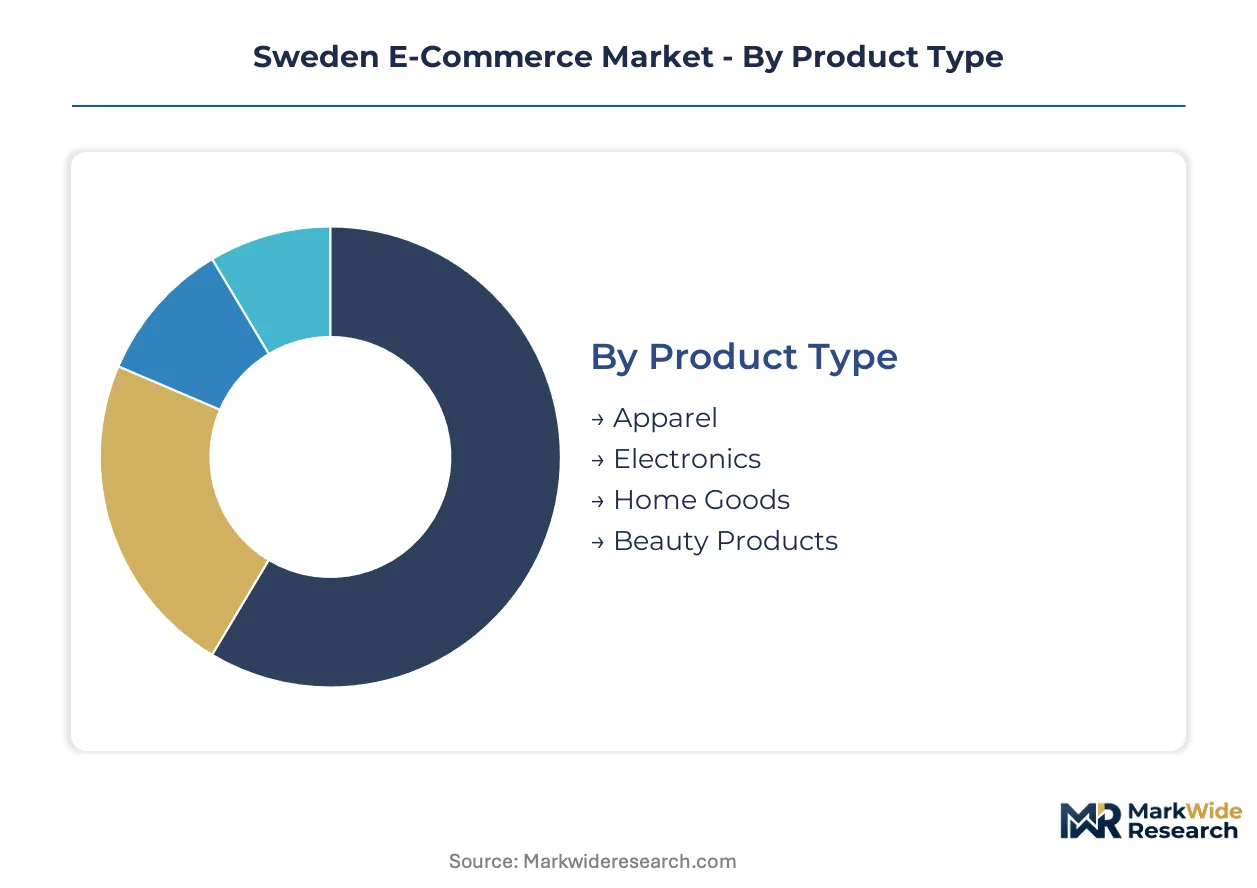
Swedish e-commerce operators segment demand across four intersecting dimensions to optimize fulfillment infrastructure and pricing architecture. Product type determines warehouse topology and last-mile density requirements, while customer cohorts drive subscription penetration and channel selection strategies.
Product Type:
Margin pools concentrate in home goods and beauty products due to higher average order values and lower return processing costs compared to fashion and electronics.
- Home Goods:Flat-pack furniture and interior furnishings require specialized warehouse configurations for bulky inventory storage. Stockholm's metropolitan corridor generates disproportionate demand density for rapid-replenishment home décor, with Ikea's vertical supply chain control setting cost benchmarks.
- Beauty Products:Skincare and cosmetics categories leverage subscription replenishment models among urban professional households. GDPR-compliant personalization engines drive conversion in this segment, though algorithmic transparency mandates under the EU AI Act will reshape recommendation architectures.
- Apparel:Fashion e-commerce dominates transaction volumes through Zalando's proprietary logistics technology, though return rates compress net margins.
- Electronics:Consumer electronics demand concentrates in urban clusters where Elgiganten's retail footprint anchors same-day delivery capabilities.
The dominant share belongs to Apparel, while Home Goods is closing the gap fastest through subscription box expansion and direct-to-consumer brand proliferation.
Customer Type:
Volume concentration tracks disposable income distribution and digital native penetration across Swedish metropolitan areas.
- Working Professionals:Stockholm-based knowledge workers drive subscription commerce adoption for grocery and personal care replenishment. Predictable consumption cycles stabilize inventory planning for operators targeting this cohort with automated reordering systems.
- Gen Z:Digital-native consumers in university cities like Uppsala and Lund favor social commerce discovery and consolidated delivery subscriptions. This cohort exhibits highest sensitivity to packaging sustainability credentials under forthcoming EU waste directives.
- Millennials:Family-forming households in Gothenburg and Malmö prioritize convenience-oriented marketplace purchasing with fixed monthly logistics costs.
- Retirees:Silver economy participants in smaller municipalities show growing comfort with encrypted payment gateways, though last-mile accessibility remains a constraint.
Working Professionals command the largest addressable spend, though Gen Z is gaining share fastest through social media channel adoption.
Pricing Model:
Cost tier stratification reflects customer lifetime value economics and platform infrastructure investment requirements.
- Subscription:Recurring revenue models capture working professionals seeking predictable replenishment cycles for consumables. Swedish grocery operators deploy automated storage systems to service these commitments with sub-hour delivery windows in Stockholm suburbs.
- One-Time Purchase:Transactional commerce retains dominance in electronics and seasonal apparel, though per-shipping fees face displacement pressure.
- Pay-Per-Use:Access-based models gain traction in home goods rental and premium appliance categories.
- Freemium:Tiered service architectures differentiate basic marketplace access from expedited fulfillment and exclusive inventory.
Subscription pricing holds the revenue concentration edge, while Pay-Per-Use is climbing the fastest through circular economy platform expansion.
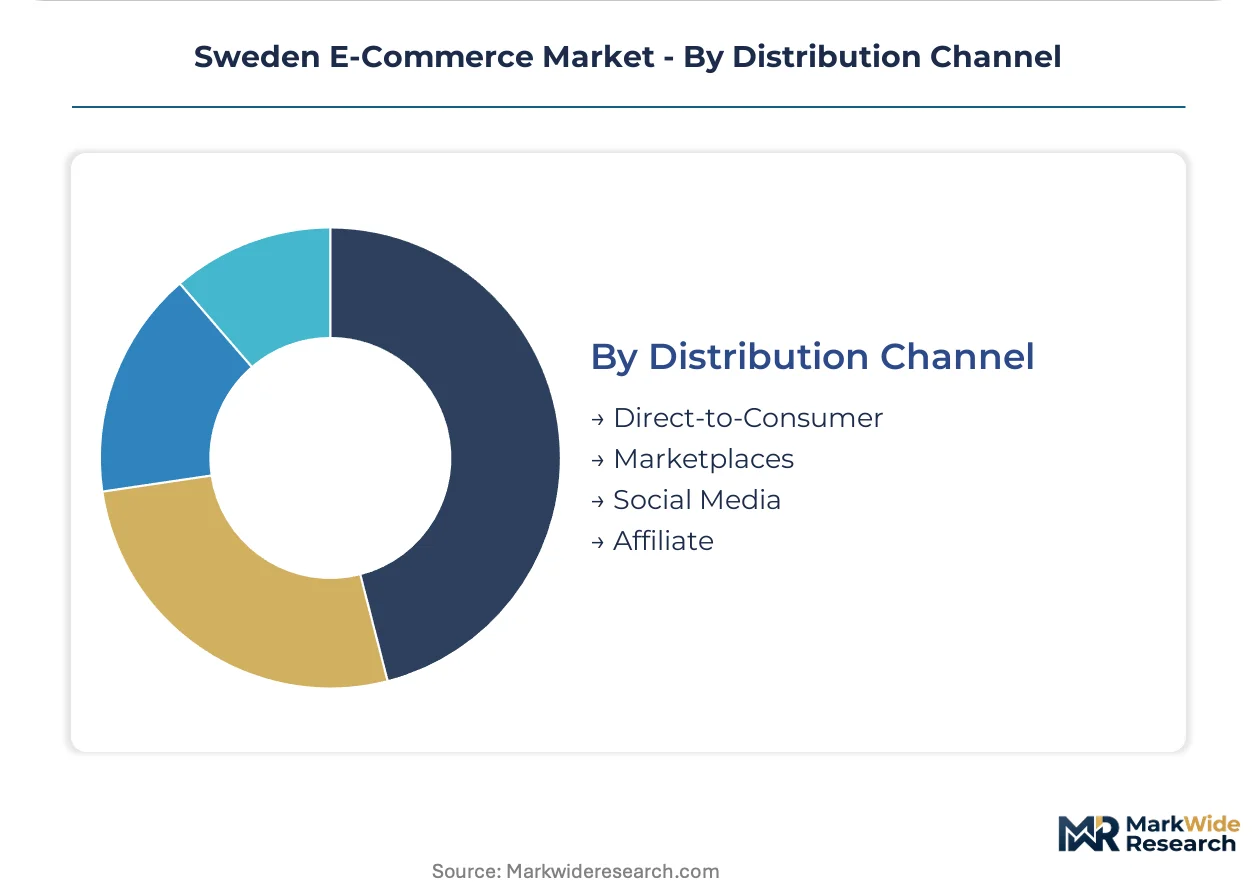
Distribution Channel:
Supply concentration varies by platform control over customer data and fulfillment infrastructure ownership.
- Direct-to-Consumer:Swedish brands bypass marketplace commission structures by building proprietary storefronts with integrated payment gateways. This channel captures disproportionate margin pools through first-party data ownership and controlled logistics costs.
- Marketplaces:Aggregated demand platforms dominate transaction volumes in fashion and electronics, though GDPR compliance friction inflates operational overhead for cross-border data processing.
- Social Media:Discovery-driven commerce accelerates among Gen Z cohorts in Malmö and Uppsala, with influencer attribution reshaping customer acquisition economics.
- Affiliate:Performance-based referral networks concentrate in price-comparison verticals and niche product categories.
Marketplaces retain volume leadership, while Direct-to-Consumer is gaining share fastest as brands invest in captive fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish e-commerce consumption patterns diverge from broader Nordic markets through higher subscription penetration and stricter sustainability expectations, with metropolitan Stockholm driving same-day delivery density unmatched elsewhere in the region.
Stockholm Metropolitan Corridor
Knowledge workers in Stockholm, Solna, and Södertälje anchor subscription commerce for grocery and personal care replenishment. The Swedish Consumer Agency enforces distance-selling regulations that exceed baseline EU requirements. Micro-fulfillment centers in Kista and Hammarby Sjöstad enable sub-hour delivery windows through automated storage systems.
Gothenburg-Västra Götaland
Family-forming households prioritize convenience-oriented marketplace purchasing with consolidated delivery subscriptions. GDPR compliance through the Swedish Authority for Privacy Protection shapes data processing for cross-border platforms. Logistics clusters in Hisingen and Mölndal concentrate last-mile infrastructure serving western Sweden's manufacturing base.
Malmö-Skåne Region
Digital-native Gen Z consumers in Lund and Malmö favor social commerce discovery and sustainability-credentialed packaging. The EU packaging waste directive drives early compliance investments among fulfillment operators. Cross-border e-commerce flows through the Öresund Bridge corridor connect Swedish inventory with Danish demand.
Uppsala University City
Student populations and young professionals drive price-sensitive marketplace adoption with high social media channel penetration. National data protection frameworks limit behavioral tracking for recommendation engines. Retail-to-warehouse conversions in central Uppsala support rapid-replenishment grocery models.
Sweden E-Commerce Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with vertical control over fulfillment infrastructure separating the tiers. The integrated tier commands proprietary logistics networks and first-party data assets, while specialists concentrate on category depth or geographic niches. Three archetypes dominate: electronics retailers leveraging physical footprints, fashion platforms with algorithmic discovery engines, and furniture operators with captive supply chains. Competitive moves center on warehouse automation investments and direct-to-consumer channel buildouts that bypass marketplace fees.
Among Nordic-anchored specialists, Zalando occupies a position exemplifying logistics-technology differentiation, while Elgiganten anchors electronics retail through nationwide showroom networks. Ikea represents vertical supply chain control in home goods, with flat-pack distribution economics that competitors struggle to replicate.
| Leading Market Players |
|---|
| Apotea |
| H&M |
| Elgiganten |
| Zalando |
| Apple |
| Ikea |
| Net on Net |
| Apoteket |
| CDON |
| Others |
Value Chain & Pricing Dynamics
EU packaging waste directive compliance gates both supplier qualification and price differentiation across Swedish e-commerce tiers. Operators must certify sustainable material standards to access premium urban consumer segments, while non-compliant fulfillment networks face margin compression from regulatory penalties and exclusion from consolidated delivery subscriptions.
Pricing Analysis
Long-term subscription contracts dominate working professional segments, while spot transactional pricing retains share in electronics and seasonal apparel. Price differentiation stems from delivery speed tiers and GDPR-compliant personalization depth, with algorithmic transparency mandates under the EU AI Act intensifying cost pressure on fashion discovery platforms. Gen Z consumers in university cities exhibit highest price sensitivity, whereas Stockholm knowledge workers prioritize convenience over per-unit cost.
Supply Chain Analysis
China, Germany, and Poland anchor electronics component and automated warehouse equipment manufacturing for Swedish fulfillment networks. Kraft paper and corrugated fiberboard inputs feed from Nordic pulp mills, with lithium-ion battery cells drawing from South Korean suppliers. Single-source vulnerability concentrates in automated storage system controllers. Distribution runs through micro-fulfillment centers in Stockholm's Kista and Hammarby Sjöstad districts before radiating to Gothenburg and Malmö logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish e-commerce sits in early-cycle expansion as subscription replenishment models penetrate grocery and personal care categories among metropolitan professionals. Same-day delivery infrastructure investments are locking in consumer switching costs ahead of regulatory consolidation.
For Market Incumbents: Shield proprietary logistics networks from labor cost inflation by accelerating warehouse automation deployment in Stockholm's inner suburbs. Anchor same-day delivery density through micro-fulfillment center expansion before GDPR enforcement tightens data processing constraints on recommendation engines. Vertical control over last-mile fleets preserves margin against wage pressure from logistics talent scarcity.
For New Entrants and Emerging Players: EU packaging waste directive fast-track certification unlocks premium positioning among sustainability-credentialed Gen Z consumers in Malmö and Lund. White-space concentrates in direct-to-consumer beauty subscriptions with GDPR-compliant personalization engines. Social commerce discovery channels offer lowest customer acquisition cost entry for digital-native cohorts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated fulfillment infrastructure as warehouse robotics deployment accelerates. Long-term viability favors operators with captive last-mile networks and first-party data assets. Monitor EU AI Act implementation timelines as inflection signal for compliance cost restructuring across algorithmic discovery platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Deployment | Automated storage systems in Stockholm suburbs enable sub-hour delivery windows for grocery subscriptions. |
| Direct-to-Consumer Channel Buildout | Proprietary storefronts bypass Zalando and Elgiganten marketplace commissions while capturing first-party data. |
| GDPR-Compliant Personalization Engine | Granular consent architectures satisfy Swedish Authority for Privacy Protection enforcement in fashion discovery. |
| Sustainable Packaging Certification | Early EU packaging waste directive alignment secures access to sustainability-sensitive Gen Z consumers in Lund. |
| Subscription Replenishment Model | Predictable consumption cycles stabilize inventory planning for Apotea and grocery operators targeting Stockholm professionals. |
Study Parameters
Cross-validation between executive interviews and customs trade data anchors the qualitative findings in this study. Primary fieldwork captured perspectives from e-commerce platform CTOs, logistics fleet operators, Swedish Consumer Agency regulatory leads, and grocery category buyers. Secondary validation drew from EU Digital Services Act filings, Swedish Authority for Privacy Protection enforcement records, pulp commodity exchange data, and automated warehouse equipment import manifests. Bottom-up channel checks and top-down macroeconomic indicators were triangulated to bound estimate ranges.
Sensitivity analysis tested forecast outputs against variable adoption rates for subscription commerce and regulatory implementation timelines. Segmentation modeling spanned product type, customer cohort, pricing model, and distribution channel dimensions across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to historical penetration data, with inputs including Stockholm metropolitan population density gradients, logistics wage inflation indices, and EU packaging directive compliance cost estimates.
Underlying assumptions cover sustained urban professional income growth and stable GDPR enforcement intensity, with deviation risk concentrated in logistics labor market tightening and EU AI Act algorithmic transparency mandate timing. Recalibration cycles align with material shifts in regulatory implementation schedules and warehouse automation cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
E-Commerce Household Appliances Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Egypt E-Commerce Market