
 Asia-Pacific Remote Sensing Technology Market | 2026-2036
Asia-Pacific Remote Sensing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Remote Sensing Technology Market Outlook
Australia's ground station infrastructure expansion is reconfiguring downstream data distribution across the Asia-Pacific. Chang Guang Satellite Technology leverages its Changchun manufacturing base to sustain cost advantages in optical payload production. Planet Labs anchors its Asia-Pacific analytics operations in Singapore, competing on rapid revisit cycles for maritime surveillance. Mitsubishi Heavy Industries dominates launch vehicle integration for Japanese government missions, extending its supplier relationships across the region.
Remote sensing technology encompasses systems that detect and measure electromagnetic radiation reflected or emitted from Earth's surface, typically operating across spectral bands from visible light through short-wave infrared with spatial resolutions ranging from sub-meter to kilometer scale, serving purposes from resource mapping to climate monitoring. Optical and radar product types lead current deployment volumes, though hyperspectral instruments capture expanding margin pools in mineral exploration and precision agriculture applications. Software solutions and data analytics technology segments are growing fastest as end users in environmental monitoring and urban planning shift from raw imagery procurement to actionable intelligence subscriptions.
Japan's METI sets domestic satellite data utilization standards, while China's SAMR enforces geospatial information security classifications that constrain foreign platform access; India's BIS certification requirements for remote sensing instruments further fragment procurement pathways across national boundaries. Australia's TGA and spatial regulators coordinate ocean monitoring data protocols with ASEAN counterparts, shaping regional interoperability expectations. Stakeholders must monitor evolving cross-border data sovereignty rules and alignment between national space agency roadmaps and commercial operator scale-up plans.
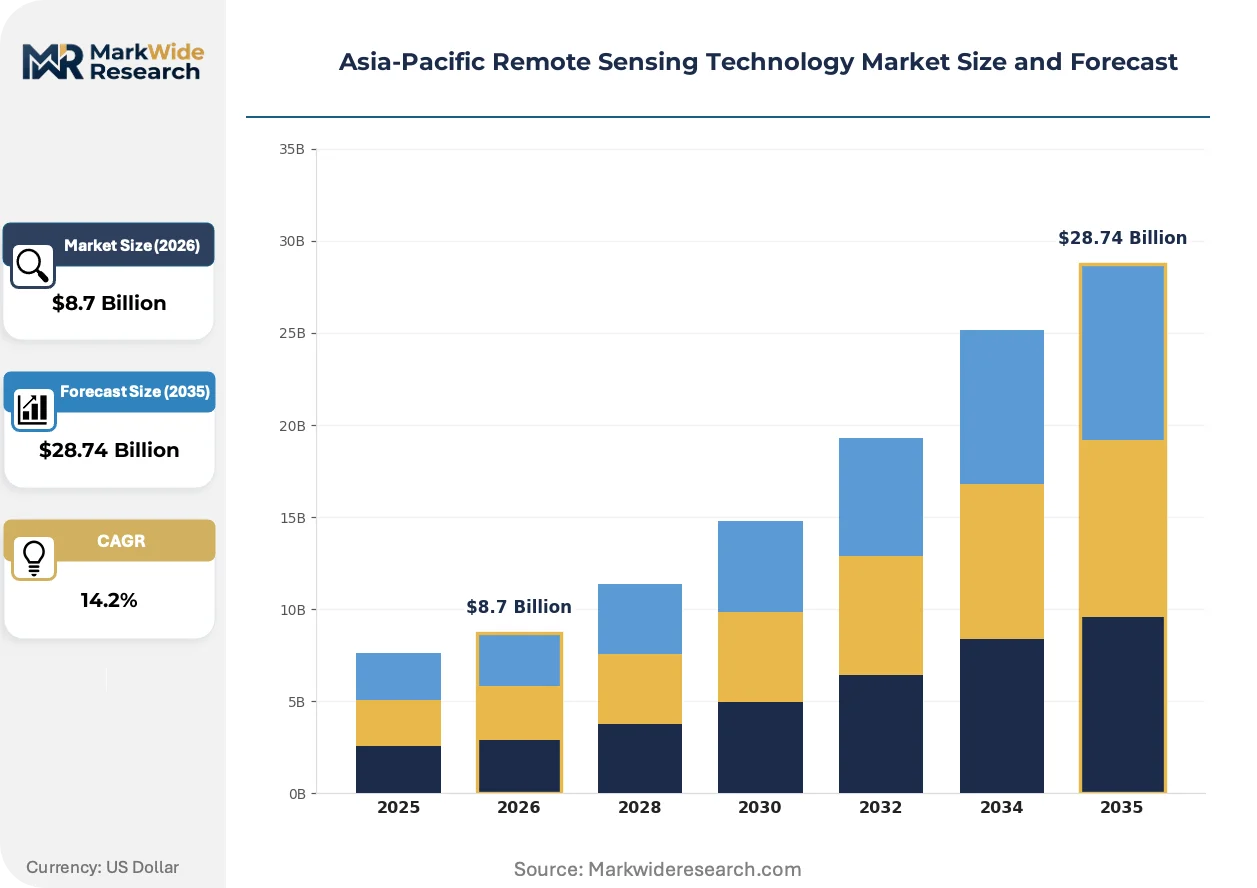
Market Dynamics
China's MIIT satellite data regulations are fragmenting procurement pathways across the Asia-Pacific, forcing foreign operators to establish domestic data processing nodes while state-backed platforms capture sovereign contract flows. This regulatory pivot is concentrating downstream value in compliant local infrastructure.
Growth Catalysts
- India's PLI scheme for space technology:Production-linked incentives are accelerating domestic manufacturing of optical payloads and ground segment equipment, reducing import dependency for government Earth observation programs.
- Precision agriculture adoption:Australian and Southeast Asian farming cooperatives are deploying multispectral drones and satellite analytics to optimize irrigation and fertilizer application, creating sustained demand for sub-meter resolution imagery.
- Smart city clusters in Guangdong and Jiangsu:Municipal governments in these Chinese provinces are procuring persistent urban monitoring systems for traffic management and environmental compliance enforcement.
Market Restraints
- Geospatial information security classifications:China's SAMR enforcement of data sovereignty tiers restricts foreign platform access to sensitive border and coastal zones, limiting addressable market scope for non-domestic operators.
- Launch capacity concentration:Japanese and Indian launch vehicle providers dominate orbital insertion services for the region, creating bottleneck risk for constellation deployment timelines.
- Hyperspectral sensor cost structure:Cryogenic cooling requirements and specialized detector materials sustain premium pricing that constrains adoption beyond mineral exploration and defense applications.
Strategic Opportunities
- ASEAN ocean monitoring protocols:Australia's TGA coordination with Southeast Asian counterparts on maritime surveillance data standards is opening interoperable contract opportunities for analytics providers.
- Software-as-a-service migration:Environmental monitoring agencies are transitioning from raw imagery procurement to subscription-based intelligence platforms, enabling recurring revenue models.
- Convergence of SAR and optical constellations:Synthetic aperture radar all-weather capability fused with high-resolution electro-optical data is enabling new applications in disaster response and infrastructure monitoring.
Industry Challenges
- Cross-border data sovereignty compliance:Operators must maintain parallel processing architectures to satisfy divergent national classification regimes across China, India, Japan, and Australia.
- Specialized photonics engineering talent:Shortages in detector calibration and optical bench design expertise are extending development cycles for next-generation instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Remote Sensing Technology Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar, LiDAR, Optical, Hyperspectral End User: Aerospace, Agriculture, Defense, Environmental Monitoring Technology: Active Sensors, Passive Sensors, Software Solutions, Data Analytics Application: Mapping, Surveillance, Disaster Management, Urban Planning |
| Companies Covered | Axelspace Corporation, Chang Guang Satellite Technology Co. Ltd, China Aerospace Science and Technology Corporation, Japan Aerospace Exploration Agency, Korea Aerospace Research Institute, Maxar Technologies, Esri, Planet Labs, Mitsubishi Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Remote Sensing Technology Market Strategic Shifts
Artificial intelligence inference at the edge is compressing the latency between satellite data capture and actionable intelligence delivery, reshaping competitive dynamics across maritime surveillance and agricultural monitoring verticals.
Hyperspectral imaging systems are digitizing mineral exploration workflows by distinguishing subtle spectral signatures of ore deposits that optical sensors cannot resolve. Australian mining operators are deploying airborne hyperspectral platforms for rapid site assessment. This capability is digitizing traditional ground-based survey methods and compressing exploration timelines from months to days.
Japan's METI satellite data utilization standards are mandating interoperability frameworks for domestic Earth observation platforms, forcing proprietary system vendors to adopt common data formats. Commercial operators must now engineer backward-compatible processing pipelines. Japanese precision agriculture and urban planning segments are the primary beneficiaries of this standardization push.
Subscription-based analytics contracts are displacing transactional imagery purchases across Asia-Pacific environmental monitoring agencies. Municipal governments in Jiangsu province now procure persistent urban change detection services rather than commissioning discrete satellite acquisitions. This shift is most visible in Chinese smart city procurement, where annual software licenses are capturing budget share previously allocated to hardware procurement.
Asia-Pacific Remote Sensing Technology Market Segmentation
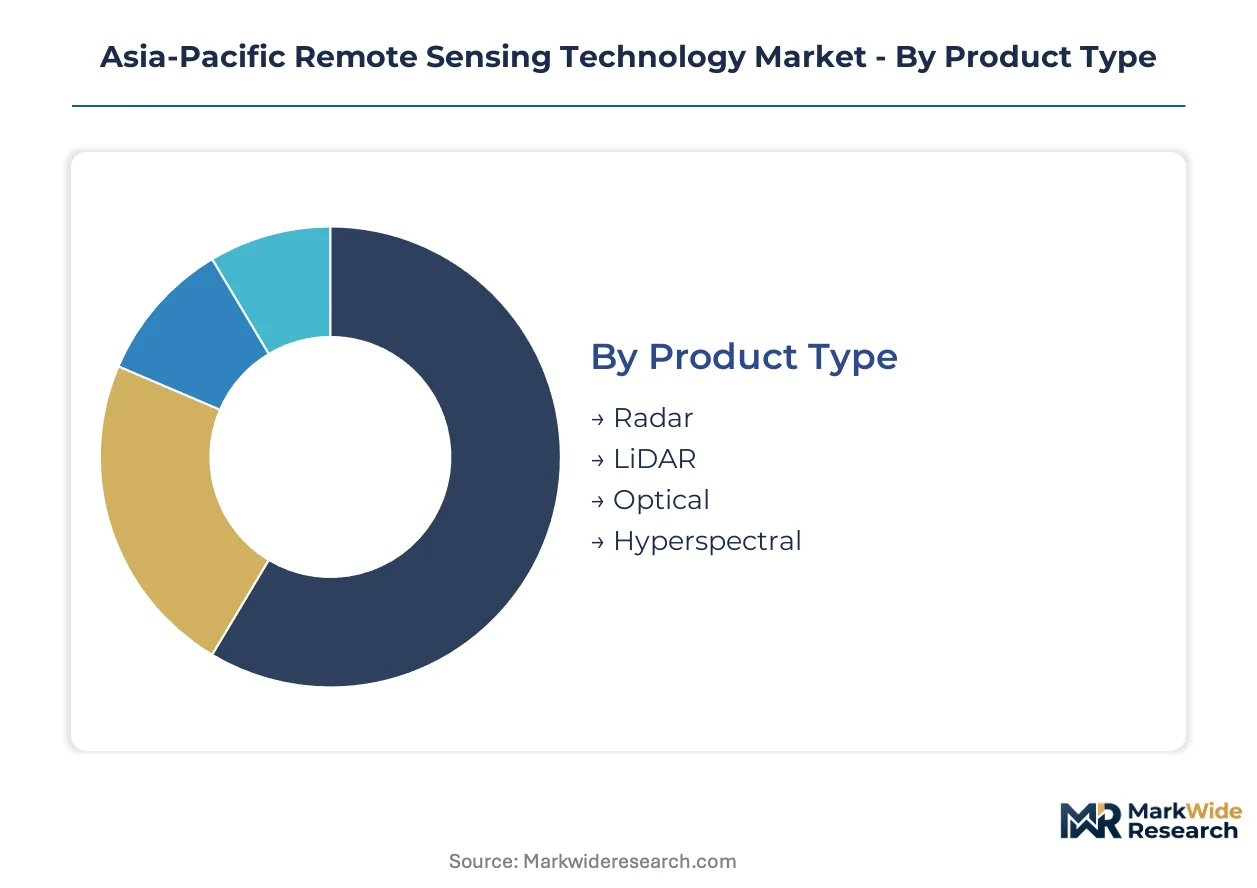
Segmentation reveals how procurement patterns diverge across the Asia-Pacific remote sensing landscape. Technical specifications, end-use requirements, and national regulatory frameworks reshape vendor selection criteria in each category.
Product Type:
After-sales service intensity varies sharply across sensor modalities, with cryogenic-cooled hyperspectral systems demanding specialized maintenance networks that constrain supplier options in Southeast Asian markets.
- Optical:Electro-optical systems capture reflected visible and near-infrared radiation with spatial resolutions reaching sub-meter scales. Demand concentrates in China's Guangdong and Jiangsu provinces where smart city procurement mandates persistent urban monitoring for traffic and environmental compliance enforcement.
- Radar:Synthetic aperture radar penetrates cloud cover and darkness using microwave illumination, enabling all-weather surveillance capabilities. Australian mining operators and Japanese maritime agencies drive procurement for infrastructure and coastal monitoring applications where optical sensors fail.
- LiDAR:Light detection and ranging systems generate precise elevation data through laser pulse timing for topographic mapping.
- Hyperspectral:Narrow-band spectral imaging distinguishes mineral compositions and vegetation health indicators beyond multispectral capability.
By volume, Optical leads. By growth pace, Hyperspectral is ahead.
End User:
Customer type determines contract structure, with defense agencies favoring long-term platform leases while agricultural cooperatives prefer per-acre analytics subscriptions.
- Defense:Military and intelligence agencies procure high-resolution imagery under classified procurement frameworks with stringent data sovereignty requirements. India's defense establishment and Australia's defense department anchor regional demand through sovereign satellite programs and foreign platform access restrictions.
- Agriculture:Farming cooperatives deploy multispectral drones and satellite analytics to optimize irrigation and fertilizer application. Australian broadacre operations and Southeast Asian plantation enterprises sustain demand for sub-meter resolution crop health monitoring.
- Environmental Monitoring:Government agencies and research institutions track deforestation, coastal erosion, and climate indicators.
- Aerospace:Satellite operators and launch service providers consume remote sensing components for platform manufacturing and ground segment integration.
Defense commands premium pricing. Agriculture shows steepest expansion trajectory.
Technology:
Margin profiles invert between hardware and software segments, with data analytics platforms capturing recurring revenue streams that sensor manufacturing cannot replicate.
- Data Analytics:Machine learning platforms transform raw imagery into actionable intelligence for subscription delivery. Municipal governments in Jiangsu province now procure persistent urban change detection services rather than discrete acquisitions, shifting budget from hardware to software licenses.
- Software Solutions:Processing pipelines and visualization tools enable end-user interpretation without specialized remote sensing expertise. Environmental monitoring agencies across Australia and ASEAN member states are migrating from transactional imagery purchases to annual subscription contracts.
- Passive Sensors:Instruments detecting naturally emitted or reflected radiation without artificial illumination.
- Active Sensors:Systems generating their own energy pulses to illuminate targets and measure return signals.
Passive Sensors dominate unit shipments. Data Analytics gains share fastest.
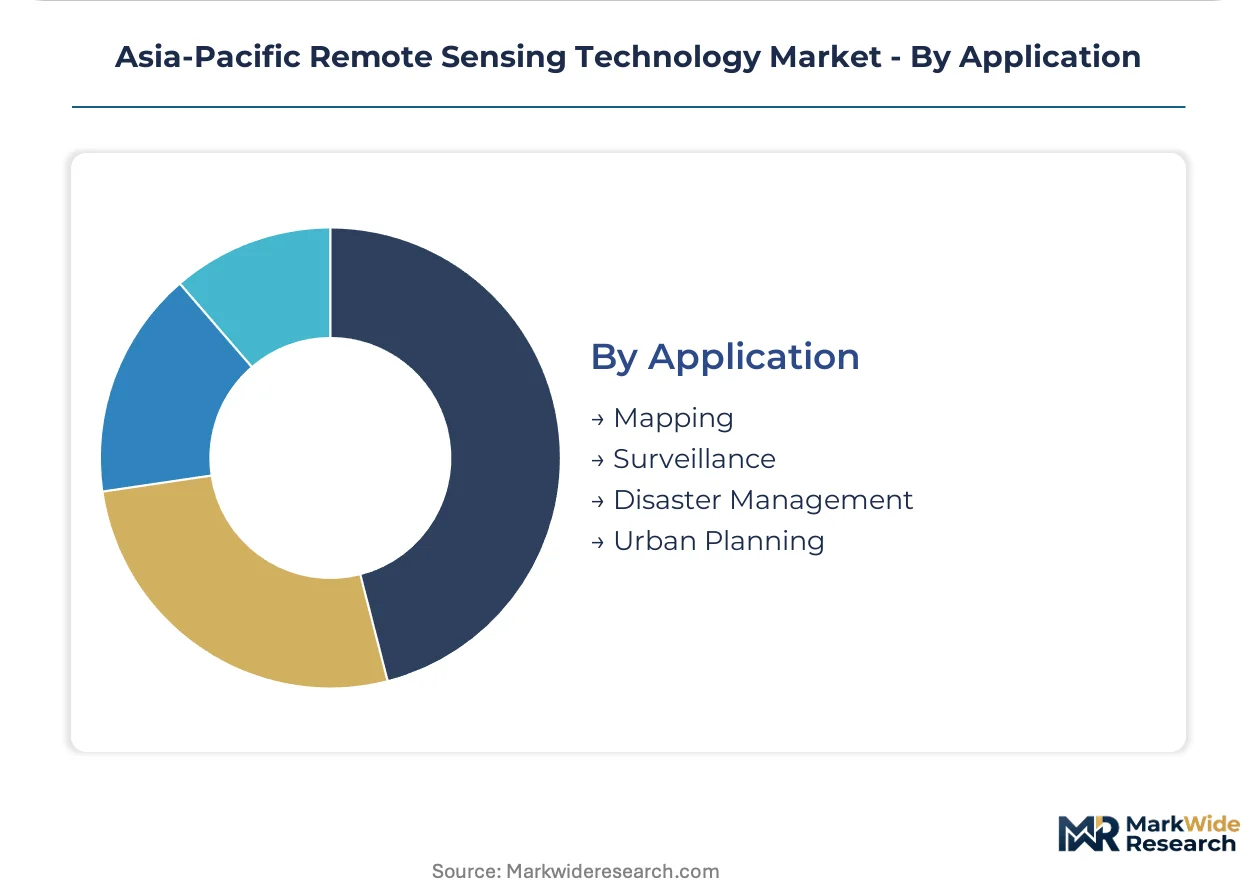
Application:
Application focus determines revisit frequency requirements, with disaster response demanding hourly updates while urban planning tolerates monthly cycles.
- Surveillance:Persistent monitoring of maritime boundaries, border zones, and critical infrastructure requires rapid revisit capabilities. Japan's coast guard and Philippine maritime agencies drive procurement for South China Sea domain awareness applications.
- Urban Planning:Land use classification, informal settlement mapping, and transportation corridor analysis support municipal governance. Chinese smart city clusters in Guangdong and Jiangsu provinces deploy persistent monitoring systems for regulatory enforcement and infrastructure development planning.
- Disaster Management:Flood, fire, and earthquake response coordination requires rapid damage assessment and resource deployment guidance.
- Mapping:Cartographic baseline data generation supports cadastral, topographic, and thematic map production.
Mapping holds largest installed base. Surveillance climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's ground station network expansion across Western Australia and the Northern Territory underwrites the region's downstream data distribution capacity. This infrastructure backbone enables real-time satellite command and control for maritime surveillance constellations serving Southeast Asian coastal states.
China
Guangdong and Jiangsu provinces anchor procurement volume through smart city investments in persistent urban monitoring systems. MIIT satellite data regulations mandate domestic processing nodes for foreign operators, fragmenting procurement pathways while state-backed platforms capture sovereign contract flows. Changchun's manufacturing base sustains cost advantages in optical payload production for regional export.
Japan
Maritime surveillance agencies drive demand for rapid-revisit SAR capabilities in the East China Sea and Philippine Sea corridors. METI satellite data utilization standards enforce interoperability frameworks that compel proprietary vendors toward common data formats. Tokyo's analytics clusters benefit from standardized procurement pipelines for precision agriculture and urban planning applications.
India
Defense Earth observation programs and agricultural monitoring initiatives sustain demand for sub-meter resolution imagery. PLI scheme incentives accelerate domestic manufacturing of optical payloads and ground segment equipment, reducing import dependency for government missions. Bengaluru's space technology corridor concentrates ISRO supplier relationships and private constellation operators.
Australia
Broadacre farming cooperatives deploy multispectral drones and satellite analytics for irrigation optimization across the Murray-Darling Basin. TGA coordination with ASEAN counterparts on ocean monitoring data protocols shapes regional interoperability expectations for maritime surveillance contracts. Perth's ground station infrastructure anchors downstream distribution for Indian Ocean coverage.
Singapore
Maritime domain awareness programs and port authority monitoring sustain demand for rapid-revisit optical and SAR analytics. The city-state's data hosting infrastructure attracts foreign operators establishing compliant Asia-Pacific regional headquarters. Planet Labs anchors its regional analytics operations here, competing on revisit cycle speed for strait surveillance applications.
Asia-Pacific Remote Sensing Technology Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in optical bench and detector fabrication. The vendor base stratifies across state-backed satellite operators, commercial constellation providers, and analytics software platforms. Three archetypes dominate: sovereign mission integrators with captive launch access, commercial imagery providers competing on revisit frequency, and SaaS analytics platforms capturing recurring revenue from environmental agencies. Capacity expansion in ground segment infrastructure and strategic partnerships for data distribution rights represent the dominant competitive vectors.
Among state-backed operators, China Aerospace Science and Technology Corporation and Japan Aerospace Exploration Agency exemplify the sovereign mission integrator archetype with captive orbital insertion capabilities. Chang Guang Satellite Technology Co. Ltd occupies a position within the commercial optical constellation tier, leveraging manufacturing scale advantages. Planet Labs represents the analytics-native competitor, anchoring regional operations in Singapore to compress latency for maritime surveillance contracts.
| Leading Market Players |
|---|
| Axelspace Corporation |
| Chang Guang Satellite Technology Co. Ltd |
| China Aerospace Science and Technology Corporation |
| Japan Aerospace Exploration Agency |
| Korea Aerospace Research Institute |
| Maxar Technologies |
| Esri |
| Planet Labs |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Changchun's optical payload manufacturing cluster concentrates precision optics fabrication for the Asia-Pacific market, anchoring margin capture in domestic processing compliance tiers rather than raw sensor hardware. China's MIIT satellite data regulations force foreign operators to establish local data nodes, fragmenting procurement pathways and concentrating value in compliant infrastructure layers. This upstream concentration reshapes where pricing power accrues across the value chain.
Pricing Analysis
China's MIIT satellite data regulations dictate the pricing tier structure across the Asia-Pacific remote sensing landscape. Three-tier pricing stratifies across sovereign-compliant platforms, hybrid local-foreign processing services, and pure foreign data imports restricted to non-sensitive zones. Price differentiation hinges on data sovereignty certification level and domestic processing node presence. Cost compression in foreign-operator tiers intensifies as state-backed platforms capture sovereign contract flows. Agricultural cooperatives in Australia and Southeast Asia exhibit highest price sensitivity, while defense agencies in India and Japan tolerate premium positioning for assured supply security.
Supply Chain Analysis
Export control regimes restricting cryogenic cooler and specialized detector materials constrain component flows into the Asia-Pacific remote sensing supply chain. Manufacturing concentrates in China for optical bench fabrication, Japan for precision detector assemblies, and South Korea for specialized semiconductor substrates. Raw material dependencies center on germanium substrates, indium antimonide detectors, and radiation-hardened electronics. Single-source vulnerability in cryogenic cooling systems poses structural risk for hyperspectral instrument production. Distribution runs through ground station networks across Australia and Singapore, with data processing increasingly localized to satisfy national classification regimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific remote sensing market sits at a platform-economics inflection where METI interoperability standards and ASEAN ocean monitoring protocols are converging data formats into interoperable ecosystems. This standardization shift reconfigures competitive moats from proprietary pipelines toward analytics-layer differentiation.
For Market Incumbents: Entrench position by deepening backward integration into Changchun-style optical manufacturing clusters and securing ground station infrastructure across Australia's Western Australia corridor. Lock in long-term data distribution rights with ASEAN maritime agencies before interoperability standards commoditize access layers. Priority lever rests on certification pre-positioning for India's BIS requirements and China's SAMR security classifications.
For New Entrants and Emerging Players: Mid-market environmental monitoring agencies in Southeast Asia represent the most penetrable entry point, with subscription-native analytics platforms displacing legacy transactional procurement. Australian broadacre farming cooperatives offer second-tier opportunity for drone-satellite hybrid services. Go-to-market angle should emphasize rapid-deployment SaaS bypassing capital-intensive constellation buildout.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-analytics sub-segments as recurring revenue models displace hardware-heavy satellite manufacturing. Long-term viability favors analytics-native platforms with established subscription bases over capital-intensive constellation operators. Acquisition target archetype: regional SaaS providers with entrenched municipal contracts in Chinese smart city clusters. Signal to watch: shift in Jiangsu province procurement from hardware to annual software licenses as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Node Establishment | MIIT compliance unlocks sovereign contract flows in China's Guangdong and Jiangsu procurement clusters. |
| Ground Station Network Expansion | Australia's Perth infrastructure anchors real-time command for Indian Ocean maritime surveillance constellations. |
| Hyperspectral Sensor Cost Reduction | Cryogenic cooling alternatives expand addressable market beyond mineral exploration into precision agriculture. |
| Analytics Platform Subscription Migration | Jiangsu municipalities now procure persistent urban monitoring services rather than discrete satellite acquisitions. |
| ASEAN Interoperability Certification | TGA-coordinated ocean monitoring protocols open standardized contract opportunities across Southeast Asian coastal states. |
Study Parameters
Cross-validation between satellite operator executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed discussions with Earth observation platform engineers, defense procurement officers, agricultural cooperative technology leads, and municipal smart city planners across China, Japan, India, Australia, and Singapore. Secondary validation drew from MIIT regulatory circulars, METI standardization documents, ISRO mission disclosures, and ASEAN maritime surveillance protocol drafts. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical mission deployment timelines and procurement contract disclosures shaped the analytical framework. Modeled dimensions span sensor modality, end-use vertical, technology layer, and national regulatory cluster. CAGRs derive from segment-level growth trajectory analysis incorporating PLI scheme incentive impacts, smart city investment pipelines, and precision agriculture adoption curves. Industry-specific inputs include orbital insertion capacity constraints, cryogenic cooling cost structures, and software-as-a-service migration velocity in environmental monitoring agencies.
Practitioners should monitor regulatory enforcement intensity around data sovereignty classifications and launch vehicle availability bottlenecks for early signals of forecast deviation. Cross-checking against ISRO mission cadence and JAXA launch manifests is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Low Power Geolocation Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Ultrasonic Technologies Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Mobile Lidar Scanner Market
Sensors
Eye Tracking Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Asset Tags Market
Sensors
IO Link Market
Sensors
Lidar in Construction Market
Sensors
Transport Monitoring System Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Yield Monitoring Systems Market
Sensors
Industrial Automation Sensors Market