
 Transport Monitoring System Market | 2026-2036
Transport Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Monitoring System Market Insights
Modular hardware-software bundles is repositioning buyer choice in the transport monitoring system space, as fleet operators seek plug-and-play telematics rather than monolithic platforms. Siemens AG anchors European rail and road infrastructure monitoring through its integrated control systems. Trimble Inc. specializes in precision GPS and sensor fusion for commercial trucking and construction logistics. Geotab Inc. leverages cloud-native architecture to sustain recurring revenue from mid-sized fleet owners across North America.
A transport monitoring system comprises GPS receivers, onboard diagnostics interfaces, environmental sensors, and wireless communication modules that capture vehicle location, engine performance, driver behavior, and cargo conditions for centralized analysis. These systems serve commercial fleet operators, public transit agencies, and emergency dispatchers by reducing fuel consumption, preventing theft, and ensuring regulatory compliance. Telematics units and GPS tracking modules currently dominate hardware shipments, while artificial intelligence and big data analytics represent the fastest-expanding technology layers as predictive maintenance and dynamic routing displace reactive fleet management. Sensor integration is maturing in cold-chain logistics and hazardous materials transport, where margin pools concentrate around certified, tamper-evident monitoring.
FAA regulations governing unmanned aerial system traffic management, NHTSA ELD mandates for commercial motor vehicles, and EU Green Deal emissions-reporting requirements through the European Commission collectively shape product certification, data retention protocols, and cross-border fleet interoperability standards. GDPR and state-level privacy laws in California and Virginia additionally constrain how driver behavior data is collected, stored, and monetized by platform vendors. Stakeholders must monitor evolving interoperability standards between proprietary telematics protocols and open-source vehicle data architectures to avoid stranded technology investments.
Market Dynamics
Fleet operators face mounting pressure to consolidate fragmented telematics stacks into unified platforms capable of satisfying overlapping ELD, emissions, and safety mandates without redundant hardware procurement.
Growth Catalysts
- ELD Mandate Enforcement:NHTSA's electronic logging device requirements for commercial motor vehicles above 10,000 pounds compel fleet-wide hardware refreshes across the United States, eliminating grandfathered paper log systems.
- Cold-Chain Integrity Demands:Pharmaceutical distributors and perishable food logistics providers deploy multi-sensor monitoring to maintain temperature excursion documentation required by FDA and EU GDP guidelines.
- Predictive Maintenance Algorithms:Machine learning models processing engine diagnostic data now flag component failures 15-30 days pre-incident, reducing unplanned downtime for long-haul trucking operators.
Market Restraints
- Semiconductor Supply Concentration:GPS module and cellular modem production clusters in Taiwan and South Korea expose telematics hardware vendors to geopolitical disruption and foundry allocation constraints.
- GDPR Compliance Friction:Cross-border fleet operators face conflicting data localization requirements between EU member states and third-country jurisdictions, complicating centralized platform architectures.
- Legacy Fleet Depreciation Cycles:Commercial vehicle replacement timelines stretching 7-10 years delay sensor retrofit adoption in owner-operator segments with thin capital reserves.
Strategic Opportunities
- Intermodal Container Tracking:Rail and maritime freight operators seek ISO-standardized telematics capable of seamless handoff between truck, vessel, and locomotive without hardware swapping.
- EV Battery State-of-Health Monitoring:Electric commercial vehicle fleets require specialized diagnostic protocols to track cell degradation, thermal runaway risk, and charging infrastructure compatibility.
- India's FASTag Integration:Mandatory RFID-based toll collection on national highways creates anchor demand for integrated toll-telecomatics bundles among logistics providers serving the Delhi-Mumbai Industrial Corridor.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Vendors competing for firmware developers capable of optimizing real-time operating systems for resource-constrained vehicle gateways face recruitment bottlenecks in automotive technology hubs.
- Multi-Protocol Integration Complexity:Fleet management platforms must reconcile proprietary SAE J1939, ISO 15143, and manufacturer-specific OBD-II implementations without degrading data fidelity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Monitoring System Market |
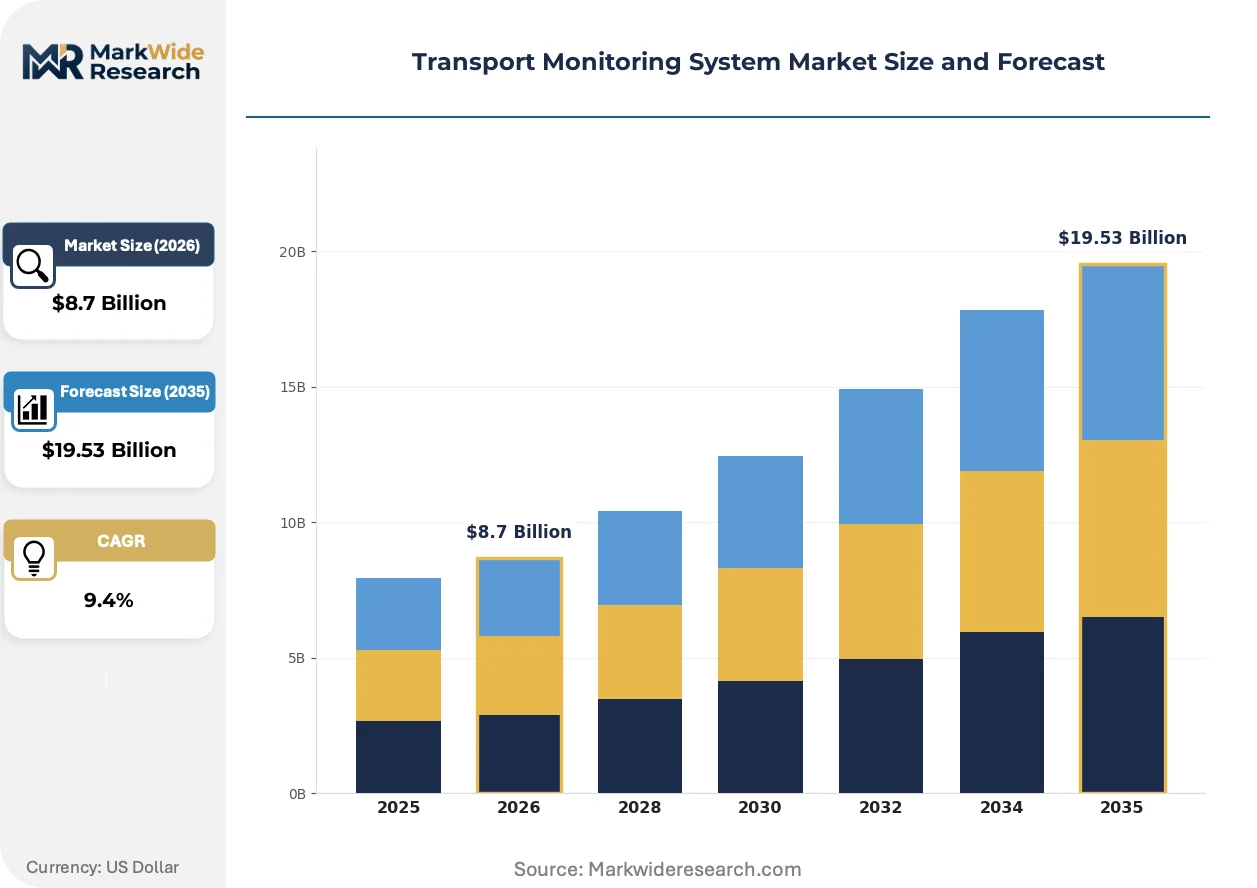
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Tracking, Sensor Integration, Telematics Unit, Mobile Application End User: Logistics Providers, Fleet Owners, Public Transport, Emergency Services Technology: IoT Solutions, Cloud Computing, Big Data Analytics, Artificial Intelligence Application: Fleet Management, Vehicle Recovery, Route Optimization, Performance Monitoring |
| Companies Covered | TomTom International BV, Verizon Communications Inc., Siemens AG, Trimble Inc., Geotab Inc., Robert Bosch GmbH, Teletrac Navman, Fleet Complete, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Monitoring System Market Trends and Innovations
Edge computing architectures are compressing latency between vehicle-born sensor acquisition and actionable fleet commands, eliminating round-trip dependencies on distant cloud data centers for time-critical safety interventions.
Sensor fusion platforms combining LiDAR, radar, and computer vision inputs are unifying previously siloed driver assistance and cargo monitoring functions into single compute modules. Heavy-duty trucking fleets operating hazardous materials routes in Germany and the United States adopt these consolidated units to reduce dashboard clutter and wiring harness complexity. This unification is compressing supplier ecosystems as standalone camera and radar vendors cede position to integrated perception stack providers.
EU Green Deal emissions-reporting requirements through the European Commission now mandate granular CO2 tracking for commercial vehicles above 3.5 tonnes operating across member state borders. Logistics operators must install certified fuel-flow sensors and GPS-correlated engine load monitors to generate auditable carbon intensity data. Cold-chain specialists serving Benelux and Nordic markets face the steepest compliance curves due to earlier enforcement deadlines and stricter penalty structures.
Subscription-based platform access is displacing perpetual license purchases among mid-sized fleet operators seeking to convert capital expenditure into operational expenditure. Third-party logistics providers managing 50-200 vehicle fleets in the United States and United Kingdom now prioritize vendors offering month-to-month elasticity without multi-year lock-in. This preference shift concentrates vendor selection authority with procurement functions rather than engineering departments, elevating total-cost-of-visibility metrics above technical specification comparisons.
Transport Monitoring System Market Segmentation
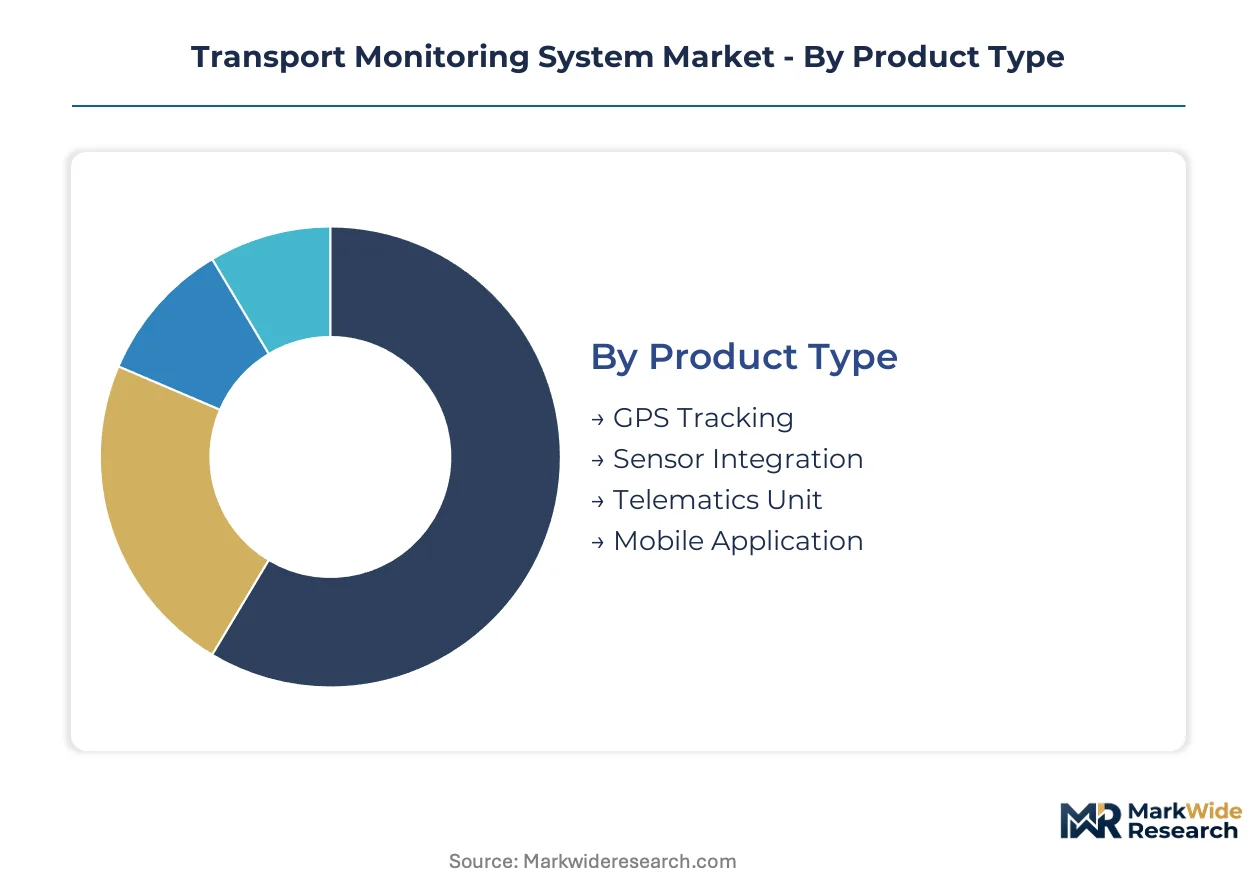
Segmentation in transport monitoring reveals divergent buyer priorities across hardware procurement, software architecture, and service delivery models. Fleet operators select components based on regulatory compliance burdens, cargo sensitivity, and integration complexity with legacy vehicle platforms.
Product Type:
Hardware differentiation separates buyers seeking plug-and-play installation from those demanding customizable sensor arrays.
- GPS Tracking:Satellite-based location modules with cellular backhaul dominate basic fleet visibility requirements. Long-haul trucking operators in the United States deploy these units to satisfy NHTSA ELD mandates without auxiliary sensor expenditure.
- Telematics Unit:Integrated onboard diagnostic interfaces capture engine performance, driver behavior, and fault codes through standardized OBD-II or SAE J1939 protocols. Cold-chain logistics providers across Germany and France prioritize certified tamper-evident units to maintain pharmaceutical distribution compliance under EU GDP guidelines.
- Sensor Integration:Multi-parameter environmental monitors track temperature, humidity, shock, and light exposure for sensitive cargo.
- Mobile Application:Driver-facing interfaces deliver route updates, compliance alerts, and documentation capture.
Telematics units lead volumes today; sensor integration is gaining share fastest.
End User:
Operational scale and regulatory exposure determine platform sophistication requirements across buyer categories.
- Logistics Providers:Third-party operators managing heterogeneous fleets require multi-protocol platforms capable of reconciling disparate vehicle data standards. These buyers prioritize subscription elasticity and API accessibility over deep customization.
- Fleet Owners:Captive vehicle operators with standardized rolling stock optimize for total cost of ownership through predictive maintenance algorithms. Owner-operators in the United States face 7-10 year depreciation cycles that delay retrofit adoption.
- Public Transport:Municipal bus and rail agencies demand redundant communication pathways and passenger information system integration.
- Emergency Services:Police, fire, and ambulance dispatchers require priority network access and sub-second location refresh rates.
Logistics providers anchor current procurement volumes; emergency services show the steepest technology upgrade trajectory.
Technology:
Architecture choices separate buyers prioritizing real-time responsiveness from those optimizing for retrospective analytics depth.
- IoT Solutions:Distributed sensor networks with edge computing capabilities process data locally before selective cloud transmission. Heavy-duty trucking fleets operating hazardous materials routes in Germany adopt these architectures to enable time-critical safety interventions without round-trip latency.
- Artificial Intelligence:Machine learning models processing engine diagnostic data flag component failures 15-30 days pre-incident. Fleet operators with thin maintenance margins deploy these systems to convert unplanned downtime into scheduled service windows.
- Cloud Computing:Centralized data lakes enable cross-fleet benchmarking and third-party analytics integration.
- Big Data Analytics:Retrospective pattern recognition supports network optimization and insurance risk modeling.
IoT solutions dominate hardware-attached revenue; artificial intelligence is climbing the fastest among software layers.
Application:
Functional deployment separates reactive operational tools from predictive optimization platforms.
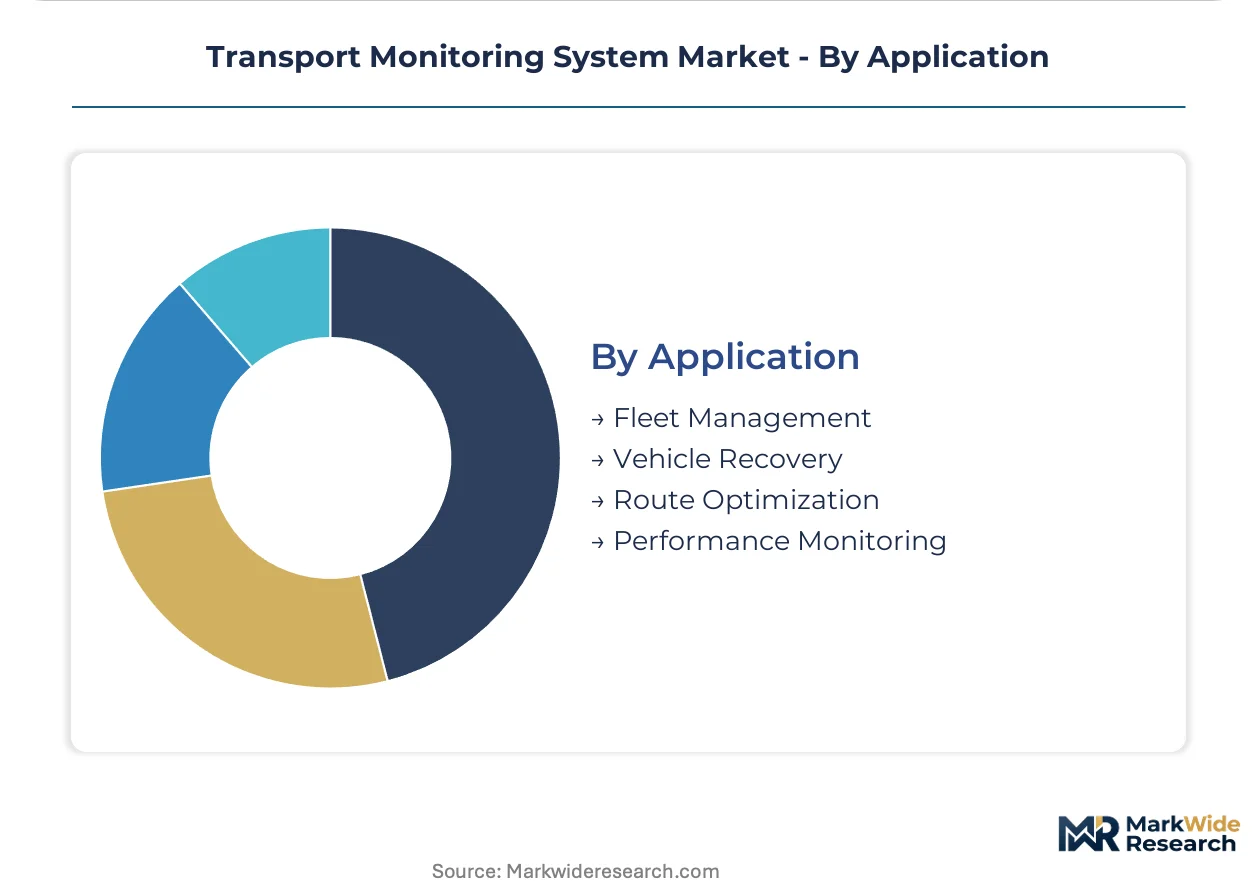
- Fleet Management:Unified visibility platforms consolidate vehicle location, driver hours, maintenance schedules, and fuel consumption into single operational dashboards. Mid-sized fleet operators in the United Kingdom and United States increasingly prefer month-to-month subscription access over perpetual licenses.
- Route Optimization:Dynamic algorithms incorporating real-time traffic, weather, and delivery window constraints reduce fuel consumption and asset utilization. Logistics providers serving the Delhi-Mumbai Industrial Corridor integrate these capabilities with India's mandatory FASTag toll collection infrastructure.
- Vehicle Recovery:Theft detection and remote immobilization systems protect high-value cargo and specialized equipment.
- Performance Monitoring:Driver scorecards and coaching interfaces target insurance premium reduction and safety incident prevention.
Fleet management commands the largest installed base; route optimization is expanding most quickly as fuel costs intensify margin pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics hardware originated in North American and European automotive corridors during the 1990s, with Germany and the United States establishing the foundational patent landscapes and regulatory frameworks that now govern fleet monitoring standards worldwide.
United States
Long-haul trucking operators dominate hardware procurement volumes as NHTSA ELD mandates eliminate grandfathered paper log systems. The Federal Motor Carrier Safety Administration enforces strict hours-of-service documentation requirements for commercial vehicles above 10,000 pounds. Dallas-Fort Worth and Atlanta anchor the densest concentrations of fleet telematics deployment, where third-party logistics providers manage heterogeneous vehicle portfolios.
Germany
Heavy-duty trucking fleets operating hazardous materials routes drive demand for consolidated perception stacks combining LiDAR, radar, and computer vision. KBA vehicle certification requirements mandate tamper-evident monitoring for pharmaceutical distribution under EU GDP guidelines. The Rhine-Ruhr corridor concentrates cold-chain logistics specialists serving Benelux markets with accelerated emissions-reporting deadlines.
India
Logistics providers serving the Delhi-Mumbai Industrial Corridor integrate route optimization with mandatory FASTag RFID toll collection infrastructure. The Ministry of Road Transport and Highways mandates commercial vehicle tracking for national permit compliance and interstate freight documentation. Maharashtra and Gujarat host the fastest-expanding telematics installer networks as owner-operators modernize aging truck fleets.
Japan
Precision manufacturing supply chains demand sub-second location refresh rates for just-in-time component delivery coordination. METI promotes connected vehicle standards harmonization with international telematics protocols to enable cross-border fleet interoperability. The Nagoya-Tokyo industrial belt concentrates automotive logistics providers deploying predictive maintenance algorithms for lean inventory systems.
United Kingdom
Mid-sized fleet operators prioritize month-to-month subscription elasticity over perpetual license purchases for fleet management platforms. DVSA commercial vehicle operator licensing requirements mandate digital tachograph integration and driver hours monitoring. The Midlands logistics triangle around Birmingham and Leicester anchors procurement volumes for cloud-native telematics architectures.
Transport Monitoring System Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive automotive electronics divisions. Tier-one suppliers and specialized telematics pure-plays occupy distinct positioning bands, with hardware-software bundling and subscription revenue models representing the primary competitive axes. Consolidation pressure intensifies as fleet operators demand unified platforms replacing fragmented point solutions. Strategic moves concentrate on sensor fusion integration and geographic expansion through local installer partnerships.
Within the industrial conglomerate tier, Siemens AG and Continental AG represent integrated control system approaches spanning rail and road infrastructure. Among specialized telematics providers, Geotab Inc. and Trimble Inc. occupy positions emphasizing cloud-native architecture and precision GPS applications respectively. Verizon Communications Inc. exemplifies telecommunications carrier verticalization into fleet services through acquired platform capabilities.
| Leading Market Players |
|---|
| TomTom International BV |
| Verizon Communications Inc. |
| Siemens AG |
| Trimble Inc. |
| Geotab Inc. |
| Robert Bosch GmbH |
| Teletrac Navman |
| Fleet Complete |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
GPS module and cellular modem costs originating from Taiwan and South Korea flow through three distinct pricing tiers before reaching fleet operators, with certification-grade telematics units commanding substantial premiums over basic ELD-compliant hardware.
Pricing Analysis
Subscription-based recurring revenue models dominate vendor pricing architecture, separating premium sensor-fusion platforms from standard GPS tracking and economy-grade ELD-only units. Price differentiation rests on GDPR certification tier and after-sales analytics bundling rather than hardware specifications alone. Cost compression in the economy tier intensifies as semiconductor foundry allocation constraints squeeze component availability. Owner-operators with thin capital reserves exhibit the highest price sensitivity, while pharmaceutical cold-chain logistics providers prioritize compliance-grade certification over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major fleet operators mandate qualified suppliers in Taiwan, South Korea, and Japan for GPS receivers and cellular modems to mitigate geopolitical disruption exposure. Raw material dependencies center on semiconductor wafers, lithium-ion battery cells for backup power, and rare-earth magnets for precision antenna assemblies. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through authorized installer networks and direct OEM partnerships rather than traditional electronics wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transport Monitoring System Market functions as a stable compounder where regulatory mandate enforcement—particularly ELD, emissions reporting, and cold-chain documentation requirements—generates predictable replacement cycles across installed fleet bases.
For Market Incumbents: Lock in fleet operator relationships through multi-year subscription contracts with embedded hardware refresh clauses before modular platform competitors erode switching costs. Vertical integration into edge computing firmware development addresses embedded systems engineering talent scarcity threatening product roadmap velocity. Prioritize API accessibility investments to defend against cloud-native challengers targeting mid-sized logistics providers. For New Entrants and Emerging Players: Launch via India's FASTag-integrated toll-telecomatics bundles to capture anchor demand along the Delhi-Mumbai Industrial Corridor where mandatory RFID infrastructure creates immediate hardware attachment opportunities. Target owner-operator segments in Maharashtra and Gujarat with pay-as-you-go financing models that circumvent 7-10 year depreciation cycle barriers. Emphasize EV battery state-of-health monitoring protocols as electric commercial vehicle fleets expand and specialized diagnostic capabilities remain undersupplied. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented telematics stacks create integration complexity for fleet operators seeking unified platforms. Long-term viability favors vendors with captive cloud-native architectures and recurring revenue bases exceeding 70% of total sales. Acquisition targets should demonstrate installed base scale across 10,000+ vehicles with demonstrated API ecosystem traction. The signal to watch is NHTSA enforcement action expanding ELD mandate scope to lighter commercial vehicles below 10,000 pounds.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Consolidated LiDAR-radar-vision modules reduce wiring complexity for hazardous materials fleets in Germany. |
| Cloud-Native Architecture Migration | Subscription elasticity attracts mid-sized UK and US fleet operators converting capital expenditure to operational expenditure. |
| EV Battery Diagnostics Development | Specialized state-of-health protocols address thermal runaway risk tracking for electric commercial vehicle deployments. |
| Intermodal Container Tracking Standardization | ISO-standardized telematics enable seamless handoff between truck, vessel, and locomotive without hardware swapping. |
| Edge Computing Firmware Investment | Local data processing eliminates round-trip cloud latency for time-critical safety interventions on hazardous routes. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down telematics hardware shipment tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, telematics platform engineers, automotive OEM integration specialists, and cold-chain compliance officers were validated against secondary sources including NHTSA enforcement databases, EU Green Deal implementation directives, FCC equipment authorization filings, and commercial vehicle registration statistics. Top-down validation drew from semiconductor trade data and cellular module import records.
Input-output matrices map GPS receiver volumes, telematics unit installations, and sensor integration deployments against fleet size distributions and regulatory compliance deadlines across the projection horizon. Segmentation dimensions include product type tier, end-user operational scale, technology architecture choice, and application functional deployment. CAGRs were derived from regression analysis of historical mandate-driven replacement cycles and forward-looking regulatory enforcement calendars. Industry-specific forecast inputs incorporate ELD mandate phase-in schedules and EU emissions reporting deadline acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or geopolitical trade restriction escalation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet modernization budget availability. Deviation in NHTSA ELD mandate expansion timing or EU Green Deal penalty structure revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Europe RFID Market
Sensors
Gesture Recognition in Retail Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Mobile Mapping Systems Market
Sensors
Smart Mat Market
Sensors
2D Barcode Reader Market
Sensors
Global RFID Market
Sensors
Wireless Synchronized Clocks Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Vision Positioning System Market
Sensors
IO-Link Technology Market
Sensors
Surface Haptic Technology Market
Sensors
Weigh-In-Motion System Market
Sensors
Ultrasonic Technologies Market
Sensors
Cloud Camera Market