
 Rare Disease Genetic Testing Market | 2026-2036
Rare Disease Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Disease Genetic Testing Market Intelligence
CLIA certification and CAP accreditation is collapsing as the baseline qualification for laboratories entering rare disease genetic testing, filtering out smaller operators that lack quality infrastructure. Quest Diagnostics leverages its national laboratory network to sustain broad geographic coverage for complex genetic assays. Centogene N.V. anchors specialized rare disease expertise through its integrated biomarker and diagnostic platform. Invitae Corp competes on test accessibility by extending physician-directed ordering channels beyond academic medical centers.
Rare disease genetic testing encompasses molecular diagnostic methods that identify pathogenic variants in genes associated with disorders affecting fewer than 200,000 individuals, utilizing next-generation sequencing with read depths exceeding 30x for reliable variant detection and Sanger confirmation of clinically significant findings. Its primary purpose is to end diagnostic odysseys for patients with unexplained syndromes and enable precision therapeutic selection. Next-generation sequencing leads product type revenue due to multiplexed panel efficiency, while whole genome sequencing represents the fastest-growing technology segment as costs decline and analytical pipelines mature. Diagnostic testing dominates application volume, though newborn screening exhibits the steepest growth trajectory as state programs expand targeted gene panels.
The FDA regulates laboratory-developed tests under evolving oversight frameworks, while CLIA establishes analytical validity standards for high-complexity molecular diagnostics; CAP accreditation adds proficiency testing requirements that shape operational costs for market participants. The EU In Vitro Diagnostic Regulation imposes stricter conformity assessment for genetic tests sold in Europe, creating compliance barriers for US-based laboratories without notified body partnerships. Stakeholders must monitor how payer coverage policies for exome and genome sequencing evolve, as reimbursement determination will decide whether clinical adoption outpaces current laboratory capacity.
Market Dynamics
Next-generation sequencing cost compression below $1,000 per genome is collapsing the economic barrier between research-grade and clinical-grade testing, forcing laboratories to recalibrate service models around throughput rather than technical premium.
Growth Catalysts
- FDA LDT Guidance:The FDA's evolving oversight framework for laboratory-developed tests is standardizing analytical validation protocols, accelerating CLIA-certified laboratory entry into high-complexity molecular diagnostics.
- Newborn Screening Expansion:State public health programs are broadening targeted gene panel coverage for metabolic and neurological disorders, creating institutional demand for multiplexed sequencing infrastructure.
- Exome Sequencing Reimbursement:Commercial and government payers in the United States are establishing coverage pathways for proband-parent trio testing, reducing out-of-pocket burden for diagnostic odyssey patients.
Market Restraints
- Reagent Supply Concentration:Illumina's dominance in sequencing instrument and consumable supply creates vulnerability for laboratories dependent on single-source chemistry and flow cell availability.
- EU MDR Compliance Burden:The In Vitro Diagnostic Regulation's notified body conformity assessment requirements impose capital-intensive quality management system upgrades on European market participants.
- Bioinformatics Bottleneck:Variant interpretation pipeline development requires scarce computational biology and clinical genetics expertise, constraining laboratory scale-up velocity regardless of instrument capacity.
Strategic Opportunities
- Direct-to-Consumer Channel:Physician-mediated ordering platforms are extending beyond academic medical centers into community practice, capturing patients excluded from traditional genetics referral pathways.
- Pharmacogenomic Convergence:Integration of rare disease diagnosis with therapeutic selection protocols creates value capture opportunities at the interface of diagnostic and pharmaceutical stakeholder ecosystems.
- India Market Entry:The country's central pharmaceutical regulator is streamlining genetic test import and registration processes, opening access to a population with high consanguinity-driven rare disease prevalence.
Industry Challenges
- Variant Classification Workforce Gap:American Board of Medical Genetics and Genomics-certified laboratory directors remain insufficient to match testing volume expansion, extending turnaround times.
- CAP Proficiency Testing Costs:College of American Pathologists accreditation mandates external quality assessment participation that disproportionately burdens mid-sized laboratories with limited test menu diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Disease Genetic Testing Market |
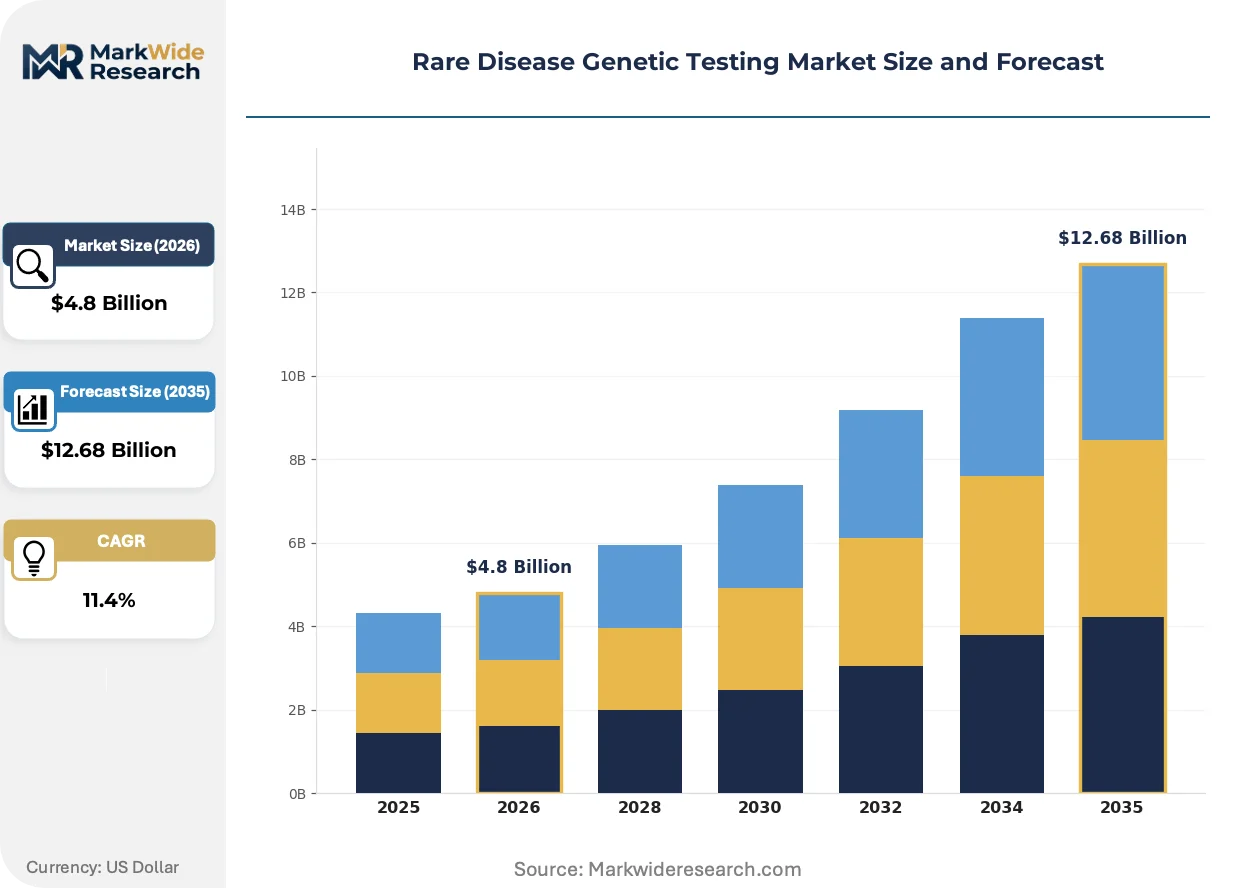
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Next-Generation Sequencing, Sanger Sequencing, Microarray, PCR Technology: Whole Genome Sequencing, Exome Sequencing, Targeted Sequencing, Gene Panels Application: Diagnostic Testing, Carrier Testing, Newborn Screening, Prenatal Testing End User: Clinical Laboratories, Hospitals, Research Institutions, Diagnostic Centers |
| Companies Covered | Quest Diagnostics Inc, Centogene N.V., Invitae Corp, 3billion, Inc., Arup Laboratories, Ambry Genetics, Strand Life Sciences, Eurofins Scientific, Myriad Genetics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Disease Genetic Testing Market Strategic Shifts & Innovations
Long-read sequencing platforms are disrupting the variant detection landscape by resolving structural variants and repeat expansions invisible to short-read chemistry, compressing the diagnostic yield gap between research and clinical workflows.
Whole genome sequencing is fragmenting the traditional tiered testing paradigm where chromosomal microarray and targeted gene panels preceded exome evaluation. Pediatric genetics programs at Boston Children's Hospital and similar institutions are adopting genome-first protocols for congenital anomaly presentations, collapsing the sequential testing timeline from months to weeks. This compression is forcing commercial laboratories to reprice service bundles around speed-to-diagnosis rather than test complexity tiers.
The EU In Vitro Diagnostic Regulation's 2022 implementation deadline is restructuring European market access for US-based genetic testing laboratories. The regulation's Class C device classification for hereditary disease tests requires notified body intervention, creating compliance barriers that favor established IVD manufacturers with existing European quality infrastructure over laboratory-developed test specialists. German and French reference laboratories are responding by pursuing vertical integration into IVD kit development to circumvent LDT restrictions.
Academic medical center procurement departments are consolidating genetic testing vendor relationships through exclusive or preferred provider agreements, displacing the fragmented ordering patterns of individual physician-directed test selection. This concentration is most visible in the United States, where health system integration has created purchasing leverage that extracts price concessions from competing laboratories in exchange for guaranteed volume commitments and embedded genetic counselor support services.
Rare Disease Genetic Testing Market Segmentation
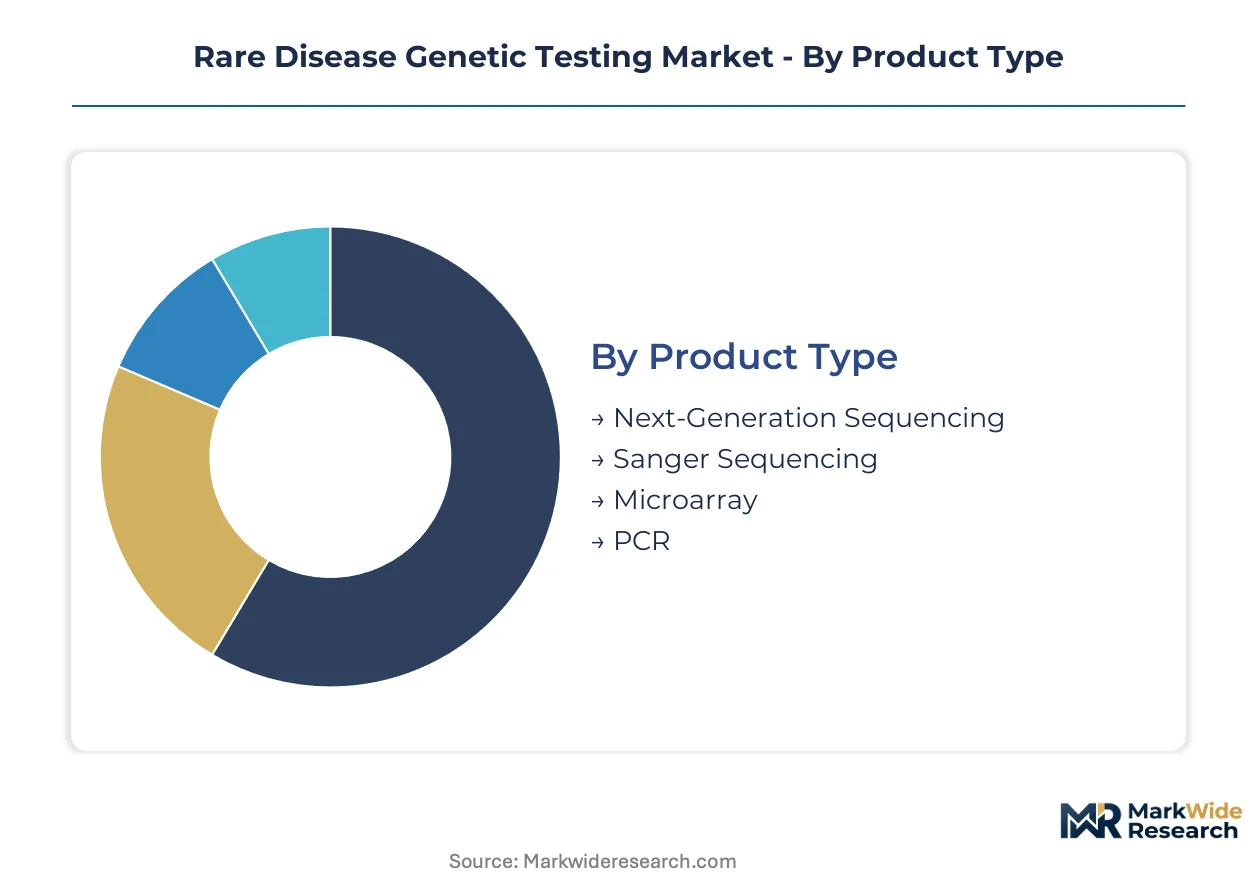
Segmentation in rare disease genetic testing reflects how laboratories balance analytical resolution against throughput economics. Product type and technology choices determine regulatory pathway complexity, while application and end-user concentration shapes reimbursement negotiation leverage.
Product Type:
FDA oversight intensity varies sharply across chemistry platforms, with CLIA high-complexity certification requirements filtering market participation.
- Next-Generation Sequencing:Massively parallel sequencing chemistry achieves read depths exceeding 30x for reliable variant detection. Demand concentrates in United States clinical laboratories expanding pediatric rare disease panels, driven by proband-parent trio reimbursement pathways from commercial payers.
- Sanger Sequencing:Dideoxy chain-termination method provides gold-standard confirmation of clinically significant variants identified through screening assays. German reference laboratories anchor European demand, constrained by EMA guidance on companion diagnostic validation requirements.
- Microarray:Chromosomal microarray analysis detects copy number variations across the genome at lower cost than sequencing.
- PCR:Polymerase chain reaction enables rapid targeted detection of known pathogenic variants in urgent clinical scenarios.
Established volume favors Next-Generation Sequencing; emerging adoption favors PCR in point-of-care configurations.
Technology:
Cost compression trajectories separate research-grade from clinically deployable platforms, with whole genome sequencing cost per genome collapsing below $1,000.
- Whole Genome Sequencing:Comprehensive nucleotide resolution captures structural variants, mitochondrial DNA, and non-coding regions invisible to exome capture. Boston Children's Hospital and similar academic medical centers in the United States are adopting genome-first protocols for congenital anomaly presentations.
- Exome Sequencing:Protein-coding region focus delivers diagnostic yield of 25-40% for neurodevelopmental disorders at reduced cost versus whole genome. United States payer coverage expansion for trio testing is accelerating hospital laboratory adoption.
- Targeted Sequencing:Amplicon or hybridization-capture methods interrogate specific gene sets with faster turnaround times.
- Gene Panels:Pre-defined variant sets address specific phenotypic presentations with streamlined interpretation workflows.
Gene Panels capture current procedural volume; Whole Genome Sequencing is climbing the fastest as analytical pipelines mature.
Application:
Reimbursement determination intensity varies by clinical setting, with newborn screening programs commanding institutional procurement consolidation.
- Diagnostic Testing:Proband evaluation for unexplained syndromes constitutes the foundational revenue stream for rare disease testing infrastructure. United States academic medical centers are consolidating vendor relationships through exclusive provider agreements.
- Newborn Screening:State public health programs in the United States are broadening targeted gene panel coverage for metabolic and neurological disorders. This application is expanding most quickly as state health departments expand sequencing infrastructure.
- Carrier Testing:Preconception screening identifies heterozygous variants in prospective parents.
- Prenatal Testing:Invasive and cell-free DNA methods detect fetal genetic abnormalities during gestation.
Diagnostic Testing sustains laboratory margin structures; Newborn Screening is gaining share fastest through state program expansion.
End User:
Procurement authority concentration determines pricing power distribution, with health system integration reshaping vendor selection criteria.
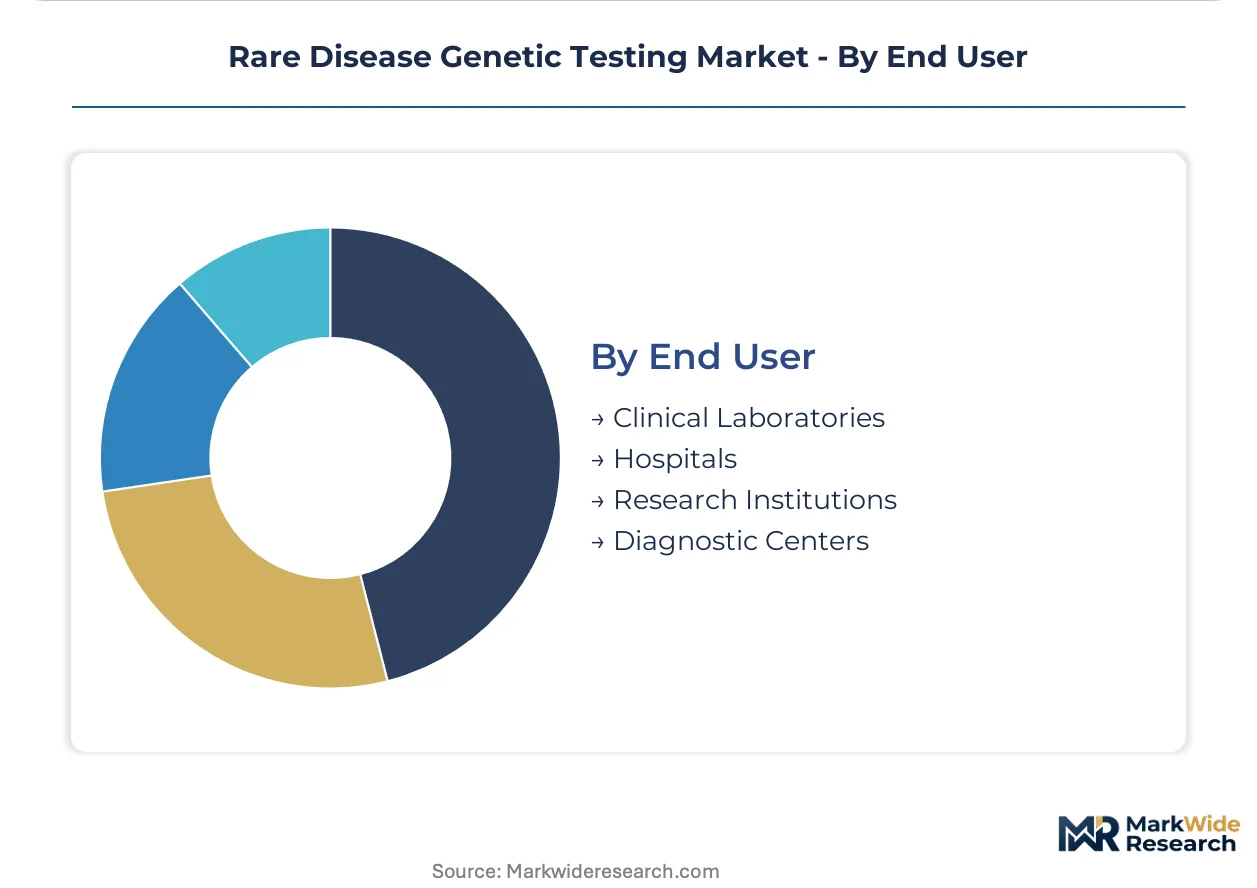
- Clinical Laboratories:CLIA-certified facilities process high-complexity molecular diagnostics under CAP proficiency testing mandates. Quest Diagnostics leverages national network coverage to sustain broad geographic reach for complex genetic assays.
- Hospitals:Integrated delivery networks in the United States are embedding genetic counselors and consolidating test ordering through preferred provider arrangements.
- Research Institutions:Academic centers bridge translational gaps between discovery genomics and clinical validation.
- Diagnostic Centers:Specialized facilities focus on specific disease categories or testing modalities.
Clinical Laboratories anchor current testing volume; Hospitals are capturing share fastest through vertical integration of genetic services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on laboratory-developed tests is accelerating CLIA-certified laboratory entry into high-complexity molecular diagnostics across multiple jurisdictions. National reimbursement policies for exome and genome sequencing are diverging, creating uneven clinical adoption patterns. Germany, the United States, India, the United Kingdom, and Japan concentrate specialized testing infrastructure and regulatory innovation.
United States
Commercial and government payers are establishing coverage pathways for proband-parent trio testing, reducing out-of-pocket burden for diagnostic odyssey patients. The FDA's evolving oversight framework for laboratory-developed tests standardizes analytical validation protocols. Boston Children's Hospital anchors genome-first protocol adoption for congenital anomaly presentations.
Germany
Centogene N.V. anchors specialized rare disease testing infrastructure through its integrated biomarker and diagnostic platform. The EU In Vitro Diagnostic Regulation's notified body conformity assessment requirements impose capital-intensive quality management system upgrades. Reference laboratories in Rostock and Berlin pursue backward integration into IVD kit development.
India
High consanguinity-driven rare disease prevalence creates institutional demand for expanded carrier screening programs. The central pharmaceutical regulator streamlines genetic test import and registration processes. Strand Life Sciences in Bangalore exemplifies domestic capability buildout in next-generation sequencing interpretation.
United Kingdom
National Health Service procurement consolidation extracts price concessions from competing laboratories in exchange for volume commitments. Genomics England's 100,000 Genomes Project established analytical pipeline standards now diffusing into clinical practice. Cambridge and London clusters concentrate bioinformatics workforce development.
Japan
PMDA regulatory pathways for companion diagnostics create convergence opportunities between rare disease diagnosis and therapeutic selection. METI funding priorities favor domestic sequencing platform development to reduce reagent import dependence. Tokyo and Osaka academic medical centers lead Asia-Pacific adoption of long-read sequencing platforms.
Rare Disease Genetic Testing Market Key Industry Players
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions. The vendor base stratifies into three tiers: national laboratory networks with CLIA-CAP dual accreditation, specialized rare disease boutiques with integrated diagnostic-biomarker platforms, and emerging entrants competing on test accessibility through physician-directed ordering channels. Dominant competitive moves include exclusive provider agreements with integrated delivery networks and embedded genetic counselor service bundling.
Within the specialized boutique tier, Centogene N.V. and Ambry Genetics exemplify integrated platform strategies spanning diagnostic testing and therapeutic development support. Quest Diagnostics occupies a position as the scale-driven national network anchor, leveraging broad geographic coverage for complex genetic assay logistics. Among emerging accessibility-focused entrants, 3billion, Inc. and Invitae Corp represent direct-to-physician ordering channel expansion beyond traditional academic medical center referral pathways.
| Leading Market Players |
|---|
| Quest Diagnostics Inc |
| Centogene N.V. |
| Invitae Corp |
| 3billion, Inc. |
| Arup Laboratories |
| Ambry Genetics |
| Strand Life Sciences |
| Eurofins Scientific |
| Myriad Genetics, Inc. |
| Others |
Cost & Logistics Intelligence
CLIA high-complexity certification and CAP accreditation simultaneously gate laboratory market entry and stratify pricing power across service tiers, compressing margins for uncredentialed operators while enabling premium positioning for dual-accredited facilities with embedded genetic counselor services.
Pricing Analysis
Certification level (CLIA-CAP versus CLIA-only versus uncredentialed) creates the primary spread in test pricing across the market. Per-unit transactional pricing dominates, with proband-parent trio testing commanding premium positioning against single-proband analysis. Cost compression in sequencing chemistry is intensifying price competition at the standard tier, eroding margins for laboratories lacking volume scale or interpretation automation. Academic medical centers exhibit lowest price sensitivity due to institutional procurement consolidation, while independent physician practices face highest out-of-pocket burden sensitivity.
Supply Chain Analysis
The United States and Germany anchor sequencing instrument and reagent manufacturing, with Singapore and South Korea emerging as flow cell production hubs. Consumable supply draws from Illumina's California and Singapore facilities, while analytical pipeline development centers on Boston and Cambridge bioinformatics clusters. Single-source vulnerability in sequencing chemistry creates structural risk for laboratories dependent on Illumina's instrument-locked reagent ecosystem. Distribution runs through CLIA-certified laboratory networks and hospital system procurement departments with exclusive provider arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Expansion of newborn screening programs and exome sequencing reimbursement pathways positions this market in early-cycle penetration growth, with state public health infrastructure buildout creating durable demand tailwinds.
For Market Incumbents: Fortify interpretation automation capabilities to offset variant classification workforce gaps compressing turnaround times. Pursue backward integration into long-read sequencing platforms to differentiate structural variant detection from short-read competitors. Lock in exclusive provider agreements with integrated delivery networks before health system procurement consolidation peaks. For New Entrants and Emerging Players: Community physician-directed ordering channels represent the most penetrable service-layer gap, as academic medical center referral pathways exclude substantial patient populations. Target point-of-care PCR configurations for urgent clinical scenarios where speed trumps analytical resolution. Deploy embedded genetic counselor telehealth services as the primary go-to-market wedge against established laboratory networks. For Investors and Strategic Acquirers: FDA's evolving LDT guidance reshapes the acquisition landscape by elevating compliance infrastructure value over raw test volume. Five-to-ten year viability favors specialized boutiques with integrated biomarker platforms and European IVD kit development capabilities. Monitor payer coverage determinations for whole genome sequencing as the critical inflection signal for laboratory capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS and commercial payer coverage pathways for trio testing determine patient access expansion velocity. |
| Hospital System Partnership | Exclusive provider agreements with integrated delivery networks lock in guaranteed volume commitments and counselor embedding. |
| CE Marking Pathway | EU IVDR Class C device classification requires notified body intervention, favoring laboratories with existing European quality infrastructure. |
| Software Companion Development | Automated variant interpretation pipelines address workforce gaps constraining laboratory scale-up regardless of instrument capacity. |
| Backward Integration into Long-Read Platforms | PacBio and Oxford Nanopore chemistry acquisition resolves structural variants invisible to short-read chemistry. |
Research Approach
Cross-validation between laboratory director interviews and payer policy documentation anchors the qualitative findings in operational reality. Primary fieldwork encompassed clinical laboratory directors, genetic counselors, hospital procurement managers, and payer medical policy leads. Secondary sources included FDA guidance documents, CMS national coverage determinations, state newborn screening program expansions, and CAP proficiency testing requirements. Bottom-up test volume modeling triangulated against top-down market sizing from sequencing instrument placement data.
Sensitivity analysis around reimbursement adoption curves and regulatory implementation timelines informs the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, technology platform, application setting, and end-user procurement authority. CAGRs derive from instrument capacity expansion, test menu growth, and payer coverage velocity. Forecast inputs weighted newborn screening program legislative mandates and exome sequencing medical necessity criteria evolution.
Forecasts assume regulatory continuity in FDA LDT oversight and EU IVDR implementation; material policy shifts would require re-modeling. Specific risks include Illumina supply disruption, variant classification workforce attrition, and payer coverage retraction for genome-first protocols. Recalibration cycles align with material shifts in reimbursement determinations and regulatory guidance finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
DNA Sequencing Services Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Digital Genome Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Genotyping Market
Genomics
Forensic Genomics Market
Genomics
United States DNA Sequencing Products Market
Genomics
Plant Genomics Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Genome Sequencing Market
Genomics
Molecular Breeding Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market