
 DNA Sequencing Services Market | 2026-2036
DNA Sequencing Services Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Sequencing Services Market Analysis
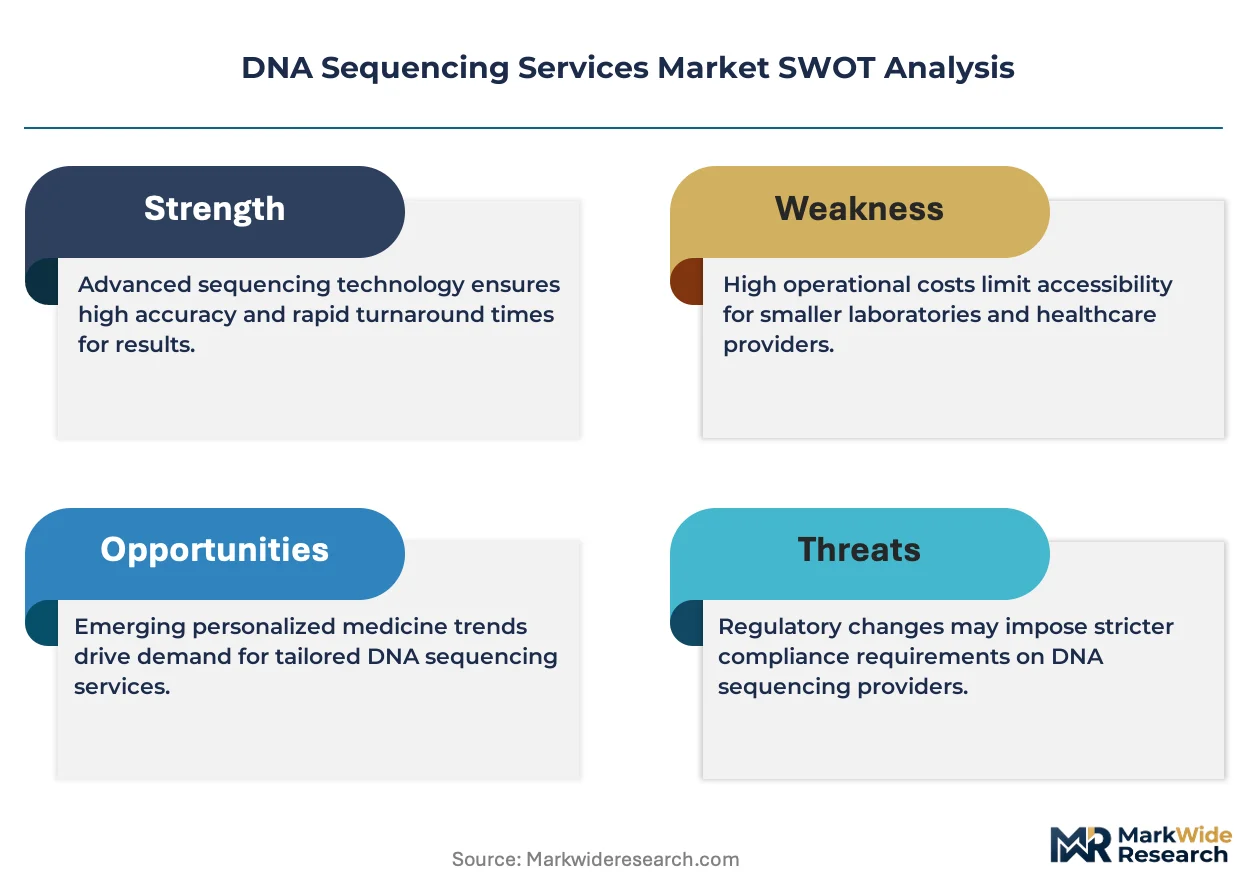
CLIA certification is redrawing competitive boundaries in DNA sequencing services, elevating barriers for new entrants while expanding addressable markets for incumbents. Illumina Inc. leverages its installed base of sequencing instruments to anchor captive service revenue streams. NeoGenomics Laboratories competes through oncology-focused laboratory networks with broad CLIA and CAP accreditations. BGI Group dominates population-scale whole genome projects through integrated sequencing and bioinformatics operations.
DNA sequencing services encompass the commercial provision of nucleic acid readout, bioinformatics analysis, and interpretive reporting using instruments capable of generating gigabase-to-terabase outputs per run. These services convert biological samples into actionable genetic data for research, clinical, and forensic decision-making. Next-Generation Sequencing services command the largest revenue share due to throughput economics and established reimbursement codes in oncology. Third-Generation Sequencing, led by Oxford Nanopore and PacBio platforms, is expanding fastest in structural variant detection and real-time pathogen surveillance where read length confers analytical advantage.
FDA oversight of laboratory-developed tests and companion diagnostics shapes service provider investment in analytical validation and quality management systems. The agency's evolving stance on artificial intelligence-enabled variant interpretation is creating new compliance dimensions for clinical reporting workflows. CAP accreditation requirements and state laboratory licensing regimes add layered jurisdictional complexity for multi-site operators. Stakeholders must monitor regulatory convergence between FDA, CMS, and state health departments as reimbursement policy increasingly ties to evidence generation standards rather than test complexity alone.
Market Dynamics
Pharmaceutical outsourcing of sequencing workflows is compressing in-house infrastructure investments while elevating vendor qualification standards around analytical validation and regulatory documentation.
Growth Catalysts
- Companion diagnostic pathways:FDA clearance requirements for oncology therapeutics are mandating parallel sequencing validation, expanding contracted service volumes from drug developers.
- Population genomics mandates:National health systems in the United Kingdom, Saudi Arabia, and Estonia are commissioning whole-genome sequencing at scale for rare disease diagnosis and preventive screening programs.
- Long-read platform maturation:Pacific Biosciences and Oxford Nanopore instruments are resolving structural variants and methylation patterns inaccessible to short-read methods, opening clinical applications in neurology and prenatal testing.
Market Restraints
- Reagent supply concentration:Illumina's control over sequencing chemistry and flow-cell manufacturing creates vulnerability to price adjustments and allocation constraints for independent service laboratories.
- Bioinformatics bottleneck:Variant interpretation pipelines require specialized computational infrastructure and curated reference databases that smaller operators cannot independently maintain.
- Reimbursement code lag:CMS and commercial payers maintain limited coverage policies for whole-exome and whole-genome sequencing outside narrow pediatric or oncology indications.
Strategic Opportunities
- Direct-to-consumer regulatory openings:Health Canada and Australia's TGA are establishing frameworks for physician-mediated genetic risk reporting, creating compliant channels beyond research-only restrictions.
- AI-enabled variant classification:Machine learning models trained on ClinVar and gnomAD datasets are accelerating pathogenicity determinations, reducing manual curation costs for high-volume service providers.
- Forensic database expansion:Law enforcement agencies in the United States are contracting rapid turnaround sequencing for unidentified remains and investigative genetic genealogy, bypassing clinical reimbursement constraints.
Industry Challenges
- CLIA certification timelines:New laboratory sites face 12-18 month validation periods for high-complexity molecular testing, delaying revenue generation and competitive response.
- Data interoperability standards:FHIR and GA4GH specifications remain inconsistently implemented across electronic health record systems, fragmenting patient data exchange for longitudinal genomic medicine.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Sequencing Services Market |
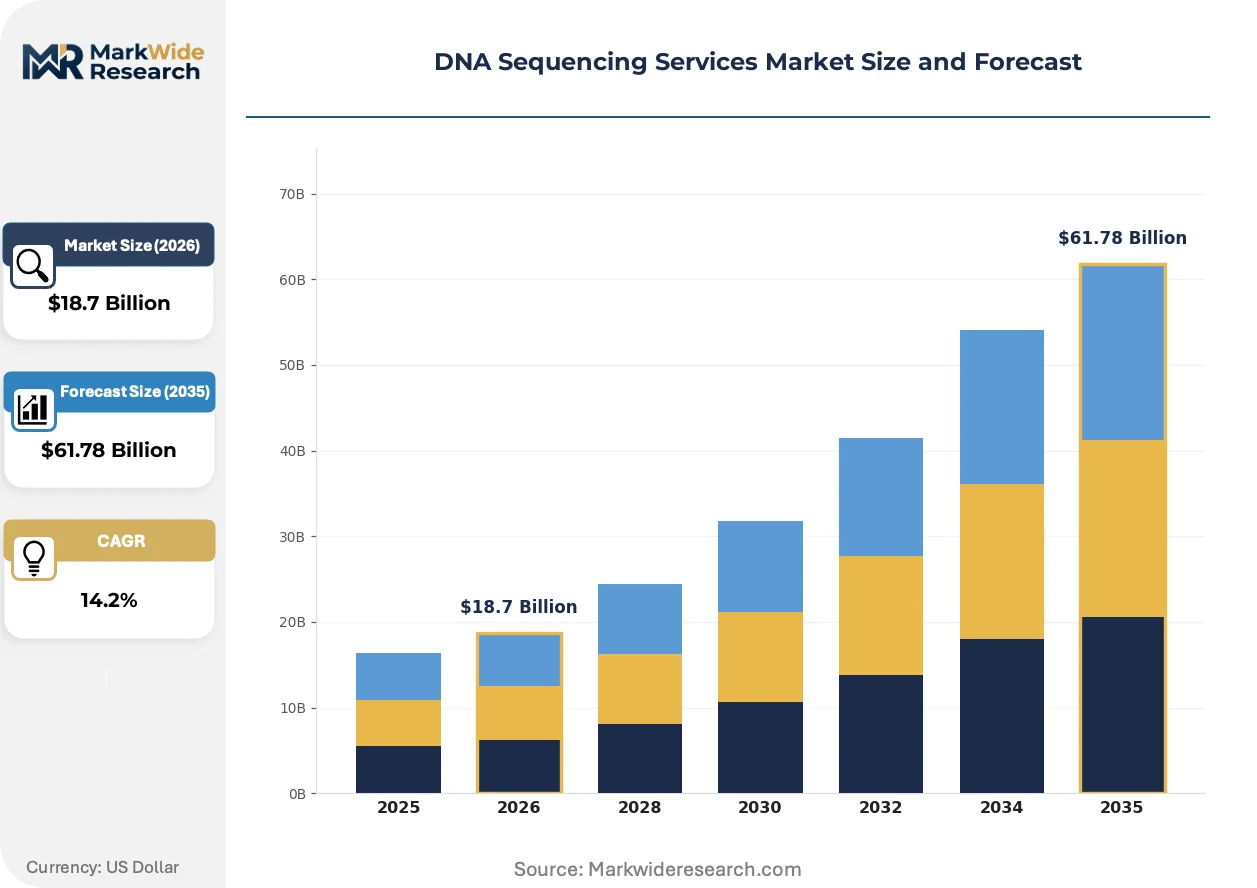
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sanger Sequencing, Next-Generation Sequencing, Third-Generation Sequencing, Whole Genome Sequencing End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Firms, Hospitals Application: Clinical Diagnostics, Agricultural Research, Genetic Testing, Forensic Analysis Technology: Illumina, Ion Torrent, PacBio, Oxford Nanopore |
| Companies Covered | Azenta US, Inc., SeqMatic, Illumina Inc., Danaher Corporation, NeoGenomics Laboratories, Novogene Co., Ltd., Psomagen, Oxford Nanopore Technologies, BGI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Sequencing Services Market Emerging Trajectories
Sequencing instrumentation is miniaturizing while computational demands expand, reshaping facility footprints and talent requirements across the service provider landscape.
Oxford Nanopore's Flongle and MinION platforms are miniaturizing field-deployable sequencing for outbreak surveillance and environmental monitoring. Public health agencies in Nigeria and Brazil are adopting these devices for real-time pathogen characterization without cold-chain logistics. The technology is miniaturizing laboratory infrastructure requirements, enabling point-of-need diagnostics that bypass centralized high-throughput facilities.
The European Union's In Vitro Diagnostic Regulation (IVDR) is reclassifying sequencing-based companion diagnostics as Class C devices requiring notified body review. Manufacturers and service providers are restructuring quality management systems and clinical evidence portfolios to meet 2028 transition deadlines. Oncology panels and pharmacogenomic assays face the steepest compliance burdens, with German and French laboratories accelerating IVDR technical documentation investments.
Academic medical centers are unbundling sequencing and interpretation services, contracting bioinformatics analysis to specialized vendors while retaining sample preparation and clinical reporting. This disaggregation is fragmenting traditional full-service relationships and pressuring integrated providers to demonstrate superior variant classification accuracy or turnaround speed. The pattern is most pronounced in the United States, where Stanford and Mayo Clinic have established preferred vendor networks for rare disease exome analysis.
DNA Sequencing Services Market Segmentation
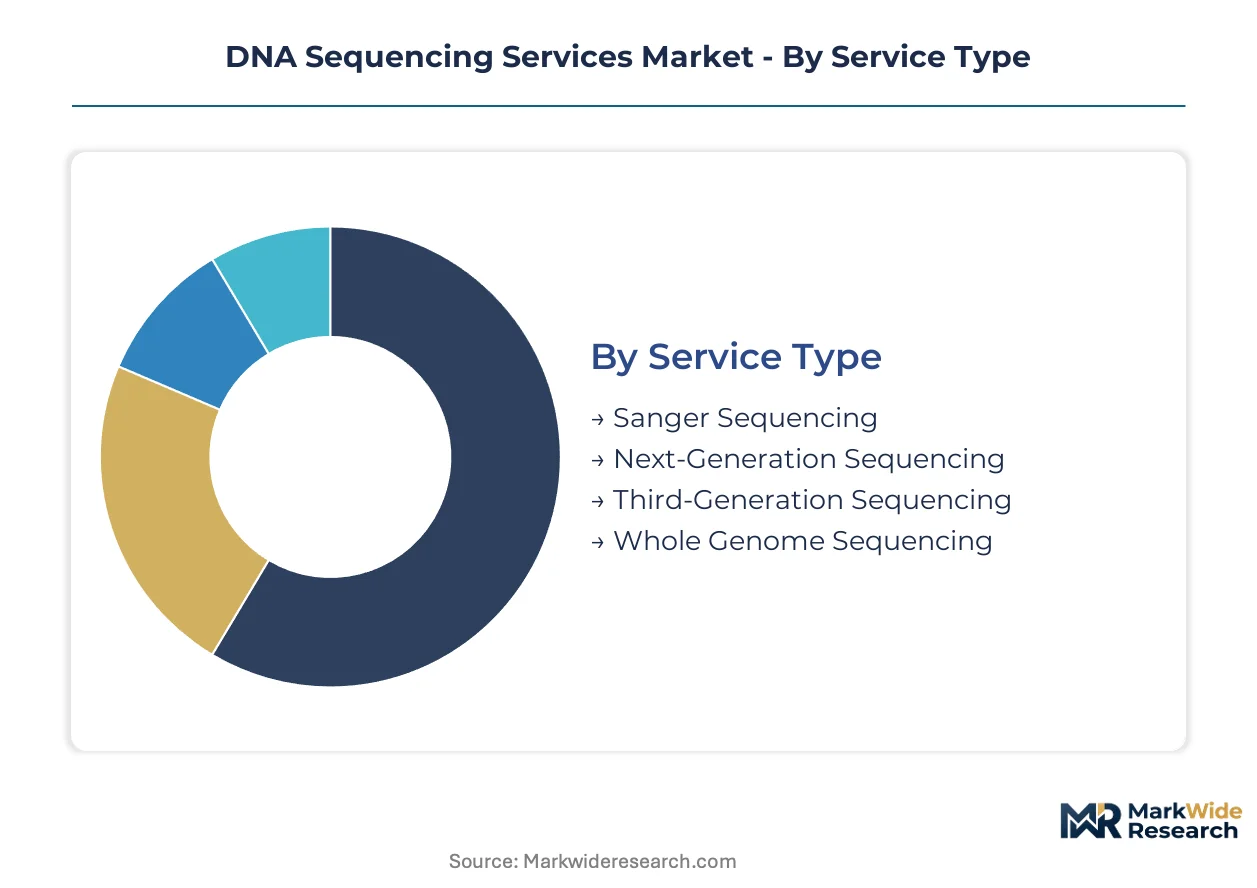
Service differentiation in DNA sequencing creates distinct competitive arenas where throughput economics, regulatory complexity, and interpretive depth determine vendor selection. Each segmentation axis reveals divergent margin structures and capability requirements that reshape provider investment priorities.
Service Type:
Substitution pressure intensifies where short-read platforms face displacement from long-read alternatives in structural variant detection and real-time applications.
- Sanger Sequencing:Capillary electrophoresis delivers high-accuracy reads up to 1,000 base pairs for targeted validation and forensic STR analysis. Demand concentrates in paternity testing laboratories and criminal DNA databases where chain-of-custody protocols mandate established methods. Regulatory acceptance in courts sustates volume despite higher per-base costs.
- Next-Generation Sequencing:Massively parallel short-read platforms generate gigabase outputs for exome panels and tumor profiling. Pharmaceutical outsourcing for companion diagnostic validation drives contracted throughput in the United States, particularly around FDA submission timelines.
- Third-Generation Sequencing:Single-molecule real-time and nanopore technologies resolve epigenetic modifications and complex rearrangements. Field-deployable MinION devices enable outbreak surveillance in Nigeria and Brazil without cold-chain infrastructure.
- Whole Genome Sequencing:Comprehensive nucleic acid readout supports rare disease diagnosis and population screening programs. National health systems in the United Kingdom and Saudi Arabia commission scaled contracts for preventive genomic medicine.
Next-Generation Sequencing retains volume leadership; Third-Generation Sequencing holds the steepest expansion curve.
End User:
Procurement sophistication varies sharply across customer types, with pharmaceutical qualification standards exceeding academic purchasing thresholds by an order of magnitude.
- Academic Institutions:Research universities and medical schools consume sequencing for hypothesis-driven discovery and grant-funded population studies. Budget constraints favor core facility access over dedicated infrastructure at smaller institutions.
- Biotechnology Companies:Venture-backed firms outsource entire workflows to preserve capital for therapeutic development. CLIA-certified partners with CAP accreditation command premium positioning for IND-enabling studies.
- Pharmaceutical Firms:Large drug developers contract companion diagnostic validation and biomarker discovery to specialized vendors. Analytical documentation requirements and FDA interaction experience filter supplier pools aggressively.
- Hospitals:Integrated delivery networks build in-house molecular pathology capabilities for oncology panel testing. Reimbursement code availability limits test menu expansion outside Medicare-covered indications.
Pharmaceutical Firms drive premium pricing; Biotechnology Companies represent the fastest volume expansion.
Application:
Reimbursement policy fragmentation creates divergent commercial models where clinical indications face coverage constraints absent from research or forensic channels.
- Clinical Diagnostics:Laboratory-developed tests for hereditary cancer and cardiovascular risk require analytical validation and physician ordering. CMS coverage determinations and commercial payer policies restrict whole-exome reimbursement to narrow pediatric indications.
- Agricultural Research:Crop breeding programs and livestock improvement initiatives utilize genotyping-by-sequencing for marker-assisted selection. Seed companies and university extension services concentrate demand in the United States Corn Belt and Brazilian soybean regions.
- Genetic Testing:Direct-to-consumer and physician-mediated risk reporting spans ancestry, carrier screening, and pharmacogenomics. Health Canada and Australia's TGA are establishing compliant frameworks beyond research-only restrictions.
- Forensic Analysis:Law enforcement agencies contract rapid-turnaround sequencing for unidentified remains and investigative genetic genealogy. Federal and state crime laboratories bypass clinical reimbursement constraints through dedicated appropriations.
Clinical Diagnostics anchors revenue concentration; Forensic Analysis gains share fastest as database expansion accelerates.
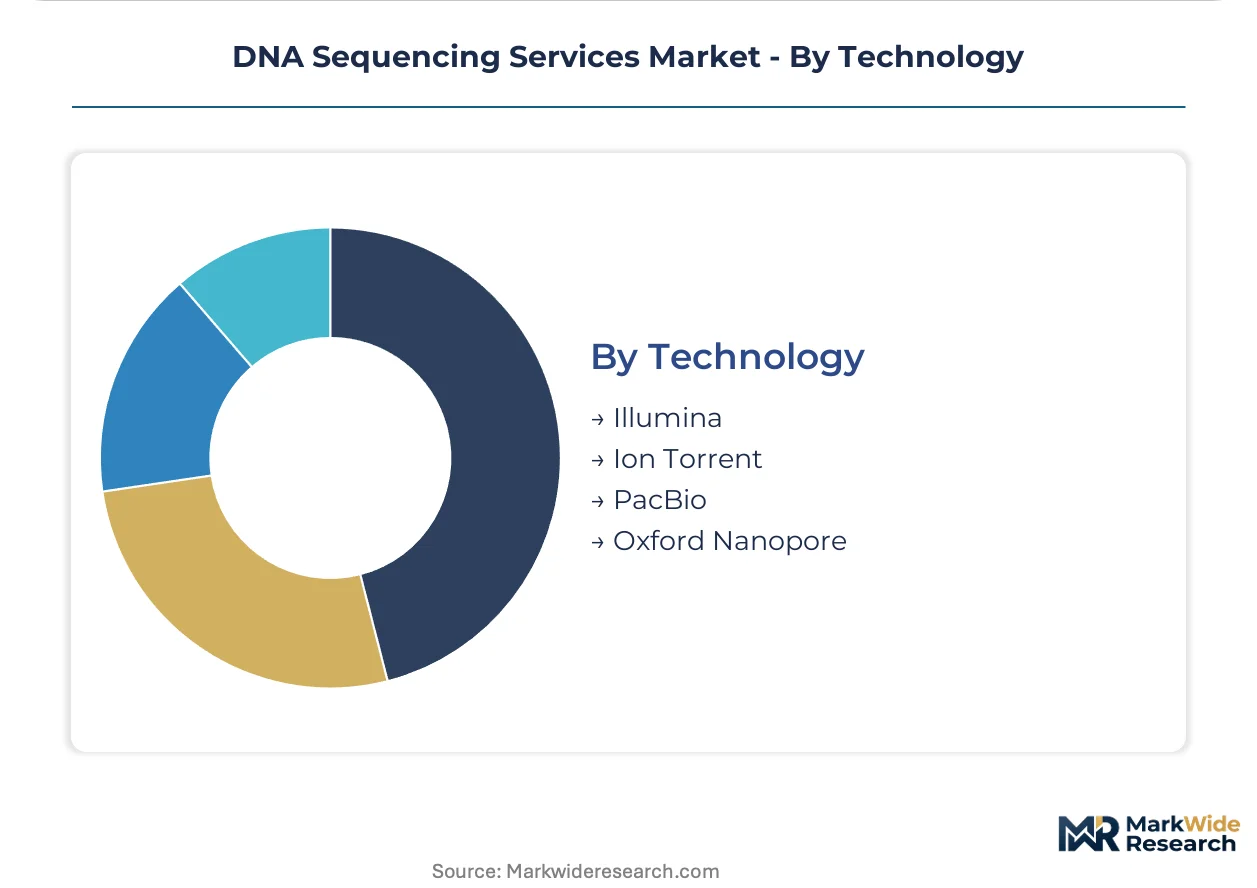
Technology:
Platform selection locks service providers into reagent supply relationships and bioinformatics ecosystems that constrain switching economics.
- Illumina:Dominant short-read ecosystem with established variant calling pipelines and largest installed base. Independent laboratories face vulnerability to flow-cell pricing and allocation decisions from the sole chemistry supplier.
- Ion Torrent:Semiconductor-based detection offers rapid turnaround for targeted oncology panels and infectious disease surveillance. Thermo Fisher's integrated instrument-reagent-content positioning serves mid-throughput clinical laboratories.
- PacBio:HiFi long-read sequencing resolves complex structural variants and tandem repeats for neurology and prenatal applications. Sequel IIe installations concentrate at reference genome centers and specialized service providers.
- Oxford Nanopore:Portable real-time sequencing enables field deployment and adaptive sampling for pathogen surveillance. GridION and PromethION scale from outbreak response to population-scale projects.
Illumina maintains installed base dominance; Oxford Nanopore captures the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical firms and academic medical centers concentrate sequencing procurement in jurisdictions with mature regulatory pathways for companion diagnostics and laboratory-developed tests. National genome programs and forensic database expansions are redistributing demand across specialized service hubs.
United States
FDA companion diagnostic mandates and CMS reimbursement policies shape service provider qualification standards. The Boston-Cambridge corridor anchors pharmaceutical outsourcing contracts for IND-enabling sequencing studies. California's Stanford and UCSF medical centers are unbundling bioinformatics analysis to specialized vendors.
United Kingdom
The National Health Service's Genomic Medicine Service commissions whole-genome sequencing for rare disease diagnosis at population scale. MHRA alignment with IVDR reclassification timelines pressures service laboratories to accelerate technical documentation. The Cambridge-London corridor concentrates academic-industry sequencing partnerships.
China
NMPA oversight of laboratory-developed tests and large-scale population screening programs drive domestic sequencing infrastructure investment. BGI Group anchors integrated sequencing and bioinformatics operations for national genome projects. Shenzhen and Beijing clusters concentrate instrument manufacturing and service provision.
Germany
IVDR transition deadlines and BfArM notification requirements reshape quality management investments for oncology panel providers. Heidelberg and Berlin medical centers maintain reference genome capabilities for European rare disease networks. German laboratories lead IVDR technical documentation preparation for Class C device reclassification.
Saudi Arabia
The Saudi Genome Program mandates whole-genome sequencing integration into primary healthcare for preventive genomic medicine. SFDA laboratory licensing requirements filter service provider qualification for clinical diagnostic contracts. Riyadh and Jeddah clusters concentrate national reference laboratory capacity and bioinformatics infrastructure.
DNA Sequencing Services Market Vendor Landscape
Player mix skews toward integrated platform manufacturers with captive service revenue streams and specialized clinical laboratories with multi-site accreditation networks. Market structure concentrates around instrument-installed-base advantages and regulatory certification depth. Two strategic archetypes dominate: platform-anchored service providers leveraging reagent lock-in, and oncology-focused laboratories competing on CLIA-CAP accreditation breadth. Competitive moves center on M&A for geographic expansion and strategic partnerships for AI-enabled variant interpretation capabilities.
Within the platform-anchored tier, Illumina Inc. and Oxford Nanopore Technologies occupy positions that exemplify divergent technology strategies—short-read dominance versus portable real-time deployment. NeoGenomics Laboratories represents the specialized clinical laboratory archetype with multi-site oncology focus. BGI Group anchors the integrated population-scale model combining sequencing infrastructure with bioinformatics operations. These three company patterns illustrate how competitive positioning depends on technology ecosystem control, regulatory certification depth, or vertical integration into national genome programs.
| Leading Market Players |
|---|
| Azenta US, Inc. |
| SeqMatic |
| Illumina Inc. |
| Danaher Corporation |
| NeoGenomics Laboratories |
| Novogene Co., Ltd. |
| Psomagen |
| Oxford Nanopore Technologies |
| BGI Group |
| Others |
Supply Flow & Price Mechanics
CLIA certification timelines gate both vendor qualification and price differentiation in DNA sequencing services, extending 12-18 months for high-complexity molecular testing while concentrating premium pricing power among incumbent laboratories with established accreditations. Pharmaceutical firms and academic medical centers face divergent procurement economics as regulatory documentation requirements filter supplier pools and compress margins for non-certified operators.
Pricing Analysis
Cost-plus contracts with reagent indexation dominate pharmaceutical outsourcing agreements, insulating service providers from Illumina flow-cell price adjustments while locking in margin structures. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited oncology laboratories from CLIA-only facilities and research-grade providers. Cost compression in standard-tier exome sequencing intensifies as academic medical centers unbundle bioinformatics analysis to specialized vendors. Biotechnology companies exhibit highest price sensitivity due to venture capital constraints, while pharmaceutical firms prioritize analytical validation depth over unit economics.
Supply Chain Analysis
Illumina's proprietary flow-cell chemistry creates a single-source chokepoint that constrains independent laboratory capacity planning and reagent allocation. Manufacturing concentrates in the United States, China, and Singapore, with BGI Group anchoring integrated sequencing infrastructure in Shenzhen and Beijing. Sequencing instruments, proprietary reagents, and curated bioinformatics databases constitute critical input dependencies. Tariff exposure on Chinese-manufactured consumables threatens margin stability for mid-tier service providers. Distribution runs through direct instrument-reagent bundling from platform manufacturers and specialized logistics networks for clinical sample chain-of-custody protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DNA sequencing services occupy an early-cycle expansion phase as FDA companion diagnostic mandates accelerate pharmaceutical outsourcing and population genomics programs penetrate national health systems. Long-read platform maturation in structural variant detection creates additional tailwinds for technology transition.
For Market Incumbents: Consolidate multi-site CLIA-CAP accreditation networks to defend against academic medical center unbundling of bioinformatics services. Deepen backward integration into proprietary variant interpretation pipelines to differentiate from AI-enabled vendor competition. Expand capacity in the Boston-Cambridge corridor where pharmaceutical outsourcing concentrates.
For New Entrants and Emerging Players: Anchor in forensic analysis and investigative genetic genealogy, where law enforcement appropriations bypass clinical reimbursement constraints and database expansion accelerates. Target rapid-turnaround sequencing contracts for unidentified remains as the most penetrable white-space segment. Pursue point-of-need deployment partnerships with public health agencies in Nigeria and Brazil using Oxford Nanopore field platforms.
For Investors and Strategic Acquirers: IVDR Class C reclassification deadlines reshape the acquisition landscape toward oncology panel providers with technical documentation readiness and notified body relationships. Five-to-ten year viability favors laboratories with dual FDA-EMA regulatory interaction experience and AI-enabled variant classification partnerships. Watch FDA artificial intelligence guidance evolution as the critical signal for clinical reporting workflow valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-CAP Multi-Site Expansion | Accelerates pharmaceutical vendor qualification for IND-enabling companion diagnostic studies. |
| AI-Enabled Variant Classification Partnership | Reduces manual curation costs using ClinVar and gnomAD-trained machine learning models. |
| Long-Read Platform Integration | Captures structural variant detection demand in neurology and prenatal testing applications. |
| Forensic Database Expansion Contract | Bypasses CMS reimbursement constraints through federal and state law enforcement appropriations. |
| IVDR Technical Documentation Investment | Secures Class C device continuity for oncology panels under European Union transition deadlines. |
Methodological Framework
A standing panel of laboratory directors, regulatory affairs specialists, pharmaceutical biomarker discovery leads, and hospital molecular pathology chiefs provided ongoing calibration against market developments. Primary interviews with service provider executives and procurement officers at academic medical centers combined with secondary validation from FDA 510(k) filings, CMS national coverage determinations, ClinicalTrials.gov sequencing protocol registrations, and CAP accreditation directories. Bottom-up service provider revenue estimates triangulated against top-down pharmaceutical R&D outsourcing expenditure analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including service type, end-user procurement sophistication, clinical versus research application, and platform technology ecosystem. CAGRs derived from instrument installed base expansion, reagent consumption curves, and contracted pharmaceutical study timelines. Forecast inputs incorporated IVDR transition deadlines, FDA artificial intelligence guidance evolution, and national genome program commissioning schedules.
Material uncertainties — regulatory approval delays for laboratory-developed tests, reagent supply allocation constraints, and reimbursement code expansion timelines — sit outside the modeled envelope. Forecasts reflect assumptions around companion diagnostic pathway maturation and long-read platform clinical adoption curves. Practitioners should keep alternative scenarios live as FDA artificial intelligence guidance and CMS coverage determination policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genomics and Transcriptomics Market
Genomics
AI in Genomics Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
United States DNA Sequencing Products Market
Genomics
Spatial OMICS Market
Genomics
Microarray Biochips Market
Genomics
Alagille Syndrome Market
Genomics
Gene Sequencing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Prenatal Genetic Testing Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
North America DNA Sequencing Products Market
Genomics
UAE Genetic Testing Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market