
 Non Invasive Prenatal Testing (NIPT) Market | 2026-2036
Non Invasive Prenatal Testing (NIPT) Market Size, Share, and Industry Trends Forecast 2026-2036
Non Invasive Prenatal Testing (NIPT) Market Intelligence
Project finance and leasing of sequencing platforms is rewriting competitive dynamics in prenatal diagnostics. Illumina, Inc. leverages its installed base of NovaSeq systems to dominate instrument placement contracts. Natera, Inc. sustains recurring revenue through proprietary Panorama test volumes in hospital networks. Laboratory Corporation of America Holdings anchors broad geographic coverage through its Quest Diagnostics partnership and independent specimen collection infrastructure.
Non Invasive Prenatal Testing analyzes cell-free fetal DNA circulating in maternal blood, typically extracted from plasma via venipuncture at gestational weeks 10 or later, with detection sensitivity exceeding 99 percent for trisomy 21. The technology serves obstetricians seeking to replace amniocentesis and chorionic villus sampling with safer first-trimester screening protocols. Sequencing-based tests occupy the largest revenue pool given their superior sensitivity for chromosomal abnormality detection, while digital PCR segments capture fastest growth in single-gene disorder screening applications. Bioinformatics algorithms represent a concentrated margin zone where specialized software vendors compete for platform integration contracts.
The FDA maintains active oversight of NIPT devices marketed as in vitro diagnostics, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements across European member states. China's NMPA accelerates review pathways for domestically manufactured cfDNA platforms under revised medical device classification rules. Stakeholders must monitor how reimbursement policy divergence between public health systems and private insurers reshapes test volume economics across patient access tiers.
Market Dynamics
The FDA's evolving oversight of laboratory-developed tests is compressing market access timelines while maternity clinics accelerate NIPT adoption as standard prenatal care. This regulatory-commercial tension is restructuring how cfDNA screening platforms reach obstetric networks.
Growth Catalysts
- First-trimester screening protocols:Obstetric practices across the United States are replacing amniocentesis with venipuncture-based cfDNA extraction at gestational week 10, eliminating procedure-related miscarriage risk.
- China's domestic screening programs:The NMPA's accelerated review pathways under revised medical device classification rules are expanding cfDNA platform deployment through state-backed maternal health initiatives.
- Sequencing sensitivity thresholds:Detection rates exceeding 99 percent for trisomy 21 are positioning NIPT as the clinical standard for chromosomal abnormality screening in high-risk pregnancies.
Market Restraints
- Instrument concentration risk:NovaSeq system placement contracts create dependency on a single sequencing hardware supplier for high-throughput laboratory operations.
- Reimbursement fragmentation:Divergence between public health system coverage and private insurer payment policies creates patient access tiering that compresses test volume economics.
- Technical limitation in single-gene disorders:Digital PCR segments face sensitivity constraints for rare variant detection compared to whole-genome sequencing approaches.
Strategic Opportunities
- Rural hospital network penetration:Independent specimen collection infrastructure enables geographic expansion beyond tertiary academic medical centers into community obstetric practices.
- EMA In Vitro Diagnostic Regulation compliance:Stricter clinical evidence requirements create first-mover advantage for laboratories with pre-submission quality management systems.
- AI-assisted variant interpretation:Convergence of machine learning algorithms with cfDNA bioinformatics is compressing reporting turnaround times for chromosomal microdeletion screening.
Industry Challenges
- Bioinformatics talent scarcity:Specialized software vendors compete for computational biologists capable of platform integration contract execution.
- Laboratory certification timelines:CAP and CLIA accreditation processes for cell-free DNA processing create 12-18 month operational delays for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Invasive Prenatal Testing (NIPT) Market |
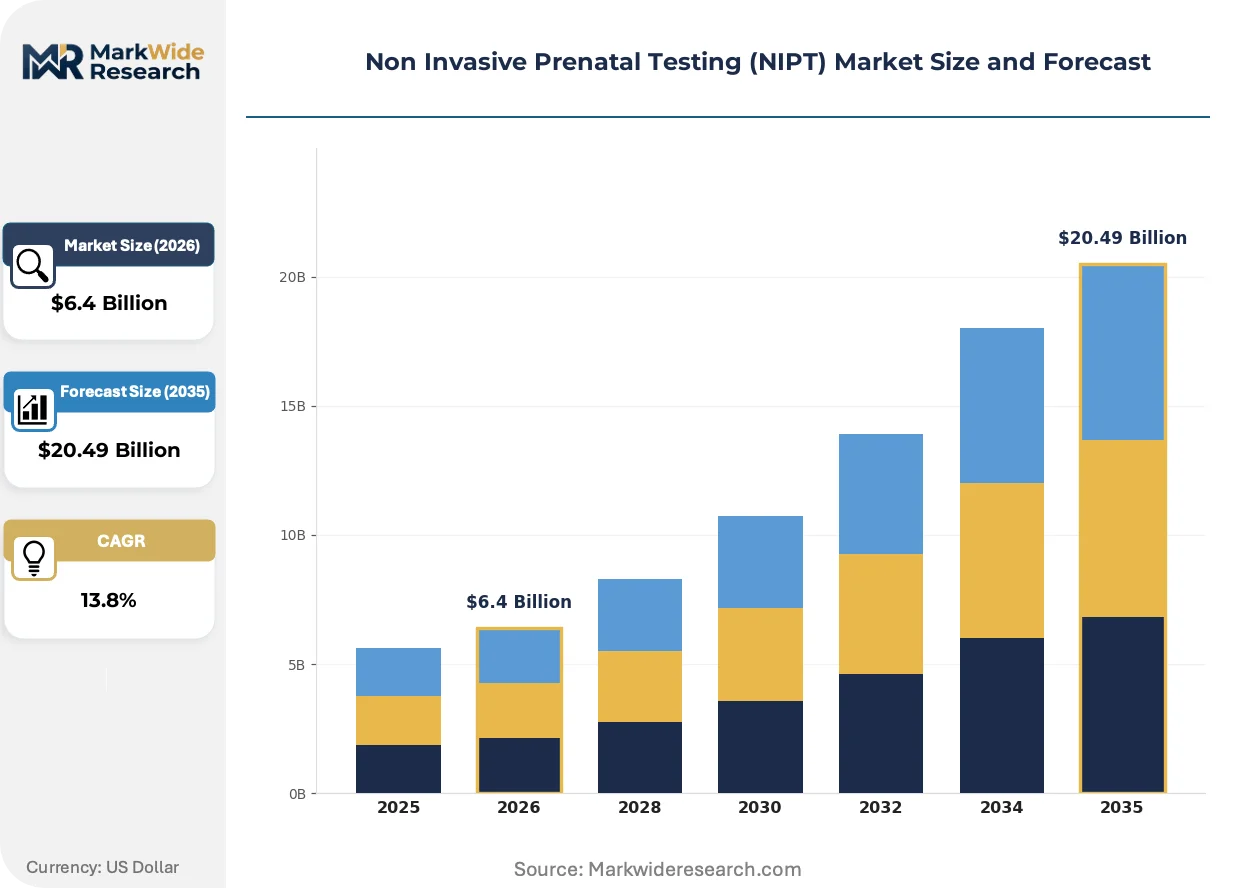
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $20.49 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing-Based Tests, Microarray-Based Tests, PCR-Based Tests, Combined Screening Tests, Targeted Mutation Analysis Technology: Next-Generation Sequencing, Digital PCR, Cell-Free DNA Analysis, Massively Parallel Sequencing, Bioinformatics Algorithms Application: Chromosomal Abnormality Detection, Single-Gene Disorder Screening, Fetal Gender Determination, Rh Incompatibility Assessment, Twin Pregnancy Screening End User: Diagnostic Laboratories, Maternity Clinics, Genetic Counseling Centers, Research Institutions, Specialty Hospitals |
| Companies Covered | Illumina, Inc., Natera, Inc., Laboratory Corporation of America Holdings, F. Hoffmann-La Roche Ltd, Eurofins LifeCodexx GmbH, BGI Genomics, Berry Genomics, PerkinElmer, Inc., Quest Diagnostics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Invasive Prenatal Testing (NIPT) Market Strategic Shifts & Innovations
Artificial intelligence is digitizing variant classification workflows while regulatory harmonization pressures reshape cross-border test commerce. These forces are converging to compress the interval between sample collection and clinical reporting.
Next-generation sequencing platforms are digitizing fetal fraction quantification through real-time quality metrics embedded in instrument control software. Hospital network laboratories are adopting these systems at 18-month replacement cycles to maintain competitive turnaround guarantees. This digitization is compressing the competitive moat between high-volume reference laboratories and mid-tier health system labs.
The EMA's In Vitro Diagnostic Regulation is mandating clinical performance studies with defined sensitivity specifications for chromosomal aneuploidy detection. European member states are requiring notified body involvement for class C device conformity assessments. Sequencing-based NIPT manufacturers are responding by establishing dedicated regulatory affairs functions in Germany and the Netherlands.
Obstetric group purchasing organizations are consolidating procurement decisions for prenatal screening panels across multi-hospital systems. Independent reference laboratories are losing direct contracting access as health systems centralize spend under single-source agreements. This concentration is most visible in the United States where Catholic health networks are standardizing NIPT vendor selection across 40-plus hospital affiliates.
Non Invasive Prenatal Testing (NIPT) Market Segmentation
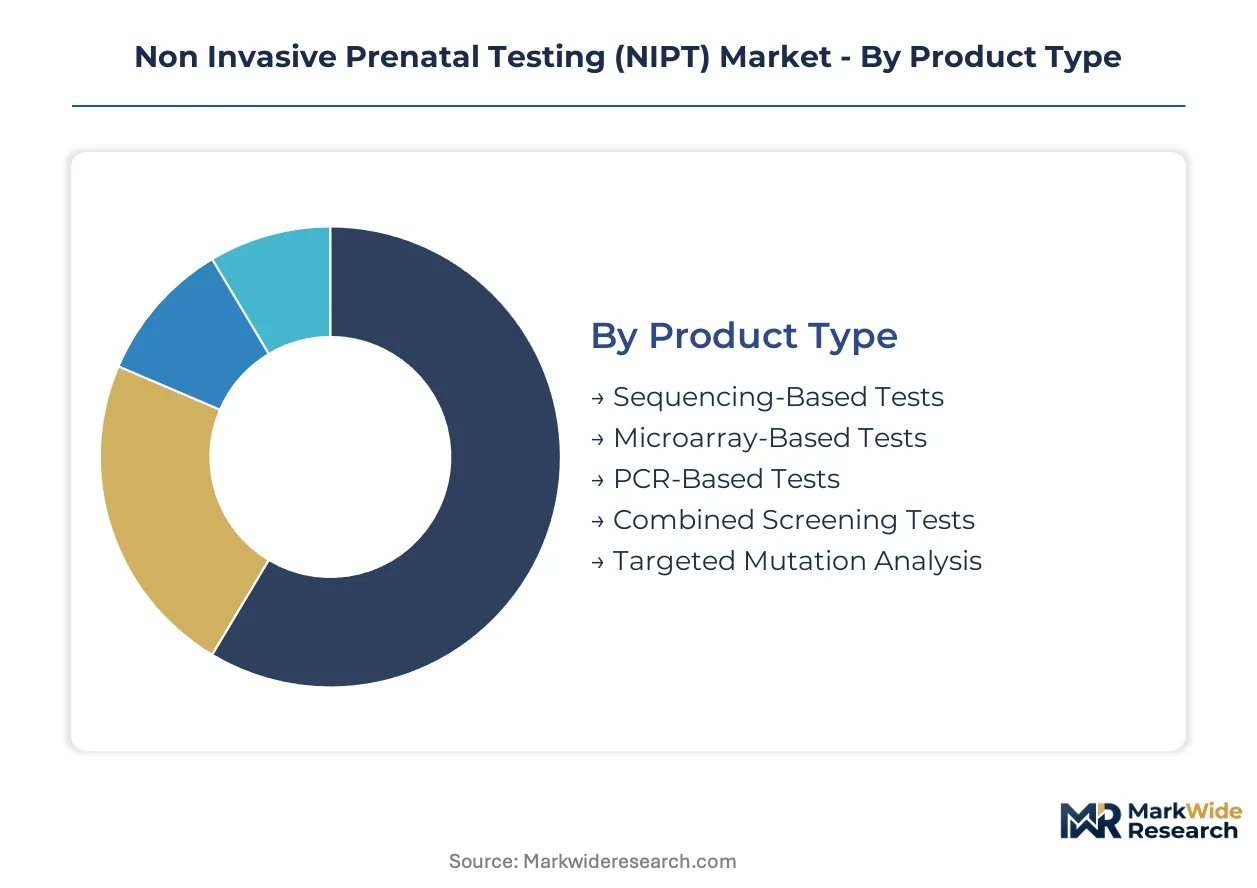
NIPT segmentation reveals how technology maturity and clinical application breadth shape procurement decisions across obstetric networks. Laboratories align platform selection with patient risk profiles, reimbursement codes, and turnaround requirements.
Product Type:
Mature sequencing platforms anchor high-volume operations while emerging modalities target specialized screening protocols.
- Sequencing-Based Tests:These platforms deploy whole-genome or targeted sequencing of cell-free fetal DNA to detect chromosomal aneuploidies with detection thresholds exceeding 99 percent for trisomy 21. Maternity clinics in the United States concentrate demand here as they replace invasive procedures with first-trimester venipuncture protocols.
- Microarray-Based Tests:Comparative genomic hybridization arrays identify subchromosomal deletions and duplications below the resolution of standard karyotyping. Genetic counseling centers in Germany and the Netherlands are expanding adoption following EMA In Vitro Diagnostic Regulation compliance requirements for microdeletion screening.
- PCR-Based Tests:Quantitative real-time PCR delivers rapid turnaround for single-locus mutations with lower capital equipment requirements.
- Combined Screening Tests:Integrating biochemical markers with cfDNA analysis refines risk stratification for intermediate-risk pregnancies.
- Targeted Mutation Analysis:Focused panels examine specific disease-causing variants in high-risk ethnic populations.
Sequencing-Based Tests retain volume leadership; Targeted Mutation Analysis holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive platforms from portable diagnostic workflows.
- Next-Generation Sequencing:Illumina NovaSeq and equivalent platforms enable high-throughput parallel processing of millions of DNA fragments simultaneously. Diagnostic laboratories in China leverage NMPA-accelerated review pathways to deploy these systems through state-backed maternal health infrastructure.
- Digital PCR:Absolute quantification of fetal DNA fractions without reference standards supports single-gene disorder screening with reduced sample input requirements. Research institutions in Japan are validating droplet-based partitioning for rare variant detection below 0.1 percent allele frequency.
- Cell-Free DNA Analysis:Isolation and enrichment of fetal DNA from maternal plasma underpins all NIPT modalities regardless of detection chemistry.
- Massively Parallel Sequencing:Semiconductor and optical detection systems generate terabase-scale outputs for population-scale screening programs.
- Bioinformatics Algorithms:Proprietary variant calling pipelines differentiate commercial offerings through false-positive rate optimization.
Next-Generation Sequencing commands the premium tier; Digital PCR is climbing the fastest among emerging technologies.
Application:
Customer type determines whether laboratories prioritize aneuploidy detection breadth or single-condition depth.
- Chromosomal Abnormality Detection:Screening for trisomies 21, 18, and 13 plus sex chromosome aneuploidies constitutes the foundational NIPT application. Maternity clinics across the United States have standardized this as first-line screening for all pregnancies regardless of maternal age.
- Single-Gene Disorder Screening:cfDNA-based detection of de novo and inherited mutations for conditions like cystic fibrosis and spinal muscular atrophy expands screening utility beyond chromosomal abnormalities. Specialty hospitals in Saudi Arabia are piloting expanded carrier screening panels through MOHAP-registered laboratories.
- Fetal Gender Determination:Y-chromosome detection enables early sex identification for X-linked disease risk assessment.
- Rh Incompatibility Assessment:Fetal RHD genotyping from maternal blood guides anti-D immunoglobulin administration decisions.
- Twin Pregnancy Screening:Algorithmic deconvolution of mixed fetal DNA signals supports zygosity determination and aneuploidy risk assignment.
Chromosomal Abnormality Detection generates the highest test volumes; Single-Gene Disorder Screening shows the steepest clinical adoption trajectory.
End User:
Geography and infrastructure availability dictate whether testing centralizes at reference laboratories or distributes to point-of-care settings.
- Diagnostic Laboratories:CAP-accredited and CLIA-certified high-complexity laboratories process tens of thousands of samples monthly with automated extraction and reporting workflows. Laboratory Corporation of America Holdings and equivalent networks in the United States dominate this channel through hospital system contracts.
- Maternity Clinics:Obstetric practices with in-house phlebotomy and courier logistics enable same-day specimen collection and reduced patient travel burden. Community clinics in India's tier-2 cities are expanding access through BIS-recognized laboratory partnerships.
- Genetic Counseling Centers:Pre-test and post-test consultation services integrate with specialized NIPT ordering for complex family histories.
- Research Institutions:Academic medical centers validate novel biomarkers and algorithmic approaches under institutional review board oversight.
- Specialty Hospitals:Fetal medicine units with dedicated maternal-fetal medicine specialists manage high-risk pregnancy screening protocols.
Diagnostic Laboratories capture the dominant share; Maternity Clinics are expanding most quickly through decentralized collection networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence between public health systems and private insurers is restructuring patient access tiers across major NIPT markets. State-backed maternal health initiatives in Asia-Pacific are accelerating platform deployment through domestic manufacturing incentives. Regulatory harmonization pressures in Europe are compressing market entry timelines for sequencing-based test providers.
United States
Obstetric group purchasing organizations are consolidating procurement decisions across multi-hospital Catholic health networks spanning 40-plus affiliates. The FDA maintains active oversight of devices marketed as in vitro diagnostics while laboratory-developed tests face evolving compliance pathways. Maternity clinics in Texas and Florida are expanding NIPT adoption as standard first-trimester care through independent specimen collection infrastructure.
China
Domestic screening programs anchored by BGI Genomics and Berry Genomics are capturing volume through state-backed maternal health infrastructure. The NMPA accelerates review pathways for domestically manufactured cfDNA platforms under revised medical device classification rules. Diagnostic laboratories in Beijing and Shanghai are deploying NovaSeq systems through project finance arrangements with instrument suppliers.
Germany
Genetic counseling centers are expanding microarray-based test adoption following EMA In Vitro Diagnostic Regulation compliance requirements for microdeletion screening. Notified body involvement for class C device conformity assessments is mandating clinical performance studies with defined sensitivity specifications. Sequencing manufacturers are establishing dedicated regulatory affairs functions in Berlin and Munich to manage notified body relationships.
Japan
Research institutions are validating droplet-based digital PCR approaches for rare variant detection below 0.1 percent allele frequency. The PMDA oversees clinical trial requirements for expanded carrier screening panels through MOHAP-registered laboratory partnerships. Academic medical centers in Tokyo and Osaka are piloting AI-assisted variant interpretation to compress reporting turnaround times.
Saudi Arabia
Specialty hospitals are piloting expanded single-gene disorder screening panels for high-risk ethnic populations through MOHAP-registered laboratory infrastructure. The SFDA regulates cfDNA platform registration under harmonized Gulf Cooperation Council medical device directives. Fetal medicine units in Riyadh are standardizing NIPT protocols across tertiary referral networks.
Non Invasive Prenatal Testing (NIPT) Market Key Industry Players
Channel-controlling players compete with product-specialist players for access to obstetric network procurement decisions. The market structure concentrates around three archetypes: sequencing platform manufacturers leveraging installed base dominance, reference laboratory networks capturing recurring test volumes through hospital contracts, and domestic Chinese players anchoring state-backed screening programs. Dominant competitive moves include strategic partnerships for specimen collection infrastructure and technology licensing agreements for bioinformatics algorithm integration.
Among US-based diagnostic service networks, Laboratory Corporation of America Holdings and Quest Diagnostics Incorporated occupy positions as channel-controlling reference laboratory archetypes. Illumina, Inc. represents the sequencing platform manufacturer archetype through instrument placement contract structures. Natera, Inc. exemplifies the product-specialist player competing through proprietary test menu differentiation. These three anchors illustrate how competitive positioning separates hardware-dependent revenue models from recurring test volume capture.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Natera, Inc. |
| Laboratory Corporation of America Holdings |
| F. Hoffmann-La Roche Ltd |
| Eurofins LifeCodexx GmbH |
| BGI Genomics |
| Berry Genomics |
| PerkinElmer, Inc. |
| Quest Diagnostics Incorporated |
| Others |
Cost & Logistics Intelligence
Air freight corridors connecting San Diego-Tijuana pharmaceutical clusters to Frankfurt distribution hubs carry sequencing reagents and consumables at rates that compress margins for mid-tier laboratories while amplifying price differentiation between CAP-certified reference labs and uncertified point-of-care operators.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium NIPT providers and commodity testing services. Three-tier pricing structure across premium, standard, and economy levels segments the market by turnaround guarantee and microdeletion panel breadth. Pricing pressure stems from obstetric group purchasing organizations consolidating multi-hospital contracts under single-source agreements. Community maternity clinics exhibit highest price sensitivity, while fetal medicine units in tertiary centers prioritize sensitivity thresholds over per-test cost.
Supply Chain Analysis
Contract manufacturing for sequencing flow cells and library prep kits concentrates at Illumina's San Diego facilities, Roche's Basel operations, and BGI Genomics' Shenzhen campuses. Raw material dependencies span semiconductor-grade silicon wafers, fluorescently labeled nucleotides, and stabilized fetal DNA collection tubes. Single-source vulnerability in NovaSeq instrument supply creates operational risk for high-throughput laboratories. Distribution runs through cold-chain logistics networks terminating at CAP-accredited processing centers, with specimen collection infrastructure decentralizing toward community obstetric practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from divergent regulatory timelines across FDA, EMA, and NMPA jurisdictions, creating geographic niches where compliance-first laboratories capture premium positioning before harmonization pressures consolidate procurement.
For Market Incumbents: Build bioinformatics algorithm moats through proprietary variant calling pipelines integrated with hospital laboratory information systems. Defensive consolidation moves center on acquiring independent specimen collection infrastructure in underserved rural obstetric networks and securing exclusive placement contracts for next-generation sequencing platforms before CLIA accreditation timelines delay competitor entry. Threat from digital PCR substitutes in single-gene disorder screening demands R&D investment in expanded carrier panels. For New Entrants and Emerging Players: Establish a beachhead in microarray-based microdeletion screening for genetic counseling centers in Germany and the Netherlands navigating EMA In Vitro Diagnostic Regulation compliance requirements. White-space targets include AI-assisted variant interpretation software licensing to mid-tier health system laboratories and droplet-based digital PCR validation for rare variant detection below 0.1 percent allele frequency. Go-to-market angle emphasizes 48-hour turnaround guarantees through courier-integrated specimen logistics. For Investors and Strategic Acquirers: Carve-out targets emerge from academic medical center spinouts holding validated cfDNA isolation protocols and institutional review board-approved biomarker datasets. Long-term viability over the coming decade hinges on regulatory affairs capabilities spanning multiple notified body jurisdictions. Acquisition target archetype combines CAP accreditation with proprietary bioinformatics pipelines. Signal to watch is NMPA approval velocity for domestic Chinese platforms as indicator of state-backed maternal health initiative expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive NIPT vendor status across Catholic health networks with 40-plus hospital affiliates secures recurring test volumes. |
| CE Marking Pathway | Notified body conformity assessment for class C devices under EMA In Vitro Diagnostic Regulation enables European market entry. |
| Software Companion Development | AI-assisted variant interpretation algorithms compress reporting turnaround times for chromosomal microdeletion screening. |
| Reimbursement Strategy | CMS Medicare coverage determination and private payer contract negotiation shape patient access tier economics. |
| Regulatory Affairs Function Establishment | Dedicated Berlin and Munich offices manage notified body relationships for sequencing-based test manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with obstetricians, maternal-fetal medicine specialists, laboratory directors, genetic counselors, and hospital procurement managers. Secondary validation drew from FDA 510(k) filings, EMA medical device database entries, NMPA registration records, hospital GPO contract repositories, and CAP accreditation directories. Bottom-up test volume modeling and top-down market sizing triangulated against instrument placement data and reagent consumption patterns.
Calibration against historical adoption curves for first-trimester screening protocols anchored projections across the analysis window. Segmentation dimensions modeled include product type, detection technology, clinical application, and end-user facility tier. CAGRs were derived from logistic diffusion curves fitted to reimbursement expansion timelines and regulatory approval velocity. Forecast inputs incorporated NMPA review pathway acceleration rates and EMA In Vitro Diagnostic Regulation implementation phasing.
Macroeconomic conditions sit as an overlay; deviation in public health system reimbursement rates or private insurance coverage policies would shift the trajectory. Forecasts reflect assumptions regarding regulatory harmonization pressures and instrument replacement cycle timing. Quarterly review of FDA laboratory-developed test guidance evolution and notified body capacity constraints is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Europe Epigenetics Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Genetic Testing Panels Market
Genomics
Mitochondrial DNA Market
Genomics
Gene Sequencing Market
Genomics
Global Genotyping Assay Market
Genomics
Plant Genomics Market
Genomics
Global Gene Expression Market
Genomics
DNA Diagnostics Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Europe DNA Sequencing Products Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market