
 Genetic Leukemia Detection Testing Market | 2026-2036
Genetic Leukemia Detection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Leukemia Detection Testing Market Foresight
Oncology clinics are reorganizing procurement priorities toward next-generation sequencing panels, pulling demand away from hospital-centric centralized testing. F. Hoffmann-La Roche Ltd anchors European distribution through its CE-IVD portfolio and deep hematopathology installed base. Thermo Fisher Scientific Inc. leverages its Ion Torrent platform to compete in clinical research settings where turnaround time commands premium positioning. Adaptive Biotechnologies Corporation specializes in minimal residual disease monitoring, a sub-area where clonoSEQ occupies distinct regulatory territory.
Genetic leukemia detection testing employs nucleic acid amplification, hybridization-based cytogenetics, and massively parallel sequencing to identify chromosomal translocations, gene fusions, and somatic mutations in hematologic malignancies. RT-PCR remains the workhorse for BCR-ABL1 quantification in chronic myeloid leukemia management, while next-generation sequencing is displacing single-gene assays in acute leukemia classification. Peripheral blood sampling is gaining share against bone marrow aspiration as liquid biopsy sensitivity improves, though marrow retains dominance in treatment-naive diagnosis. Flow cytometry and genetic profiling together define the methodological core, with immunophenotyping providing cell-lineage confirmation that sequencing alone cannot deliver.
FDA premarket authorization pathways and EMA IVDR conformity requirements shape product development timelines and commercial access for genetic leukemia assays. WHO classification updates for myeloid neoplasms and acute leukemia, now in their fifth edition, directly drive panel content decisions and reimbursement negotiations. Stakeholders must monitor how CMS coverage determinations for circulating tumor DNA assays reshape the economic boundary between research-use-only and clinical-grade testing in hematologic malignancies.
Market Dynamics
The transition from single-gene PCR assays to comprehensive NGS panels is restructuring procurement authority, shifting purchasing decisions from hospital laboratory directors toward oncology clinic administrators who control patient referral economics.
Growth Catalysts
- Companion diagnostic pathways:FDA and EMA premarket authorization frameworks for CDx-linked therapeutics are accelerating assay validation investments by test developers seeking drug-label inclusion.
- Liquid biopsy maturation:Peripheral blood sampling for minimal residual disease monitoring is expanding addressable testing volume beyond bone marrow-dependent workflows.
- WHO classification alignment:The fifth edition myeloid neoplasm guidelines are mandating genetic profiling integration into diagnostic criteria, forcing panel content upgrades.
Market Restraints
- Reagent supply concentration:Critical enzymes and fluorescent probes depend on a narrow base of North American and European specialty chemical suppliers.
- IVDR transition friction:European conformity assessment bottlenecks are extending time-to-market for novel assay submissions beyond historical CE-IVD timelines.
- Technical sensitivity floors:Detecting low-abundance somatic mutations in hematologic malignancies requires input material quantities that liquid biopsy platforms struggle to guarantee.
Strategic Opportunities
- Japan precision oncology infrastructure:PMDA accelerated approval pathways for genomic profiling tests create favorable regulatory terrain for hematologic panel entrants.
- Community oncology penetration:Decentralized NGS platforms enable testing capture outside academic medical centers where referral leakage currently concentrates.
- Artificial intelligence integration:Machine learning variant interpretation tools converge with cloud-based bioinformatics to reduce pathologist review burden and report turnaround time.
Industry Challenges
- Molecular pathologist scarcity:Interpretation of complex genomic findings in hematologic contexts requires specialized training that fellowship programs are not scaling to match test volume growth.
- LIMS integration complexity:Laboratory information management systems at mid-sized oncology practices lack API architectures that NGS data pipelines require, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Leukemia Detection Testing Market |
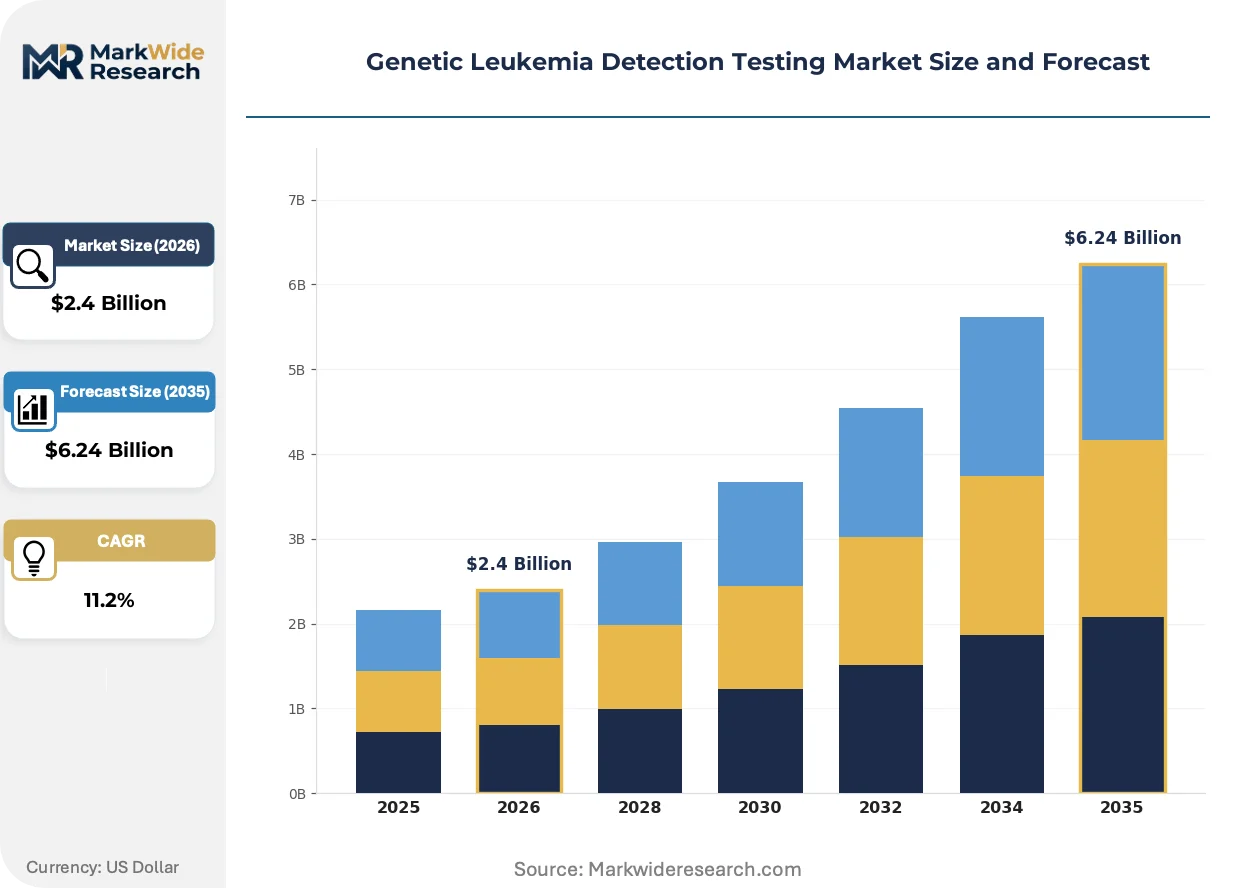
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: RT-PCR, Next-Generation Sequencing, FISH, Microarray End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncology Clinics Sample Type: Bone Marrow, Peripheral Blood, Lymph Node, Tissue Biopsy Methodology: In Vitro, Flow Cytometry, Immunohistochemistry, Genetic Profiling |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Sysmex Corporation, QIAGEN N.V., Guardant Health, Inc., Adaptive Biotechnologies Corporation, Invivoscribe Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Leukemia Detection Testing Market Shifts & Advancements
Next-generation sequencing platforms are fragmenting into distinct performance tiers, with hardware specialization diverging between high-throughput reference laboratories and rapid-turnaround clinical settings. This technological stratification is reshaping vendor competitive boundaries and customer switching economics.
Hybridization-capture NGS is bifurcating the leukemia testing market into two operational models. Amplicon-based panels dominate community oncology clinics where technical staff depth is limited and same-day result requirements are tightening. Academic medical centers with embedded bioinformatics cores are adopting exome-scale hybridization approaches that enable retrospective analysis and research protocol enrollment. The structural consequence is compressing price elasticity at the mid-panel tier, forcing vendors to anchor positioning at either extreme of the sensitivity-throughput spectrum.
EMA In Vitro Diagnostic Regulation enforcement is compressing commercial timelines for European market entry. Notified body capacity constraints are extending conformity assessment durations, prompting manufacturers to prioritize US FDA submissions as primary regulatory milestones. Hematologic oncology assay developers are responding by front-loading clinical validation studies to support parallel regulatory dossiers rather than sequential geography rollouts.
Clinic administrators are consolidating testing contracts through integrated delivery networks, displacing the physician-directed laboratory selection that historically governed leukemia assay procurement. Large oncology group purchasing organizations in the United States are extracting volume commitments in exchange for preferred vendor status, compressing margins for manufacturers who lack differentiated turnaround time or report content. This concentration is most visible in Texas and Florida, where multi-site hematology practices have achieved sufficient scale to demand custom bioinformatics deliverables.
Genetic Leukemia Detection Testing Market Segmentation
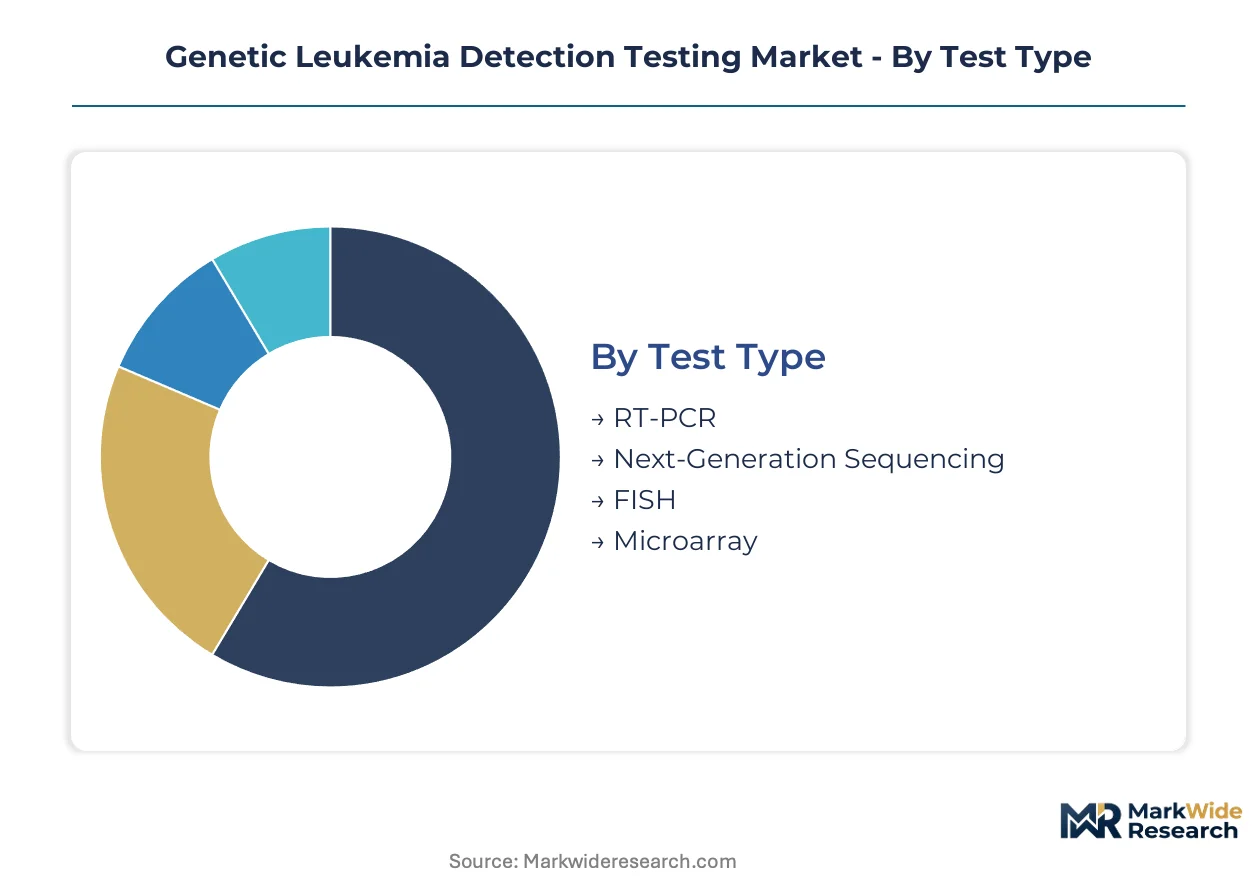
Leukemia testing segmentation reveals how procurement authority, sample logistics, and regulatory pathways fragment commercial opportunity. Each dimension carries distinct margin profiles and competitive entry barriers that reshape vendor positioning across clinical and research settings.
Test Type:
Domestic demand concentrates in RT-PCR and NGS platforms where hospital laboratory infrastructure already exists; FISH and microarray segments rely more heavily on export markets and research contract volume.
- RT-PCR:Quantitative amplification remains the clinical standard for BCR-ABL1 monitoring in chronic myeloid leukemia management. United States oncology clinics drive procurement volume through Medicare reimbursement for molecular response assessment. Reagent supply concentration from North American specialty chemical vendors creates procurement risk during demand surges.
- Next-Generation Sequencing:Massively parallel sequencing displaces single-gene assays in acute leukemia classification panels. Germany and Japan precision oncology infrastructure commands premium positioning for comprehensive genomic profiling. Turnaround time compression and bioinformatics integration determine competitive differentiation.
- FISH:Fluorescence in situ hybridization retains dominance for chromosomal translocation visualization in specific subtypes.
- Microarray:Array-based comparative genomic hybridization serves research protocols and retrospective analysis in academic medical centers.
RT-PCR holds the largest share; momentum sits with Next-Generation Sequencing.
End User:
Cost tier stratification separates capital-intensive hospital installations from leaner clinic-based models where per-test economics dominate procurement decisions.
- Hospitals:Integrated health systems anchor reference laboratory infrastructure with embedded hematopathology expertise. Centralized testing captures complex case referrals from community oncology practices. Capital equipment amortization and FTE pathologist coverage create high fixed-cost structures.
- Oncology Clinics:Decentralized NGS platforms enable same-day result requirements and patient retention. Texas and Florida multi-site hematology practices extract volume commitments through group purchasing organization consolidation. Technical staff depth limitations favor amplicon-based panel simplicity.
- Diagnostic Laboratories:Independent reference labs compete on turnaround time and custom bioinformatics deliverables.
- Research Institutions:Exome-scale hybridization approaches support protocol enrollment and retrospective discovery analysis.
Hospitals retain volume leadership; Oncology Clinics are expanding most quickly.
Sample Type:
Application urgency differentiates acute diagnostic settings requiring marrow aspirate from surveillance monitoring where peripheral blood convenience reshapes patient compliance.
- Peripheral Blood:Liquid biopsy sensitivity improvements are displacing bone marrow dependence for minimal residual disease surveillance. Japan PMDA accelerated approval pathways favor blood-based assay validation investments. Sample collection logistics reduce patient burden and expand testing frequency.
- Bone Marrow:Aspiration retains diagnostic authority for treatment-naive acute leukemia classification and initial cytogenetic assessment. United States academic medical centers maintain marrow-centric protocols for WHO fifth edition compliance. Invasive collection requirements limit repeat testing economics.
- Lymph Node:Excisional biopsy supports specific lymphoid neoplasm subtyping where circulating tumor DNA sensitivity remains inadequate.
- Tissue Biopsy:Solid tissue specimens serve extramedullary disease presentation and rare histologic transformation cases.
Bone Marrow holds the largest share; Peripheral Blood is gaining share fastest.
Methodology:
Customer type specialization separates high-throughput in vitro diagnostic manufacturers from analytical service providers integrating multiple technical modalities.
- Genetic Profiling:Comprehensive nucleic acid analysis combines sequencing, amplification, and hybridization for integrated leukemia classification. European EMA IVDR conformity requirements extend validation timelines for multi-platform assay submissions. Cloud-based variant interpretation tools reduce pathologist review burden.
- Flow Cytometry:Immunophenotyping delivers cell-lineage confirmation that sequencing alone cannot provide for mixed phenotype acute leukemia. United States community oncology penetration depends on technical staff training scalability. Instrument standardization across network sites enables quality consistency.
- In Vitro:CE-IVD and FDA-cleared reagent kits anchor regulatory-compliant clinical testing workflows.
- Immunohistochemistry:Protein expression analysis supports morphologic correlation and targeted therapy selection in specific subtypes.
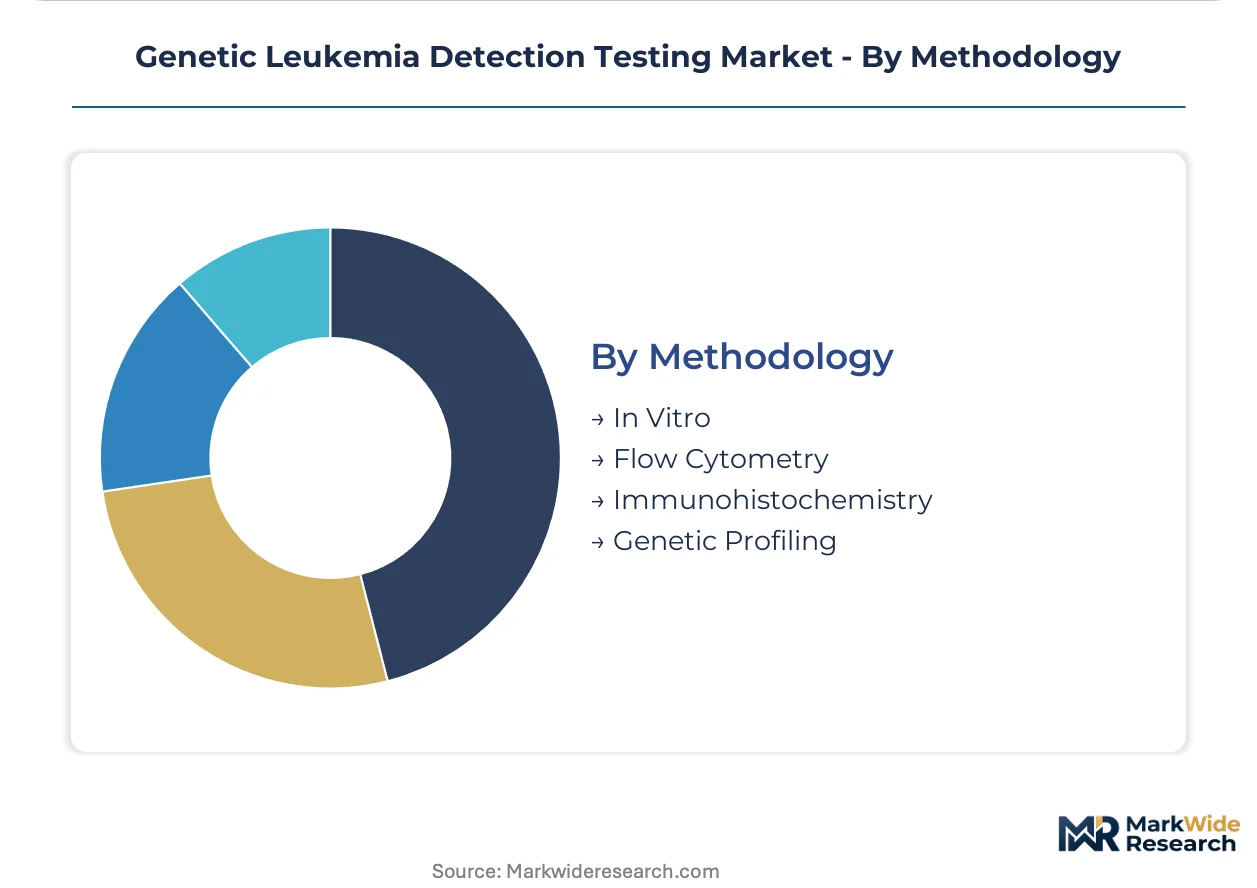
Genetic Profiling holds the largest share; Flow Cytometry maintains steepest expansion trajectory through platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors transatlantic precision oncology infrastructure through the FDA's premarket authorization pathways, while Japan's PMDA accelerated approval frameworks and Germany's EMA-notified body density create complementary regulatory poles for assay commercialization.
United States
Oncology clinic administrators in Texas and Florida now control procurement authority through group purchasing organization consolidation. FDA companion diagnostic pathways for CDx-linked therapeutics accelerate assay validation investments by developers seeking drug-label inclusion. The Greater Boston corridor houses reference laboratories embedding hematopathology expertise for complex case referrals.
Germany
EMA IVDR conformity assessment bottlenecks extend time-to-market for novel assay submissions beyond historical CE-IVD timelines. The country's national pharmaceutical regulator enforces stringent clinical validation requirements for hematologic oncology panels. The Rhine-Ruhr metropolitan region concentrates notified body capacity and hematopathology training programs.
Japan
PMDA accelerated approval pathways for genomic profiling tests create favorable regulatory terrain for hematologic panel entrants. METI precision oncology infrastructure investments expand peripheral blood-based assay validation. The Kanto region around Tokyo hosts the highest density of clinical trial sites for liquid biopsy sensitivity studies.
United Kingdom
NHS England's genomic medicine service mandates genetic profiling integration into leukemia diagnostic pathways. The national pharmaceutical regulator aligns with EMA frameworks while maintaining distinct MHRA post-Brexit submission requirements. The Cambridge-Oxford-London triangle anchors academic medical centers adopting exome-scale hybridization approaches.
Switzerland
Swissmedic maintains recognition agreements with FDA and EMA that streamline parallel regulatory dossier submissions. The country's pharmaceutical regulator emphasizes quality management system audits for IVD manufacturers. Basel's pharmaceutical cluster drives demand for companion diagnostic co-development partnerships.
Genetic Leukemia Detection Testing Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier capacity and hematopathology installed base depth. The vendor base stratifies into three tiers: diversified life science conglomerates with CE-IVD portfolios, platform-focused sequencing specialists, and minimal residual disease monitoring pure-plays. Strategic archetypes include reference laboratory anchors, decentralized clinic enablers, and CDx co-development partners. Competitive moves concentrate on IVDR transition readiness and artificial intelligence variant interpretation integration.
Among diversified diagnostic conglomerates, F. Hoffmann-La Roche Ltd and Abbott Laboratories exemplify the reference laboratory anchor archetype through deep hematopathology installed bases. Thermo Fisher Scientific Inc. occupies a position within the platform-specialist tier, competing in clinical research settings where turnaround time commands premium positioning. Adaptive Biotechnologies Corporation represents the pure-play monitoring specialist, with clonoSEQ occupying distinct regulatory territory in minimal residual disease surveillance.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Sysmex Corporation |
| QIAGEN N.V. |
| Guardant Health, Inc. |
| Adaptive Biotechnologies Corporation |
| Invivoscribe Technologies, Inc. |
| Others |
Supply & Pricing Matrix
FDA premarket authorization and EMA IVDR conformity regimes simultaneously gate supplier qualification and stratify price tiers across the genetic leukemia detection testing landscape. Reagent manufacturers must absorb validation costs for both regulatory pathways, compressing margins at the economy tier while premium-positioned vendors extract markups from oncology clinic administrators seeking single-source contracting simplicity.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between oncology group purchasing organizations and assay manufacturers. Three-tier pricing separates FDA-cleared companion diagnostic panels from CE-IVD standard assays and research-use-only economy alternatives. Price differentiation hinges on turnaround time guarantees and bioinformatics integration depth. Cost compression in the standard tier intensifies as community clinics consolidate contracts through integrated delivery networks. Hospital laboratory directors exhibit lowest price sensitivity due to embedded hematopathology expertise and capital amortization structures.
Supply Chain Analysis
The United States and Germany anchor production of critical enzymes and fluorescent probes for nucleic acid amplification workflows. Japan manufactures specialized hybridization reagents for cytogenetic applications. Raw material dependencies center on thermostable polymerases, fluorophore-labeled oligonucleotides, and magnetic bead separation matrices. Single-source vulnerability concentrates in North American specialty chemical suppliers during demand surges for minimal residual disease monitoring kits. Distribution runs through regional reference laboratory hubs that feed decentralized oncology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genetic leukemia detection testing market represents a high-growth disruption driven by WHO fifth edition classification mandates integrating genomic profiling into diagnostic criteria. This regulatory inflection forces panel content upgrades and reshapes procurement authority toward clinic administrators controlling patient referral economics.
For Market Incumbents: Consolidate hematopathology installed base depth through exclusive bioinformatics service contracts with multi-site hematology practices in Texas and Florida. Acquire cloud-based variant interpretation capabilities to defend against artificial intelligence pure-plays eroding pathologist review revenue. Lock in reagent supply commitments from North American enzyme manufacturers before IVDR transition bottlenecks extend procurement timelines.
For New Entrants and Emerging Players: Japan PMDA accelerated approval pathways offer fastest regulatory traction for peripheral blood-based minimal residual disease assays. Target community oncology penetration outside academic medical centers where technical staff depth limitations favor amplicon-based panel simplicity. Pursue white-label manufacturing partnerships with established IVD conglomerates lacking liquid biopsy sensitivity expertise.
For Investors and Strategic Acquirers: EMA IVDR enforcement reshapes the acquisition landscape toward US-domiciled assets with FDA premarket authorization already secured. Position portfolios for five-to-ten year holding periods as molecular pathologist scarcity creates interpretation bottleneck value capture opportunities. Monitor CMS coverage determinations for circulating tumor DNA assays as the signal indicating shift from research-use-only to clinical-grade testing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA drug-label inclusion secures exclusive assay positioning for targeted therapeutics in chronic myeloid leukemia management. |
| Artificial Intelligence Variant Interpretation | Machine learning tools reduce pathologist review burden and compress report turnaround time for community oncology clinics. |
| Liquid Biopsy Sensitivity Advancement | Peripheral blood assay validation expands addressable volume beyond bone marrow-dependent minimal residual disease workflows. |
| Integrated Delivery Network Contracting | Group purchasing organization consolidation in Texas and Florida extracts volume commitments and compresses vendor margins. |
| EMA IVDR Parallel Dossier Submission | Front-loaded clinical validation studies support simultaneous FDA and European regulatory pathways rather than sequential geography rollouts. |
Research Methodology
The analysis maps RT-PCR, next-generation sequencing, FISH, and flow cytometry sub-sectors, each validated through hematopathologists, oncology clinic administrators, diagnostic laboratory directors, and group purchasing organization contract managers. Primary interview insights triangulate against FDA 510(k) filings, EMA IVDR submission databases, CMS Medicare reimbursement schedules, and WHO classification guideline updates. Bottom-up test volume modeling converges with top-down precision oncology infrastructure spending analysis across the United States, Germany, and Japan.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends and academic medical center capital expenditure disclosures. The analytical framework segments by test type, end user, sample type, and methodology across the projection horizon. CAGRs derive from installed base expansion rates, reimbursement trajectory assumptions, and technology substitution elasticities. Forecast inputs incorporate PMDA approval pathway timelines, IVDR notified body capacity constraints, and liquid biopsy sensitivity improvement curves.
Underlying assumptions cover regulatory pathway stability, reagent supply continuity, and molecular pathologist training pipeline scaling, with deviation risk concentrated in EMA IVDR transition bottlenecks and CMS coverage determination timing. Forecasts reflect these conditions with acknowledgment that WHO classification updates, companion diagnostic pathway reforms, or reimbursement policy shifts could materially revise trajectory. Recalibration cycles align with material shifts in regulatory enforcement patterns, precision oncology infrastructure investments, and minimal residual disease monitoring clinical adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
DNA Mass Ladder Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Microarray Scanners Market
Genomics
Human Genetics Market
Genomics
Genetic Testing Panels Market
Genomics
Next Generation Genomics Market
Genomics
Pharmacogenomics Technology Market
Genomics
Next Generation Sequencing Market
Genomics
Mitochondrial DNA Market
Genomics
Mrna Sequencing Market
Genomics
APO E Gene Test Kit Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Global Pharmacogenomics Market
Genomics
Plant Genomics Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Genomics and Transcriptomics Market