
 Europe Epigenetics Market | 2026-2036
Europe Epigenetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Epigenetics Market Foresight
Software-defined bioinformatics analysis is decoupling raw instrument sales from recurring revenue in the Europe epigenetics landscape. Illumina Inc. leverages its cloud-based informatics platform to extend customer retention beyond hardware replacement cycles. Thermo Fisher Scientific anchors its European position through integrated reagent-instrument bundles that tighten laboratory switching costs. QIAGEN competes on sample-to-insight workflow automation, reducing manual intervention in methylation profiling protocols.
Epigenetics encompasses heritable changes in gene expression that occur without alterations to the underlying DNA sequence, primarily through DNA methylation, histone modification, and non-coding RNA mechanisms, typically detected via bisulfite conversion followed by sequencing or array-based interrogation with sensitivity thresholds reaching single-base resolution. These molecular signatures enable disease stratification, therapeutic target identification, and patient selection in precision medicine programs across European healthcare systems. Sequencing technologies command the dominant share of technology spending as clinical-grade methylation panels replace research-only assays. Reagents and kits represent the most rapidly expanding product category, driven by recurring consumable demand in high-throughput academic and contract research laboratories.
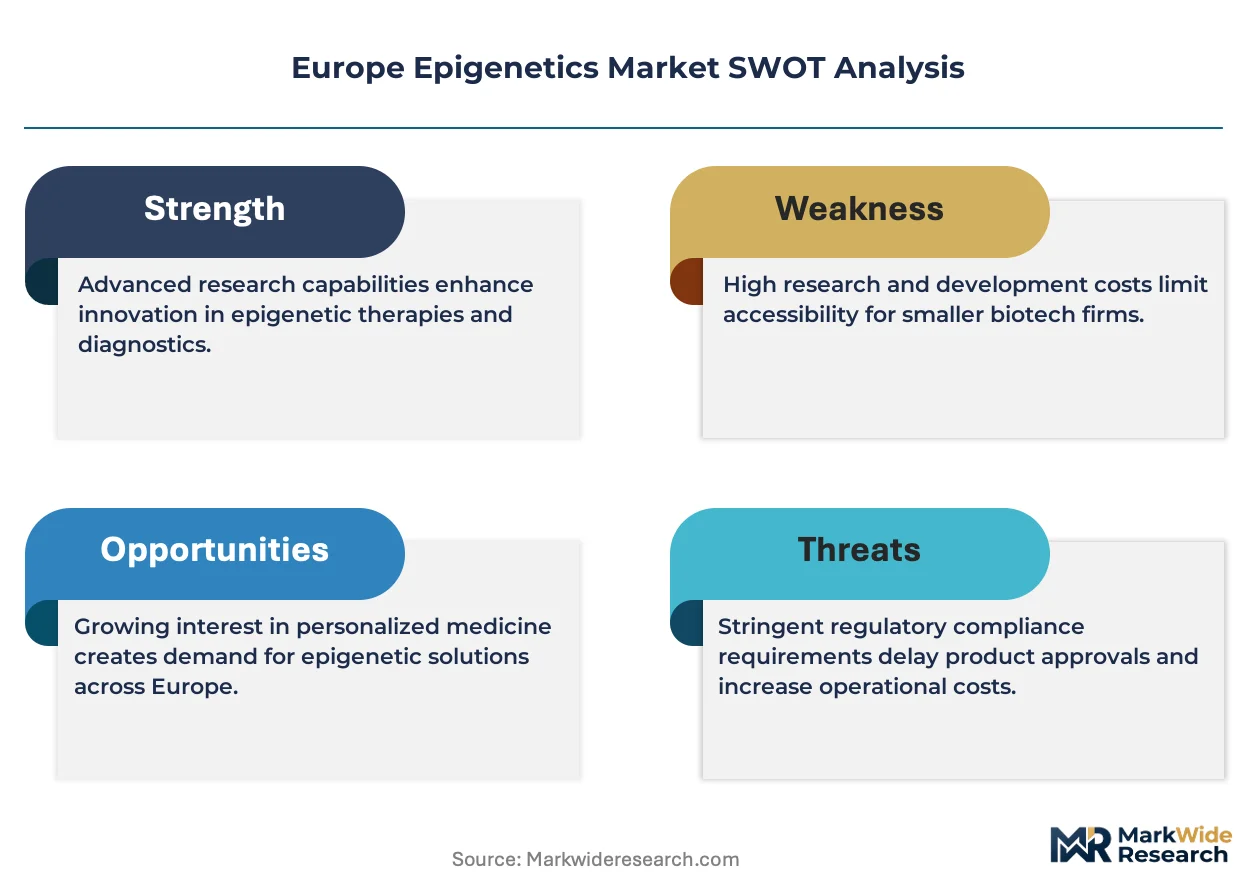
EMA biomarker qualification pathways and the EU In Vitro Diagnostic Regulation reshape product development timelines, forcing manufacturers to generate clinical evidence earlier in the commercialization process. REACH compliance for chemical reagents and the EU AI Act's risk classification framework for diagnostic algorithms add parallel compliance layers for software-integrated platforms. Stakeholders must monitor how EMA's evolving stance on epigenetic biomarkers in oncology trials affects the addressable market for companion diagnostic developers.
Market Dynamics
EMA biomarker qualification pathways and the EU In Vitro Diagnostic Regulation compress product development timelines, forcing manufacturers to generate clinical evidence earlier in commercialization cycles. This regulatory acceleration reshapes capital allocation across sequencing platform vendors and diagnostic developers.
Growth Catalysts
- Oncology trial expansion:EMA's evolving stance on epigenetic biomarkers in oncology trials expands the addressable market for companion diagnostic developers across European healthcare systems.
- Cloud-based informatics:Software-defined bioinformatics analysis decouples raw instrument sales from recurring revenue streams, extending customer retention beyond hardware replacement cycles.
- Integrated workflow automation:Sample-to-insight automation reduces manual intervention in methylation profiling protocols, accelerating throughput in high-volume academic and contract research laboratories.
Market Restraints
- REACH chemical compliance:Registration, Evaluation, Authorisation and Restriction of Chemicals obligations add cost layers and documentation burdens for reagent manufacturers sourcing modified nucleotides and enzymatic formulations.
- Sequencing platform concentration:Dominant instrument vendors control critical hardware-software interfaces, creating switching friction for laboratories seeking alternative analytical pipelines.
- Single-cell resolution limits:Current bisulfite conversion protocols introduce DNA degradation artifacts that compromise sensitivity in heterogeneous tissue samples.
Strategic Opportunities
- Central and Eastern Europe:Underpenetrated markets in Poland, Czech Republic, and Hungary present expansion vectors for clinical-grade methylation panels as healthcare infrastructure modernizes.
- EU AI Act diagnostic algorithms:Risk classification frameworks for software-integrated platforms create first-mover advantages for vendors pre-validating machine learning classifiers under notified body supervision.
- Long-read sequencing convergence:Integration of nanopore and PacBio technologies with bisulfite alternatives eliminates PCR amplification bias, opening new clinical applications in repeat-rich genomic regions.
Industry Challenges
- Bioinformatics specialist scarcity:Shortages of computational biologists trained in epigenetic data interpretation constrain scaling of clinical diagnostic services.
- MDR certification timelines:Extended conformity assessment procedures for in vitro diagnostic medical devices delay market entry for novel methylation biomarker assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Epigenetics Market |
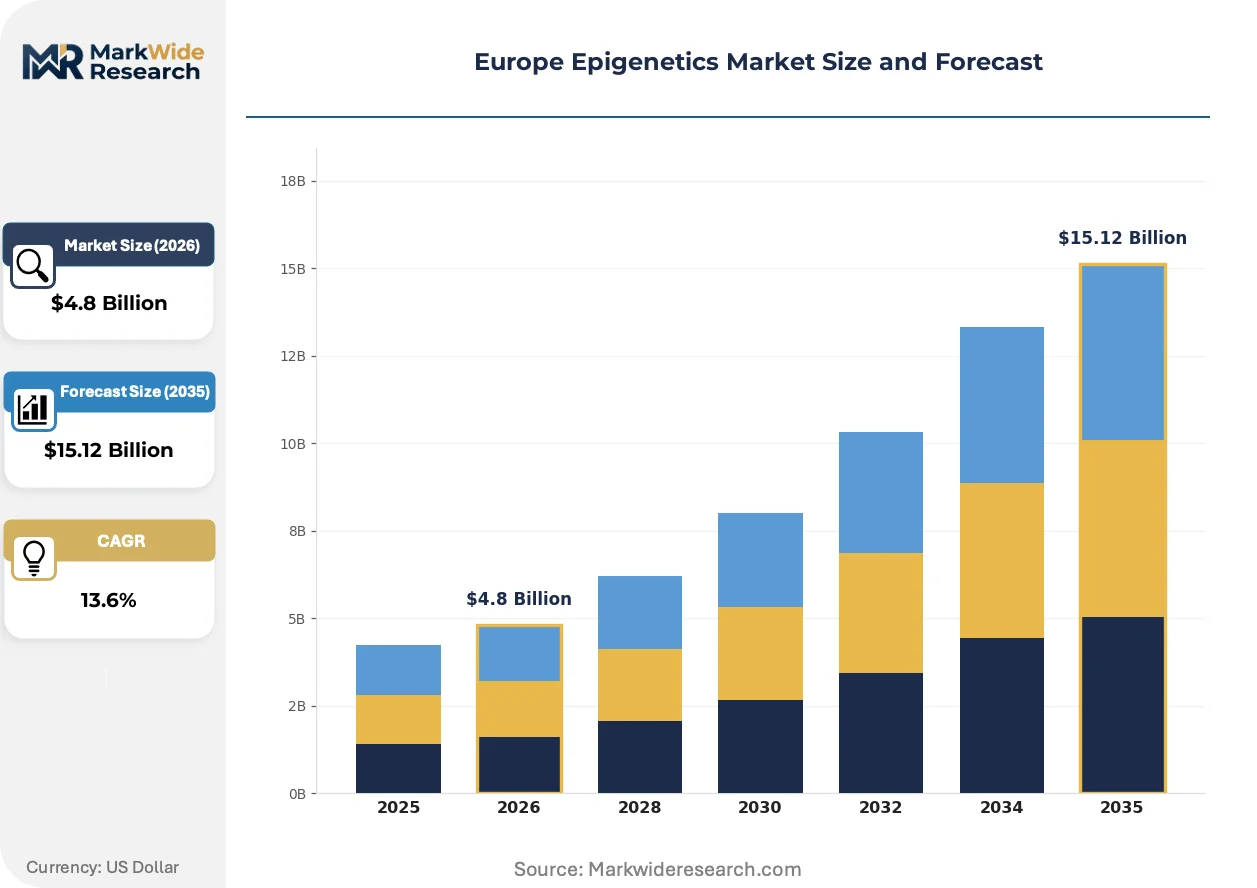
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sequencing Technologies, PCR, Microarrays, Mass Spectrometry Product Type: Instruments, Reagents, Kits, Software End User: Academic Research, Pharmaceutical Companies, Biotech Firms, Contract Research Organizations Application: Cancer Research, Drug Development, Clinical Diagnostics, Genetic Research |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific, QIAGEN, Merck & Co. Inc., Zymo Research Corporation, Roche Holding AG, Abcam plc, Diagenode Inc., Active Motif Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Epigenetics Market Shifts & Advancements
Sequencing technology maturation and regulatory digitization are compressing development cycles while fragmenting buyer power across European healthcare procurement systems.
Third-generation sequencing platforms are rewriting competitive dynamics in methylation analysis. Oxford Nanopore and PacBio systems enable direct detection of modified bases without bisulfite conversion degradation. Academic medical centers in Germany and the Netherlands are piloting these platforms for rapid turnaround oncology testing. The structural consequence is a compression in the reagent-instrument bundle value capture that incumbent vendors have relied upon.
EMA's qualification advice procedure for novel methodologies is formalizing evidentiary standards for epigenetic biomarkers in drug development. This industrial consequence accelerates parallel track development where diagnostic developers must generate clinical utility data contemporaneously with therapeutic trials. Oncology companion diagnostic segments in France and Italy are responding by pre-submission engagement with the Committee for Medicinal Products for Human Use.
Laboratory procurement functions are consolidating vendor relationships around integrated service contracts rather than transactional reagent purchasing. Group purchasing organizations in the United Kingdom and Nordic hospital networks are unbundling after-sales support from instrument acquisition. This behavioral shift is most visible in National Health Service pathology networks, where multi-site framework agreements now specify minimum uptime guarantees and cloud data residency requirements.
Europe Epigenetics Market Segmentation
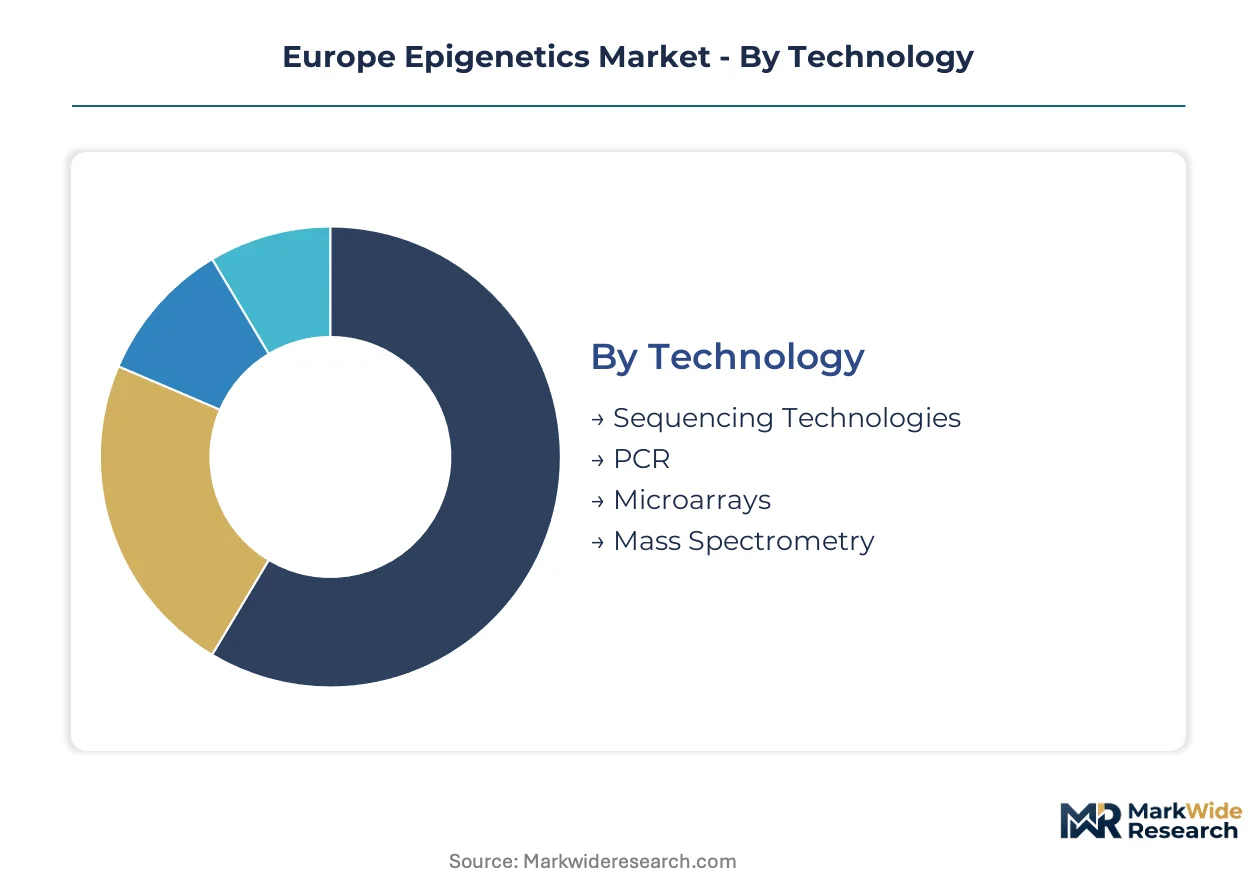
Technology choices in European epigenetics determine downstream workflow economics and regulatory compliance burdens. Product configurations and end-user procurement patterns fragment the competitive landscape across national healthcare systems.
Technology:
Supply concentration in sequencing platforms concentrates vendor power around reagent-software bundles.
- Sequencing Technologies:Next-generation sequencing dominates methylation analysis through bisulfite conversion protocols and emerging direct-detection chemistries. German academic medical centers and UK National Health Service pathology networks drive demand for clinical-grade throughput and cloud-integrated informatics pipelines.
- PCR:Quantitative methylation-specific PCR delivers rapid turnaround for targeted biomarker validation in pharmaceutical quality control settings. French and Italian contract research organizations favor this modality for companion diagnostic feasibility studies where speed outweighs genomic coverage breadth.
- Microarrays:Array-based methylation profiling retains cost advantages for large-scale population epigenetics cohorts.
- Mass Spectrometry:Mass spec approaches enable absolute quantification of modified nucleotides without amplification bias.
Sequencing technologies absorb the bulk of installed capacity; mass spectrometry is expanding most quickly in metabolomics-epigenetics convergence applications.
Product Type:
Margin structures diverge sharply between capital equipment and recurring consumable revenue streams.
- Reagents:Modified nucleotides, polymerases, and bisulfite conversion kits generate predictable recurring revenue tied to sequencing run volume. REACH compliance costs for chemical formulations concentrate manufacturing in established European supply bases.
- Kits:Sample-to-answer methylation profiling kits reduce protocol variability in multi-site clinical studies. Nordic hospital procurement frameworks specify kit-based workflows to standardize pre-analytical handling across decentralized laboratory networks.
- Instruments:Sequencing platforms and liquid handling automation represent front-loaded capital expenditure with extended replacement cycles.
- Software:Cloud-based bioinformatics pipelines decouple analytical capability from hardware ownership.
Reagents and kits together capture the majority of annual spending; software is climbing the fastest as laboratories outsource computational infrastructure.
End User:
Customer procurement sophistication ranges from grant-funded academic flexibility to pharmaceutical enterprise-scale vendor consolidation.
- Academic Research:University laboratories and national research institutes prioritize instrument access and open-source analytical tools. Max Planck Institute and Francis Crick Institute facilities drive early adoption of third-generation sequencing platforms for method development.
- Pharmaceutical Companies:Integrated drug discovery operations demand validated, audit-ready methylation workflows with regulatory documentation packages. EMA biomarker qualification engagement shapes vendor selection timelines for oncology pipeline support.
- Biotech Firms:Venture-funded developers favor flexible kit-based solutions with rapid scalability.
- Contract Research Organizations:CROs compete on throughput guarantees and multi-omics integration capabilities.
Pharmaceutical companies deploy the largest per-site procurement volumes; contract research organizations are gaining share fastest through outsourced epigenetics service expansion.
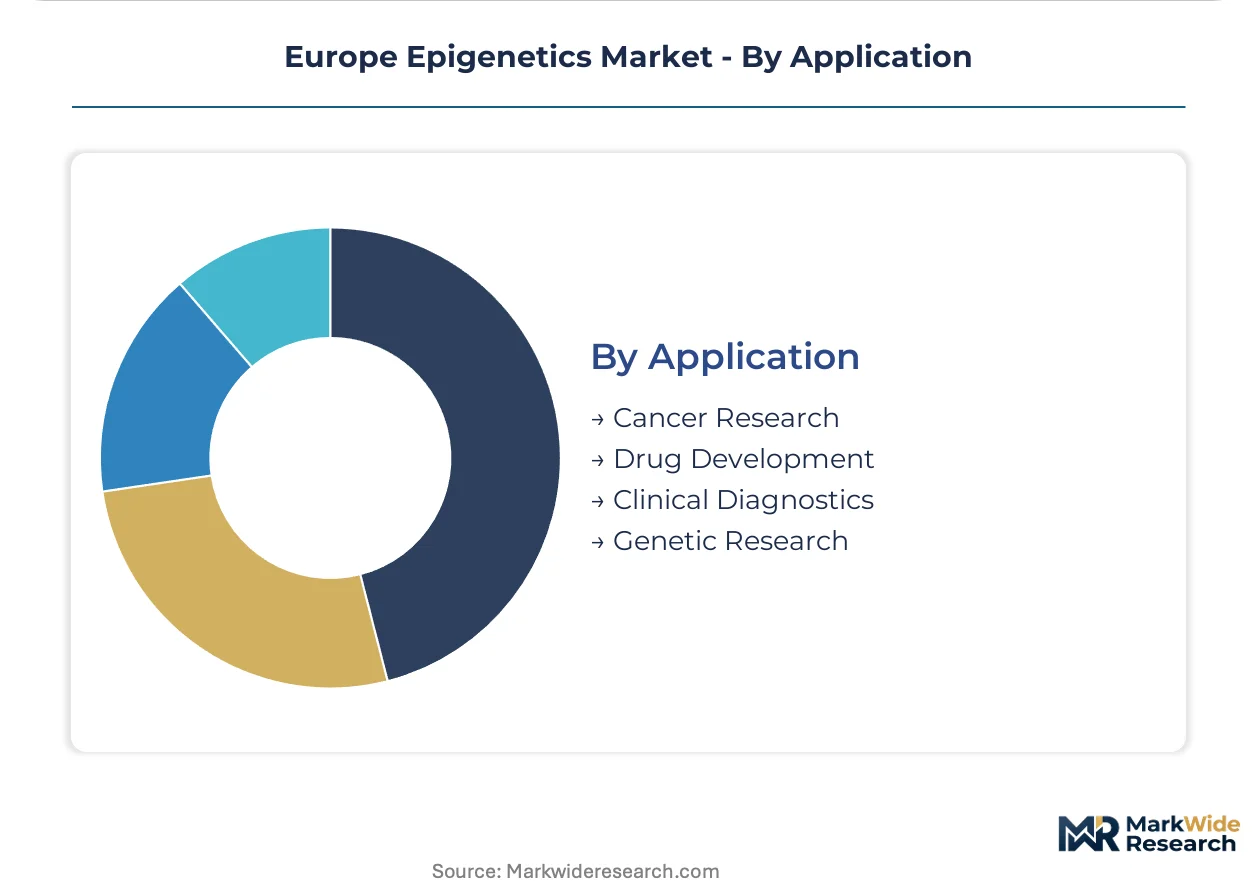
Application:
Clinical translation readiness varies dramatically across research-dominated versus regulated diagnostic endpoints.
- Cancer Research:Methylation biomarker discovery in solid tumors and hematological malignancies commands the largest funding allocation. French and German comprehensive cancer centers coordinate multi-center validation studies for EMA-aligned companion diagnostic development.
- Clinical Diagnostics:Regulatory-cleared methylation assays for early cancer detection and minimal residual disease monitoring represent the highest-value commercial opportunity. MDR certification timelines constrain market entry for novel assay formats.
- Drug Development:Epigenetic target identification and patient stratification biomarkers support therapeutic pipeline decisions.
- Genetic Research:Fundamental epigenetics mechanism studies in model organisms and population cohorts underpin translational advances.
Cancer research absorbs the bulk of current epigenetics spending; clinical diagnostics follows the steepest expansion trajectory as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epigenetics instrument manufacturing concentrates in North American and East Asian supply bases, while European healthcare systems absorb the bulk of clinical-grade sequencing demand. Consumption patterns diverge sharply between mature Western European markets and emerging Central European infrastructure.
Germany
Max Planck Institute facilities and Heidelberg University Hospital drive demand for third-generation sequencing platforms in method development applications. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), coordinates with EMA on biomarker qualification pathways for oncology companion diagnostics. The Munich-Stuttgart corridor anchors industrial clustering for liquid handling automation and reagent manufacturing.
United Kingdom
National Health Service pathology networks consolidate procurement around multi-site framework agreements specifying cloud data residency and minimum uptime guarantees. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UKCA marking requirements post-Brexit, creating parallel compliance tracks for diagnostic developers. The Cambridge-London corridor concentrates biotech venture funding for epigenetic therapeutic pipelines.
France
Comprehensive cancer centers in Paris and Lyon coordinate multi-center validation studies for EMA-aligned companion diagnostic development. The National Agency for Food, Environmental and Occupational Health Safety (ANSM) oversees in vitro diagnostic conformity assessment alongside EMA biomarker qualification procedures. The Île-de-France region hosts the highest density of contract research organizations offering integrated epigenetics services.
Netherlands
Academic medical centers in Rotterdam and Utrecht pilot Oxford Nanopore platforms for rapid-turnaround oncology testing without bisulfite conversion degradation. The Healthcare and Youth Inspectorate (IGJ) implements EU In Vitro Diagnostic Regulation through notified body supervision of software-integrated diagnostic algorithms. The Randstad metropolitan cluster attracts pharmaceutical R&D investment in epigenetic target identification.
Poland
Underpenetrated clinical diagnostics infrastructure creates expansion vectors for standardized methylation panels as healthcare modernization accelerates. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products (URPL) aligns national regulatory frameworks with EU MDR and IVDR timelines. The Warsaw-Łódź corridor emerges as a cost-competitive location for contract research organization service delivery.
Europe Epigenetics Market Competitive Landscape
Capital-heavy sequencing platform manufacturers compete with asset-light bioinformatics developers for value capture in European epigenetics workflows. The vendor base stratifies around integrated reagent-instrument bundles versus modular sample-to-insight automation. Three archetypes dominate: diversified life science conglomerates with full-stack capabilities, specialized epigenetics reagent developers, and cloud-native informatics platforms. Competitive positioning hinges on M&A activity consolidating point-solution vendors and strategic partnerships securing EMA biomarker qualification engagement.
Among diversified life science conglomerates, Illumina Inc., Thermo Fisher Scientific, and QIAGEN occupy positions spanning instrument hardware, consumable reagents, and analytical software. These entities exemplify the integrated bundle strategy that tightens laboratory switching costs across European academic and pharmaceutical customer segments. Their geographic footprints and corporate structures reflect North American headquarters with substantial European operational presence.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific |
| QIAGEN |
| Merck & Co. Inc. |
| Zymo Research Corporation |
| Roche Holding AG |
| Abcam plc |
| Diagenode Inc. |
| Active Motif Inc. |
| Others |
Supply & Pricing Matrix
Captive reagent manufacturing in Germany and the United Kingdom anchors supply positions for sequencing platform vendors while reinforcing pricing power through bundled instrument-consumable contracts. Pharmaceutical laboratories and NHS pathology networks face elevated switching costs as REACH-compliant chemical formulations concentrate in established European supply bases, limiting alternative sourcing flexibility.
Pricing Analysis
Margin tightening in reagent tiers reflects REACH compliance burdens and specialized polymerase manufacturing concentration. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales support intensity. Pricing pressure stems from cloud-native informatics vendors decoupling analytical software from hardware ownership. Academic research laboratories exhibit highest price sensitivity; pharmaceutical quality control operations prioritize audit-ready documentation over unit cost.
Supply Chain Analysis
Refurbishment flows for sequencing instruments concentrate service revenue around original equipment manufacturers in Germany and the Netherlands. Modified nucleotides and enzymatic formulations draw from chemical manufacturing clusters in Switzerland and Germany. Single-source vulnerability persists for third-generation sequencing platforms dependent on Oxford Nanopore and PacBio component supply. Distribution runs through group purchasing organizations in the United Kingdom and Nordic hospital networks consolidating multi-site framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatics specialist scarcity constrains clinical diagnostic service scaling, propping pricing for automated sample-to-insight workflows as laboratories compete for limited computational biology talent.
For Market Incumbents: Anticipate third-generation sequencing platforms displacing bisulfite-dependent chemistries by accelerating direct-detection methylation assay development. Deepen backward integration into modified nucleotide manufacturing to defend reagent margin positions against REACH cost pass-through. Prioritize EMA biomarker qualification engagement to tighten companion diagnostic switching costs.
For New Entrants and Emerging Players: Capture underpenetrated clinical diagnostics infrastructure in Poland and the Czech Republic through standardized methylation panels aligned with EU IVDR timelines. Target contract research organization service delivery models emphasizing multi-omics integration and rapid turnaround guarantees. Lead with cloud-resident informatics pipelines to bypass capital-intensive instrument manufacturing barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified life science conglomerates seeking sample-to-insight workflow automation. Long-term viability hinges on regulatory pre-validation under EU AI Act risk classification frameworks for diagnostic algorithms. Monitor EMA qualification advice procedure throughput as inflection indicator for companion diagnostic addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Biomarker Qualification Engagement | Accelerates parallel-track diagnostic development alongside oncology therapeutic trials in France and Germany. |
| Cloud-Native Informatics Platform Launch | Decouples recurring software revenue from hardware replacement cycles for Illumina and competing vendors. |
| REACH-Compliant Reagent Manufacturing Scale-Up | Concentrates modified nucleotide production in Munich-Stuttgart corridor to limit regulatory cost pass-through. |
| Third-Generation Sequencing Integration | Eliminates bisulfite conversion degradation artifacts for Rotterdam and Utrecht academic medical centers. |
| Multi-Site NHS Framework Agreement | Consolidates UK pathology network procurement around uptime guarantees and cloud data residency specifications. |
Research Methodology
Document review covered EMA qualification procedure documentation, EU IVDR implementation guidance, and REACH chemical compliance frameworks, complemented by interviews with sequencing platform product managers, diagnostic assay regulatory leads, hospital procurement directors at NHS and German university hospitals, and contract research organization operations heads. Secondary validation drew from BfArM and MHRA regulatory filings, ClinicalTrials.gov epigenetic biomarker entries, and European Research Council grant award databases. Bottom-up segment sizing triangulated against top-down healthcare technology spending benchmarks.
Historical instrument placement and reagent consumption patterns cross-referenced against panel input from academic medical center laboratory directors and pharmaceutical biomarker strategists. Segmentation dimensions modeled span technology modality, product type margin structure, end-user procurement sophistication, and application clinical translation readiness. CAGRs derived from weighted scenario analysis across regulatory pathway acceleration and sequencing chemistry substitution timelines. Forecast inputs incorporated EMA biomarker qualification pipeline velocity and third-generation platform clinical adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR certification timeline extensions and EU AI Act diagnostic algorithm risk reclassifications. Forecasts reflect documented assumptions regarding EMA-EMA biomarker qualification throughput and REACH chemical authorization timelines. Practitioners should monitor Oxford Nanopore and PacBio clinical pilot program expansion rates and notified body capacity constraints for early signals of competitive chemistry displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Multiomics Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Retail Genomics Market
Genomics
Genomics Personalized Health Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Genetic Material Market
Genomics
Alagille Syndrome Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Reproductive Genetics Market
Genomics
Genetic Analysis Services Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
APO E Gene Test Kit Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market