
 Plant Genomics Market | 2026-2036
Plant Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Genomics Market Intelligence
CRISPR-edited alleles is repositioning trait economics away from transgenic pipelines toward cisgenic precision. Illumina Inc. dominates sequencing instrument placement across agricultural research stations. Bayer AG leverages its seed manufacturing footprint to integrate genomic selection directly into hybrid development programs. Thermo Fisher Scientific Inc. competes through reagent and service bundles tailored to crop improvement workflows.
Plant genomics encompasses the sequencing, assembly, annotation, and functional analysis of plant nuclear, chloroplast, and mitochondrial genomes, typically leveraging next-generation platforms that generate read lengths from 150 base pairs to multi-megabase contiguous assemblies for complex polyploid species. Its commercial purpose centers on identifying loci governing agronomic performance, stress tolerance, and nutritional composition to accelerate breeding cycles that traditionally span six to ten generations. Seed Genomics commands the largest revenue share as foundational germplasm characterization precedes all downstream applications. Trait Mapping represents the fastest-expanding segment as marker-assisted selection migrates toward whole-genome prediction models. CRISPR technology anchors margin concentration because editing reagents and guide RNA design services carry premium pricing relative to commoditized sequencing chemistries.
The USDA oversees plant pest risk assessments for gene-edited crops under revised SECURE rule guidance, while China's Ministry of Agriculture and Rural Affairs establishes safety evaluation protocols for agricultural genome-edited organisms. The EU Green Deal and associated Farm to Fork strategy pressure breeders to reduce chemical inputs, indirectly accelerating demand for genomics-derived disease resistance traits. Stakeholders must monitor divergence between jurisdictions treating CRISPR products as conventional breeding versus regulated GMOs, as this classification determines market access timelines and R&D allocation across breeding pipelines.
Market Dynamics
CRISPR regulatory divergence between jurisdictions treating edited crops as conventional breeding versus regulated GMOs is forcing seed manufacturers to maintain parallel product development tracks and duplicate safety dossiers for identical genetic modifications.
Growth Catalysts
- USDA SECURE Rule Streamlining:The USDA's revised SECURE guidance exempts certain gene-edited crops from plant pest risk assessments, compressing approval timelines for developers targeting North American markets.
- EU Green Deal Pressure:The EU Green Deal and Farm to Fork strategy mandate chemical input reductions, pulling breeders toward genomics-derived disease resistance traits that replace fungicide applications.
- Polyploid Assembly Breakthroughs:Long-read sequencing platforms now resolve complex wheat and cotton genomes, enabling marker-assisted selection in crops previously intractable to genomic prediction.
Market Restraints
- Guide RNA Synthesis Cost Concentration:CRISPR reagent production concentrates among specialized chemical suppliers, creating input cost volatility for breeding programs scaling editing pipelines.
- EU Regulatory Friction:The European Court of Justice's 2018 ruling classifying CRISPR products as GMOs imposes trait-specific approval costs that deter market entry for specialty crop developers.
- Reference Genome Gaps:Incomplete assemblies for orphan crops and landrace varieties limit genomic selection applicability across sorghum, millet, and underutilized legume breeding programs.
Strategic Opportunities
- Brazilian Cerrado Expansion:Brazil's precision breeding programs for soybeans and corn create demand for localized genomic prediction services adapted to tropical photoperiod sensitivity.
- China Dual Carbon Alignment:China's dual carbon goals incentivize nitrogen-use-efficiency traits that reduce fertilizer emissions, opening public-private partnerships for genome-edited varieties.
- Digital Phenotyping Convergence:Integration of drone-based hyperspectral imaging with genomic selection models enables real-time trait scoring that compresses field trial cycles.
Industry Challenges
- Quantitative Genetics Talent Scarcity:Breeding programs face acute shortages of computational biologists capable of implementing whole-genome prediction models and managing training population design.
- Multi-Jurisdictional Dossier Burden:Divergent data requirements between USDA, China's Ministry of Agriculture and Rural Affairs, and EFSA force redundant molecular characterization studies for identical edits.
- Legacy LIMS Integration Friction:Genomic data pipelines encounter interoperability failures when interfacing with decades-old seed inventory and pedigree tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Genomics Market |
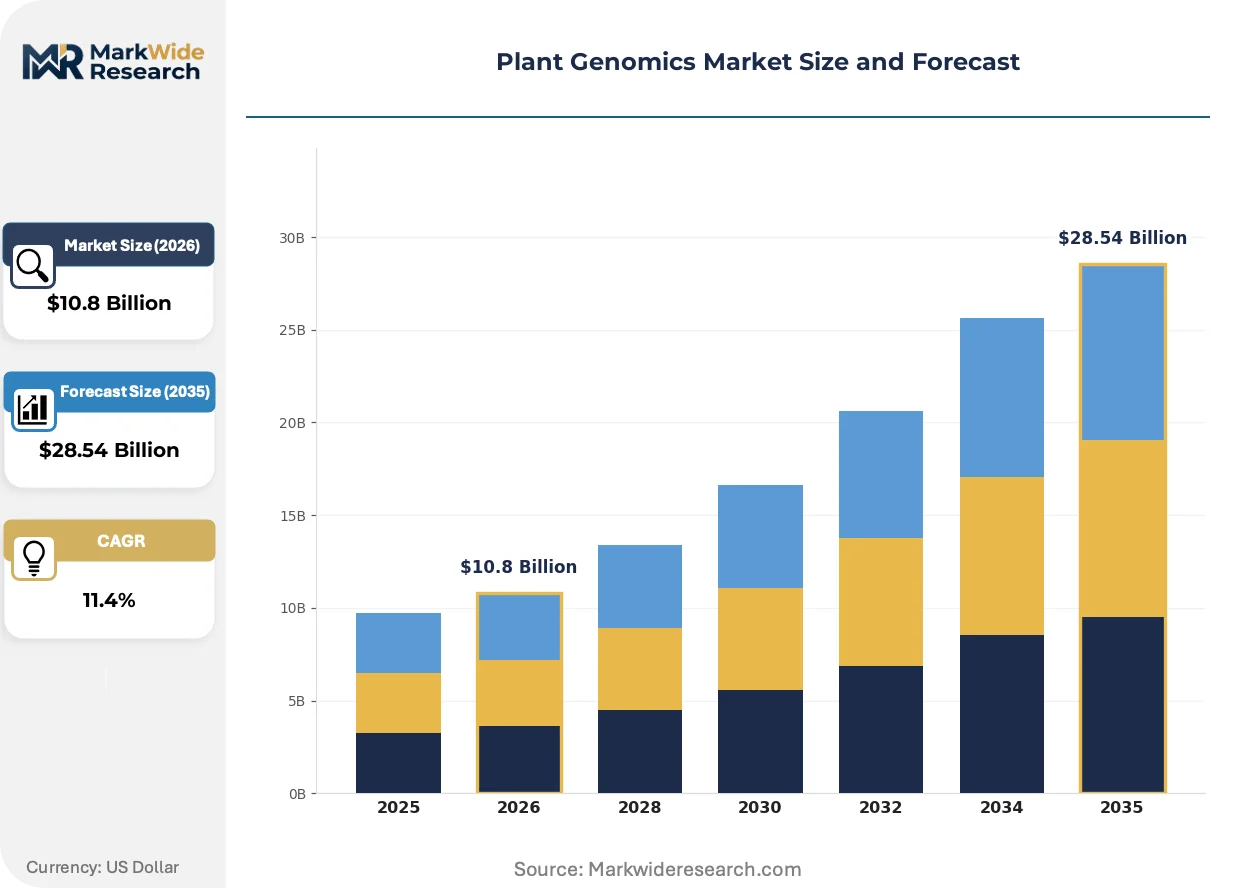
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $28.54 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Genomics, Trait Mapping, Genomic Selection, Genetic Engineering Technology: CRISPR, DNA Sequencing, Genotyping, Bioinformatics Application: Crop Improvement, Disease Resistance, Yield Enhancement, Nutritional Quality End User: Agricultural Research, Biotechnology Companies, Seed Manufacturers, Academic Institutions |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., Eurofins Scientific, BGI Genomics Co., Ltd., Agilent Technologies Inc., QIAGEN, Bayer AG, Corteva Agriscience, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Genomics Market Strategic Shifts & Innovations
Long-read sequencing platforms and multiplexed CRISPR editing are converging to compress trait development cycles from multi-year timelines toward single-season validation. These shifts are redrawing competitive boundaries between instrument vendors, reagent suppliers, and vertically integrated seed manufacturers.
Base editing and prime editing systems are electrifying precision breeding by enabling single-nucleotide modifications without double-strand breaks. Seed manufacturers in the United States and China are adopting these platforms for stacked trait introduction in elite germplasm. The technology is electrifying trait economics by eliminating transgenic cassette integration and associated regulatory scrutiny.
The EU Green Deal's Farm to Fork pesticide reduction targets are reshaping trait prioritization across European breeding programs. National variety registration offices in France, Germany, and the Netherlands now fast-track disease resistance candidates with documented genomic markers. Wheat and potato improvement programs face the steepest compliance pressure as fungicide-dependent varieties lose subsidy eligibility.
Chinese state-owned agricultural institutes are consolidating germplasm banks and genomic databases into centralized national repositories. Public breeding programs in Brazil and India now negotiate data access terms rather than maintaining independent sequencing infrastructure. This concentration is visible most acutely in soybean and rice improvement pipelines where training population scale determines prediction accuracy.
Plant Genomics Market Segmentation
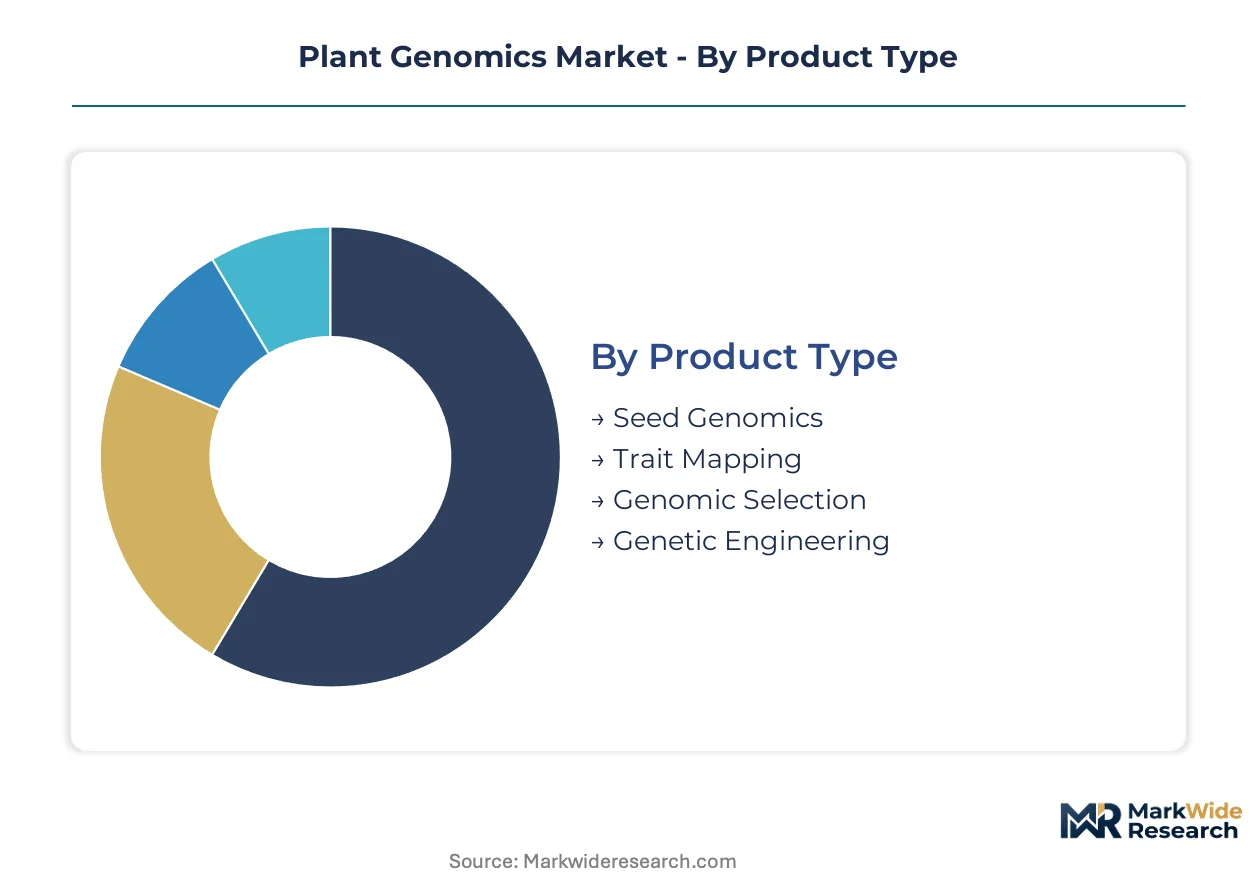
Plant genomics segments by buyer capability and investment horizon. Seed manufacturers prioritize genomic selection platforms for hybrid development velocity, while research institutions concentrate spending on foundational sequencing infrastructure. Technology choice determines regulatory pathway complexity and time-to-market for trait commercialization.
Product Type:
Buyers differentiate by where they sit in the breeding value chain — upstream germplasm characterization demands foundational tools, downstream product development requires predictive and editing platforms.
- Seed Genomics:Germplasm characterization through whole-genome sequencing and diversity panel analysis establishes the genetic baseline for all downstream breeding decisions. Demand concentrates among multinational seed manufacturers in the United States and China who maintain proprietary inbred line libraries requiring continuous genetic fingerprinting. USDA SECURE rule exemptions for certain gene-edited products accelerate investment in foundational genomic infrastructure.
- Trait Mapping:Quantitative trait locus identification and marker-assisted selection migrate toward whole-genome prediction models that compress field trial cycles. European breeding programs under EU Green Deal pesticide reduction mandates drive fastest adoption for disease resistance loci discovery in wheat and potato improvement pipelines.
- Genomic Selection:Training population design and prediction equation calibration for complex polyploid crops including wheat and cotton. Brazil's precision breeding programs for tropical soybean photoperiod adaptation create localized service demand.
- Genetic Engineering:Transgenic cassette integration and regulatory dossier preparation for trait stacking in elite germplasm. China's dual carbon alignment incentivizes nitrogen-use-efficiency trait development through public-private partnerships.
Seed Genomics leads volumes today; Trait Mapping is gaining share fastest.
Technology:
Technology selection hinges on edit precision requirements versus throughput economics — base editing commands premium pricing for single-nucleotide modifications while sequencing commoditizes at scale.
- CRISPR:Guide RNA design services and editing reagent production enable targeted modifications without transgenic cassette integration. Regulatory divergence between USDA exemption pathways and EU GMO classification forces parallel product development tracks for identical genetic modifications.
- DNA Sequencing:Next-generation platforms generating 150 base pair reads to multi-megabase contiguous assemblies for complex polyploid genome resolution. Long-read sequencing breakthroughs now enable genomic prediction in previously intractable wheat and cotton improvement programs.
- Genotyping:High-throughput SNP arrays and targeted amplicon sequencing for training population characterization and parent selection. Seed manufacturers integrate genotyping directly into hybrid development programs to accelerate breeding cycles.
- Bioinformatics:Pipeline development for assembly, annotation, and functional analysis of nuclear, chloroplast, and mitochondrial genomes. Acute scarcity of computational biologists capable of implementing whole-genome prediction models constrains adoption velocity.
DNA Sequencing anchors revenue concentration; CRISPR shows steepest expansion trajectory.
Application:
Application prioritization reflects regulatory pressure and input cost structures — pesticide reduction mandates pull toward disease resistance, fertilizer price volatility drives nitrogen-use-efficiency investment.
- Crop Improvement:Broad-spectrum agronomic performance enhancement through stacked trait introduction in elite germplasm. China's consolidated national germplasm repositories and genomic databases centralize training population scale for prediction accuracy.
- Disease Resistance:Genomics-derived fungicide replacement traits responding to EU Farm to Fork pesticide reduction targets. French, German, and Dutch variety registration offices fast-track candidates with documented resistance markers.
- Yield Enhancement:Photosynthetic efficiency and stress tolerance modifications for staple crop productivity gains. Brazil's Cerrado expansion creates demand for localized genomic prediction services adapted to tropical growing conditions.
- Nutritional Quality:Biofortification for micronutrient density improvement in orphan crops and underutilized legumes. Incomplete reference genome assemblies for sorghum and millet limit genomic selection applicability.
Crop Improvement dominates current deployment; Disease Resistance exhibits strongest demand acceleration.
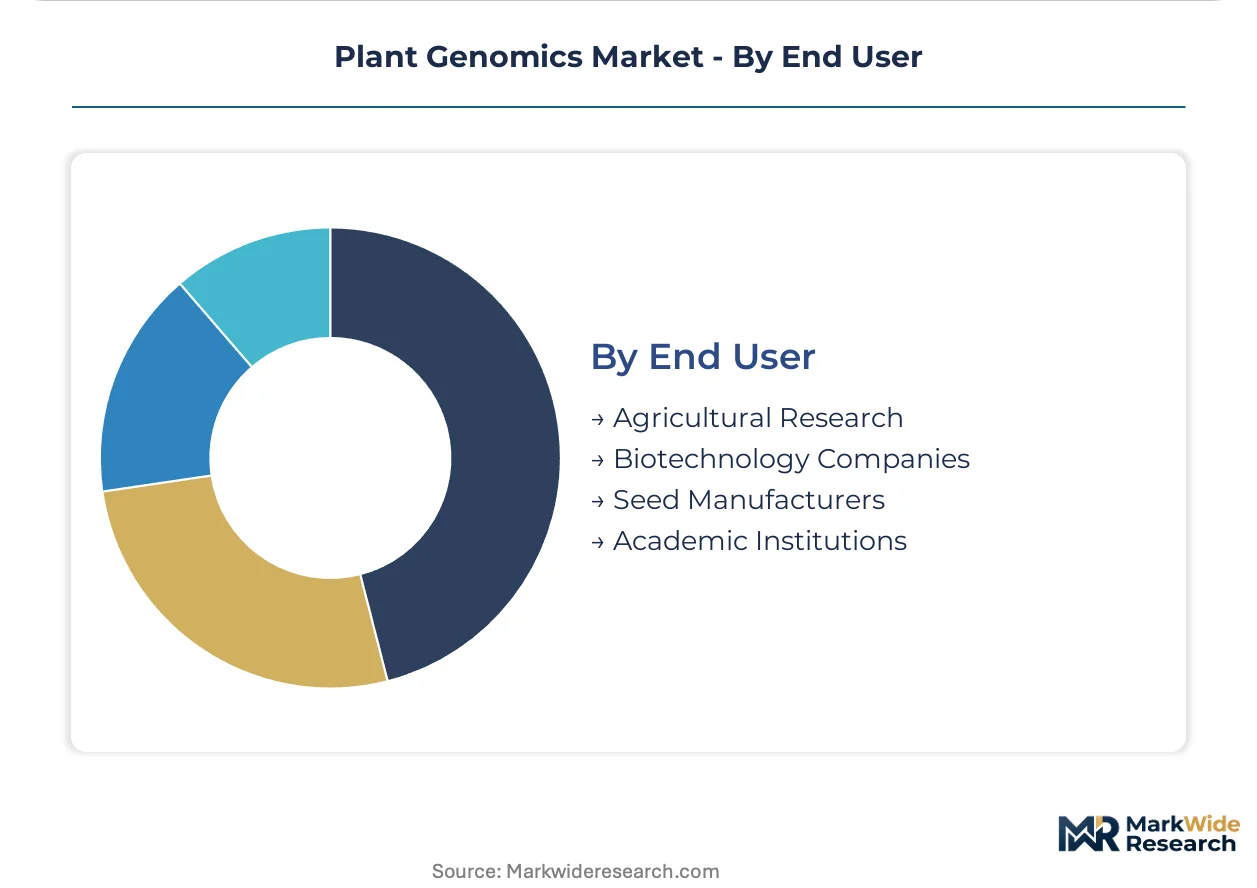
End User:
End user categories separate by data infrastructure maturity — legacy seed inventory systems create integration friction for genomic pipeline adoption.
- Seed Manufacturers:Vertically integrated breeding programs combining germplasm libraries, genomic selection, and regulatory dossier preparation. Interoperability failures between genomic data pipelines and decades-old pedigree tracking systems impede implementation.
- Biotechnology Companies:Specialized editing service providers and guide RNA synthesis suppliers concentrating CRISPR reagent production. Input cost volatility affects breeding program scaling decisions.
- Agricultural Research:Public breeding programs and state-owned institutes negotiating data access terms rather than maintaining independent sequencing infrastructure. India's public programs now access Chinese centralized repositories for soybean and rice improvement.
- Academic Institutions:Foundational genome assembly and functional annotation research feeding downstream commercial application. Training population design and quantitative genetics talent development remain concentrated at this tier.
Seed Manufacturers command largest budget allocation; Biotechnology Companies show fastest spend growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park concentration anchors North American plant genomics infrastructure, with federal research stations and seed manufacturer R&D facilities clustering around genomic selection capabilities and regulatory science expertise.
United States
USDA SECURE rule exemptions for certain gene-edited crops compress approval timelines, pulling seed manufacturers toward cisgenic precision breeding. The Farm Bill conservation programs indirectly fund genomic prediction research for drought tolerance traits. St. Louis and Johnston, Iowa host concentrated breeding program headquarters where genomic selection integrates directly into hybrid development pipelines.
China
Dual carbon alignment incentivizes nitrogen-use-efficiency trait development through public-private partnerships with state-owned agricultural institutes. The Ministry of Agriculture and Rural Affairs establishes safety evaluation protocols for genome-edited organisms that diverge from transgenic regulatory pathways. Beijing and Hainan Island anchor centralized national germplasm repositories consolidating genomic databases for soybean and rice improvement.
Brazil
Cerrado expansion for soybeans and corn creates localized demand for genomic prediction services adapted to tropical photoperiod sensitivity. Embrapa public breeding programs negotiate data access terms with Chinese repositories rather than maintaining independent sequencing infrastructure. São Paulo state concentrates precision breeding program headquarters serving multinational seed manufacturer operations.
Germany
EU Green Deal Farm to Fork pesticide reduction mandates pull breeders toward genomics-derived disease resistance traits replacing fungicide applications. The German Federal Office of Consumer Protection and Food Safety enforces variety registration requirements that fast-track candidates with documented resistance markers. Munich and Cologne host concentrated agricultural biotechnology research clusters where European breeding programs coordinate marker-assisted selection migration.
India
Public breeding programs for orphan crops and underutilized legumes face reference genome gaps limiting genomic selection applicability. The Indian Council of Agricultural Research negotiates data access terms with Chinese centralized repositories for rice improvement training populations. Hyderabad and New Delhi anchor national agricultural research institute clusters where computational biology talent scarcity constrains whole-genome prediction model implementation.
Plant Genomics Market Key Industry Players
Global majors compete with regional champions across sequencing instrument placement and CRISPR reagent supply channels. The vendor base stratifies between instrument manufacturers anchoring foundational infrastructure, reagent suppliers capturing recurring consumable revenue, and vertically integrated seed manufacturers internalizing genomic selection capabilities. Three archetypes dominate: sequencing platform providers, editing technology specialists, and seed manufacturers with captive genomics pipelines. Competitive moves concentrate on strategic partnerships for localized service delivery and technology licensing agreements for CRISPR guide RNA design capabilities.
Within the sequencing platform tier, Illumina Inc. and Thermo Fisher Scientific Inc. occupy positions as archetypal instrument and reagent suppliers respectively. Among agricultural biotechnology conglomerates, Bayer AG exemplifies the vertically integrated seed manufacturer archetype internalizing genomic selection directly into hybrid development programs. BGI Genomics Co., Ltd. represents the regional champion model, anchoring genomic service provision for Asia-Pacific breeding programs through consolidated database access and localized prediction services.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Eurofins Scientific |
| BGI Genomics Co., Ltd. |
| Agilent Technologies Inc. |
| QIAGEN |
| Bayer AG |
| Corteva Agriscience |
| DuPont de Nemours Inc. |
| Others |
Cost & Logistics Intelligence
Illumina sequencing reagent index volatility cascades through plant genomics supply chains into three distinct pricing tiers: premium instrument placements for multinational seed manufacturers, mid-market service bundles for regional breeding programs, and economy genotyping arrays for public research stations. Input cost pass-through elasticity varies sharply by buyer scale, with captive in-house pipelines absorbing margin compression that outsourcing-dependent programs cannot shoulder.
Pricing Analysis
Input-cost pass-through from guide RNA synthesis suppliers concentrates pricing power among CRISPR reagent specialists, forcing breeding programs to accept annual contract escalators tied to phosphoramidite commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates enterprise genomic selection platforms from project-based trait mapping services and per-sample genotyping transactions. Pricing pressure stems from long-read sequencing platform commoditization as Pacific Biosciences and Oxford Nanopore erode Illumina's instrument placement premiums. Public agricultural research institutes exhibit highest price sensitivity, while vertically integrated seed manufacturers with captive reagent production face least exposure.
Supply Chain Analysis
Freight cost spikes for temperature-controlled oligonucleotide shipments from specialized chemical suppliers in Germany and South Korea have reconfigured regional inventory positioning. Supply concentrates in the United States for sequencing instrument manufacturing, China for CRISPR guide RNA synthesis capacity, and Germany for precision reagent production. Raw material dependencies center on phosphoramidite chemistries, high-fidelity polymerases, and synthetic DNA templates. Single-source vulnerability in guide RNA design software platforms creates chokepoint risk for editing pipeline scaling. Distribution runs through direct instrument vendor relationships for large breeding programs and distributor networks for smaller research installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant genomics functions as a stable compounder anchored by irreversible seed manufacturer investment in genomic selection infrastructure that compresses breeding cycles regardless of commodity price cycles.
For Market Incumbents: Lock in exclusive reagent supply agreements with CRISPR guide RNA synthesis specialists before emerging editing platforms displace current chemistries. Extend backward integration into bioinformatics pipeline development to capture recurring service revenue from training population design. Threat of base editing and prime editing platform shifts demands R&D allocation toward single-nucleotide modification capabilities. For New Entrants and Emerging Players: Begin with localized genomic prediction services for Brazil's Cerrado soybean programs, where tropical photoperiod adaptation expertise remains scarce among incumbent vendors. Target orphan crop improvement pipelines for sorghum and millet, where reference genome gaps exclude established players. Go-to-market through Embrapa partnership channels rather than direct multinational competition. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service providers combining Chinese germplasm database access with localized breeding program relationships. Long-term viability over a multi-year horizon hinges on regulatory pathway diversification across USDA exemption and EU GMO classification jurisdictions. Watch for EU Court of Justice ruling modifications as the critical inflection signal for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Regulatory Pathway Diversification | Parallel USDA and EFSA dossier preparation compresses time-to-market for identical edits across jurisdictions. |
| Long-Read Sequencing Platform Migration | Pacific Biosciences Revio placements in wheat and cotton programs unlock previously intractable polyploid genomic prediction. |
| Guide RNA Design Service Acquisition | Captive guide RNA synthesis capacity insulates breeding programs from phosphoramidite cost volatility. |
| Brazilian Cerrado Service Localization | São Paulo-based prediction services capture tropical soybean photoperiod adaptation demand from multinational seed manufacturers. |
| Chinese Germplasm Repository Access | Data partnerships with Beijing and Hainan Island national repositories accelerate training population scale for rice improvement. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed manufacturer breeding directors, CRISPR reagent procurement leads, agricultural biotechnology regulatory affairs specialists, and public breeding program directors with secondary validation against USDA SECURE rule guidance documents, EFSA scientific opinions, Chinese Ministry of Agriculture genome-edited organism safety protocols, and Illumina and Thermo Fisher Scientific SEC filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed value and volume across seed genomics, trait mapping, genomic selection, and genetic engineering product categories, with technology splits for CRISPR, DNA sequencing, genotyping, and bioinformatics. Application dimensions captured crop improvement, disease resistance, yield enhancement, and nutritional quality deployment. End-user stratification separated seed manufacturers, biotechnology companies, agricultural research institutes, and academic institutions. CAGRs derived from logistic growth curve fitting against historical instrument placement trajectories and regulatory approval velocity assumptions.
Caveats apply where EU Court of Justice ruling modifications, phosphoramidite commodity price spikes, or CRISPR platform technology shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory pathway convergence and training population scale requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Market
Genomics
China Genetic Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Spatial OMICS Market
Genomics
Genetic Analysis Services Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
DNA Gene Chip Market
Genomics
Global Metagenomics Market
Genomics
Next Generation Sequencing Market
Genomics
Genome Sequencing Market
Genomics
North America Microarray Market
Genomics
Genomic Biomarkers Market
Genomics
Antisense Oligonucleotides Market
Genomics
UAE Genetic Testing Market