
 North America Whole Exome Sequencing Market | 2026-2036
North America Whole Exome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Whole Exome Sequencing Market Analytics
The divergence between premium reference-grade exome platforms and commodity library-prep reagents is hardening across the North American supply base. Illumina Inc leverages its installed base of NovaSeq systems to dominate high-throughput clinical sequencing contracts. Thermo Fisher Scientific Inc anchors its position through captive supply of Ion Torrent instruments and affiliated consumables. Twist Bioscience differentiates via synthetic biology-driven target enrichment panels that reduce wet-lab turnaround times for mid-volume laboratories.
Whole exome sequencing captures protein-coding regions comprising approximately one percent of the human genome while containing roughly eighty-five percent of known disease-causing variants, operating through hybridization-based target enrichment followed by massively parallel sequencing. The services segment leads revenue contribution as hospitals and academic institutes outsource bioinformatics interpretation to specialized providers. Sequencing by synthesis technology occupies the dominant platform share given its throughput scalability, while the diagnostics application category commands premium pricing tied to reimbursement codes for hereditary disorder testing.
The US FDA regulates exome-based in vitro diagnostics under its NGS guidance framework, while Health Canada and Mexico's national health regulator apply parallel but non-harmonized quality standards that fragment cross-border service deployment. CLIA certification requirements in the United States shape laboratory accreditation costs and directly influence vendor selection criteria for hospital purchasers. Stakeholders must monitor reimbursement policy shifts by the Centers for Medicare and Medicaid Services as coverage determinations for exome sequencing in undiagnosed disease populations remain the decisive demand lever.
Market Dynamics
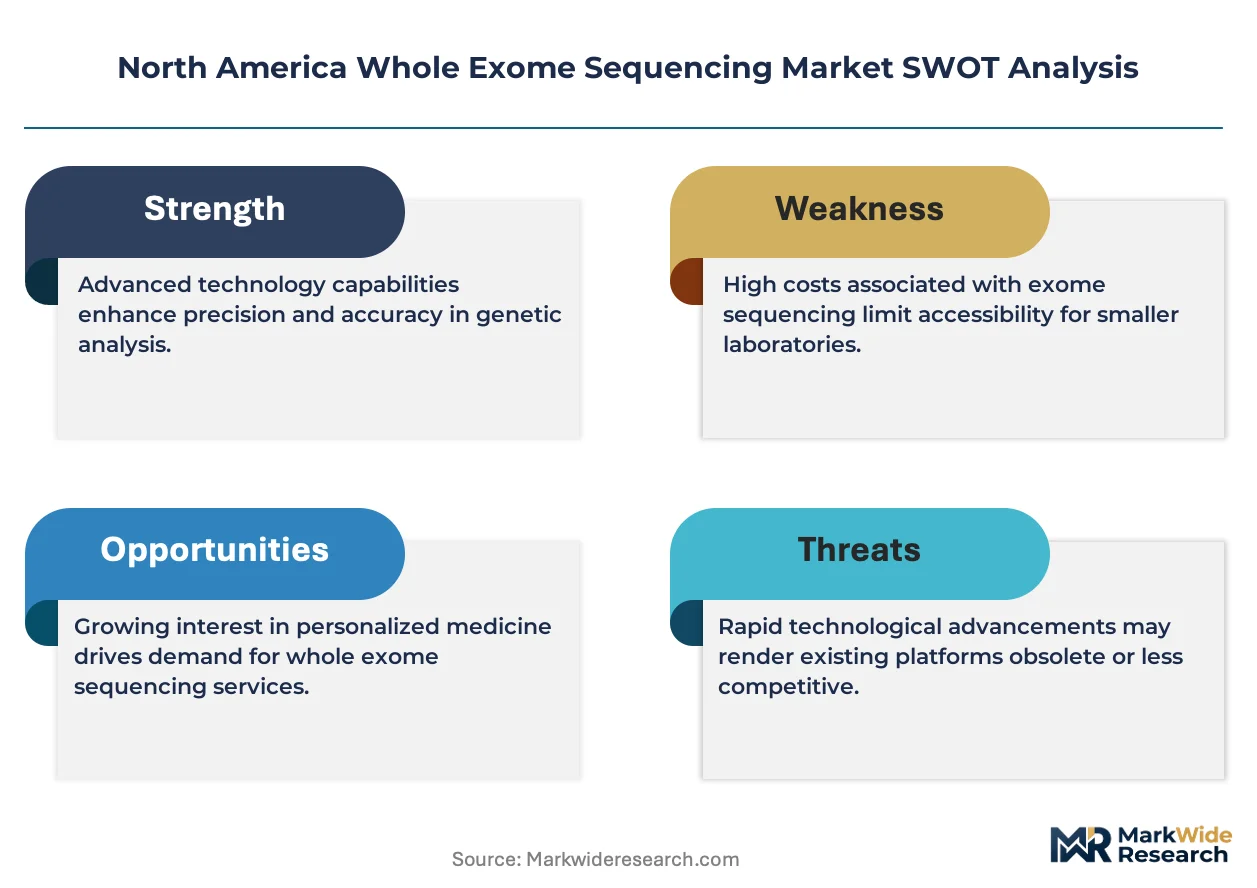
The US FDA's evolving NGS guidance framework is compressing regulatory timelines for exome-based in vitro diagnostics, forcing laboratories to accelerate CLIA certification upgrades while simultaneously expanding reimbursement eligibility for hereditary disorder testing.
Growth Catalysts
- CMS Coverage Expansion:The Centers for Medicare and Medicaid Services is broadening reimbursement codes for exome sequencing in undiagnosed disease populations, directly unlocking hospital laboratory budgets across the United States.
- Hybridization-Based Target Enrichment:Advances in capture chemistry are reducing wet-lab turnaround times, enabling mid-volume clinical diagnostic laboratories to compete with high-throughput reference centers.
- Boston-Cambridge Cluster Concentration:Academic medical centers in Massachusetts are driving demand for research-grade exome services that bridge translational pipelines into clinical validation.
Market Restraints
- Illumina Installed Base Lock-In:Sequencing-by-synthesis platform concentration creates supply vulnerability for laboratories dependent on NovaSeq consumables and service contracts.
- Cross-Border Regulatory Fragmentation:Health Canada's parallel but non-harmonized quality standards impose duplicate validation costs on US-based service providers seeking Canadian market access.
- Bioinformatics Bottleneck:Interpretation complexity for variants of uncertain significance limits scalable clinical reporting without specialized computational infrastructure.
Strategic Opportunities
- Mexico Regulatory Opening:Mexico's national health regulator is developing NGS diagnostic standards that create first-mover advantage for CLIA-certified US laboratories with Spanish-language reporting capabilities.
- Pharmacogenomics Convergence:Integration of exome data with therapeutic drug monitoring protocols is creating new service lines in oncology and psychiatric medication management.
- Direct-to-Consumer Channel:Telehealth platforms are emerging as novel distribution vectors for physician-ordered exome testing, bypassing traditional hospital procurement committees.
Industry Challenges
- Variant Interpretation Workforce Scarcity:Board-certified molecular geneticists and genomic counselors remain concentrated in coastal metropolitan areas, constraining laboratory expansion into secondary markets.
- CLIA Certification Timeline Compression:High-complexity testing accreditation requirements extend facility startup timelines by 12-18 months, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Whole Exome Sequencing Market |
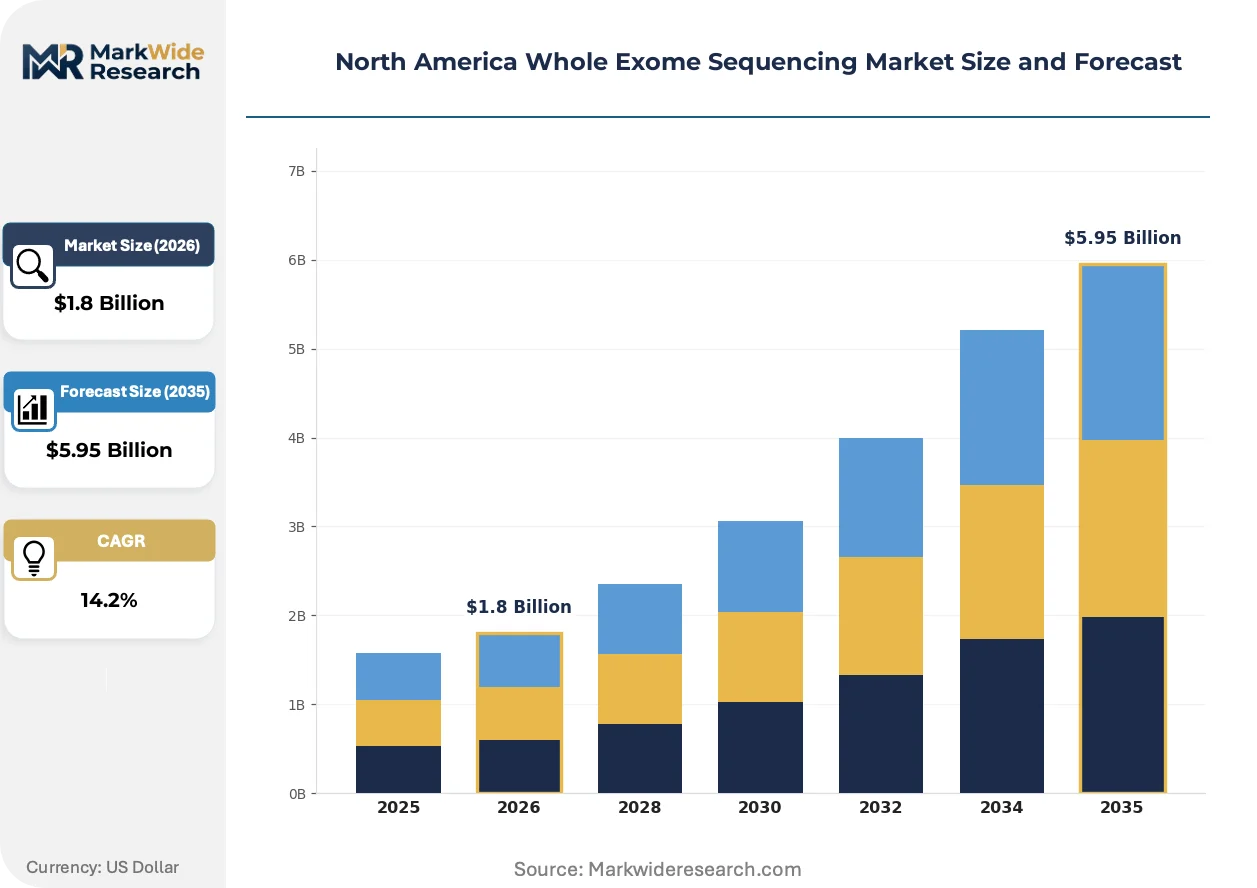
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Services, Software, Consumables Application: Diagnostics, Research, Therapeutics, Drug Discovery End User: Hospitals, Academic Institutes, Research Labs, Pharmaceutical Companies Technology: Sequencing By Synthesis, Ion Torrent, PCR, Microarray |
| Companies Covered | Illumina Inc, Thermo Fisher Scientific Inc, Agilent Technologies Inc, QIAGEN, Eurofins Scientific SE, Pacific Biosciences of California Inc, Azenta Inc, Beckman Coulter Inc, Twist Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Whole Exome Sequencing Market Evolving Landscape
Automation of pre-analytical workflows and cloud-based variant interpretation pipelines are compressing the cost-per-exome while expanding addressable test volumes beyond academic medical centers.
Automated library preparation systems are eliminating manual pipetting steps in hybridization-based target enrichment protocols. Community hospital laboratories in Texas and Florida are adopting these platforms to maintain turnaround parity with reference laboratories. The technology is automating sample-to-sequence workflows that previously required dedicated molecular technologists, enabling overnight batch processing without shift coverage.
The FDA's 2024 NGS-based device guidance update is clarifying analytical validation requirements for germline variant detection. Diagnostic manufacturers must now demonstrate reproducibility across specified variant classes prior to premarket submission. High-complexity molecular pathology laboratories in California are responding by consolidating validation studies across multiple instrument platforms to preempt 510(k) review cycles.
Consolidated procurement through integrated delivery networks is displacing individual hospital laboratory purchasing autonomy. IDN supply chain committees in the Midwest are mandating preferred vendor agreements for exome sequencing services, squeezing independent reference laboratories. This concentration is most visible in Illinois and Ohio, where three health systems control over sixty percent of outpatient hereditary cancer testing referrals.
North America Whole Exome Sequencing Market Segmentation
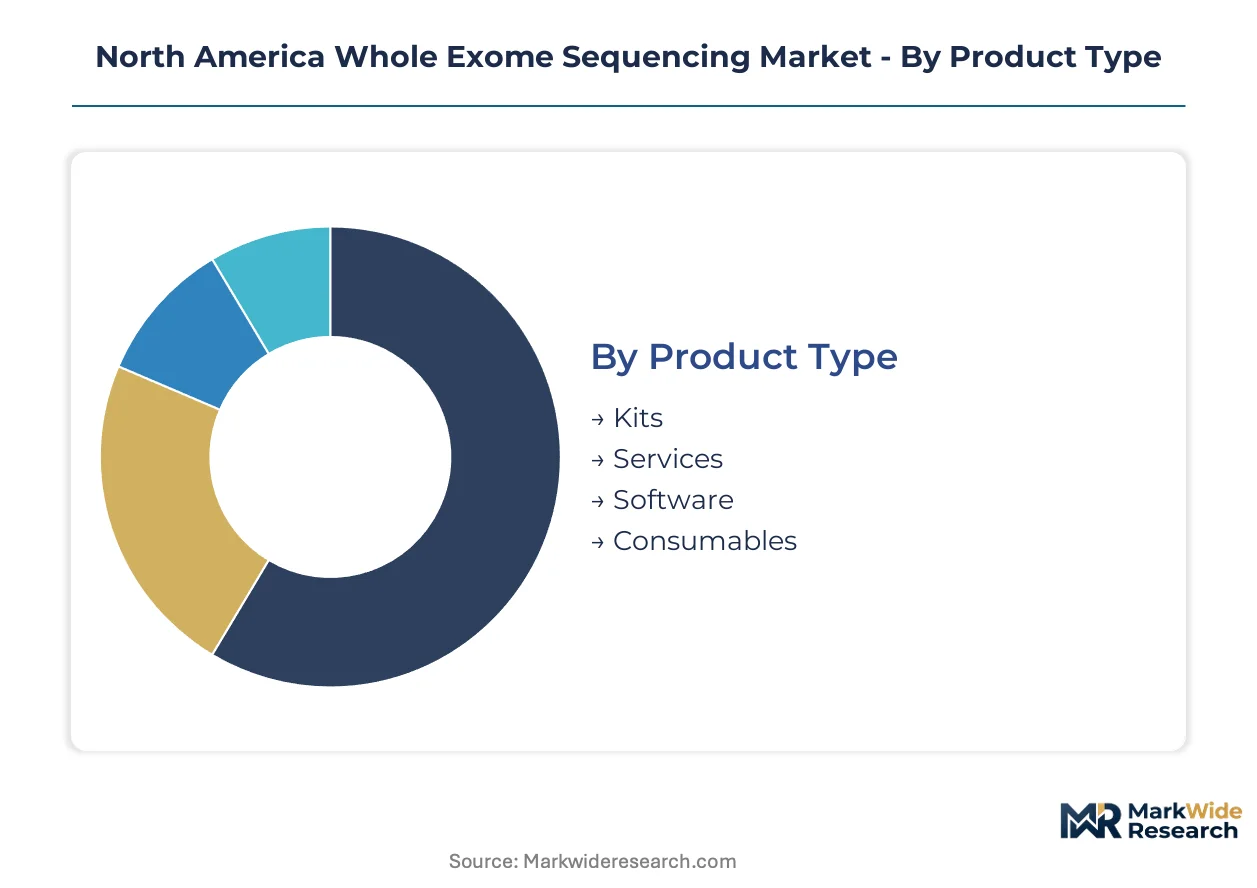
Segmentation in the North American whole exome sequencing market reveals divergent buyer priorities across product tiers, application contexts, and institutional capabilities. Laboratories select categories based on throughput requirements, reimbursement eligibility, and internal bioinformatics capacity rather than uniform technology preferences.
Product Type:
Buyers in this category separate by capital intensity and technical autonomy—hospitals with CLIA-certified labs favor consumables and kits for in-house control, while smaller facilities outsource entirely to service providers.
- Kits:Target enrichment and library preparation kits bundle hybridization probes with standardized reagents for wet-lab workflows. Academic medical centers in the Boston-Cambridge corridor purchase these in volume to maintain research-grade turnaround times without vendor dependency.
- Services:End-to-end exome sequencing with clinical interpretation delivered by specialized reference laboratories. Community hospitals across Texas and Florida contract these services to bypass CLIA certification investments and variant interpretation workforce constraints.
- Software:Variant calling pipelines and clinical decision support platforms for in-house bioinformatics teams.
- Consumables:Flow cells, sequencing reagents, and capture probes tied to specific instrument platforms.
Services leads volumes today; kits are gaining share fastest among laboratories building internal capacity.
Application:
Application selection tracks reimbursement codes and translational pipeline positioning—clinical diagnostics commands premium pricing while research applications feed longitudinal validation studies.
- Diagnostics:Germline variant detection for hereditary disorders and undiagnosed disease programs. California's Bay Area biotech corridor concentrates demand where integrated health systems bundle exome testing with genetic counseling services.
- Research:Discovery-grade sequencing for population genetics and disease mechanism studies. Academic institutes in Massachusetts deploy these services to bridge findings into clinical validation pipelines.
- Therapeutics:Patient stratification and treatment response monitoring in precision medicine programs.
- Drug Discovery:Target identification and biomarker development for pharmaceutical development pipelines.
Diagnostics generates the highest revenue per test; research applications are climbing the fastest as translational programs expand.
End User:
End-user categories reflect procurement authority and sample volume—hospitals control clinical testing budgets while pharmaceutical companies drive contract research scale.
- Hospitals:Integrated delivery networks and academic medical centers with in-house molecular pathology laboratories. IDN supply chain committees in Illinois and Ohio mandate preferred vendor agreements, squeezing independent reference laboratory access.
- Academic Institutes:University-affiliated research centers with dual clinical and basic science missions. These institutions in the Boston-Cambridge cluster purchase research-grade services that feed into clinical validation studies.
- Research Labs:Standalone basic science facilities without clinical accreditation requirements.
- Pharmaceutical Companies:Biopharma sponsors contracting exome sequencing for clinical trial companion diagnostics and target discovery programs.
Hospitals dominate test volumes currently; pharmaceutical company contracting is expanding most quickly as precision oncology pipelines mature.
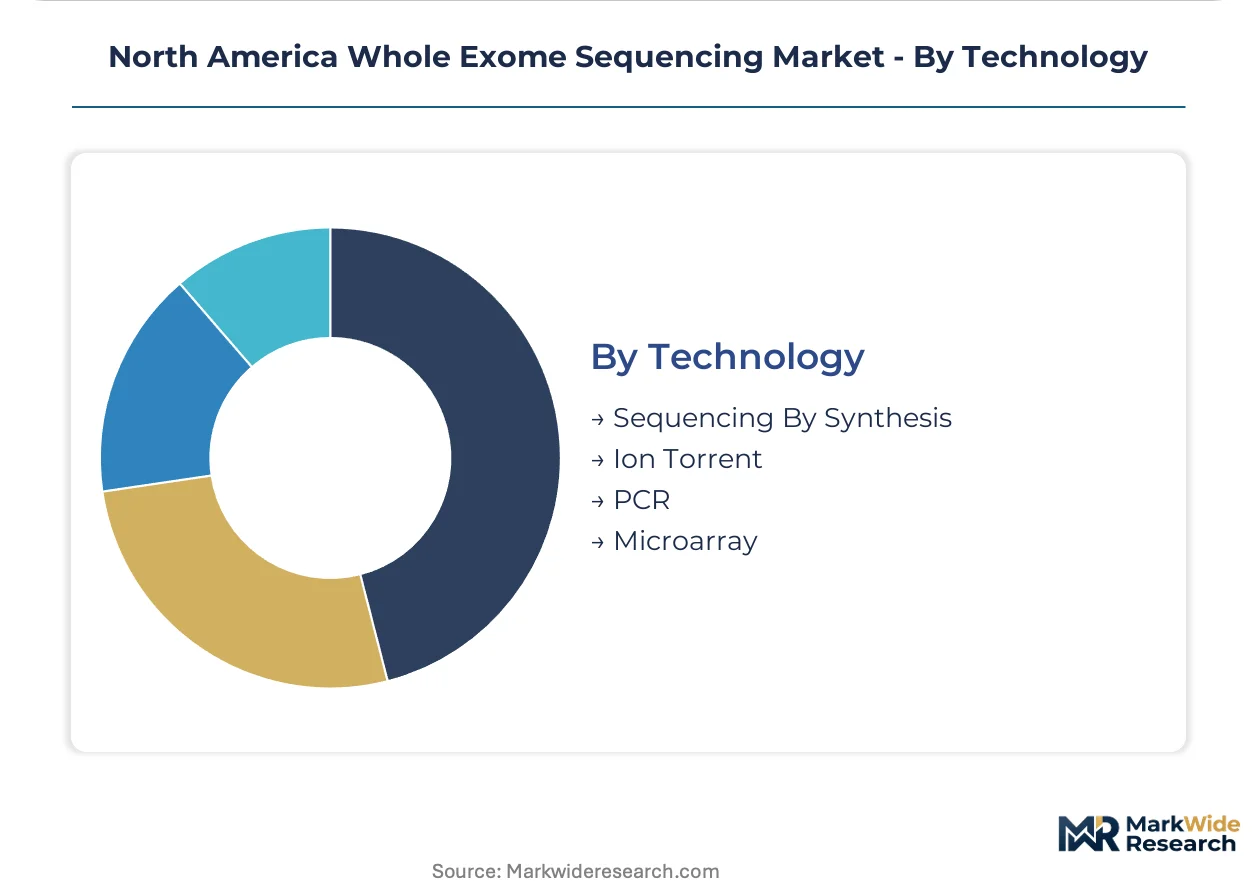
Technology:
Technology selection locks laboratories into ecosystem-dependent consumable supply chains and service contract structures.
- Sequencing By Synthesis:Reversible terminator chemistry enabling massively parallel detection with high accuracy. High-throughput clinical diagnostic laboratories across the United States standardize on this platform for its throughput scalability and established FDA recognition pathways.
- Ion Torrent:Semiconductor-based detection using pH changes during nucleotide incorporation. Mid-volume laboratories in secondary markets adopt this technology for faster turnaround on smaller batch sizes without NovaSeq capital commitments.
- PCR:Targeted amplification methods for focused gene panel validation.
- Microarray:Hybridization-based genotyping for copy number variation detection and quality control applications.
Sequencing by synthesis anchors installed base today; Ion Torrent is capturing share fastest among mid-tier clinical laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified molecular geneticists and genomic counselors concentrate in coastal metropolitan areas, constraining laboratory expansion into secondary markets across the continent.
United States
Integrated delivery networks in Illinois and Ohio control over sixty percent of outpatient hereditary cancer testing referrals, mandating preferred vendor agreements that squeeze independent reference laboratories. The FDA's evolving NGS guidance framework accelerates standardization timelines while CMS reimbursement expansion unlocks hospital laboratory budgets. California's Bay Area biotech corridor anchors demand where integrated health systems bundle exome testing with genetic counseling services.
Canada
Health Canada applies parallel but non-harmonized quality standards that fragment cross-border service deployment and impose duplicate validation costs on US-based providers. The country's national health regulator maintains distinct analytical validation requirements for germline variant detection. Toronto and Vancouver concentrate academic medical center demand for research-grade exome services bridging translational pipelines.
Mexico
Mexico's national health regulator is developing NGS diagnostic standards that create first-mover advantage for CLIA-certified US laboratories with Spanish-language reporting capabilities. The regulatory opening coincides with precision medicine program expansion in Mexico City metropolitan hospitals. Nuevo León's emerging life sciences cluster attracts contract research organization investment for clinical trial companion diagnostics.
Massachusetts
Academic medical centers in the Boston-Cambridge cluster drive demand for research-grade exome services that bridge translational pipelines into clinical validation. Massachusetts General Hospital and affiliated institutes purchase research-grade services feeding longitudinal validation studies. The concentration of dual clinical and basic science missions creates unique procurement patterns distinct from pure diagnostic demand.
Texas
Community hospital laboratories across Texas adopt automated library preparation systems to maintain turnaround parity with reference laboratories without dedicated molecular technologist staffing. The state's independent hospital systems bypass CLIA certification investments by contracting end-to-end services. Houston's Texas Medical Center anchors the southern concentration of hereditary disorder testing demand.
North America Whole Exome Sequencing Market Competitive Landscape
Top-tier vendors anchor the sequencing platform tier, while mid-volume specialists and synthetic biology-driven panel providers occupy differentiated positions below. The market structure hardens around installed base concentration and consumable lock-in effects. Three strategic archetypes dominate: platform incumbents with captive instrument ecosystems, synthetic biology specialists compressing wet-lab turnaround, and reference laboratories bundling interpretation services. Competitive moves concentrate on strategic partnerships for bioinformatics capacity and geographic expansion through CLIA-certified facility replication.
Within the platform incumbent tier, Illumina Inc and Thermo Fisher Scientific Inc exemplify contrasting ecosystem strategies—one leveraging NovaSeq installed base concentration, the other anchoring position through Ion Torrent instrument supply and affiliated consumables. Twist Bioscience occupies a distinct synthetic biology specialist position. These three California-based entities represent the geographic concentration of sequencing technology development, with their competitive positioning reflecting divergent bets on throughput scalability versus mid-volume laboratory accessibility.
| Leading Market Players |
|---|
| Illumina Inc |
| Thermo Fisher Scientific Inc |
| Agilent Technologies Inc |
| QIAGEN |
| Eurofins Scientific SE |
| Pacific Biosciences of California Inc |
| Azenta Inc |
| Beckman Coulter Inc |
| Twist Bioscience |
| Others |
Value Network & Pricing Analysis
Board-certified molecular geneticists and genomic counselors concentrate in coastal metropolitan areas, creating labor-cost differentials that widen pricing-tier spreads between premium reference laboratories and mid-volume service providers.
Pricing Analysis
The bundled-vs-unbundled service split separates pricing models across the North American exome sequencing market. Reference laboratories command premium project-based pricing for end-to-end clinical interpretation bundled with genetic counseling, while mid-tier providers compete on per-unit transactional models for wet-lab sequencing alone. Price differentiation hinges on CLIA certification tier and turnaround time guarantees, with diagnostic-grade turnaround commanding substantial premiums over research-grade delivery. Cost compression in the unbundled reagent tier intensifies as synthetic biology-driven panel providers erode hybridization kit margins. Hospital procurement committees exhibit the highest price sensitivity, particularly in secondary markets where integrated delivery networks mandate preferred vendor agreements.
Supply Chain Analysis
Direct-to-laboratory channels handle high-throughput instrument and consumable demand from CLIA-certified molecular pathology facilities. The supply chain draws from concentrated manufacturing in the United States, Singapore, and Ireland for sequencing instruments, with flow cell production anchored in California and Massachusetts. Critical dependencies include semiconductor chips for detection systems, synthetic oligonucleotides for capture probe synthesis, and fluorophore-labeled nucleotides for sequencing-by-synthesis chemistry. Single-source vulnerability around NovaSeq consumable supply creates operational risk for laboratories locked into Illumina's installed base. Distribution runs through authorized distributor networks for capital equipment and direct fulfillment for recurring consumable orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America whole exome sequencing market represents a late-cycle quality story as demand shifts decisively toward FDA-cleared diagnostic-grade specifications over research-grade services.
For Market Incumbents: Lock in CLIA-certified laboratory networks through exclusive preferred vendor agreements with integrated delivery networks in Illinois and Ohio. Deepen captive supply of target enrichment reagents to defend margin position against synthetic biology specialists eroding kit pricing. The threat of automated library preparation systems commoditizing wet-lab workflows makes bioinformatics interpretation capacity the critical defensive lever. For New Entrants and Emerging Players: Enter via Mexico's regulatory opening for CLIA-certified US laboratories with Spanish-language reporting capabilities. The most penetrable segment lies in community hospital laboratories across Texas and Florida seeking to bypass CLIA certification investments. A telehealth-integrated go-to-market angle bypasses traditional hospital procurement committees and captures direct-to-consumer channel growth. For Investors and Strategic Acquirers: Integrated delivery networks and precision medicine platform companies are the most active acquirer in this space, consolidating reference laboratory assets to capture vertical integration synergies. The long-term viability window favors targets with dual CLIA certification and proprietary variant interpretation pipelines over pure wet-lab service providers. Watch CMS reimbursement determinations for exome sequencing in undiagnosed disease populations as the decisive inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Expansion | High-complexity laboratory accreditation unlocks reimbursement eligibility for hereditary disorder testing codes. |
| Spanish-Language Reporting Capability | Mexico's emerging NGS diagnostic standards create first-mover advantage for US-based service providers. |
| Automated Library Preparation Deployment | Pre-analytical workflow automation eliminates manual pipetting steps and compresses turnaround times. |
| Pharmacogenomics Service Line Integration | Exome data convergence with therapeutic drug monitoring protocols creates oncology and psychiatric medication management revenue. |
| Cloud-Based Variant Interpretation Pipeline | Scalable computational infrastructure addresses the bioinformatics bottleneck constraining clinical reporting volume. |
Research Methodology
Multiple input streams — primary interviews with laboratory directors and genetic counselors, regulatory filing analysis, and hospital procurement database review — were reconciled to construct market estimates. Conversations with CLIA-certified molecular pathology laboratory managers, integrated delivery network supply chain committees, and genomic counselor workforce planners informed operational demand assessments. Secondary validation drew from FDA NGS guidance documents, CMS Medicare reimbursement determinations, and Health Canada quality standard publications. Bottom-up exome test volume estimates were triangulated against top-down sequencing instrument installed base calculations.
Historical growth patterns were cross-referenced against panel input from industry stakeholders to anchor projection assumptions. The analytical framework modeled segmentation across product type, application, end user, and technology dimensions, with additional granularity on CLIA certification tier and reimbursement eligibility status. CAGRs were derived from curve-fitting approaches applied to instrument placement trajectories and consumable pull-through rates. Forecast inputs included CMS coverage expansion timelines, FDA premarket review cycle durations, and genomic counselor training program graduation rates.
Inputs from laboratory accreditation databases and Medicare claims data were available through the study window; gaps in real-time pricing transparency for bundled clinical interpretation services introduce uncertainty bands around revenue estimates. Forecasts reflect assumptions regarding regulatory timeline compression and reimbursement code expansion that could revise substantially based on FDA guidance updates or CMS national coverage determinations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
DNA Sequencing Services Market
Genomics
SNP Genotyping Market
Genomics
Microarray Biochips Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Global Pharmacogenomics Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Pharmacogenomics Technology Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
DNA Gene Chip Market
Genomics
Digital Genome Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Next-Generation Sequencing Data Analysis Market