
 Europe Gene Synthesis (Research Use) Market | 2026-2036
Europe Gene Synthesis (Research Use) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gene Synthesis (Research Use) Market Insights
Modular gene fragment bundles is repositioning how European research buyers configure procurement, shifting from single-gene orders to multi-fragment workflows. Twist Bioscience leverages silicon-based DNA synthesis to sustain cost advantages at scale. GenScript anchors its European presence through localized production capabilities. Thermo Fisher Scientific, Inc. competes across the full plasmid-to-artificial-gene stack with integrated reagent portfolios.
Gene synthesis for research use denotes the de novo chemical assembly of nucleotide sequences into functional DNA constructs, typically achieving lengths from 200 base pairs to multi-kilobase artificial genes through phosphoramidite chemistry or enzymatic methods. Its primary purpose enables researchers to generate optimized coding sequences, regulatory elements, and pathway modules without template DNA constraints. Oligonucleotides dominate transaction volumes due to their ubiquity in PCR, CRISPR guide RNA production, and mutagenesis workflows across European laboratories. Plasmids capture concentrated margin pools where complex multigene assembly and regulatory-grade documentation justify premium positioning. Contract production as a delivery mode is expanding fastest as pharmaceutical firms outsource GMP-compliant gene synthesis to specialized European providers.
The European Medicines Agency oversees clinical-grade gene therapy materials, while REACH governs chemical hazard classification of synthetic nucleic acids and their precursors. The EU AI Act introduces emerging compliance dimensions for algorithmic sequence design tools, reshaping vendor qualification requirements. Germany's national pharmaceutical regulator and France's ANSM enforce divergent preclinical documentation standards that fragment market access protocols. Stakeholders must monitor how the F-Gas Regulation's refrigerant restrictions affect cold-chain logistics for temperature-sensitive synthesized DNA shipments across intra-European routes.
Market Dynamics
Modular gene fragment bundles is compressing order cycles across European research institutions, forcing synthesis providers to reconfigure production workflows around multi-fragment assemblies rather than discrete single-gene transactions.
Growth Catalysts
- EU AI Act compliance infrastructure:Algorithmic sequence design tools now require vendor qualification protocols that favor established European providers with documented audit trails.
- France's ANSM preclinical documentation standards:Pharmaceutical firms are escalating synthetic biology investments to meet divergent national regulatory requirements ahead of therapy pipeline submissions.
- Enzymatic synthesis methods:German biotechnology corridors from Munich to Heidelberg are adopting phosphoramidite alternatives to reduce hazardous chemical handling and streamline REACH reporting.
Market Restraints
- Phosphoramidite precursor supply concentration:Three specialized chemical manufacturers control European feedstock for traditional DNA synthesis, creating input cost volatility during energy price spikes.
- REACH hazard classification complexity:Synthetic nucleic acids and their chemical precursors face evolving ECHA substance evaluation protocols that extend product registration timelines.
- CRISPR guide RNA alternatives:Direct RNA synthesis workflows are displacing DNA-templated guide production in some gene editing applications, eroding addressable volume in specific research niches.
Strategic Opportunities
- Poland and Czech Republic research infrastructure:Underpenetrated Central European markets are expanding synthetic biology capacity through EU cohesion fund investments in laboratory equipment.
- F-Gas Regulation cold-chain innovation:Refrigerant restrictions on temperature-sensitive DNA shipments are creating demand for alternative stabilization chemistries and ambient-temperature logistics networks.
- Silicon-based synthesis convergence with AI design:Integration of automated sequence optimization with high-density DNA printing platforms enables same-day turnaround for urgent research orders.
Industry Challenges
- Bioinformatics-trained laboratory technicians:European institutions face acute shortages of personnel capable of operating integrated design-to-synthesis platforms and interpreting complex sequence verification data.
- GMP-compliant facility certification:Contract production providers must navigate divergent EMA and national pharmaceutical regulator standards, extending facility qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gene Synthesis (Research Use) Market |
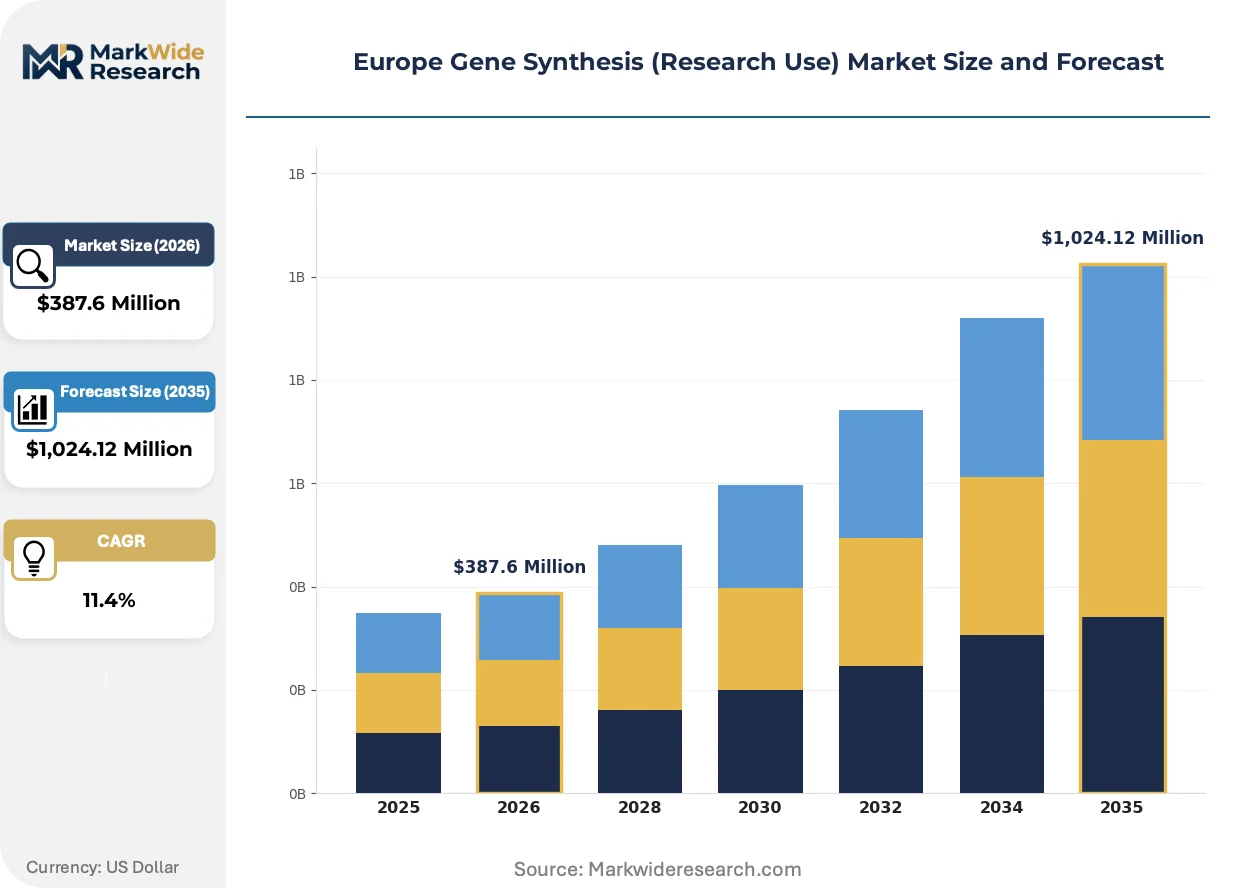
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, Oligonucleotides, Gene Fragments, Artificial Genes Delivery Mode: Physical Delivery, Digital Delivery, In-House Production, Contract Production End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Firms, Research Organizations Application: Synthetic Biology, Vaccine Development, Gene Therapy, Functional Genomics |
| Companies Covered | Thermo Fisher Scientific, Inc., GenScript, Twist Bioscience, Azenta, Inc. (GENEWIZ), ProteoGenix, Inc, Integrated DNA Technologies, Inc. (Danaher), ProMab Biotechnologies, Inc., Trenzyme GmbH, BioCat GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gene Synthesis (Research Use) Market Trends and Innovations
European gene synthesis workflows are undergoing platform-level automation that compresses design-to-delivery cycles while embedding compliance documentation directly into production traceability systems.
Silicon-based DNA synthesis is automating high-throughput production of oligonucleotide libraries through microfluidic reaction chambers etched into semiconductor substrates. Academic core facilities in Germany and the Netherlands are adopting these platforms to replace legacy column-based synthesis for routine PCR primer production. The technology is automating cost structures that previously required manual intervention at scale, enabling per-base pricing compression without quality trade-offs.
REACH and the EU AI Act are jointly reshaping vendor qualification requirements for algorithmic sequence design tools used in engineered biological materials. ECHA substance evaluation protocols now intersect with AI system risk classification, creating dual compliance burdens for providers of automated gene design software. Contract research organizations in France and Belgium are responding by building dedicated regulatory affairs functions that bridge chemical safety and algorithmic transparency documentation.
Research buyers are consolidating procurement around multi-fragment workflow bundles that include sequence optimization, synthesis, and downstream cloning services. European pharmaceutical firms are displacing discrete transactional purchasing with annual framework agreements that lock capacity at specialized providers. This concentration is most visible in Germany's biotechnology corridor, where Heidelberg-based research institutes now negotiate consolidated contracts covering plasmid design through GMP-compliant gene production.
Europe Gene Synthesis (Research Use) Market Segmentation
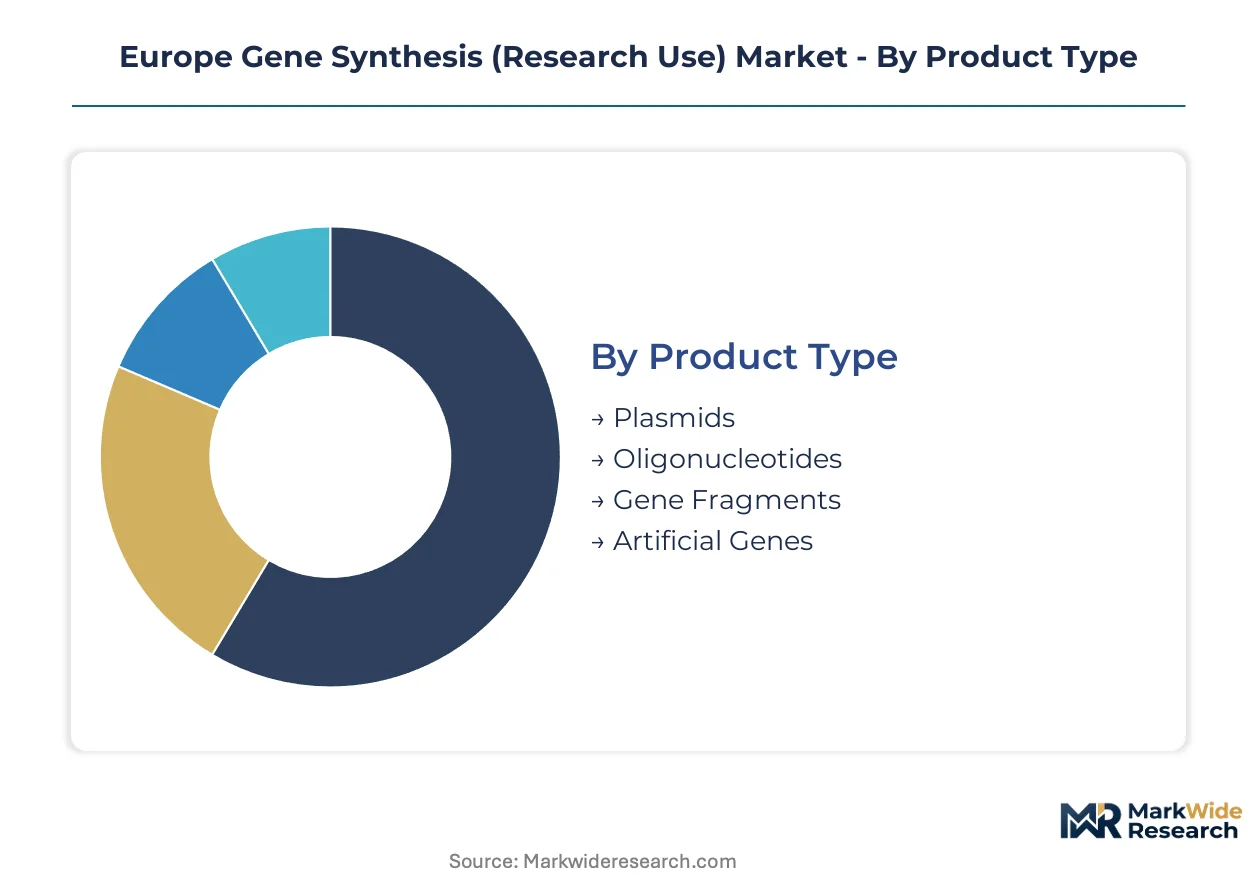
Segmentation in the European gene synthesis market reveals how procurement patterns diverge across research workflows. Academic core facilities favor high-volume oligonucleotide bundles while pharmaceutical firms prioritize plasmid-based contract production with regulatory documentation.
Product Type:
Upgrade cycles in European laboratories are accelerating as phosphoramidite-based synthesis equipment reaches end-of-life and enzymatic platforms gain REACH compliance advantages.
- Plasmids:Circular DNA vectors engineered for protein expression, viral packaging, or CRISPR delivery typically span 2-15 kilobases with antibiotic resistance cassettes. Heidelberg-based research institutes and Munich biotechnology clusters drive concentrated demand for multigene assembly plasmids with regulatory-grade sequence verification.
- Oligonucleotides:Short synthetic DNA strands ranging from 20-200 base pairs serve as PCR primers, sequencing adapters, and CRISPR guide templates. German academic core facilities consume the highest volumes through automated reorder systems integrated with laboratory information management platforms.
- Gene Fragments:Linear double-stranded DNA constructs of 200-3000 base pairs enable rapid pathway assembly without template constraints.
- Artificial Genes:De novo assembled sequences exceeding 3 kilobases with codon optimization for heterologous expression systems.
Oligonucleotides sit at the top of the volume ranking, with gene fragments climbing the fastest as modular assembly workflows displace single-gene ordering.
Delivery Mode:
Cost tier differentiation separates commodity synthesis from premium contract manufacturing, with pricing spreads widening between standardized digital workflows and GMP-compliant physical production.
- Physical Delivery:Lyophilized or hydrated DNA samples shipped under temperature-controlled logistics with chain-of-custody documentation. France's ANSM documentation requirements and Germany's pharmaceutical regulator standards fragment compliance protocols across cross-border shipments.
- Contract Production:Outsourced manufacturing at specialized European facilities with EMA-aligned quality systems and batch release certification. Heidelberg-Munich biotechnology corridor firms increasingly lock multi-year capacity agreements to secure GMP-compliant gene supply for clinical pipeline transitions.
- Digital Delivery:Sequence files transmitted electronically for local production or direct integration into automated cloning platforms.
- In-House Production:Captive synthesis capabilities at institutional core facilities or corporate research centers with dedicated phosphoramidite or enzymatic equipment.
Physical delivery maintains the highest transaction frequency, while contract production gains share fastest as pharmaceutical outsourcing accelerates.
End User:
Customer type concentration maps directly onto funding cycles, with Horizon Europe grant disbursements and national research council allocations timing procurement surges across institutional categories.
- Academic Institutions:University laboratories and core facilities purchasing through centralized procurement frameworks with volume discount structures. French and German synthetic biology programs are scaling fragment bundle orders to replace discrete single-gene transactions.
- Pharmaceutical Firms:Integrated drug developers requiring GMP-compliant gene synthesis for cell line engineering and viral vector production. Divergent national pharmaceutical regulator standards between France's ANSM and Germany's federal authority extend vendor qualification timelines.
- Biotechnology Companies:Venture-backed developers of gene therapies, cell therapies, and engineered biologics with milestone-dependent synthesis budgets.
- Research Organizations:National laboratories, EU joint undertakings, and nonprofit institutes with multi-year programmatic funding.
Academic institutions anchor the volume base, with pharmaceutical firms expanding most quickly as gene therapy pipelines mature toward clinical stages.
Application:
Application maturity curves diverge sharply, with synthetic biology workflows achieving platform standardization while gene therapy applications remain constrained by EMA clinical material guidelines.
- Synthetic Biology:Engineering of biological systems for metabolic pathway construction, biosensor development, and industrial enzyme optimization. German biotechnology corridors from Munich to Heidelberg concentrate demand for multigene pathway assembly with automated design-to-synthesis integration.
- Gene Therapy:Production of viral vector components, therapeutic transgenes, and regulatory cassettes for clinical development. EMA oversight of clinical-grade materials and REACH chemical hazard classification create dual compliance burdens for European providers.
- Vaccine Development:Antigen sequence optimization, DNA vaccine backbone construction, and adjuvant vector engineering.
- Functional Genomics:CRISPR library construction, reporter gene systems, and genome-scale perturbation screening platforms.
Synthetic biology commands the deepest volume penetration, with gene therapy showing the steepest expansion trajectory as European pharmaceutical investment in advanced therapies accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene synthesis for research use originated in European academic laboratories during the 1980s phosphoramidite chemistry era, with Heidelberg and Cambridge emerging as early centers of de novo DNA assembly expertise before commercial providers scaled across the continent.
Germany
The Munich-to-Heidelberg biotechnology corridor drives concentrated demand for multigene pathway assembly and GMP-compliant contract production. REACH enforcement by ECHA and Germany's federal pharmaceutical regulator imposes dual chemical safety and clinical material documentation requirements on synthetic nucleic acid providers. Bavarian research institutes in Martinsried and Planegg now negotiate consolidated procurement frameworks covering sequence design through regulatory-grade gene delivery.
France
Paris-Saclay and Lyon bioclusters are escalating synthetic biology investments to meet ANSM preclinical documentation standards for gene therapy pipelines. The EU AI Act intersects with REACH substance evaluation protocols, forcing French contract research organizations to build dedicated regulatory affairs bridging algorithmic transparency and chemical hazard classification. Île-de-France academic core facilities are displacing discrete single-gene orders with modular fragment bundle workflows.
United Kingdom
Cambridge and Oxford synthetic biology hubs sustain demand for oligonucleotide libraries and CRISPR guide RNA production despite post-Brexit divergence from EMA oversight. The UK Medicines and Healthcare products Regulatory Agency now operates independent clinical-grade gene therapy material guidelines that fragment vendor qualification protocols relative to continental standards. London-based pharmaceutical firms are locking multi-year capacity agreements with specialized European providers to secure cross-border GMP-compliant supply chains.
Netherlands
Leiden and Utrecht life science clusters concentrate demand for enzymatic synthesis platforms that reduce hazardous chemical handling and streamline REACH reporting obligations. Dutch academic core facilities are adopting silicon-based DNA synthesis technologies to replace legacy column-based production for routine PCR primer manufacturing. The national pharmaceutical regulator aligns with EMA standards while maintaining distinct batch release certification protocols that extend facility qualification timelines for contract providers.
Switzerland
Basel and Zurich pharmaceutical research centers sustain premium demand for artificial gene assembly with codon optimization for heterologous expression systems. Swissmedic operates independent clinical material oversight that diverges from both EMA and national EU pharmaceutical regulator frameworks, creating specialized vendor qualification requirements. The country's biotechnology corridor is consolidating procurement around providers with documented audit trails for algorithmic sequence design tools under emerging EU AI Act compliance infrastructure.
Europe Gene Synthesis (Research Use) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across documentation-grade and throughput dimensions, with GMP-certified contract manufacturers commanding pricing spreads over standard research-grade synthesis providers. The vendor base organizes into three strategic tiers: integrated life science conglomerates with full plasmid-to-artificial-gene stacks, silicon-based synthesis specialists leveraging semiconductor microfluidics for cost compression, and regional contract production facilities with EMA-aligned quality systems. Dominant competitive moves include capacity reservation agreements from pharmaceutical firms securing multi-year GMP-compliant gene supply, and technology licensing partnerships transferring enzymatic synthesis platforms to academic core facilities.
Within the integrated conglomerate tier, Thermo Fisher Scientific, Inc. anchors market presence across reagent-integrated synthesis workflows. GenScript occupies a position representing localized European production capabilities that circumvent cross-border logistics complexity. Twist Bioscience exemplifies the silicon-based synthesis archetype, with semiconductor-derived cost structures enabling scale advantages in high-throughput oligonucleotide production. These three entities collectively represent the spectrum from reagent-integrated portfolios to microfluidic manufacturing platforms and regional production footprints.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| GenScript |
| Twist Bioscience |
| Azenta, Inc. (GENEWIZ) |
| ProteoGenix, Inc |
| Integrated DNA Technologies, Inc. (Danaher) |
| ProMab Biotechnologies, Inc. |
| Trenzyme GmbH |
| BioCat GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive production of phosphoramidite precursors by German chemical conglomerates anchors both supply security and pricing power across the European gene synthesis corridor. This backward integration into feedstock manufacturing insulates established providers from energy-driven cost volatility while enabling margin capture at multiple value chain stages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by documentation grade and regulatory certification. GMP-compliant contract production commands substantial premiums over research-grade synthesis, while academic volume bundles compress per-base costs through annual framework agreements. Cost compression in standard-tier oligonucleotides is intensifying because silicon-based synthesis platforms automate previously manual production steps. Academic core facilities exhibit the highest price sensitivity, whereas pharmaceutical firms prioritize qualification reliability over unit cost.
Supply Chain Analysis
EMA-aligned facility certification functions as the primary gating mechanism for supply chain participation, extending qualification timelines for new entrants. Manufacturing capacity concentrates in Germany, France, and Switzerland, with specialized chemical feedstock production anchored in German industrial clusters. Raw material dependencies include phosphoramidite monomers, controlled-pore glass supports, and high-purity solvents. Single-source vulnerability persists for enzymatic synthesis reagents where patent-protected formulations limit supplier options. Distribution runs through temperature-controlled logistics networks with chain-of-custody documentation for cross-border shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe gene synthesis market compounds steadily as synthetic biology programs across German and French academic institutions generate durable demand for modular DNA constructs. Regulatory tightening under REACH and the EU AI Act reinforces incumbent advantages through elevated compliance barriers.
For Market Incumbents: Acquire enzymatic synthesis platform capabilities to reduce hazardous chemical handling exposure and streamline REACH reporting obligations. Consolidate fragmented Central European contract production capacity in Poland and the Czech Republic before EU cohesion fund investments mature local competitors. Threat substitution from direct RNA synthesis in CRISPR applications demands defensive positioning in downstream cloning and assembly services. For New Entrants and Emerging Players: The pricing gap between premium GMP-certified contract production and economy-grade academic synthesis creates entry space for mid-tier providers offering regulatory-grade documentation without full pharmaceutical certification. Central European research infrastructure expansion presents the most penetrable geography, with synthetic biology capacity growing faster than specialized provider presence. A go-to-market angle anchored on ambient-temperature DNA stabilization chemistries addresses F-Gas Regulation compliance pain points in cold-chain logistics. For Investors and Strategic Acquirers: Roll-up economics work for regional contract production facilities because EMA-aligned quality system investments create scale advantages that fragment competitors cannot replicate. The 5-10 year viability window favors platforms with documented audit trails for algorithmic sequence design tools under EU AI Act infrastructure. Acquisition target archetype: mid-scale European providers with GMP facility certification and established pharmaceutical customer relationships. Signal to watch: ANSM and German federal pharmaceutical regulator harmonization initiatives that would consolidate currently fragmented national qualification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Platform Adoption | REACH compliance advantages reduce hazardous chemical handling costs for German biotechnology corridors. |
| GMP Facility Certification Investment | EMA-aligned quality systems lock pharmaceutical outsourcing contracts during clinical pipeline transitions. |
| Silicon-Based Manufacturing Scale-Up | Microfluidic semiconductor platforms compress per-base pricing for high-volume oligonucleotide production. |
| Central European Capacity Expansion | EU cohesion fund laboratory investments in Poland and Czech Republic create localized demand capture. |
| Regulatory Affairs Function Buildout | Bridging REACH chemical safety and EU AI Act algorithmic transparency documentation addresses dual compliance burdens. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with gene synthesis procurement managers, regulatory affairs leads at contract research organizations, core facility directors at German and French academic institutions, and pharmaceutical supply chain executives. Secondary validation drew from EMA regulatory filings, ECHA substance evaluation protocols, EU funding disbursement records, and national research council allocation data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across product type, delivery mode, and end user dimensions.
Comparable-period anchoring established baseline demand patterns from historical procurement cycles before projecting forward across the analysis window. The analytical framework modeled segmentation by product type, delivery mode, end user category, application area, and national regulatory cluster. CAGRs were derived from normalized growth rate distributions fitted to observed capacity expansion and funding trajectory data. Industry-specific forecast inputs included Horizon Europe synthetic biology allocation trends and pharmaceutical pipeline advancement rates toward clinical stages.
The model assumes a particular technology adoption path; alternative pathways for enzymatic synthesis would alter the outlook if phosphoramidite chemistry retains cost advantages longer than projected. Forecasts reflect assumptions about regulatory harmonization timelines and EU AI Act enforcement intensity. A model refresh is warranted upon material change in EMA clinical-grade material guidelines or F-Gas Regulation refrigerant restriction scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Gene Amplification Technologies Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Restriction Endonucleases Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Forensic Genomics Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Next Generation Sequencing Market
Genomics
Antisense Oligonucleotides Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
DNA Diagnostics Market
Genomics
Predisposition Biomarkers Market