
 Molecular Breeding Market | 2026-2036
Molecular Breeding Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Breeding Market Intelligence
Consolidation among major seed companies is restructuring procurement patterns for molecular breeding technologies. Bayer AG leverages its extensive seed portfolio to drive internal development of advanced traits. Corteva Agriscience competes through its integrated platform of seed genetics and crop protection solutions, creating a closed-loop system. LGC Limited specializes in providing high-throughput genotyping services and tools to the broader research community, serving both large corporations and academic institutions.
Molecular breeding involves the application of genomic tools, such as DNA markers, to accelerate the selection of desired traits in plant and animal development. This process utilizes techniques like high-density SNP marker analysis to identify genes linked to characteristics like yield or stress tolerance. SNP markers command a significant share due to their high abundance and suitability for automated, high-throughput analysis. Within applications, cereal improvement and disease resistance breeding represent the largest areas of investment for both public and private sector breeders.
Regulatory frameworks from the USDA in the United States and the European Food Safety Authority (EFSA) create divergent pathways for market access. These bodies set the standards for the safety assessment and commercialization of new plant varieties developed through advanced breeding techniques. Navigating the evolving regulatory distinctions between conventional genetic modification and newer genome editing methods is critical for stakeholder success.
Market Dynamics
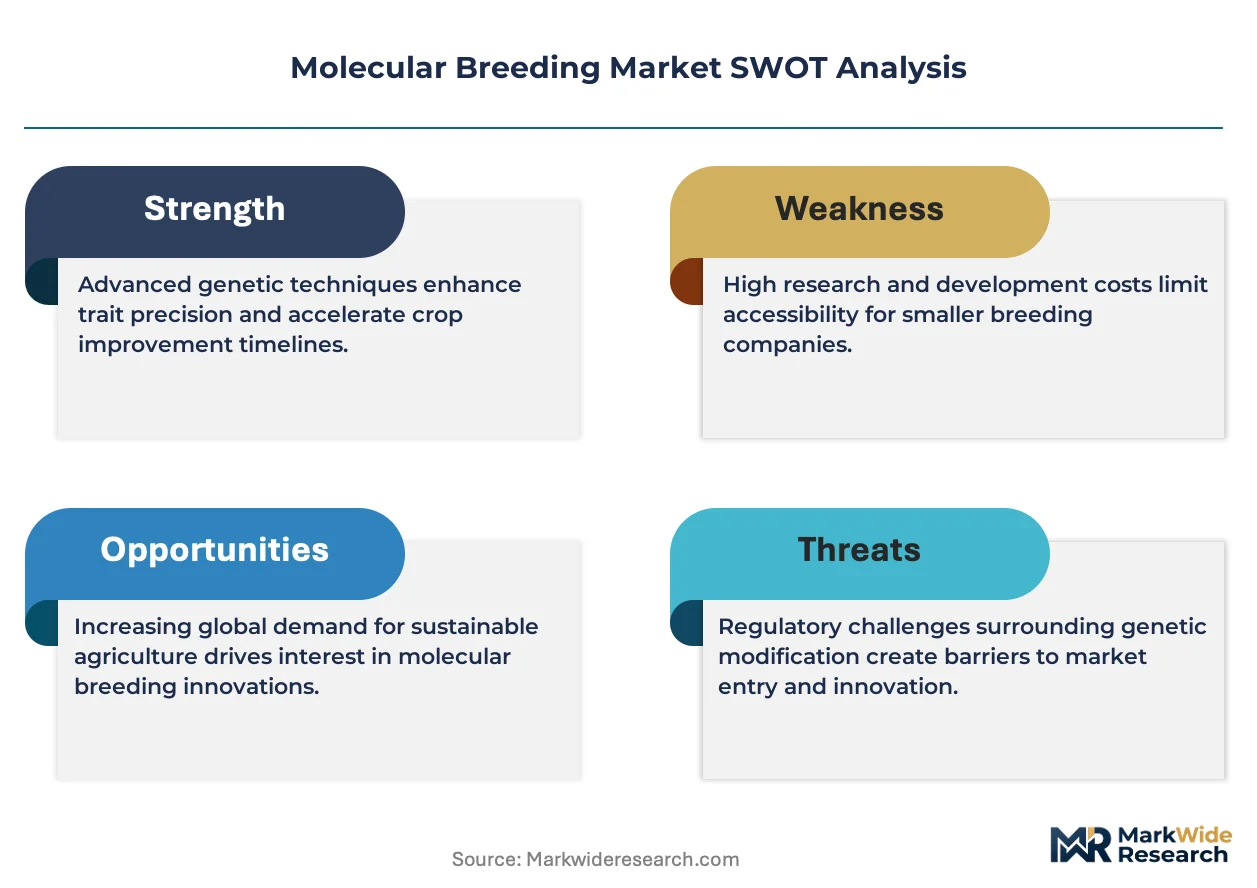
The molecular breeding market's trajectory is defined by the powerful interplay between rapid genomic technology innovation and fragmented, often slow-moving, regulatory frameworks. This dynamic creates both immense opportunity for accelerated crop improvement and significant uncertainty for market access and commercialization.
Growth Catalysts
- Genomic Technology Proliferation:The widespread availability of affordable, high-throughput SNP genotyping platforms enables faster and more precise selection cycles in large-scale cereal and oilseed improvement programs.
- National Food Security Policies:Government-led initiatives, particularly within China's agricultural sector, direct substantial public and private investment toward agritech, including molecular breeding tools to boost domestic crop production.
- Climate Resilience Demand:Growing environmental pressures accelerate the need for crops with enhanced stress tolerance, driving research investment into identifying genes linked to drought, heat, and salinity resistance.
Market Restraints
- Divergent Regulatory Frameworks:Conflicting standards for genome-edited products between the USDA in the United States and the European Food Safety Authority (EFSA) create significant compliance burdens and market fragmentation.
- High Capital Investment:The substantial upfront cost required to establish automated, high-throughput genotyping and phenotyping infrastructure limits adoption among smaller seed companies and public research institutions.
- Intellectual Property Complexity:A dense web of patents and licensing agreements surrounding foundational genome editing technologies like CRISPR creates legal risks and can slow the commercial development of new traits.
Strategic Opportunities
- Expansion into Orphan Crops:Applying molecular breeding techniques to specialty and orphan crops, such as legumes and regional fruits, presents an underpenetrated market segment beyond staple grains like wheat and corn.
- AI and Predictive Breeding:Integrating machine learning algorithms with vast genomic and environmental datasets allows for the prediction of complex trait performance, optimizing the design and efficiency of breeding programs.
- Service Model for Emerging Markets:Developing tailored molecular breeding services for agricultural economies in Sub-Saharan Africa and Southeast Asia addresses a critical technology gap and opens new geographic revenue streams.
Industry Challenges
- Bioinformatics Talent Gap:A persistent scarcity of skilled bioinformaticians and quantitative geneticists capable of managing and interpreting large-scale genomic data acts as a primary operational bottleneck for breeding programs.
- Data Interoperability:The absence of standardized formats for collecting and sharing genomic and phenotypic data across different platforms hinders large-scale collaborative research and validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Breeding Market |
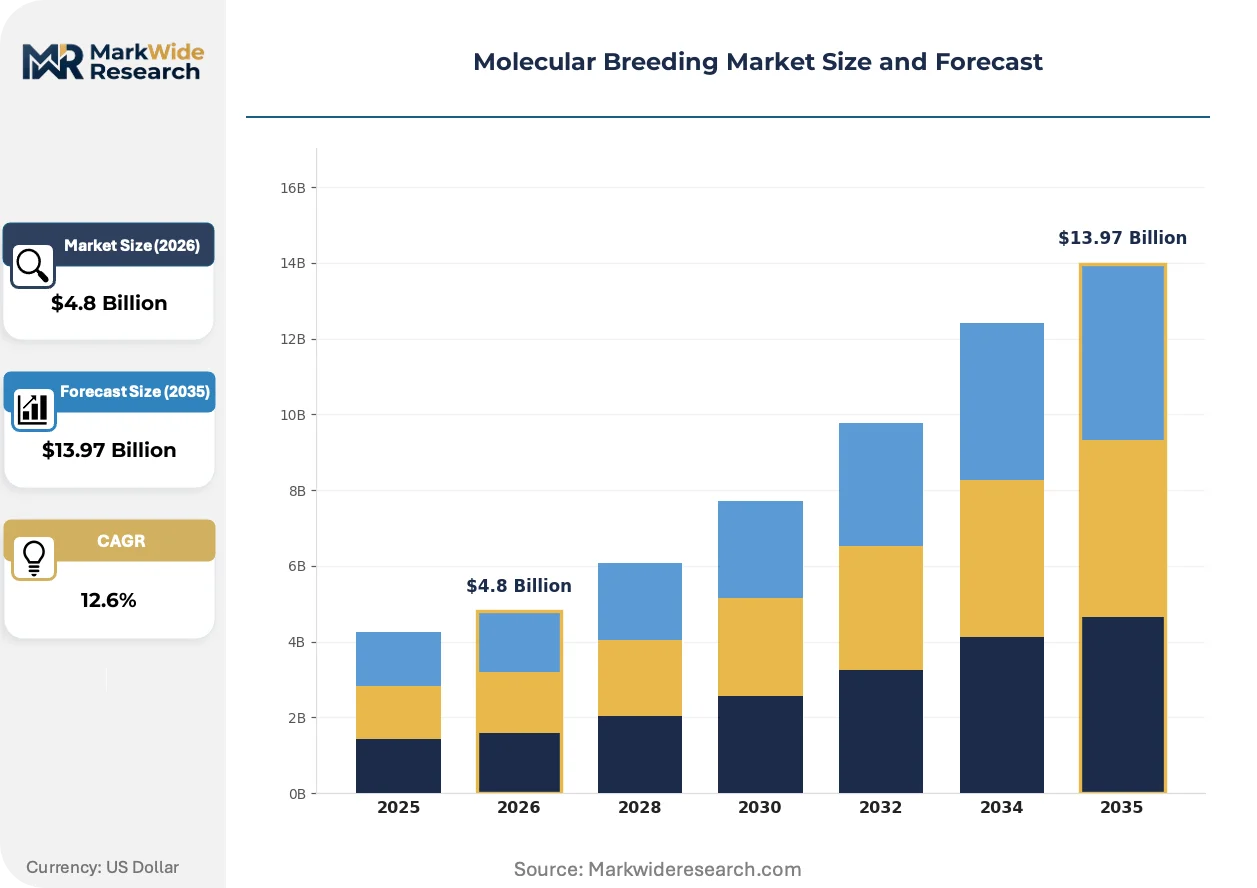
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Markers, SNP Markers, SSR Markers, RAPD Markers, AFLP Markers Application: Cereal Improvement, Horticulture Enhancement, Livestock Genetic Improvement, Biofuel Crop Development, Disease Resistance Breeding Technology: Marker-Assisted Selection, Marker-Assisted Backcrossing, Genomic Selection, RNA Interference, Genome Editing End User: Seed Companies, Agricultural Universities, Research Institutes, Biotechnology Firms, Plant Breeders |
| Companies Covered | Illumina, Thermo Fisher Scientific Inc., Bayer AG, Eurofins Scientific, LGC Limited, SGS, Corteva Agriscience, Syngenta Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Breeding Market Strategic Shifts & Innovations
The convergence of advanced data analytics with high-density genomic information is fundamentally reshaping the speed and precision of plant and animal trait development. This shift moves breeding programs beyond simple marker-assisted selection toward a more predictive and integrated science.
Pangenome sequencing captures the complete genetic diversity within a crop species, moving beyond a single reference individual. Major agricultural research consortia and large seed companies are rapidly adopting this technique for staple crops like maize, wheat, and rice. This approach is unifying disparate genomic datasets into a more holistic framework, enabling the discovery of novel genes for complex traits that were previously hidden.
Regulatory bodies in nations like Japan and Argentina are establishing streamlined approval pathways for specific genome-edited crops that do not contain foreign DNA. This distinction from traditionally defined GMOs significantly reduces development costs and accelerates the time to market. Small and medium-sized enterprises focused on specialty vegetable and fruit breeding are the primary beneficiaries, gaining more viable access to advanced breeding technologies.
A clear transition toward integrated "genotyping-as-a-service" business models is altering how breeders access technology. This service-based approach disrupts the traditional capital equipment purchasing cycle by offering outsourced, high-throughput data generation and analysis. The shift is most visible among academic institutions and mid-sized seed companies in North America and Europe that seek to leverage cutting-edge tools without major in-house investment.
Molecular Breeding Market Segmentation
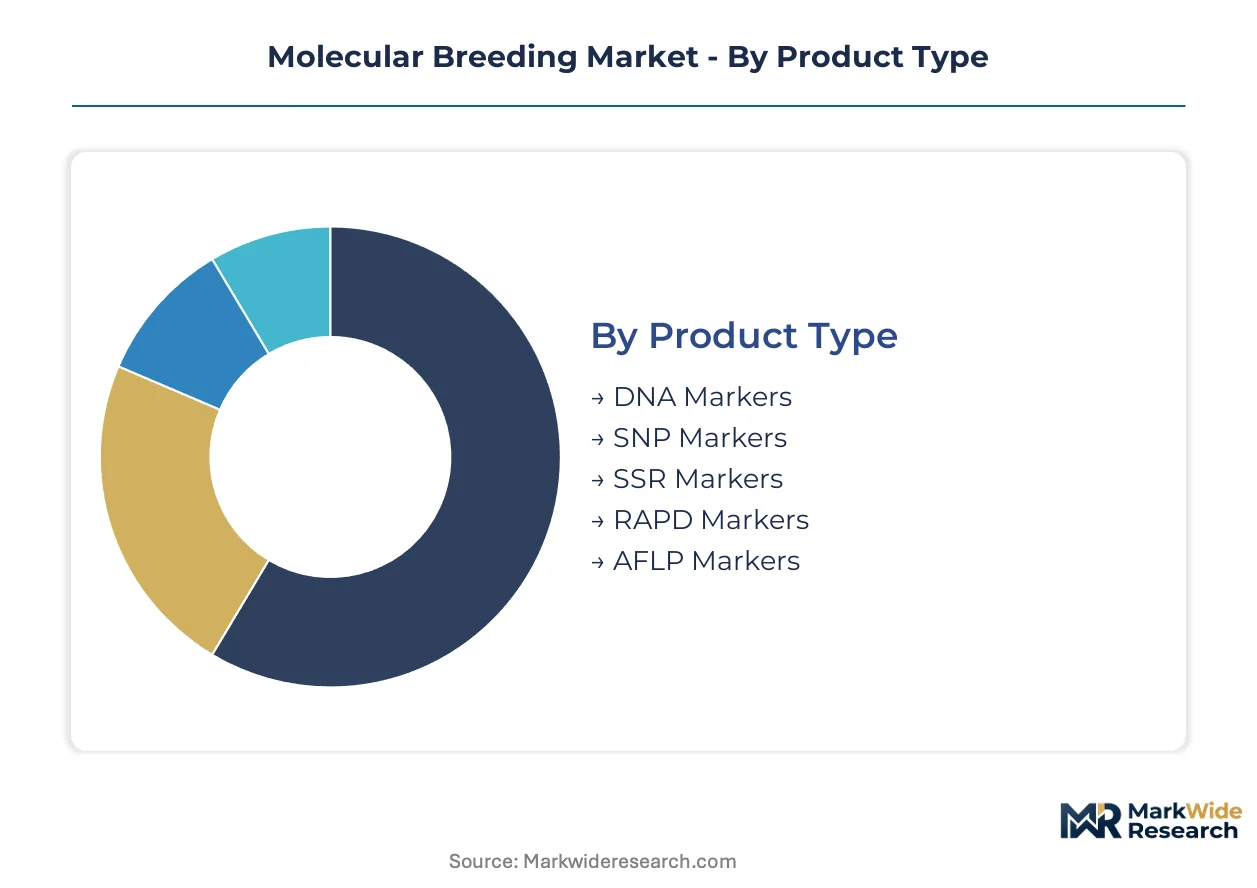
Understanding the molecular breeding market's segmentation is critical for stakeholders to identify specific growth vectors and address distinct user requirements. This granular analysis illuminates where technological advancements intersect with practical agricultural needs, guiding investment and product development strategies within the sector.
Product Type:
Molecular breeding programs frequently evaluate existing marker systems for upgrades or replacements, seeking more efficient and cost-effective genotyping solutions. This assessment drives shifts in product type adoption across research and commercial settings.
- SNP Markers:Single Nucleotide Polymorphism markers are highly abundant, co-dominant, and suitable for high-throughput automated analysis across diverse species. Demand concentrates among large seed companies and research institutions for precise trait mapping and genomic selection in staple crops.
- DNA Markers:These represent a broad category of genetic markers based on DNA sequence variations, including RFLPs and RAPDs, used to identify specific genes or traits. Demand remains strong in foundational research and for species where high-density SNP panels are not yet cost-effective.
- SSR Markers:Simple Sequence Repeat markers, also known as microsatellites, offer high polymorphism and co-dominance, useful for genetic diversity studies and parentage analysis.
- RAPD Markers:Random Amplified Polymorphic DNA markers are cost-effective, PCR-based markers that do not require prior sequence information, often used in preliminary genetic mapping.
- AFLP Markers:Amplified Fragment Length Polymorphism markers provide a high level of polymorphism detection across the genome, useful for genetic fingerprinting and mapping studies.
Volume placements concentrate in DNA Markers; the faster expansion belongs to SNP Markers.
Application:
The diverse applications of molecular breeding techniques reflect strategic investment priorities in addressing specific agricultural challenges and enhancing crop or livestock characteristics.
- Cereal Improvement:This application focuses on enhancing yields, nutritional content, and stress tolerance in major cereal crops like wheat, rice, and maize. Public and private sector breeders extensively use molecular tools to accelerate the development of superior varieties for global food security.
- Disease Resistance Breeding:Breeders apply molecular techniques to identify and incorporate genes conferring resistance to various plant pathogens and pests. This application addresses significant crop losses and reduces reliance on chemical treatments, with demand from both conventional and organic agriculture.
- Horticulture Enhancement:This segment uses molecular breeding to improve fruit quality, shelf life, pest resistance, and aesthetic traits in horticultural crops.
- Livestock Genetic Improvement:Molecular breeding assists in enhancing productivity traits like milk yield, meat quality, and disease resistance in livestock animals.
- Biofuel Crop Development:The focus here is on developing dedicated energy crops with increased biomass production and improved conversion efficiency for biofuel generation.
Significant investment targets Cereal Improvement, with Disease Resistance Breeding expanding most quickly.
Technology:
Technology maturity and accessibility dictate the adoption curves for various molecular breeding approaches, influencing which methods are widely deployed versus those in early-stage research.
- Genome Editing:This advanced technology allows for precise modifications to an organism's DNA, enabling targeted trait development with unprecedented accuracy. Research institutions and biotechnology firms in Japan and Argentina are particularly active in this area.
- Genomic Selection:This method uses genome-wide marker data to predict breeding values, accelerating selection cycles and improving the accuracy of trait prediction. Large seed companies leverage genomic selection for complex traits in major field crops.
- Marker-Assisted Selection:This traditional molecular breeding technique uses DNA markers linked to desired traits to select superior individuals in a breeding population.
- Marker-Assisted Backcrossing:This technique uses molecular markers to efficiently transfer a specific gene or trait from a donor parent into an elite recipient line.
- RNA Interference:RNAi technology involves gene silencing to modify gene expression, offering a tool for pest control or trait modification in plants.
Established methods like Marker-Assisted Selection maintain broad use, but Genome Editing shows the steepest expansion trajectory.
End User:
Different end-user segments leverage molecular breeding tools based on their operational scale, research capabilities, and commercial objectives within the agricultural value chain.
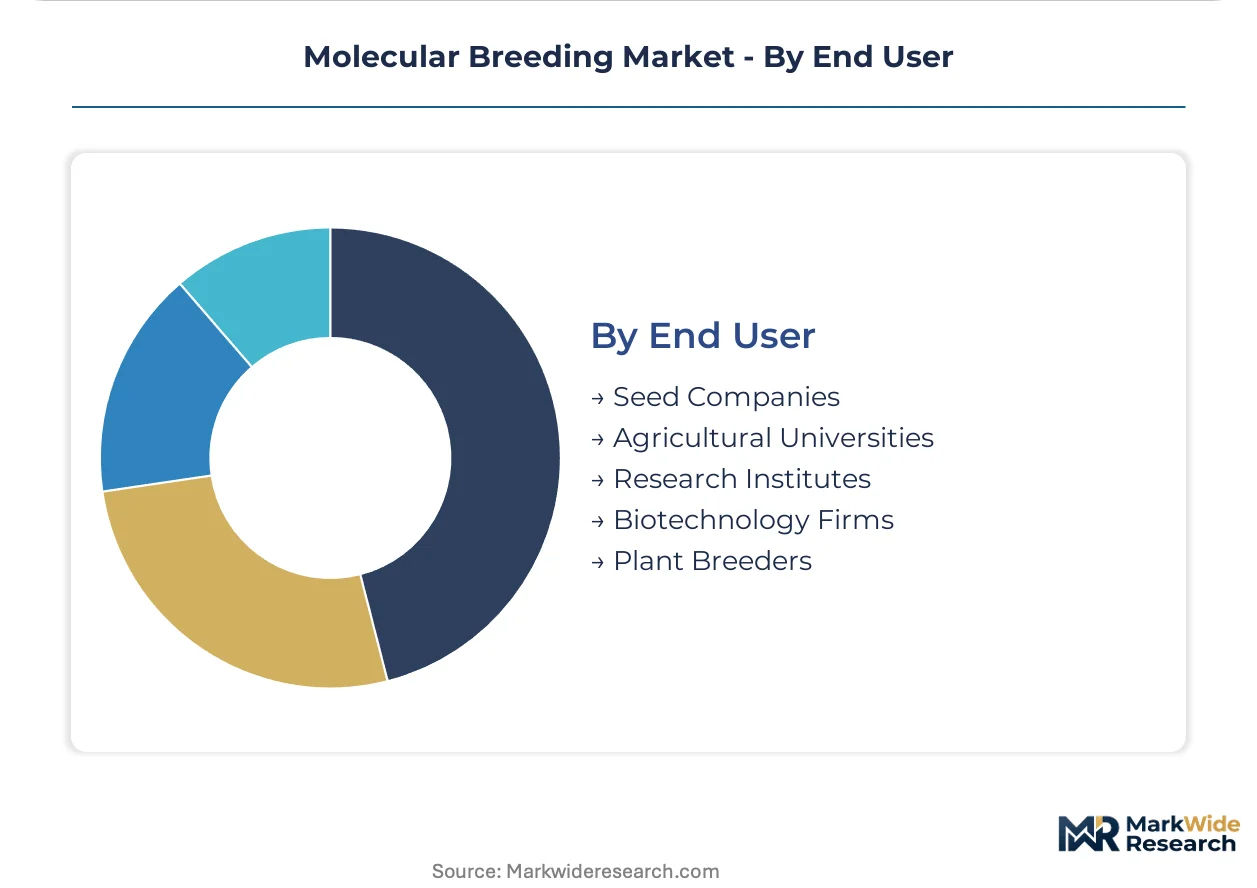
- Seed Companies:These entities apply molecular breeding extensively to develop and commercialize new crop varieties with enhanced traits, forming a core part of their product development pipeline. Bayer AG and Corteva Agriscience exemplify this concentrated internal development.
- Research Institutes:Public and private research organizations utilize molecular breeding for fundamental genetic studies, trait discovery, and the development of new breeding methodologies. LGC Limited provides high-throughput genotyping services to support these institutions.
- Agricultural Universities:Academic institutions conduct basic and applied research in molecular breeding, contributing to scientific knowledge and training the next generation of plant breeders.
- Biotechnology Firms:These companies specialize in developing novel genetic technologies and products, often licensing or partnering with seed companies for commercialization.
- Plant Breeders:Individual plant breeders, across various organizational settings, directly implement molecular breeding strategies to improve crop characteristics.
Seed Companies represent a major user segment, while Biotechnology Firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for molecular breeding technologies focuses significantly on China's agricultural sector. National food security initiatives and substantial agritech investments drive this concentration. This global demand shapes regional market dynamics and technology deployment across various continents.
China
China's agricultural sector drives significant molecular breeding demand for enhancing crop yields and nutritional value. The government's national food security initiatives, alongside GB standards for agricultural products, accelerate technology adoption. Investment in agritech clusters like the Yangtze River Delta supports advanced breeding research and deployment.
United States
United States demand emphasizes cereal improvement programs and the development of climate-resilient crops. USDA regulatory frameworks guide market access and commercialization pathways for advanced breeding techniques. Major seed companies in the Midwest agricultural belt leverage molecular breeding for trait development and product pipelines.
Japan
Japanese agricultural entities prioritize genome editing for specialty vegetable and fruit breeding. Regulatory bodies in Japan establish streamlined approval pathways for genome-edited crops without foreign DNA. Biotechnology firms and research consortia in Tokyo actively develop advanced breeding technologies.
Germany
German agricultural research focuses on integrated seed genetics and high-throughput genotyping services. The European Food Safety Authority (EFSA) influences market access and safety assessments for new plant varieties. Research institutions and biotechnology firms in Bavaria contribute to advanced molecular breeding techniques.
Argentina
Argentina exhibits strong demand for genome editing technologies to accelerate staple crop improvement. Argentinian regulatory bodies have established streamlined approval pathways for non-foreign DNA genome-edited products. Research centers and agricultural producers in the Pampas region adopt these advanced breeding methods.
Molecular Breeding Market Key Industry Players
North American and European seed companies anchor one tier; specialized service providers hold another. The molecular breeding market shows consolidation among major seed companies, alongside a fragmented landscape of technology providers. Integrated seed companies, specialized genotyping service providers, and biotechnology firms represent key strategic archetypes. Companies pursue M&A activities to expand portfolios, invest in internal development of advanced traits, and integrate crop protection solutions.
Integrated seed companies like Bayer AG and Corteva Agriscience exemplify the strategy of leveraging extensive seed portfolios for internal trait development. Bayer AG utilizes its vast seed business to drive advanced trait innovation, integrating its product development. Corteva Agriscience competes through its integrated platform of seed genetics and crop protection solutions, creating a closed-loop system for agricultural inputs. Conversely, LGC Limited occupies a distinct niche, specializing in providing high-throughput genotyping services and tools to the broader research community. This LGC Limited model serves both large corporations and academic institutions, offering specialized analytical capabilities without requiring major in-house investment from clients.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific Inc. |
| Bayer AG |
| Eurofins Scientific |
| LGC Limited |
| SGS |
| Corteva Agriscience |
| Syngenta Group |
| BASF SE |
| Others |
Cost & Logistics Intelligence
High-density SNP marker analysis platforms dictate upstream investment for genotyping service providers. This cost structure influences the pricing of advanced breeding tools for downstream agricultural end-users.
Pricing Analysis
Volume-based pricing dominates high-throughput genotyping services, while specialized trait development commands higher margins through licensing. Project-based pricing models often include customization for specific crop types or desired traits, alongside bundled bioinformatics support. Pricing pressure stems from the increasing availability of standardized SNP marker panels and competitive service providers. Smaller academic institutions and mid-sized seed companies exhibit higher price sensitivity compared to large, integrated agricultural corporations.
Supply Chain Analysis
Certification for molecular breeding products, particularly for genome-edited varieties, gates market access in regions like the European Union and the United States. The supply chain for advanced genomic tools concentrates heavily in the United States and Germany, with China emerging as a significant producer of basic reagents. Key dependencies include specialized enzymes for DNA manipulation and high-throughput sequencing equipment from a limited number of global manufacturers. Single-source vulnerability for proprietary reagents poses a structural risk, impacting service continuity. Distribution primarily runs through direct sales channels and specialized genotyping-as-a-service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molecular breeding market is witnessing a vertical-integration race, with major seed companies aggressively pursuing in-house development of advanced traits. This strategy aims to control the entire value chain from genetic discovery to commercial seed production.
For Market Incumbents: Cement market leadership through strategic M&A activities targeting niche genome editing technologies and specialized bioinformatics firms. Strengthen intellectual property portfolios around novel trait discoveries to counter the threat from emerging biotechnology firms. Invest heavily in AI and predictive breeding platforms to accelerate development cycles and maintain a competitive edge. Consolidate genotyping services internally to optimize cost structures and enhance data security.
For New Entrants and Emerging Players: Capture underserved segments by focusing molecular breeding efforts on orphan crops, such as legumes and regional fruits, beyond staple grains. Target emerging markets in Sub-Saharan Africa and Southeast Asia with tailored, cost-effective genotyping-as-a-service models. The specialty vegetable and fruit breeding market presents a highly penetrable segment due to streamlined regulatory pathways in countries like Japan. Develop partnerships with local agricultural cooperatives for localized trait development.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile biotechnology firms in regions with evolving regulatory clarity like Japan and Argentina. The market offers strong long-term viability over a 5-10 year window, driven by persistent food security and climate resilience demands. Identify acquisition targets with proprietary genome editing platforms or established high-throughput genotyping service footprints in key agricultural economies. Regulatory harmonization between major economic blocs, particularly concerning genome-edited products, serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Bioinformatics Specialist | Integrates advanced data analytics capabilities, enhancing predictive breeding accuracy for major seed companies. |
| Expansion into Orphan Crop Trait Development | Addresses unmet demand in specialty agriculture, diversifying revenue streams beyond staple cereals. |
| Licensing of Novel Genome Editing IP | Secures access to cutting-edge tools, accelerating precise trait development for biotechnology firms. |
| Development of AI-Driven Breeding Platforms | Optimizes selection cycles, significantly improving efficiency for large-scale cereal improvement programs. |
| Establishment of Regional Service Hubs | Extends genotyping-as-a-service models to emerging markets, addressing technology gaps in Sub-Saharan Africa. |
Research Approach
Independent corroboration across USDA reports, EFSA publications, and industry association whitepapers underwrites the qualitative findings. This approach combines insights from primary interviews with plant breeders, agronomists, and biotechnology executives. Secondary validation also draws from academic research databases and company financial filings. Bottom-up market sizing and top-down revenue analysis triangulate volume and value outputs for robust data integrity.
Rate-of-change decomposition analyzes market evolution across the projection horizon, considering historical trends and future growth drivers. The analytical framework models market dynamics by product type, application, technology, end-user, and specific crop types. Compound Annual Growth Rates (CAGRs) are derived through a weighted average of segment-specific growth trajectories. Key forecast inputs include R&D spending in advanced genomics and regional regulatory approval rates for new varieties.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory distinctions and unforeseen technological breakthroughs. These forecasts reflect current market assumptions. A model refresh is warranted upon material change in global food security policies or major genome editing advancements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Gene Expression Market
Genomics
DNA Microarray Market
Genomics
Microarray Biochips Market
Genomics
Forensic Genomics Market
Genomics
Apolipoprotein Test Market
Genomics
Predisposition Biomarkers Market
Genomics
Mitochondrial DNA Market
Genomics
Genetic Material Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Gene Sequencing Market
Genomics
Latin America Gene Expression Market
Genomics
Prenatal Genetic Testing Market
Genomics
Transcriptomics Technologies Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Restriction Endonucleases Market
Genomics
DNA Mass Ladder Market