
 Pharmacogenomic (Pgx) Testing Market | 2026-2036
Pharmacogenomic (Pgx) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacogenomic (Pgx) Testing Market Analytics
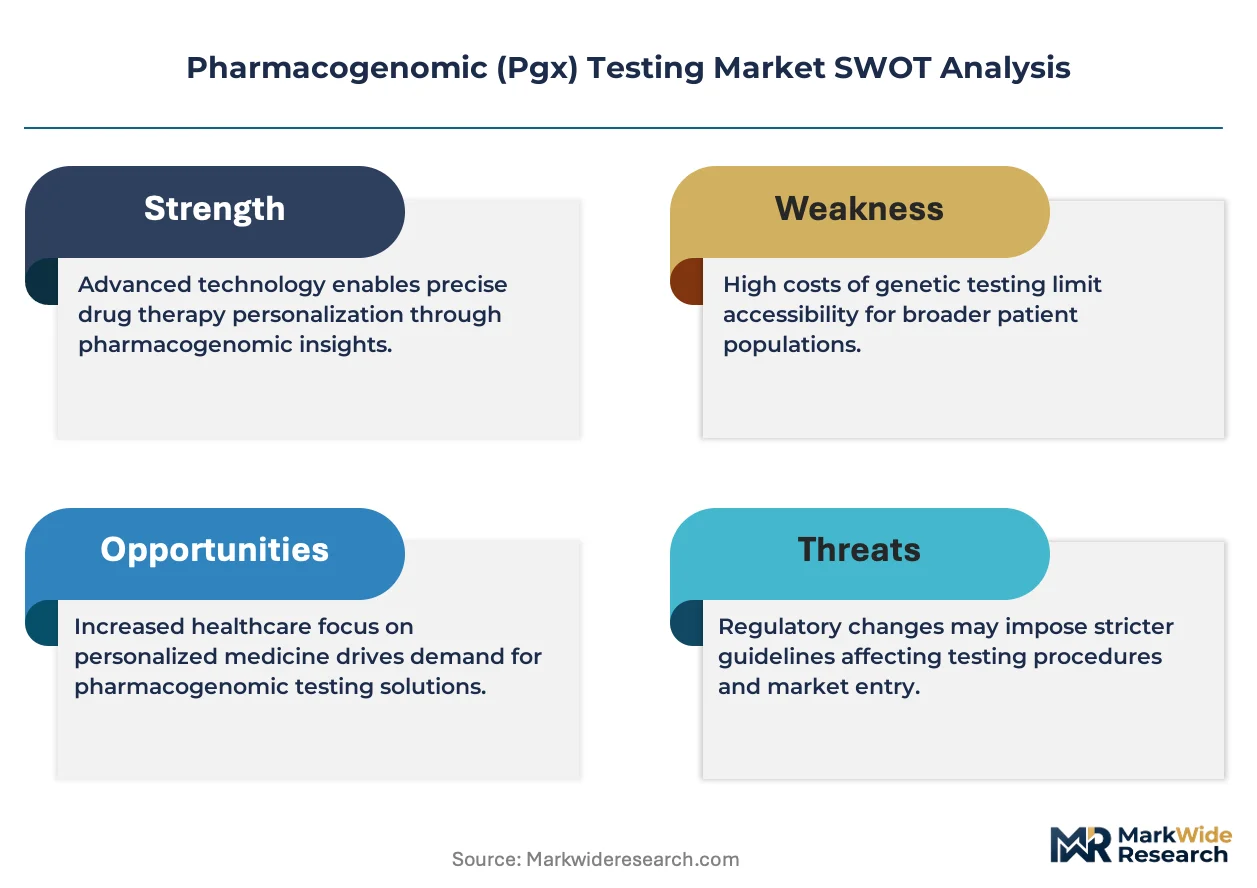
CLIA certification and CAP laboratory accreditation is unwinding competitive access across the pharmacogenomic testing landscape. Thermo Fisher Scientific leverages its end-to-end instrument and reagent portfolio to sustain integrated workflow dominance in clinical laboratories. QIAGEN anchors its position through specialized bioinformatics pipelines that interpret pharmacogenomic variant data for therapeutic decision support. Illumina competes by extending its sequencing platform installed base into hospital-based PGx programs.
Pharmacogenomic testing analyzes genetic variations affecting individual drug metabolism, efficacy, and toxicity through DNA sequencing, PCR amplification, and microarray hybridization against established pharmacogene reference panels. The technology enables clinicians to select optimal therapeutics and dosing regimens based on a patient's inherited genotype rather than empirical trial-and-error prescribing. Next-generation sequencing platforms capture the largest value share within the technology dimension due to multiplexed panel capabilities and declining per-sample costs. Oncology applications generate the deepest margin pools as oncologists deploy comprehensive pharmacogenomic profiling to guide targeted therapy selection across solid tumors and hematologic malignancies.
FDA pharmacogenomic biomarker table updates and CLIA quality standards shape test development requirements and laboratory operational compliance across the United States. CAP proficiency testing programs and state laboratory licensing boards enforce analytical validity thresholds that determine which laboratories qualify for clinical sample processing. Stakeholders must monitor evolving payer coverage determinations for multi-gene pharmacogenomic panels as commercial insurers and CMS refine reimbursement criteria for preemptive versus reactive testing strategies.
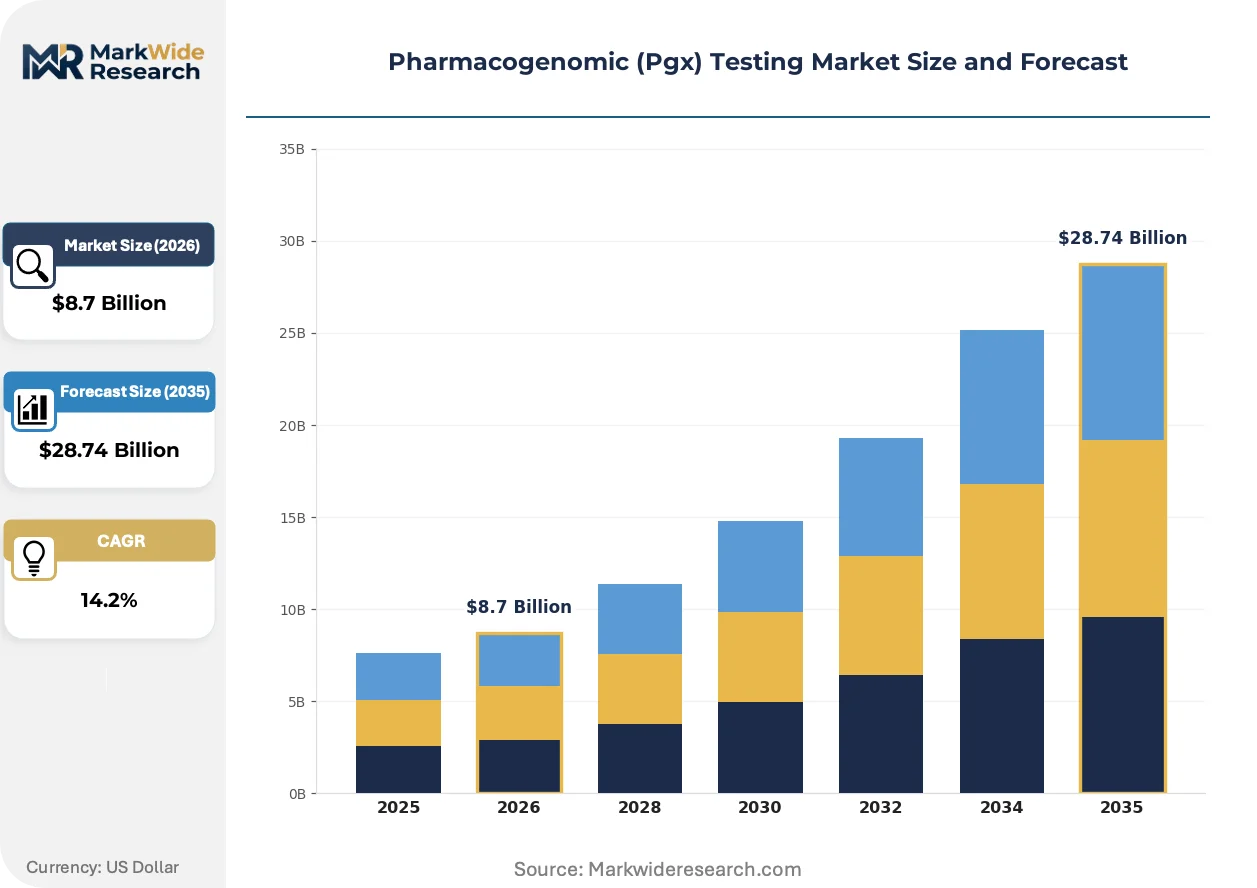
Market Dynamics
The pharmacogenomic testing market is restructuring around CLIA certification requirements and CAP laboratory accreditation, which filter competitive access and consolidate analytical validity standards across clinical sample processing networks.
Growth Catalysts
- FDA Biomarker Table Expansion:The agency's pharmacogenomic biomarker table updates accelerate test standardization and enable broader therapeutic area coverage for clinical laboratories.
- Medicare Reimbursement Maturation:Mental health and cardiology PGx testing now qualify for coverage, expanding addressable patient populations beyond oncology.
- NGS Platform Economics:Multiplexed panel capabilities and declining per-sample costs enable hospital systems to integrate comprehensive profiling into routine chemotherapy selection protocols.
Market Restraints
- Reagent Supply Concentration:Specialized polymerase enzymes and fluorescent probe chemistries concentrate among a limited supplier base, creating input cost volatility for PCR-based assays.
- State Licensing Fragmentation:Laboratory licensing boards impose non-uniform operational requirements that complicate multi-state clinical sample processing for reference laboratories.
- Interpretation Bottleneck:Bioinformatics pipeline complexity and variant classification uncertainty limit test turnaround times and constrain report standardization.
Strategic Opportunities
- Preemptive Testing Protocols:Health systems in Germany and France are piloting population-scale pharmacogenomic screening programs that trigger reimbursement expansion for multi-gene panels.
- Point-of-Care Integration:Rapid genotyping assays for warfarin and clopidogrel metabolism enable pharmacy-based therapeutic decision support outside centralized laboratories.
- AI-Augmented Variant Interpretation:Machine learning classification algorithms are converging with curated pharmacogene databases to automate clinical report generation and reduce pathologist review burden.
Industry Challenges
- CAP Proficiency Testing Burden:Quarterly external quality assessment requirements strain smaller laboratories with limited quality control infrastructure and personnel bandwidth.
- EHR Integration Complexity:Pharmacogenomic result codes lack standardized interoperability with legacy electronic health record systems, forcing manual clinician workflow interruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacogenomic (Pgx) Testing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, PCR Testing, Microarray Analysis, Gene Expression Profiling Application: Oncology, Cardiology, Infectious Diseases, Neurology End User: Hospitals, Clinical Laboratories, Academic Research Institutes, Pharmaceutical Companies Technology: Next-Generation Sequencing, Sanger Sequencing, Mass Spectrometry, Bioinformatics |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., QIAGEN, F. Hoffmann-La Roche Ltd, Myriad Genetics, Inc., Abbott Laboratories, Bio-Rad Laboratories, Inc., Quest Diagnostics Incorporated, OneOme, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacogenomic (Pgx) Testing Market Evolving Landscape
Next-generation sequencing platforms are compressing cost structures and enabling multiplexed therapeutic area expansion, while regulatory frameworks mature to accommodate preemptive genetic screening models.
Comprehensive pharmacogenomic profiling is displacing single-gene companion diagnostic approaches in oncology departments. Hospital-based cancer centers are adopting 12-20 gene panels for chemotherapy selection. This displacement compresses the addressable market for standalone CYP2D6 or TPMT assays.
EMA's In Vitro Diagnostic Regulation implementation is reshaping conformity assessment pathways for pharmacogenomic assays marketed across European Union member states. Manufacturers must now engage notified bodies for clinical evidence review. German and Dutch reference laboratories are accelerating IVDR technical documentation preparation.
Hospital procurement departments are consolidating pharmacogenomic testing contracts under centralized laboratory service agreements. Independent reference laboratories face exclusion from preferred vendor lists. This concentration is most visible in United States health system networks exceeding ten affiliated hospitals.
Pharmacogenomic (Pgx) Testing Market Segmentation
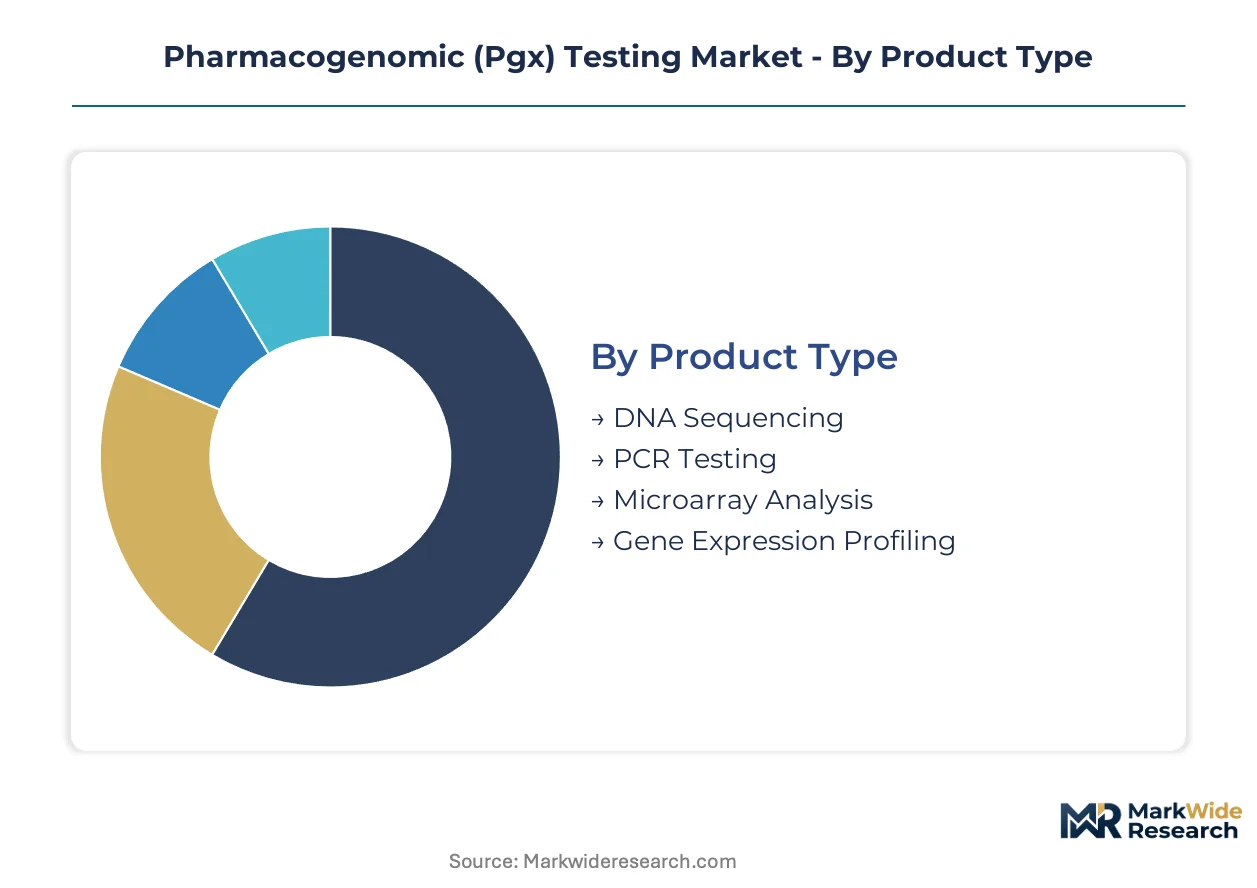
Pharmacogenomic testing segments reveal distinct geographic and institutional demand patterns. Product categories diverge sharply between high-throughput hospital systems and distributed point-of-care settings. Application areas concentrate in oncology within the United States while cardiology programs gain traction across European health networks.
Product Type:
Domestic demand concentrates in PCR-based assays for routine clinical workflows, while DNA sequencing platforms drive export-led revenue through instrument sales to emerging health systems.
- DNA Sequencing:Platforms detect single-nucleotide variants, insertions, and deletions across pharmacogene panels through targeted enrichment and high-throughput read generation. United States cancer centers deploy these systems for preemptive screening protocols ahead of chemotherapy initiation.
- PCR Testing:Amplification-based assays deliver rapid turnaround for CYP450 family variants and TPMT genotyping with minimal bioinformatics overhead. German hospital laboratories favor PCR workflows for same-day warfarin dosing decisions.
- Microarray Analysis:Hybridization-based detection covers common pharmacogenomic variants at moderate throughput for research screening applications.
- Gene Expression Profiling:RNA quantification methods assess drug response biomarkers in immuno-oncology therapeutic monitoring.
PCR testing commands the established base. The steepest expansion runs through DNA sequencing.
Application:
Margin structures vary by therapeutic complexity, with solid tumor profiling commanding premium pricing over cardiovascular risk stratification.
- Oncology:Comprehensive profiling guides targeted therapy selection across solid tumors and hematologic malignancies through multi-gene somatic and germline analysis. United States Medicare reimbursement maturation for preemptive screening accelerates hospital adoption.
- Cardiology:CYP2C19 and VKORC1 genotyping optimizes antiplatelet and anticoagulant prescribing for coronary artery disease patients. Dutch cardiovascular centers integrate rapid genotyping into catheterization laboratory workflows.
- Infectious Diseases:Pharmacogenomic markers predict antiretroviral drug toxicity and hepatitis C treatment response in specialized infectious disease units.
- Neurology:CYP2D6 and CYP2C19 variants inform psychotropic medication selection for depression and epilepsy management.
Oncology captures the deepest margin pools. Cardiology applications are climbing the fastest as European reimbursement frameworks mature.
End User:
Procurement authority concentrates in centralized laboratory service agreements, squeezing independent reference laboratories from preferred vendor lists.
- Hospitals:Integrated health systems deploy pharmacogenomic testing within oncology and cardiology departments to guide therapeutic decision-making at the point of care. United States networks exceeding ten affiliated hospitals consolidate testing contracts under single-vendor arrangements.
- Clinical Laboratories:Independent reference laboratories process samples from physician offices and smaller hospitals under CLIA certification and CAP accreditation requirements. State licensing fragmentation complicates multi-state operations for these facilities.
- Academic Research Institutes:University medical centers conduct population-scale pharmacogenomic studies and biomarker discovery programs.
- Pharmaceutical Companies:Drug developers apply pharmacogenomic data to stratify clinical trial populations and support companion diagnostic submissions.
Hospitals control the volume base. Pharmaceutical companies are gaining share fastest through trial-enrichment partnerships.
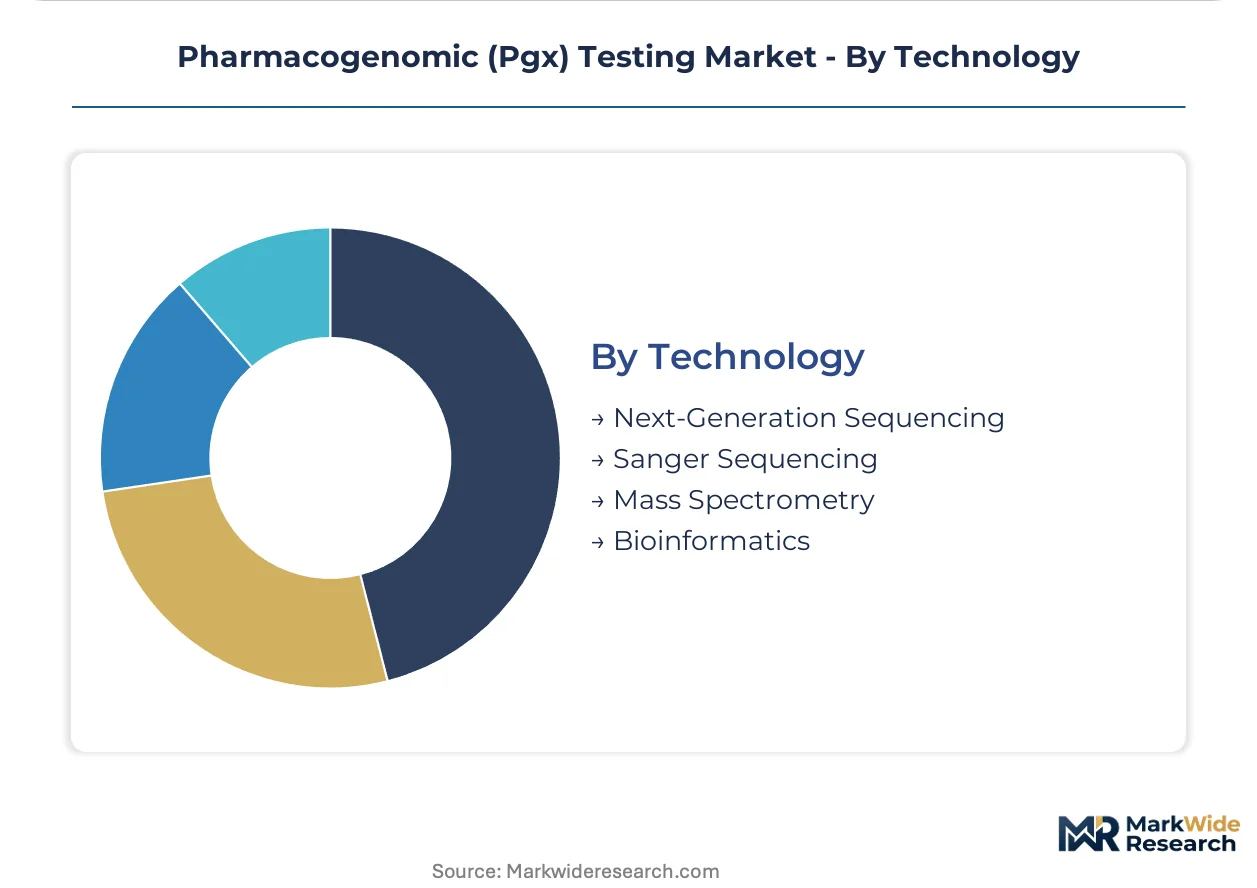
Technology:
Platform economics favor multiplexed detection methods as per-sample costs decline and panel content expands.
- Next-Generation Sequencing:Massively parallel sequencing enables simultaneous detection of hundreds of pharmacogenomic variants across multiple therapeutic genes. United States clinical laboratories deploy NGS platforms for comprehensive chemotherapy selection panels.
- Sanger Sequencing:First-generation sequencing confirms variants detected by screening methods and resolves ambiguous calls in low-complexity samples.
- Mass Spectrometry:Matrix-assisted laser desorption methods quantify drug metabolite levels for pharmacokinetic phenotyping applications.
- Bioinformatics:Variant classification pipelines interpret raw sequence data against curated pharmacogene databases for clinical report generation.
Next-generation sequencing anchors the installed base. Bioinformatics capabilities are expanding most quickly as AI-augmented interpretation tools reduce pathologist review burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments concentrate demand in integrated health systems exceeding ten affiliated facilities. Medicare reimbursement maturation for mental health and cardiology applications accelerates United States volume. European health networks pilot population-scale screening programs.
United States
Oncology departments within hospital systems drive fastest-growing demand as clinicians integrate genetic screening into chemotherapy selection protocols. FDA expanded guidance on pharmacogenomic biomarker table updates accelerates test standardization. The Greater Boston cluster anchors precision medicine research with hospital-based cancer centers deploying comprehensive profiling panels.
Germany
Reference laboratories accelerate IVDR technical documentation preparation for conformity assessment pathways. EMA In Vitro Diagnostic Regulation implementation reshapes clinical evidence review requirements. The Munich-Stuttgart corridor concentrates diagnostic manufacturing with specialized bioinformatics pipeline development for therapeutic decision support.
Netherlands
Cardiovascular centers integrate rapid genotyping into catheterization laboratory workflows for antiplatelet optimization. Dutch reimbursement frameworks mature for preemptive pharmacogenomic screening programs. The Rotterdam-Utrecht health network pilots population-scale multi-gene panel deployment in routine cardiac care protocols.
France
Health systems pilot population-scale pharmacogenomic screening programs triggering reimbursement expansion. ANSM oversees clinical evidence standards for pharmacogenomic assay marketing authorization. The Paris-Saclay cluster concentrates academic medical centers conducting biomarker discovery and trial-enrichment partnerships with pharmaceutical developers.
United Kingdom
NHS England evaluates preemptive testing protocols for mental health medication selection in specialized psychiatric units. MHRA guidance aligns with evolving FDA biomarker table standards for test development. The Cambridge-London corridor anchors genomic medicine research with integrated hospital-laboratory service agreements consolidating procurement authority.
Pharmacogenomic (Pgx) Testing Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with end-to-end workflow portfolios. Thermo Fisher Scientific leverages integrated instrument-reagent dominance in clinical laboratories. QIAGEN anchors position through specialized bioinformatics pipelines. Competitive moves center on CAP accreditation consolidation and AI-augmented variant interpretation licensing.
Among platform-technology providers, Illumina, Inc. and Thermo Fisher Scientific Inc. represent the sequencing and integrated workflow archetypes respectively. QIAGEN occupies a position within the specialized interpretation tier. These three entities exemplify how competitive positioning diverges between hardware-installed-base expansion and software-driven clinical decision support.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Myriad Genetics, Inc. |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| Quest Diagnostics Incorporated |
| OneOme, LLC |
| Others |
Value Network & Pricing Analysis
CLIA certification and CAP laboratory accreditation gate both supply qualification and price differentiation simultaneously across the pharmacogenomic testing landscape, forcing laboratories to absorb compliance costs that concentrate pricing power among accredited high-volume operators while squeezing margin structures for smaller facilities.
Pricing Analysis
Cost-plus contracts with Medicare reimbursement indexation anchor pricing for hospital-based PGx programs, with three-tier pricing structure across premium, standard, and economy levels driven by panel complexity and turnaround speed. Price differentiation rests on CAP accreditation status and NGS platform throughput scale. Cost compression in PCR-based assays is intensifying because reagent supply concentrates among limited enzyme suppliers. Academic medical centers exhibit highest price sensitivity; integrated health systems leverage volume consolidation for least sensitivity.
Supply Chain Analysis
Inventory lead times for specialized polymerase enzymes and fluorescent probe chemistries extend 8-12 weeks, creating procurement bottlenecks for clinical laboratories. Supply concentrates in the United States, Germany, and the Netherlands for NGS instrumentation and bioinformatics pipelines. Raw material dependencies include semiconductor chips for sequencing platforms, specialized reagents for PCR amplification, and curated pharmacogene databases for variant interpretation. Single-source vulnerability runs through thermostable polymerase suppliers. Distribution runs through centralized laboratory service agreements at integrated health systems exceeding ten affiliated hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacogenomic testing represents high-growth disruption as FDA biomarker table expansion and AI-augmented variant interpretation converge to compress test turnaround times and expand reimbursable applications beyond oncology into mental health and cardiology.
For Market Incumbents: Consolidate CAP accreditation coverage across multi-state laboratory networks to defend against emerging point-of-care genotyping entrants. Deepen backward integration into specialized reagent manufacturing to mitigate polymerase supply concentration. Lock in exclusive bioinformatics licensing agreements with academic medical centers to secure variant interpretation pipelines.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market access for AI-driven pharmacogenomic report generation tools. Target pharmacy-based warfarin and clopidogrel rapid genotyping as the most penetrable white space. Pursue white-label partnerships with independent reference laboratories lacking in-house bioinformatics capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across NGS platform-as-a-service models as cloud-based variant interpretation displaces on-premise infrastructure. Five-to-ten year viability favors laboratories with preemptive testing contracts at integrated health systems. Target acquisition archetype: mid-scale CLIA-certified facilities with established oncology department relationships. Signal to watch: CMS national coverage determination expansions for multi-gene panels.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Variant Interpretation Licensing | Machine learning algorithms from Tempus and Foundation Medicine automate pathologist review for clinical report generation. |
| Preemptive Testing Hospital Partnerships | Exclusive service agreements with United States health systems exceeding ten hospitals lock in multi-year revenue visibility. |
| IVDR Technical Documentation Acceleration | European reference laboratories in Germany and the Netherlands front-run conformity assessment for EU market access. |
| Point-of-Care Rapid Genotyping Deployment | Pharmacy-based warfarin and clopidogrel testing displaces centralized laboratory workflows for anticoagulant optimization. |
| Reagent Backward Integration | Thermo Fisher Scientific and QIAGEN secure captive polymerase supply chains against input cost volatility. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, hospital oncology department heads, bioinformatics pipeline developers, and Medicare reimbursement policy specialists and refined through secondary validation against FDA pharmacogenomic biomarker table updates, CMS national coverage determinations, CAP proficiency testing program requirements, and EMA IVDR implementation guidance. Bottom-up and top-down triangulation reconciled test volume estimates from hospital procurement databases with instrument installed base data from NGS platform manufacturers.
Variance-decomposition framing separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application area, end-user institution scale, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for technology adoption spliced with reimbursement policy phase-in schedules. Industry-specific forecast inputs incorporated CLIA laboratory certification counts and CAP accreditation renewal rates.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement expansion for multi-gene panels or accelerated FDA biomarker table updates would require recalibration. Forecasts reflect documented assumptions regarding NGS platform cost decline trajectories and AI variant interpretation accuracy improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Europe Genetic Testing Market
Genomics
Forensic Genomics Market
Genomics
Next Generation Sequencing Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
US Genetic Testing Market
Genomics
Genetic Testing Panels Market
Genomics
Plant Genomics Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Immunogenetics Market
Genomics
Antisense Oligonucleotides Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Reproductive Genetics Market
Genomics
NGS-Based RNA-Sequencing Market