
 DNA Diagnostics Market | 2026-2036
DNA Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Diagnostics Market Analysis
Clinical laboratories is reorganizing demand patterns as hospital systems consolidate molecular testing services. Illumina Inc. dominates sequencing instrument placements through captive reagent ecosystems. Thermo Fisher Scientific Inc. extends its position via integrated workflow solutions spanning sample prep to data analysis. Danaher Corporation leverages its diagnostics platform architecture to sustain pricing power in automated nucleic acid extraction.
DNA diagnostics encompasses molecular assays that detect, quantify, or characterize nucleic acid sequences for clinical or forensic purposes, typically operating through PCR amplification, hybridization, or sequencing chemistries with sensitivity thresholds reaching single-copy detection. The technology generates actionable information for disease identification, therapeutic selection, and hereditary risk stratification. Sequencing platforms command premium instrument placements but face margin pressure from consumables commoditization, while PCR retains volume leadership in infectious disease surveillance due to turnaround speed and regulatory familiarity. Oncology applications concentrate the highest per-test value as companion diagnostic mandates expand across solid tumor categories.
FDA oversight of laboratory-developed tests and companion diagnostic co-approval requirements shapes product development timelines and commercial access pathways in the United States. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards and post-market surveillance obligations across European markets. Stakeholders must monitor evolving payer coverage policies for multi-gene panel tests and liquid biopsy applications to anticipate reimbursement-driven demand shifts.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing vendor relationships, forcing molecular diagnostics suppliers to restructure pricing and service models around multi-site enterprise contracts rather than individual laboratory procurement.
Growth Catalysts
- Oncology companion diagnostics mandates:FDA co-approval requirements for targeted therapies are expanding molecular profiling volumes across solid tumor categories, embedding diagnostic testing into standard-of-care protocols.
- PCR infrastructure in infectious disease surveillance:Public health agencies maintain platform investments for pathogen detection, sustaining consumable demand through established regulatory pathways and rapid turnaround requirements.
- Liquid biopsy clinical validation:Circulating tumor DNA applications are penetrating minimal residual disease monitoring and early cancer detection, opening reimbursement discussions with Medicare and private payers.
Market Restraints
- Reagent commoditization pressure:Open-platform chemistry alternatives are eroding margins on proprietary consumables, particularly affecting sequencing instrument vendors dependent on captive supply economics.
- EU MDR transition costs:EMA's stricter clinical evidence requirements and notified body capacity constraints are extending certification timelines and inflating regulatory compliance expenditures for European market access.
- Specialized workforce scarcity:Bioinformatics interpretation and clinical molecular genetics expertise concentrates in academic medical centers, limiting test expansion into community hospital settings.
Strategic Opportunities
- Pharmacogenomic expansion in psychiatry:CYP450 genotyping for antidepressant selection remains underpenetrated relative to oncology, presenting white space for assay developers addressing medication response prediction.
- Direct-to-consumer regulatory clarity:FDA framework evolution for consumer-initiated genetic testing is creating channel access for hereditary risk screening products beyond traditional clinical ordering.
- CRISPR-based diagnostic platforms:Convergence of gene editing biochemistry with portable detection hardware is enabling point-of-care nucleic acid testing outside centralized laboratory infrastructure.
Industry Challenges
- Multi-gene panel reimbursement uncertainty:Payer coverage policies for expanded genomic profiling lack standardization, creating revenue recognition challenges and prior authorization bottlenecks for molecular pathology laboratories.
- Laboratory information system integration:Disparate data formats between sequencing platforms and electronic health records impede clinical workflow efficiency, requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Diagnostics Market |
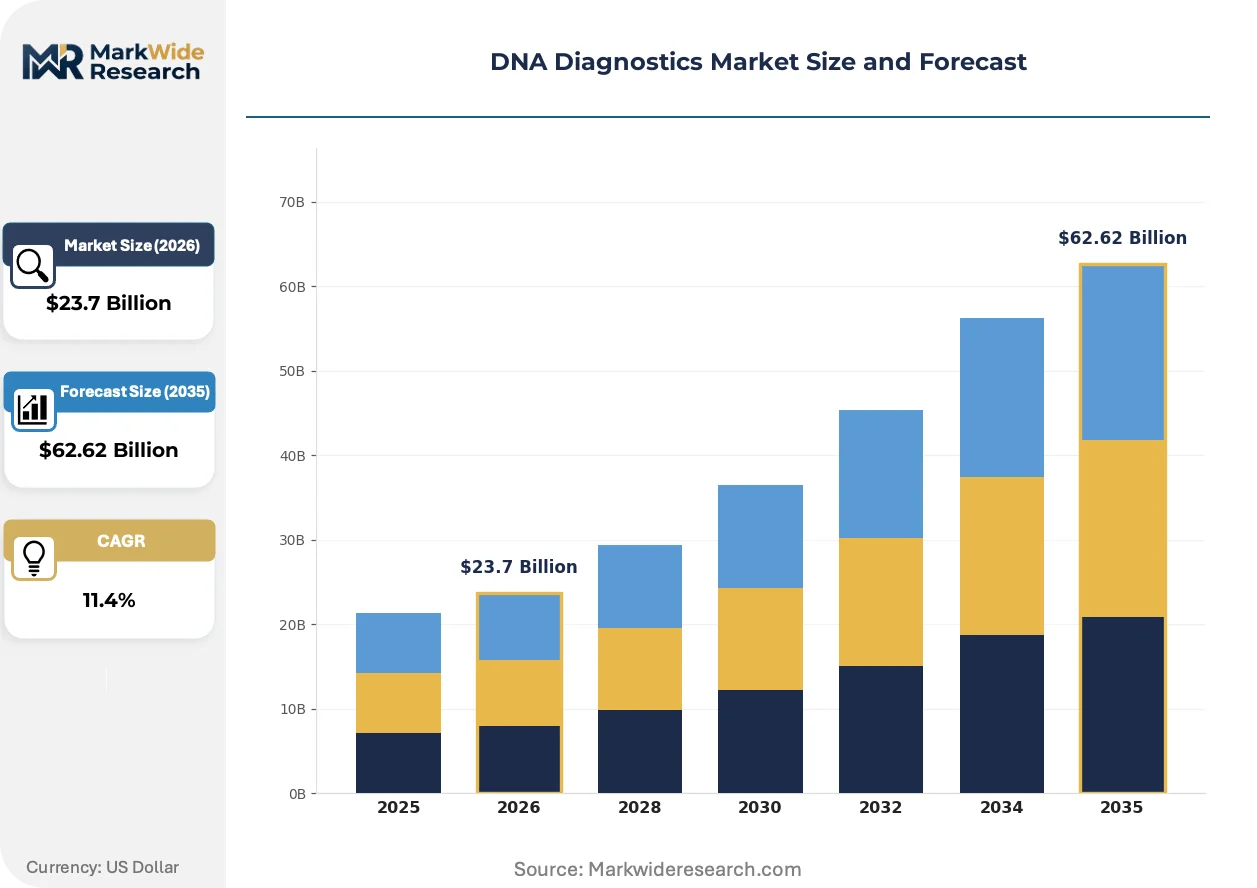
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Kits Application: Oncology, Infectious Diseases, Genetic Testing, Forensics Technology: Sequencing, PCR, Microarray, CRISPR End User: Hospitals, Laboratories, Research Institutions, Clinics |
| Companies Covered | Illumina Inc., Danaher Corporation, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Abbott Laboratories, QIAGEN, Bio-Rad Laboratories Inc., Agilent Technologies Inc., Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Diagnostics Market Emerging Trajectories
Next-generation sequencing platforms are fragmenting into distinct performance tiers as clinical applications diverge from research-scale throughput requirements, reshaping vendor competitive positioning and instrument placement strategy.
Sequencing chemistry is bifurcating into two performance categories: high-throughput systems serving population-scale genomics and rapid-turnaround instruments targeting acute care decision-making. Emergency departments and intensive care units are adopting nanopore and other long-read technologies for same-day pathogen identification and pharmacogenomic guidance. This technology split is compressing the mid-range instrument market, forcing manufacturers to defend installed bases through reagent lock-in and service bundling rather than hardware differentiation.
EMA's In Vitro Diagnostic Regulation is imposing post-market surveillance obligations and clinical performance documentation requirements that exceed predecessor directives. Manufacturers face expanded quality management system audits and periodic safety reporting for devices across risk classes. Companion diagnostic developers targeting European oncology markets are responding by front-loading clinical validation studies and establishing EU-based authorized representatives to maintain market access.
Health system procurement is consolidating molecular testing under centralized laboratory medicine governance, displacing decentralized department-level purchasing. Integrated delivery networks in the United States are negotiating enterprise-wide reagent contracts and demanding standardized platforms across affiliated hospitals. This buyer concentration is most visible in multi-state health systems pursuing laboratory network optimization, where CFO oversight of supply chain spend is overriding individual pathologist instrument preferences.
DNA Diagnostics Market Segmentation
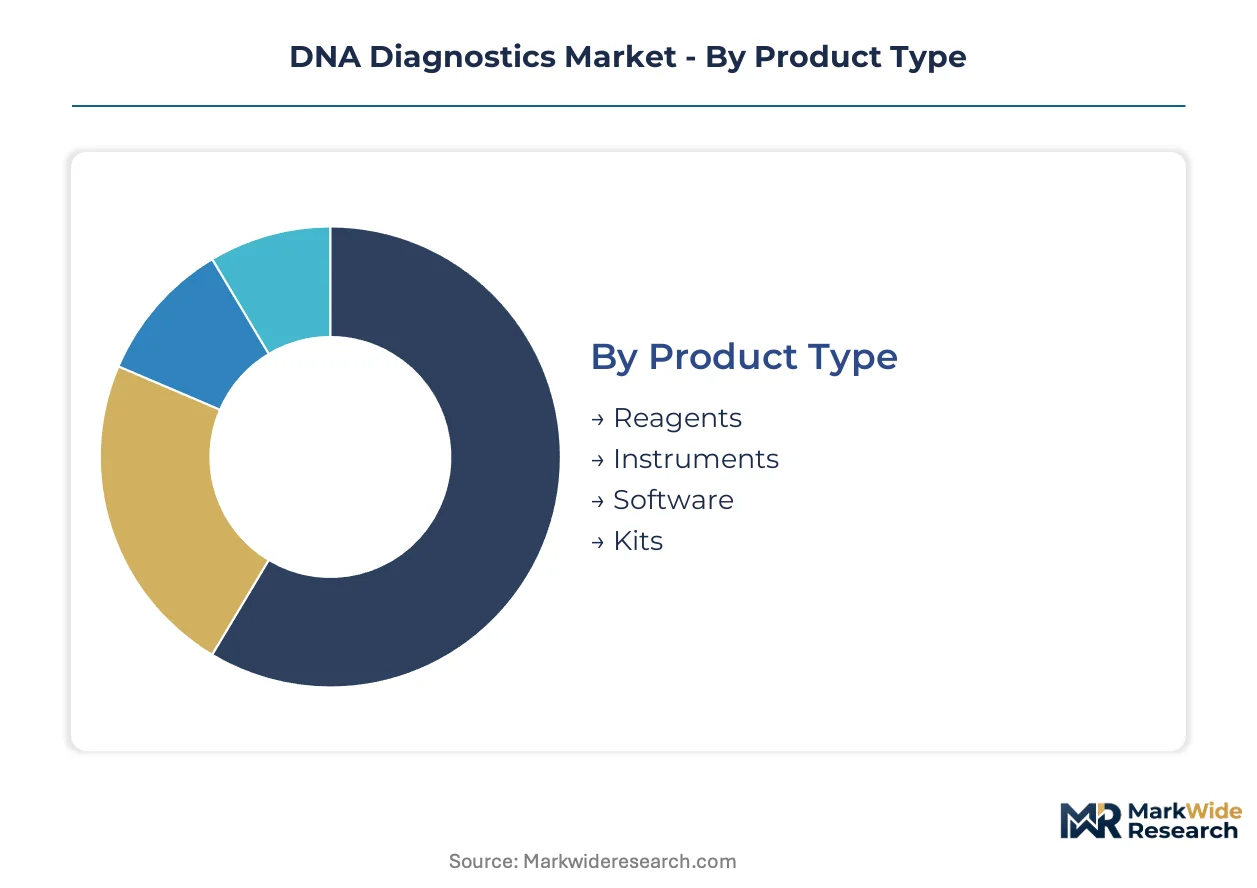
Molecular diagnostics vendors structure product portfolios around four intersecting dimensions that determine pricing power and customer stickiness. Technology-platform choices lock laboratories into consumable ecosystems, while application-specific regulatory pathways create divergent margin profiles across oncology and infectious disease segments.
Product Type:
Reagent suppliers face accelerating substitution pressure from open-platform chemistries and third-party consumables that erode proprietary lock-in strategies.
- Reagents:Enzyme formulations, nucleotides, and master mixes constitute the recurring revenue foundation for platform vendors. Hospital laboratory consolidations in the United States and Germany are forcing reagent pricing concessions through enterprise procurement contracts.
- Instruments:Sequencing and PCR hardware placements generate upfront capital expenditure concentrated in academic medical centers and reference laboratories. Illumina and Thermo Fisher defend installed bases through service bundling and trade-in programs rather than hardware differentiation alone.
- Software:Bioinformatics pipelines for variant calling and clinical interpretation command subscription pricing tied to test volume tiers. FDA scrutiny of algorithm-based diagnostic outputs is extending validation timelines for new entrants.
- Kits:Pre-configured assay panels reduce laboratory workflow complexity for targeted gene profiling. CE-IVD marked kits dominate European clinical adoption due to EMA's stricter post-market surveillance requirements under MDR.
Reagents retain volume leadership; instruments hold the steepest expansion curve as laboratories upgrade to next-generation platforms.
Application:
Oncology commands per-test value premiums that exceed infectious disease screening by an order of magnitude, reshaping vendor R&D allocation toward companion diagnostic development.
- Oncology:Solid tumor molecular profiling and liquid biopsy applications drive the highest reimbursement rates. FDA co-approval mandates for targeted therapies embed diagnostic testing into standard-of-care protocols across lung, breast, and colorectal cancer categories.
- Infectious Diseases:Respiratory panels, sepsis detection, and antimicrobial resistance surveillance sustain high test volumes with compressed margins. Public health agencies in the United Kingdom and South Korea maintain platform investments for pathogen surveillance infrastructure.
- Genetic Testing:Hereditary risk screening and carrier detection serve reproductive health and preventive medicine applications. Direct-to-consumer regulatory frameworks in the United States are expanding channel access beyond traditional clinical ordering.
- Forensics:DNA profiling for criminal casework and disaster victim identification operates through government contract procurement. CODIS database expansion and rapid DNA legislation drive instrument placements in federal and state laboratories.
Infectious diseases anchor test volume; oncology claims the most rapid reimbursement expansion.
Technology:
Sequencing chemistry bifurcation into high-throughput and rapid-turnaround systems is compressing the mid-range instrument market and forcing vendor specialization.
- Sequencing:Next-generation platforms fragment into population-scale systems and point-of-care instruments for acute care decision-making. Nanopore technologies penetrate emergency departments in Australia and Singapore for same-day pathogen identification.
- PCR:Quantitative and digital PCR retain dominance in infectious disease surveillance due to regulatory familiarity and turnaround speed. Cepheid and Bio-Rad compete through cartridge-based portability for near-patient testing.
- Microarray:Comparative genomic hybridization and SNP arrays serve cytogenetic and pharmacogenomic applications with established reimbursement codes. Declining per-sample costs pressure this segment against sequencing substitution.
- CRISPR:Gene editing biochemistry converges with portable detection hardware for point-of-care nucleic acid testing. Sherlock Biosciences and Mammoth Biosciences advance FDA-cleared platforms for decentralized diagnostics.
PCR sustains installed base dominance; CRISPR-based platforms are climbing the fastest toward clinical validation milestones.
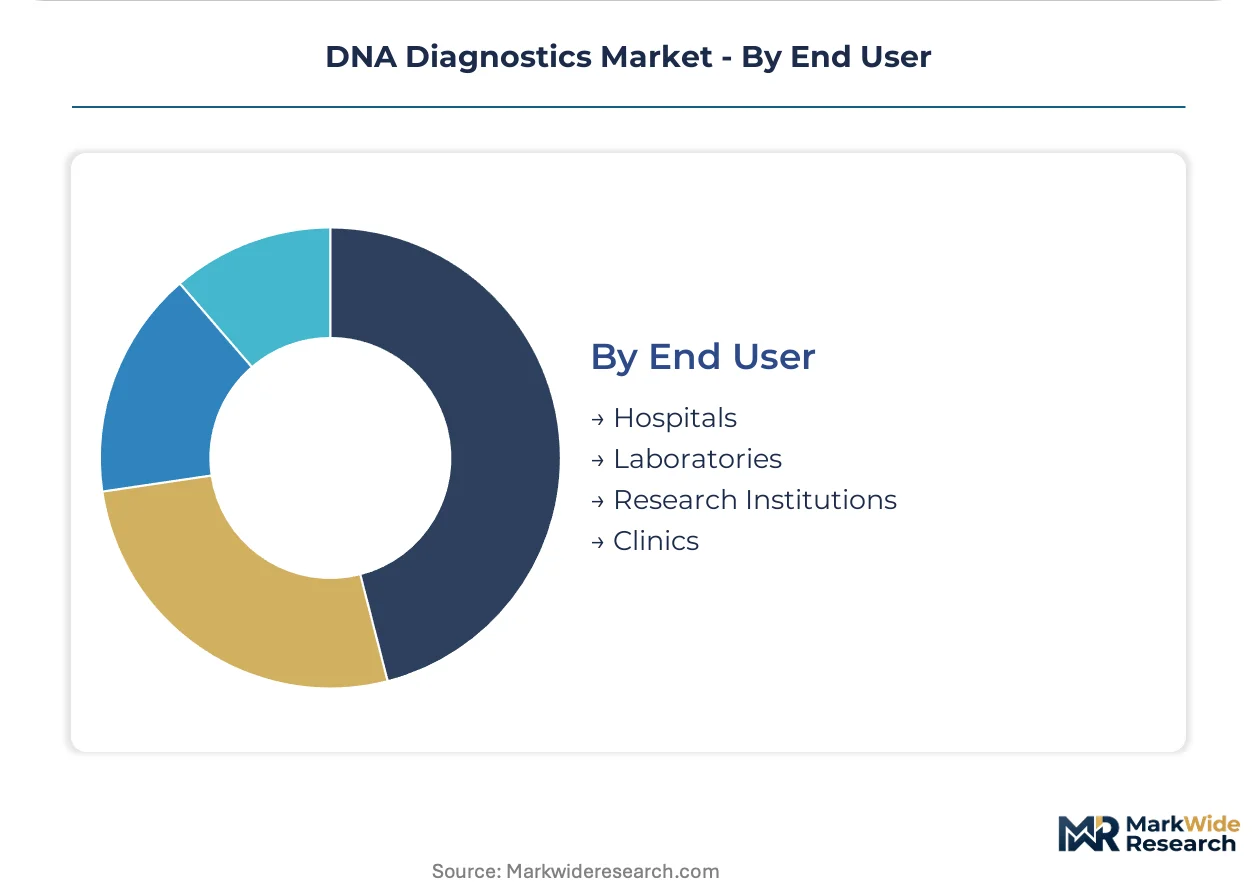
End User:
Hospital system consolidation into integrated delivery networks is compressing vendor relationships around multi-site enterprise contracts.
- Hospitals:In-house molecular pathology laboratories perform oncology profiling and infectious disease testing for admitted patients. CFO oversight of supply chain spend is overriding individual pathologist instrument preferences in multi-state health systems.
- Laboratories:Reference and commercial laboratories process high-throughput sequencing for health system outsourcing contracts. Quest Diagnostics and LabCorp negotiate national pricing agreements with payers for multi-gene panel coverage.
- Research Institutions:Academic medical centers concentrate bioinformatics expertise and clinical molecular genetics training. NIH funding priorities shape technology adoption patterns for translational research applications.
- Clinics:Physician office laboratories and urgent care settings adopt cartridge-based PCR for rapid infectious disease diagnosis. CLIA-waived test expansion depends on FDA simplification of quality control requirements.
Laboratories process the highest test volumes; clinics are gaining share fastest through point-of-care platform miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Diego-Tijuana biotechnology corridor anchors North American sequencing infrastructure, while Rotterdam's port logistics enable European reagent distribution networks. These physical assets concentrate procurement authority and shape vendor access strategies across their respective markets.
United States
FDA co-approval mandates for oncology companion diagnostics drive molecular profiling volumes in academic medical centers. The agency's laboratory-developed test oversight extends validation timelines for multi-gene panels. Boston's Longwood Medical Area concentrates bioinformatics expertise and clinical molecular genetics training programs.
Germany
EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards than predecessor directives, extending certification timelines for European market access. Germany's diagnostic reagent manufacturing clusters in Munich and Heidelberg face expanded quality management system audits. The country's hospital consolidation into integrated delivery networks compresses vendor relationships around enterprise procurement contracts.
China
NMPA regulatory pathways for gene sequencing instruments accelerate domestic platform approvals while maintaining import restrictions on foreign systems. Shenzhen's precision medicine industrial park hosts CRISPR-based diagnostic developers targeting point-of-care applications. The Yangtze River Delta concentrates reference laboratory capacity for health system outsourcing contracts.
United Kingdom
NHS England's genomic medicine service embeds molecular testing into standard-of-care protocols across cancer and rare disease categories. The Medicines and Healthcare products Regulatory Agency aligns post-market surveillance with EMA's MDR requirements. London's Genomics England headquarters coordinates national sequencing infrastructure and data sharing frameworks.
Japan
PMDA's companion diagnostic guidance documents shape co-development timelines for targeted oncology therapies. Japan's super-aging demographic concentrates demand for pharmacogenomic applications in cardiovascular and psychiatric medication management. The Kobe biomedical innovation cluster hosts automated nucleic acid extraction system manufacturers serving Asia-Pacific reference laboratories.
DNA Diagnostics Market Vendor Landscape
Listed leaders compete with private specialists across instrument placement and reagent supply dimensions, producing a tiered structure where scale advantages concentrate in sequencing hardware while niche biochemistries sustain specialist margins. Strategic archetypes include platform vendors defending installed bases through captive consumable ecosystems, integrated workflow providers spanning sample prep to data analysis, and automated extraction specialists leveraging diagnostics architecture for pricing power. Dominant competitive moves encompass multi-site enterprise contract restructuring around health system consolidation and regulatory front-loading for EMA's MDR transition.
Within the platform vendor tier, Illumina Inc. and Thermo Fisher Scientific Inc. exemplify contrasting approaches to sequencing market positioning. Danaher Corporation occupies a distinct position in automated sample preparation, anchoring a workflow specialization that resists direct platform competition. These three entities collectively represent the spectrum from pure-play sequencing to diversified life sciences conglomerates, with each archetype demanding different procurement negotiation strategies from consolidated hospital systems.
| Leading Market Players |
|---|
| Illumina Inc. |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| QIAGEN |
| Bio-Rad Laboratories Inc. |
| Agilent Technologies Inc. |
| Siemens Healthineers AG |
| Others |
Supply Flow & Price Mechanics
Instrument placement density in the United States and Germany creates scale economies that compress per-test reagent costs while elevating price floors for specialized biochemistries. This concentration of sequencing infrastructure shapes both vendor pricing power and laboratory procurement leverage across enterprise contract negotiations.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement contracts between consolidated hospital systems and platform vendors. Three-tier pricing stratifies across premium companion diagnostic assays, standard infectious disease panels, and economy-grade research-use-only reagents. Price differentiation hinges on FDA co-approval status and health system purchasing volume. Cost compression in the mid-range instrument segment is intensifying because open-platform chemistry alternatives erode proprietary consumable margins. Community hospital laboratories exhibit the highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore ports affect European and Asia-Pacific reagent distribution economics, particularly for temperature-sensitive enzyme formulations. Manufacturing concentration in the United States, Germany, and China anchors global supply for sequencing instruments and PCR platforms. Raw material dependencies include semiconductor components for detection hardware, purified enzymes for amplification chemistries, and synthetic oligonucleotides for probe manufacturing. Single-source vulnerability in semiconductor supply creates bottleneck risk for instrument production cycles. Distribution runs through authorized distributor networks serving consolidated health system procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated hospital systems and integrated delivery networks, compressing vendor margins through multi-site enterprise contracts that displace decentralized laboratory purchasing.
For Market Incumbents: Shield installed base economics by deepening captive reagent ecosystems and accelerating service bundling around sequencing platforms. Threat substitution from CRISPR-based point-of-care diagnostics demands preemptive investment in rapid-turnaround instrument tiers. Prioritize backward integration into critical enzyme manufacturing to defend consumable margins against open-platform erosion. For New Entrants and Emerging Players: Lead with pharmacogenomic applications in psychiatry and cardiovascular medication management, segments where companion diagnostic mandates remain underdeveloped relative to oncology. The most penetrable white space sits in CLIA-waived point-of-care platforms for urgent care settings. Pursue regulatory front-loading for FDA emergency use authorization pathways to accelerate channel access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated nucleic acid extraction specialists with diagnostics platform architecture. Long-term viability over the next decade favors vendors with demonstrated reimbursement strategy execution and health system GPO contract penetration. Acquisition targets should demonstrate EU MDR certification progress and Medicare coverage determination traction. Watch liquid biopsy reimbursement decisions as the critical inflection signal for molecular profiling expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enterprise Contract Restructuring | Multi-site health system procurement consolidation demands pricing concessions and standardized platform commitments. |
| Regulatory Front-Loading | EMA MDR clinical evidence requirements extend certification timelines and inflate compliance expenditures for European access. |
| Reagent Ecosystem Defense | Proprietary consumable lock-in strategies protect margins against open-platform chemistry substitution pressure. |
| Liquid Biopsy Reimbursement Strategy | Medicare coverage determination processes shape commercial payer adoption for circulating tumor DNA applications. |
| Point-of-Care Platform Miniaturization | Cartridge-based PCR and CRISPR diagnostics penetrate urgent care settings beyond centralized laboratory infrastructure. |
Methodological Framework
A standing panel of molecular pathology laboratory directors, hospital procurement executives, diagnostic platform engineers, and payer policy specialists provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, CMS Medicare coverage determinations, and hospital GPO contract repositories. Bottom-up test volume modeling and top-down market sizing triangulated across independent analytical approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by technology platform, application area, end-user category, and regional regulatory cluster. CAGRs were derived from instrument placement trajectories, consumable pull-through rates, and reimbursement expansion patterns. Industry-specific forecast inputs included companion diagnostic co-approval timelines and health system consolidation velocity.
Forecasts assume regulatory continuity in FDA laboratory-developed test oversight and EMA MDR implementation; material policy shifts would require re-modeling. Specific risk factors include payer coverage reversals for multi-gene panels and semiconductor supply disruptions affecting instrument manufacturing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Metagenomic Sequencing Market
Genomics
Microarray Biochips Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Global Genotyping Assay Market
Genomics
Pharmacogenomics Technology Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Immunogenetics Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Global Long Read Sequencing Market
Genomics
Next Generation Sequencing Market