
 Digital Genome Market | 2026-2036
Digital Genome Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Genome Market Analysis
Pharmaceutical companies is redrawing demand patterns in the digital genome space, overtaking research institutions as the primary spenders on sequencing services and AI analytics. Illumina leverages its installed base of sequencing instruments to sustain recurring revenue from consumables and software subscriptions. Thermo Fisher Scientific anchors its position through integrated workflows spanning sample preparation to cloud data management. BGI Genomics competes on manufacturing scale, offering high-throughput sequencing services at cost points that pressure Western peers.
Digital genome refers to the complete digital representation of an organism's genetic material, encoded as nucleotide sequence data generated through next-generation sequencing platforms producing reads from 50 to 300 base pairs, stored and analyzed via bioinformatics pipelines for therapeutic target identification and clinical decision support. Sequencing technology leads in revenue contribution due to instrument placement and reagent pull-through, while AI Analytics represents the fastest-expanding margin pool as pharmaceutical buyers prioritize predictive variant interpretation. Cloud Computing infrastructure supports real-time collaboration across distributed research networks, reducing latency in multi-site drug development programs.
FDA oversight of laboratory-developed tests and EMA's In Vitro Diagnostic Regulation shape product validation requirements and market access timelines for diagnostic applications. HIPAA compliance obligations and GDPR data-localization rules constrain cross-border genomic data flows, forcing vendors to architect region-specific cloud deployments. Stakeholders must weigh regulatory fragmentation against the efficiency gains of unified global bioinformatics platforms when allocating infrastructure investment.
Market Dynamics
Pharmaceutical buyers now drive sequencing volume, forcing vendors to re-architect service models around FDA validation requirements and predictive analytics integration rather than raw throughput metrics.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Harmonized validation standards accelerate diagnostic kit approvals across European member states, compressing time-to-market for companion diagnostics.
- Cloud bioinformatics:Distributed research networks now access shared variant databases in real time, eliminating data silos that previously stalled multi-site oncology trials.
- Boston-Cambridge biotech corridor:Dense clustering of CRISPR therapeutics developers generates concentrated demand for high-throughput functional genomics services.
Market Restraints
- Consumables cost structure:Proprietary sequencing reagents lock buyers into single-vendor ecosystems, inflating per-run costs beyond academic budget tolerances.
- HIPAA-GDPR friction:Conflicting data-localization mandates force redundant infrastructure deployment, raising operational overhead for cross-border clinical studies.
- Optical mapping substitution:Long-read platforms bypass short-read assembly limitations for structural variant detection, threatening installed-base stickiness of legacy instruments.
Strategic Opportunities
- Liquid biopsy integration:Cell-free DNA analysis pipelines open recurring revenue streams in cancer monitoring, displacing invasive tissue biopsies for treatment response tracking.
- India's PLI scheme:Domestic manufacturing incentives attract sequencing instrument assembly, creating regional supply hubs to serve South Asian research institutions.
- AI-CRISPR convergence:Machine learning guides guide-RNA design, compressing experimental cycles for functional screening applications in agricultural biotechnology.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation specialists command premium compensation, constraining scale-up of clinical reporting operations.
- ISO 15189 accreditation timelines:Laboratory certification for clinical-grade sequencing extends 18-24 months, delaying revenue recognition for diagnostic service launches.
- LIMS integration complexity:Legacy sample tracking systems resist API connectivity with cloud analytics platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Genome Market |
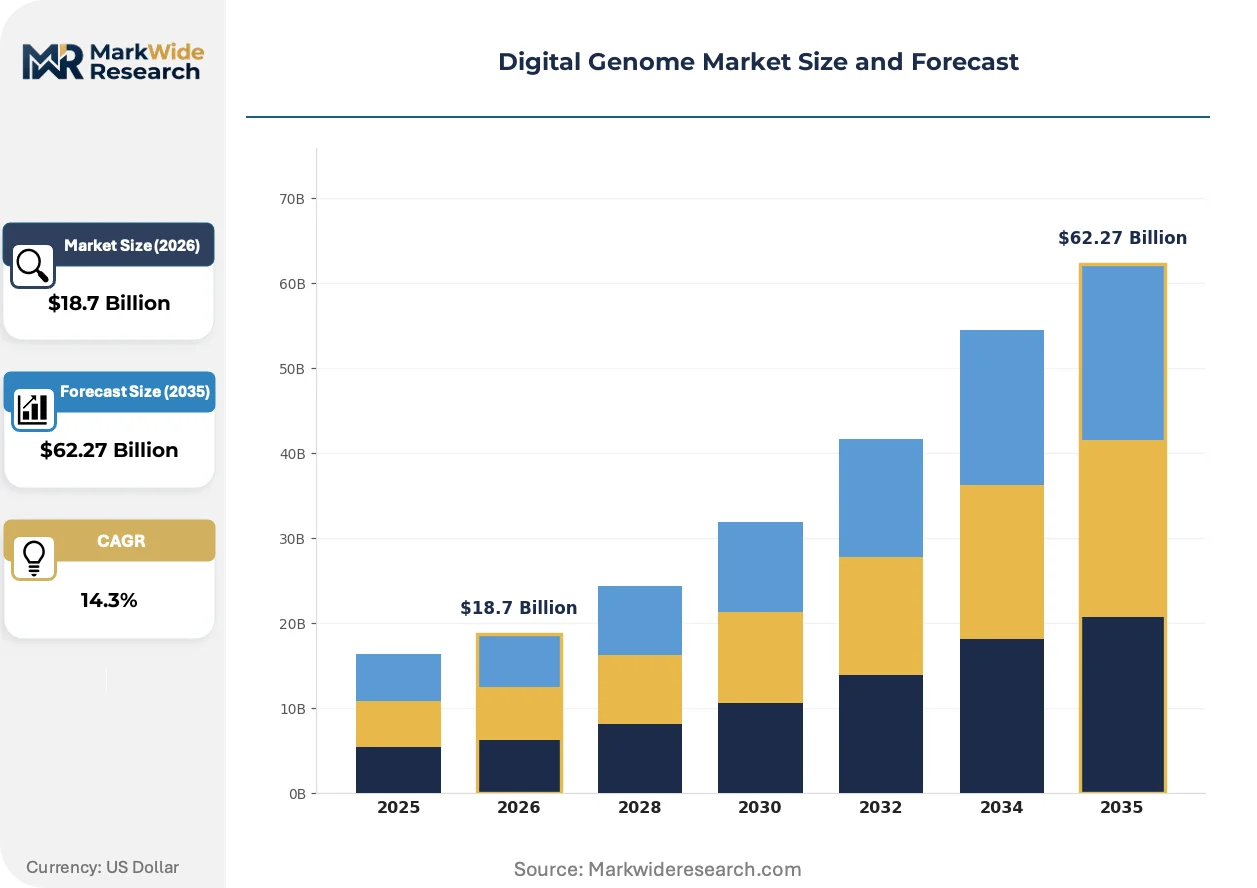
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Drug Development, Personalized Medicine, Gene Therapy, Diagnostics Technology: Sequencing, Bioinformatics, Cloud Computing, AI Analytics End User: Research Institutions, Pharmaceutical Companies, Hospitals, Biotechnology Firms Service Type: Consulting, Data Analysis, Sequencing Services, Software Solutions |
| Companies Covered | Illumina, Thermo Fisher Scientific, Agilent Technologies, Roche, BGI Genomics, Qiagen, Pacific Biosciences, Oxford Nanopore Technologies, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Genome Market Emerging Trajectories
Next-generation platforms now compete on analytical software depth rather than raw read length, embedding AI directly at the instrument edge to reduce data transfer burdens.
Portable nanopore sequencers are displacing centralized core facility models for point-of-need pathogen surveillance. Field epidemiology teams in outbreak response units adopt palm-sized devices for same-day genomic characterization. This decentralization is compressing the traditional sample-to-insight cycle from weeks to hours in infectious disease monitoring.
FDA's guidance on artificial intelligence in medical devices imposes predetermined change control plans on adaptive algorithms. Machine learning models for variant classification must document locked training parameters before clinical deployment. Diagnostic developers in the United States now front-load validation costs to secure premarket authorization for AI-augmented reporting tools.
Consolidated purchasing by health system networks concentrates sequencing procurement decisions within centralized value analysis committees. Academic medical centers negotiate enterprise licenses spanning multiple hospital affiliates, displacing the prior model of individual laboratory reagent contracts. This shift is most visible in the United States, where integrated delivery networks now account for the majority of clinical exome sequencing volume.
Digital Genome Market Segmentation
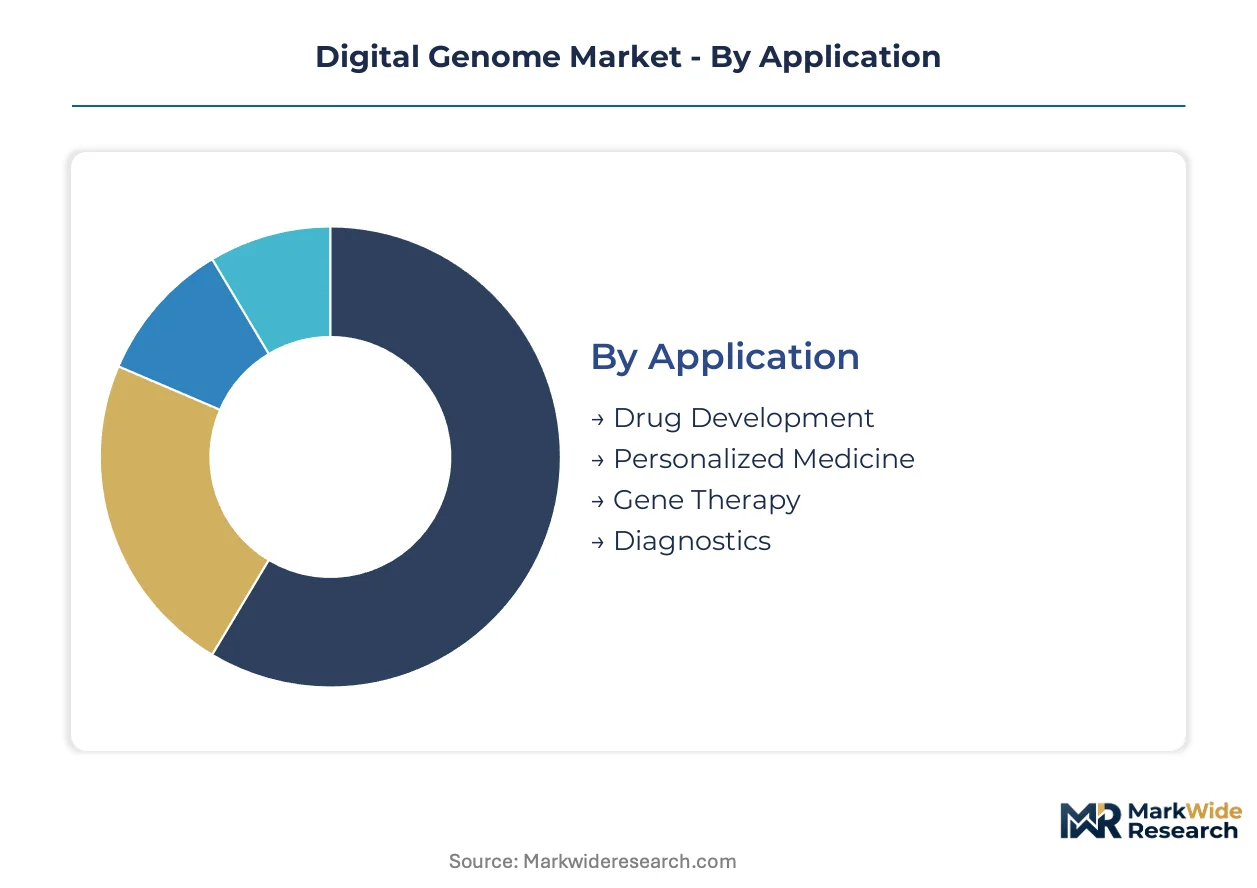
Segmentation in the digital genome market reveals how regulatory pathways and procurement authority concentrate value in distinct technology-application combinations. Pharmaceutical buyers prioritize validated workflows for FDA submissions, while research institutions optimize for cost per base pair in exploratory studies.
Application:
FDA premarket authorization requirements and EMA companion diagnostic pathways create divergent investment timelines across therapeutic areas.
- Drug Development:Genomic target identification and patient stratification protocols now embed directly into Phase I-III trial designs. Pharmaceutical sponsors in the United States and Germany commission whole-exome sequencing to support IND filings and biomarker qualification packages.
- Personalized Medicine:Pharmacogenomic testing guides dosing algorithms for oncology and cardiovascular therapeutics. Health system networks in Massachusetts and Bavaria deploy clinical decision support tools integrating variant interpretation with electronic health records.
- Gene Therapy:Viral vector characterization and off-target analysis for CRISPR-based interventions.
- Diagnostics:Hereditary disease panels and infectious pathogen identification for hospital laboratories.
Drug Development handles the majority of throughput; Personalized Medicine is gaining share fastest as reimbursement codes solidify for pharmacogenomic testing.
Technology:
Cost per gigabase and computational latency separate deployment tiers across customer segments.
- Sequencing:Short-read platforms dominate instrument placements with consumable pull-through models. Illumina's installed base in the United States and China's sequencing centers sustains recurring reagent revenue for high-throughput production environments.
- AI Analytics:Machine learning models for variant classification reduce manual curation burdens in clinical reporting. FDA predetermined change control plans now govern adaptive algorithm deployments, front-loading validation costs for diagnostic developers.
- Bioinformatics:Pipeline orchestration and variant annotation for research-grade analysis.
- Cloud Computing:Distributed storage and compute for multi-site collaboration.
Sequencing commands the largest revenue footprint; AI Analytics expands most quickly as pharmaceutical procurement shifts toward predictive interpretation tools.
End User:
Budget authority and validation requirements segment procurement behavior across institutional types.
- Pharmaceutical Companies:Enterprise-scale sequencing contracts with integrated bioinformatics support for regulatory submission packages. FDA and EMA validation standards drive vendor selection toward ISO 13485-certified service providers.
- Research Institutions:Grant-funded exploratory sequencing with cost-sensitive reagent sourcing. Academic core facilities in the Boston-Cambridge corridor negotiate volume discounts for population-scale genomics initiatives.
- Hospitals:Clinical laboratory integration for diagnostic test menus and patient care workflows.
- Biotechnology Firms:Outsourced sequencing and data analysis for preclinical pipeline advancement.
Pharmaceutical Companies concentrate the highest per-customer spending; Biotechnology Firms show the steepest expansion trajectory as venture-funded startups scale sequencing operations.
Service Type:
Margin structure and customer stickiness vary with technical complexity and regulatory exposure.
- Sequencing Services:High-throughput production with instrument utilization optimization. BGI Genomics and European service providers compete on turnaround time and per-sample pricing for pharmaceutical contract research.
- Software Solutions:Subscription-based variant interpretation platforms with API integration for laboratory information systems. HIPAA and GDPR compliance requirements force region-specific deployment architectures.
- Data Analysis:Custom bioinformatics pipelines and statistical genetics support for publication-grade outputs.
- Consulting:Regulatory strategy and experimental design advisory for genomic data submission packages.
Sequencing Services generates the highest absolute revenue; Software Solutions climbs fastest on recurring subscription models and regulatory compliance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor's dense fiber optic and cloud infrastructure underwrites North America's dominance in genomic data throughput, while submarine cable landing stations in Singapore and Mumbai enable real-time bioinformatics collaboration across Asian research networks.
United States
FDA premarket authorization pathways and NIH precision medicine initiatives drive pharmaceutical sequencing contracts. HIPAA compliance mandates shape cloud deployment architectures for cross-border data flows. The Boston-Cambridge corridor concentrates CRISPR therapeutics developers generating sustained demand for functional genomics services.
Germany
EMA companion diagnostic harmonization accelerates diagnostic kit approvals across member states. The country's national pharmaceutical regulator enforces ISO 15189 laboratory certification extending 18-24 months for clinical-grade sequencing. The Munich biotech cluster anchors pharmaceutical R&D spending on whole-exome sequencing for IND filings.
China
NMPA oversight of gene sequencing instruments and reagents shapes domestic manufacturing scale. The country's dual carbon goals pressure energy-intensive data center operations for genomic cloud storage. The Yangtze River Delta sequencing centers compete on per-sample pricing for high-throughput production environments.
United Kingdom
NHS Genomic Medicine Service procurement centralizes sequencing decisions within integrated care systems. GDPR data-localization rules constrain cross-border genomic data flows to European research partners. The Cambridge life sciences cluster concentrates nanopore sequencing adoption for point-of-need pathogen surveillance.
India
PLI scheme domestic manufacturing incentives attract sequencing instrument assembly for regional supply hubs. CDSCO medical device regulations govern diagnostic kit import and local production timelines. The Bangalore-Hyderabad biotech corridor scales sequencing operations for agricultural biotechnology and pharmaceutical contract research.
Digital Genome Market Vendor Landscape
Listed leaders compete with private specialists across instrument placement and cloud bioinformatics subscription models. The vendor base stratifies between integrated workflow providers and point-solution specialists. Three archetypes dominate: sequencing platform incumbents with consumable pull-through, AI analytics pure-plays with regulatory compliance bundling, and contract research service providers with manufacturing scale. Consolidation concentrates around strategic partnerships for FDA validation packages and geographic expansion into PLI-subsidized manufacturing zones.
Within the integrated workflow tier, Illumina and Thermo Fisher Scientific exemplify platform-centric business models sustaining recurring revenue through instrument-installed bases and reagent lock-in. BGI Genomics occupies a position representing manufacturing-scale service competition pressuring Western peers on per-run cost structures. These three anchors span the competitive spectrum from premium instrument ecosystems to cost-optimized production sequencing, with each archetype targeting distinct procurement authority segments across pharmaceutical enterprise contracts and academic core facility budgets.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Roche |
| BGI Genomics |
| Qiagen |
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Long-term consumable supply contracts lock pharmaceutical buyers into predictable per-run pricing while securing reagent access from Illumina's manufacturing footprint in the United States. These arrangements stabilize budget forecasting for high-throughput sequencing operations but limit vendor-switching flexibility as ISO 13485-certified alternatives remain scarce.
Pricing Analysis
Volume-discount tiering separates enterprise pharmaceutical contracts from academic core facility purchasing, with the former commanding 40-60% price breaks on reagent bundles above ten thousand annual runs. Pricing stratifies across premium (FDA-validated workflows), standard (research-grade reagents), and economy (BGI Genomics outsourced production) tiers. Cost compression in the economy tier intensifies because Chinese manufacturing scale undercuts Western consumable pricing. Academic buyers exhibit highest price sensitivity; pharmaceutical sponsors prioritize validation documentation over per-base cost.
Supply Chain Analysis
Semiconductor-grade silicon wafer fabrication in Taiwan and South Korea underwrites flow-cell production for next-generation sequencing instruments. Supply draws from specialized polymer chemistry feedstocks in Germany, rare-earth magnet components for optical systems in China, and precision optics manufacturing in Japan. Single-source vulnerability concentrates in Taiwanese foundry capacity for CMOS image sensors. Distribution runs through direct field service organizations for instrument placements and third-party logistics for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variant interpretation expertise now constrains clinical reporting scale-up, with bioinformatics specialists commanding compensation premiums that compress service margins. This talent scarcity rewards vendors who automate interpretation pipelines or captive training programs.
For Market Incumbents: Compound installed-base stickiness through backward integration into cloud analytics platforms, capturing recurring software subscription revenue that offsets consumable pricing pressure. Prioritize ISO 15189 accreditation investments for diagnostic service expansions before long-read substitution platforms erode short-read structural variant detection advantages.
For New Entrants and Emerging Players: CDSCO fast-track pathways for sequencing instrument assembly under India's PLI scheme offer regulatory arbitrage against FDA premarket authorization timelines. White-space concentrates in agricultural biotechnology AI-CRISPR convergence and liquid biopsy monitoring services for community oncology practices. Go-to-market should anchor in Bangalore-Hyderabad contract research partnerships.
For Investors and Strategic Acquirers: AI analytics pure-plays with predetermined change control plans locked for FDA submission represent asymmetric upside as diagnostic developers front-load validation costs. Long-term viability hinges on regulatory compliance bundling rather than raw sequencing throughput. Watch for NMPA domestic manufacturing mandates shifting production gravity toward Yangtze River Delta assembly hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan | Locks adaptive algorithm parameters before clinical deployment, front-loading validation investment for AI-augmented diagnostic tools. |
| ISO 15189 Laboratory Accreditation | Extends certification timelines 18-24 months, delaying revenue recognition for clinical-grade sequencing service launches. |
| Cloud Bioinformatics Platform Integration | Eliminates data silos across distributed research networks, reducing latency in multi-site pharmaceutical trial programs. |
| Liquid Biopsy Pipeline Development | Opens recurring revenue streams in cancer monitoring, displacing invasive tissue biopsies for treatment response tracking. |
| PLI Scheme Manufacturing Localization | Attracts sequencing instrument assembly to India, creating regional supply hubs serving South Asian research institutions. |
Methodological Framework
Desk research of FDA premarket authorization databases, EMA companion diagnostic submissions, and NIH precision medicine initiative disclosures preceded structured interviews with pharmaceutical drug development executives, clinical laboratory directors, bioinformatics platform engineers, and health system procurement managers. Primary intelligence combined with secondary validation from ISO certification registries, cloud infrastructure capex disclosures, and customs trade data for sequencing instrument imports. Bottom-up service provider revenue estimates triangulated against top-down pharmaceutical R&D spending allocations.
Variance-decomposition across technology segments, application workflows, and end-user procurement tiers structured the analytical framework over the projection horizon. Modeled dimensions span sequencing platform generation, AI analytics deployment architecture, validation tier (research-grade through FDA-cleared), and regional regulatory cluster. CAGRs derived from instrument placement trajectories, consumable pull-through rates, and software subscription renewal patterns. Industry-specific inputs include CRISPR therapeutic pipeline advancement and pharmacogenomic reimbursement code expansion.
Decision-makers should treat outputs as directional under assumptions of sustained FDA-EMA regulatory harmonization and cloud infrastructure cost decline; material deviation would warrant model refresh. Revision becomes warranted when HIPAA-GDPR data-localization friction triggers redundant infrastructure deployment exceeding threshold cost burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
North America DNA Sequencing Products Market
Genomics
Genomics Personalized Health Market
Genomics
Next Generation Molecular Assay Market
Genomics
Alagille Syndrome Market
Genomics
Genetic Material Market
Genomics
Next Generation Sequencing Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
UAE Genetic Testing Market
Genomics
Hereditary Testing Market
Genomics
Restriction Endonucleases Market
Genomics
Next Generation Genomics Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Global Pharmacogenomics Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Spatial Genomics and Transcriptomics Market