
 Global Microarray Analysis Market | 2026-2036
Global Microarray Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microarray Analysis Market Foresight
The EU Green Deal's push for sustainable laboratory practices is hardening procurement criteria across European academic research centers and molecular diagnostic labs. Illumina, Inc. anchors the high-density sequencing-integrated microarray segment with sustained R&D investment in label-free detection architectures. QIAGEN N.V. leverages its sample-to-insight workflow dominance to compete in genomic profiling applications, while Thermo Fisher Scientific Inc. extends its channel control across pharmaceutical developer accounts in North America and Asia-Pacific.
Microarray analysis refers to a high-throughput molecular biology technique that enables simultaneous interrogation of thousands of biomolecules—typically DNA, RNA, proteins, or peptides—immobilized on a solid substrate at defined spatial coordinates, with detection sensitivity reaching femtomolar concentrations through fluorescence or chemiluminescence readout systems. DNA microarrays retain the largest installed base among product types due to mature genomic profiling protocols, though label-free detection technologies are capturing margin pools in drug discovery settings where real-time kinetic binding data eliminates fluorescent label artifacts. Peptide microarrays occupy a specialized niche in biomarker identification workflows, particularly within European biotechnology firms seeking reduced assay complexity.
The FDA governs microarray-based diagnostic devices through its in vitro diagnostic framework, while the EMA's In Vitro Diagnostic Regulation mandates enhanced clinical evidence for molecular diagnostic labs deploying these platforms in patient care. ISO 13485 certification shapes supplier qualification processes for pharmaceutical developers, creating compliance barriers for uncertified component vendors. Stakeholders must monitor evolving harmonization between FDA and EMA post-market surveillance requirements to anticipate retooling costs for dual-market product strategies.
Market Dynamics
Label-free detection architectures are compressing the addressable market for fluorescence-based microarray systems as pharmaceutical developers prioritize real-time kinetic binding data over endpoint measurements. This technical displacement is forcing incumbent platform vendors to retool detection modules while academic centers delay replacement cycles.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:The EMA's enhanced clinical evidence mandates for molecular diagnostic labs are accelerating validation protocols for high-density genomic profiling platforms.
- Pharmaceutical developer workflows:Drug discovery teams in North America and Asia-Pacific are integrating microarray data with AI-driven target identification pipelines.
- Peptide microarray specialization:European biotechnology firms are adopting reduced-complexity biomarker identification assays for immunogenicity screening.
Market Restraints
- Fluorophore supply concentration:Specialty dye chemistries for chemiluminescence readout systems face input cost volatility from concentrated Asian chemical suppliers.
- ISO 13485 certification barriers:Uncertified component vendors in developing markets are structurally excluded from pharmaceutical developer procurement pools.
- Next-generation sequencing substitution:Clinical diagnostic labs are redirecting genomic profiling budgets toward sequencing platforms for variant detection.
Strategic Opportunities
- EU Green Deal laboratory mandates:Sustainable procurement criteria are creating first-mover advantage for vendors with energy-efficient thermal cycling modules.
- Sample-to-insight workflow convergence:Integration of automated nucleic acid extraction with microarray hybridization is opening pharmaceutical CRO accounts.
- India pharmaceutical R&D expansion:CDSCO-registered contract research organizations are building captive microarray capabilities for bioequivalence studies.
Industry Challenges
- Bioinformatics pipeline integration:Diagnostic labs struggle to harmonize legacy LIMS infrastructure with cloud-based variant interpretation platforms.
- Dual-market certification timelines:Synchronized FDA and EMA post-market surveillance requirements are extending product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microarray Analysis Market |
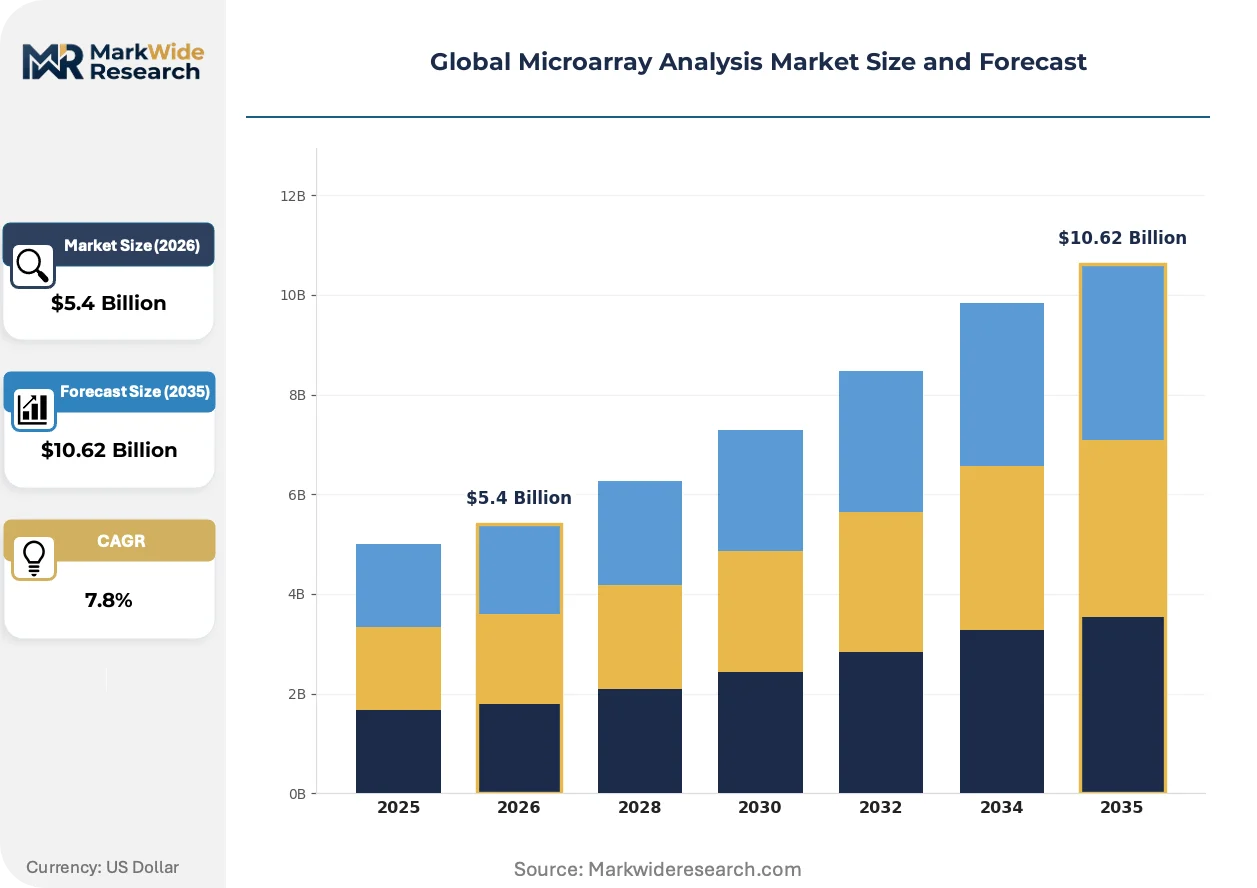
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarrays, Protein Microarrays, Tissue Microarrays, Carbohydrate Microarrays, Peptide Microarrays Technology: Two-Color, One-Color, High-Density, Low-Density, Label-Free Detection Application: Genomic Profiling, Gene Expression Analysis, Drug Discovery, Biomarker Identification, Epigenetics End User: Biotechnology Firms, Pharmaceutical Developers, Academic Research Centers, Molecular Diagnostic Labs |
| Companies Covered | F. Hoffmann-La Roche AG, QIAGEN N.V., Illumina, Inc., Luminex Corporation, PerkinElmer, Inc., Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Danaher Corporation, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microarray Analysis Market Shifts & Advancements
Detection modality preferences are fragmenting across end-use segments as real-time binding measurement displaces endpoint fluorescence in drug discovery settings. Platform vendors are responding with modular architectures that accommodate multiple readout chemistries within shared fluidic infrastructure.
Surface plasmon resonance microarrays are overtaking traditional fluorescence-based systems in lead optimization workflows. Large-molecule therapeutic developers in Germany and the United States are deploying these platforms for affinity ranking at throughput rates exceeding 10,000 interactions per run. The shift is compressing demand for labeled secondary antibodies while expanding service revenue from kinetic parameter databases.
REACH chemical registration requirements are reshaping substrate manufacturing economics across European supply chains. Microarray slide coating vendors are reformulating silane chemistries to eliminate SVHC-classified crosslinkers ahead of authorization deadlines. German and Swiss component suppliers are absorbing retooling costs while Asian competitors face extended market access timelines.
Academic procurement committees are unbundling capital equipment from reagent supply contracts. Research centers in Japan and the United Kingdom are negotiating separate vendor relationships for high-density chips versus detection instrumentation. The decoupling is most visible in National Institutes of Health-funded consortia where equipment refresh cycles now lag consumable conversion by 24-36 months.
Global Microarray Analysis Market Segmentation
Platform heterogeneity across the Global Microarray Analysis Market demands granular segmentation mapping. Procurement patterns diverge sharply between academic centers optimizing for throughput density and pharmaceutical developers prioritizing kinetic binding fidelity.
Product Type:
Substrate chemistry concentration determines margin distribution across consumable supply chains.
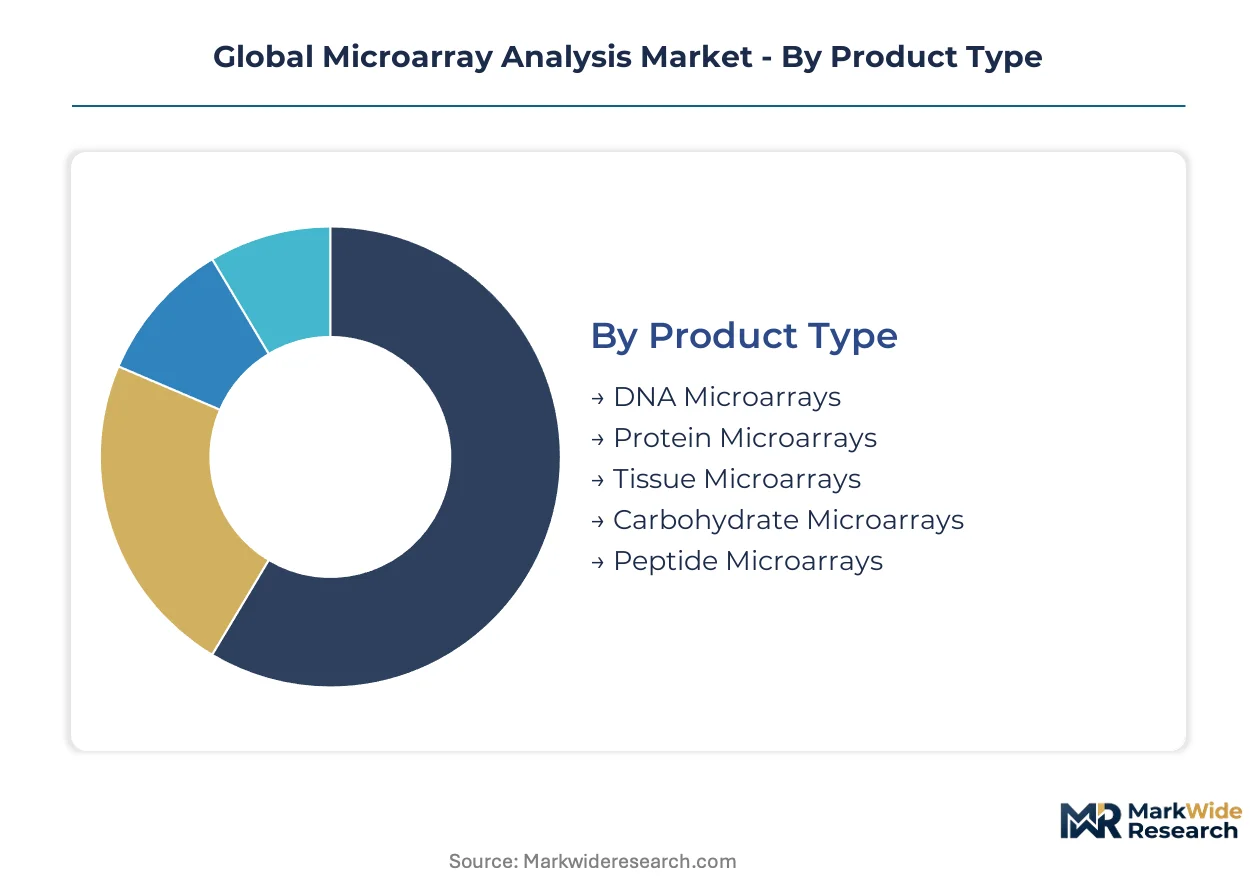
- DNA Microarrays:Oligonucleotide probes immobilized on glass or silicon substrates enable parallel interrogation of thousands of genomic loci. Academic research centers in the United States and Germany absorb the majority of high-density chip procurement for population-scale genomic profiling studies.
- Protein Microarrays:Purified proteins or antibodies spotted at defined coordinates support multiplexed serum biomarker detection. Pharmaceutical developers in North America and Japan are redirecting antibody characterization budgets toward these platforms as label-free detection modules mature.
- Tissue Microarrays:Formalin-fixed tissue cores arrayed for immunohistochemistry standardization.
- Carbohydrate Microarrays:Glycan structures printed for pathogen binding specificity studies.
- Peptide Microarrays:Synthetic peptide libraries for epitope mapping and immunogenicity screening.
DNA Microarrays absorb the bulk of installed capacity; Peptide Microarrays are expanding most quickly.
Technology:
Detection modality preferences fragment sharply between endpoint measurement and real-time kinetic readout.
- Label-Free Detection:Surface plasmon resonance and interferometric sensors eliminate fluorescent dye artifacts while delivering binding kinetics. Drug discovery teams in Germany and the United States are displacing legacy chemiluminescence workflows with these architectures for lead optimization.
- High-Density:Feature densities exceeding 100,000 probes per square centimeter enable genome-wide association studies. National Institutes of Health-funded consortia and RIKEN in Japan dominate procurement of these platforms for transcriptome-wide expression mapping.
- Two-Color:Competitive hybridization of Cy3/Cy5-labeled samples for relative expression quantification.
- One-Color:Single-channel fluorescence for absolute abundance measurement.
- Low-Density:Targeted panels for focused gene set validation.
High-Density platforms command the largest capital equipment footprint; Label-Free Detection is gaining share fastest.
Application:
Workflow integration requirements shape platform selection across discovery and diagnostic settings.
- Drug Discovery:Lead compound screening and target validation pipelines absorb the majority of pharmaceutical R&D microarray expenditure. North American biotechnology firms are embedding microarray data into AI-driven target identification workflows.
- Genomic Profiling:Copy number variation and SNP detection for disease association studies. Academic medical centers in Germany and Japan are expanding high-density platform procurement under precision medicine initiatives.
- Gene Expression Analysis:Transcriptome-wide mRNA abundance measurement.
- Biomarker Identification:Differential expression screening for diagnostic signature development.
- Epigenetics:DNA methylation and histone modification mapping.
Drug Discovery absorbs the bulk of platform investment; Genomic Profiling is climbing the fastest.
End User:
Procurement authority concentration varies sharply between centralized pharmaceutical purchasing and distributed academic acquisition.
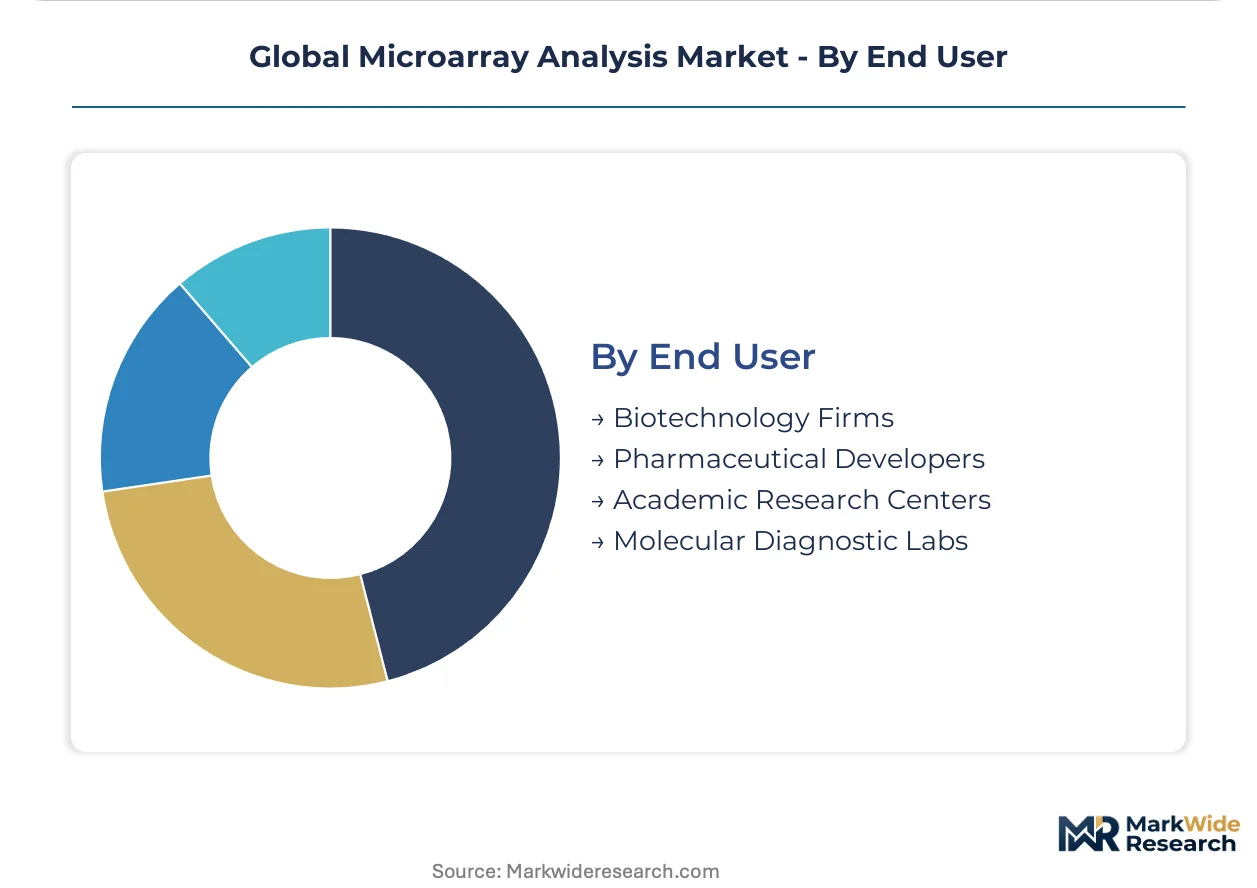
- Academic Research Centers:Decentralized procurement committees negotiate unbundled equipment and consumable contracts. National Institutes of Health-funded institutions in the United States and Max Planck Society affiliates in Germany are extending equipment refresh cycles while accelerating chip consumption.
- Pharmaceutical Developers:Centralized vendor management under ISO 13485-certified supply agreements. Thermo Fisher Scientific and QIAGEN channel control dominates North American and Asia-Pacific accounts through sample-to-insight workflow bundling.
- Biotechnology Firms:Mid-scale operations prioritizing flexible platform configurations.
- Molecular Diagnostic Labs:Clinical validation requirements under FDA and EMA frameworks.
Academic Research Centers absorb the bulk of installed base; Pharmaceutical Developers are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Germany, Switzerland, and the United States, while consumption spreads across academic medical centers in Japan, India, and European precision medicine hubs. This geographic split shapes vendor localization strategies and regulatory compliance architectures.
United States
NIH-funded consortia drive high-density platform procurement for population-scale genomic studies. FDA oversight of in vitro diagnostic devices mandates 510(k) clearance pathways for clinical microarray deployments. The Boston-Cambridge biotechnology corridor anchors label-free detection R&D, with pharmaceutical developers embedding surface plasmon resonance modules into lead optimization pipelines.
Germany
Max Planck Society affiliates extend equipment refresh cycles while accelerating consumable throughput for transcriptome mapping. EU In Vitro Diagnostic Regulation and REACH chemical registration reshape substrate manufacturing economics, forcing silane chemistry reformulation. The Munich-Heidelberg axis concentrates peptide microarray specialization for immunogenicity screening among mid-scale biotechnology firms.
Japan
RIKEN institutes dominate high-density platform procurement under national precision medicine initiatives. PMDA regulatory frameworks govern clinical diagnostic lab accreditation, creating compliance barriers for uncertified component vendors. The Kanto region around Tokyo houses concentrated pharmaceutical R&D expenditure, with drug discovery teams integrating microarray data into AI-driven target identification workflows.
India
CDSCO-registered contract research organizations build captive microarray capabilities for bioequivalence studies under pharmaceutical export mandates. Central Drugs Standard Control Organization oversight tightens quality documentation for molecular diagnostic platforms. The Hyderabad-Bengaluru corridor attracts captive service centers from multinational platform vendors seeking cost-advantaged technical support infrastructure.
Switzerland
Swissmedic certification requirements shape supplier qualification for pharmaceutical developer procurement pools. Precision medicine initiatives in Basel and Zurich drive demand for genomic profiling platforms with integrated sample-to-insight workflows. Swiss component suppliers absorb REACH-driven retooling costs for silane crosslinker reformulation ahead of authorization deadlines.
Global Microarray Analysis Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with channel control across pharmaceutical accounts. Three to five integrated platform vendors anchor the high-density sequencing-integrated segment, while specialized substrate chemistry suppliers occupy narrow niches in surface coating technologies. Strategic moves concentrate on workflow bundling and geographic expansion into Indian and Chinese pharmaceutical R&D markets.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc., QIAGEN N.V., and Illumina, Inc. exemplify contrasting competitive positions. Thermo Fisher extends channel dominance through sample-to-insight workflow integration. QIAGEN occupies a position centered on nucleic acid extraction-to-analysis continuity. Illumina anchors the sequencing-integrated microarray segment with sustained architecture investment. These three represent the archetype of platform vendors competing through ecosystem breadth rather than point solution specialization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| QIAGEN N.V. |
| Illumina, Inc. |
| Luminex Corporation |
| PerkinElmer, Inc. |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Agilent Technologies, Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal laboratory sustainability mandates gate qualified supply access and premium-tier pricing eligibility for microarray platform vendors serving European academic and diagnostic markets. REACH chemical registration requirements for silane crosslinkers and substrate coatings force reformulation costs onto German and Swiss suppliers, compressing margin pools for uncertified Asian competitors while elevating certified-component pricing tiers.
Pricing Analysis
Throughput-based value pricing anchors equipment contracts, with pharmaceutical developers paying premium rates for real-time kinetic binding data and academic centers negotiating per-run consumable bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling. Cost compression in standard-tier fluorescence systems intensifies as label-free detection modules capture drug discovery budgets. Academic procurement committees exhibit highest price sensitivity, extending equipment refresh cycles while accelerating chip consumption.
Supply Chain Analysis
Freight cost volatility for temperature-controlled oligonucleotide shipments from Asian synthesis hubs to European coating facilities is reshaping regional sourcing strategies. Substrate manufacturing concentrates in Germany, Switzerland, and the United States, while specialty dye chemistries draw from concentrated Japanese and South Korean chemical suppliers. Single-source vulnerability in high-purity glass slide supply creates exposure to export licensing delays. Distribution runs through ISO-certified channel partners serving pharmaceutical developer accounts and unbundled academic procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Microarray Analysis Market sits in a technology-transition phase as surface plasmon resonance architectures displace legacy fluorescence-based detection systems in pharmaceutical lead optimization workflows.
For Market Incumbents: Acquire label-free detection module specialists to close capability gaps against next-generation sequencing substitution threats. Consolidate channel control through sample-to-insight workflow bundling in North American pharmaceutical accounts. Invest in ISO 13485 certification coverage for Indian and Chinese component suppliers to defend margin position against REACH-driven European supply constraints. For New Entrants and Emerging Players: Enter via peptide microarray specialization for European biotechnology immunogenicity screening, where reduced assay complexity commands pricing premiums. Target CDSCO-registered Indian contract research organizations building captive capabilities for bioequivalence studies. Deploy cloud-based bioinformatics pipeline integration as the primary go-to-market wedge against legacy LIMS infrastructure. For Investors and Strategic Acquirers: FDA 510(k) clearance timelines extending for dual-market diagnostic platforms is the leading indicator that regulatory compliance capabilities will concentrate acquisition value in the mid-term. Position for platform vendors with synchronized FDA-EMA post-market surveillance infrastructure. Monitor academic procurement committee unbundling trends as the signal for consumable-pure-play consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Label-Free Detection Module Acquisition | Closes capability gaps against surface plasmon resonance displacement in German and US pharmaceutical accounts. |
| ISO 13485 Certification Expansion | Unlocks pharmaceutical developer procurement pools in North America and Asia-Pacific. |
| Sample-to-Insight Workflow Integration | Captures RIKEN and NIH-funded consortia through automated nucleic acid extraction bundling. |
| REACH-Compliant Substrate Reformulation | Preserves European market access for silane chemistry suppliers ahead of authorization deadlines. |
| Indian CRO Captive Capability Partnership | Secures cost-advantaged technical support infrastructure in the Hyderabad-Bengaluru corridor. |
Research Methodology
Document review covered SEC 10-K filings, FDA 510(k) clearance databases, EMA In Vitro Diagnostic Regulation guidance documents, and REACH chemical authorization lists, complemented by interviews with platform engineering directors, molecular diagnostic lab managers, pharmaceutical R&D procurement leads, and academic research center technology transfer officers. Bottom-up triangulation across instrument shipment records, consumable consumption patterns, and reagent supply contracts validated top-down market sizing derived from NIH and RIKEN funding disclosures.
Segment-level value outputs across product type, detection technology, application workflow, and end-user procurement authority were generated through econometric modeling of capital equipment replacement cycles and consumable throughput rates. CAGRs were derived from regression analysis of historical procurement patterns against precision medicine initiative funding trajectories and pharmaceutical R&D expenditure trends. Forecast inputs incorporated AI-driven target identification pipeline integration rates and label-free detection module adoption curves in lead optimization settings.
Revisions become necessary when synchronized FDA-EMA post-market surveillance harmonization delays materialize, when fluorophore supply concentration triggers input cost volatility, or when next-generation sequencing substitution accelerates beyond modeled clinical diagnostic lab budget reallocation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
North America Whole Exome Sequencing Market
Genomics
Genetic Material Market
Genomics
North America DNA Sequencing Products Market
Genomics
Immunogenetics Market
Genomics
Global Metagenomics Market
Genomics
APO E Gene Test Kit Market
Genomics
Spatial OMICS Market
Genomics
Global Metagenomic Sequencing Market
Genomics
UAE Genetic Testing Market
Genomics
Next Generation Genomics Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Molecular Breeding Market
Genomics
Antisense Oligonucleotides Market
Genomics
Genomics and Transcriptomics Market
Genomics
Plant Genomics Market
Genomics
Global Hereditary Cancer Testing Market