
 Viral Vector Development Market | 2026-2036
Viral Vector Development Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector Development Market Analytics
Synthetic DNA is expanding its role in plasmid supply chains, reducing reliance on traditional fermentation-derived inputs and lowering per-batch costs for lentiviral and AAV vector production. Lonza Group AG leverages end-to-end manufacturing platforms that span plasmid synthesis through fill-finish, anchoring its position in contract development. Thermo Fisher Scientific Inc. sustains broad distribution reach across research-grade and GMP reagent portfolios. Merck KGaA differentiates through its specialized lipid and transfection reagent portfolios that integrate into upstream viral packaging workflows.
Viral vector development encompasses the engineered design, production, and quality-controlled manufacture of modified viruses used to deliver genetic payloads into target cells, with titers, empty-to-full particle ratios, and replication competence serving as critical release specifications for clinical-grade material. The primary commercial purpose centers on supplying gene therapy, cancer immunotherapy, and vaccine programs with vectors that meet regulatory purity and potency thresholds. Adenoviral vectors occupy the most mature manufacturing infrastructure, reflecting decades of vaccine application experience, while AAV vectors attract the fastest capacity expansion as durable expression profiles align with one-time gene therapy dosing paradigms. Lentiviral vectors lead margin capture in ex vivo cell therapy applications where stable genomic integration remains mandatory.
The FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy products shapes facility design and validation requirements, while EMA's ATMP framework defines batch release and pharmacovigilance obligations across European manufacturing sites. ISO 14644 cleanroom classifications and WHO biosafety standards further constrain facility construction and operator training protocols. Stakeholders must monitor emerging FDA guidance on genome editing-associated vectors and decide whether to build captive capacity or deepen reliance on contract manufacturing organizations as pipeline candidates advance toward registrational trials.
Market Dynamics
Gene therapy developers now consolidate vector procurement around platforms that compress cell-line development timelines from months to weeks, forcing CDMOs to commit capital ahead of confirmed pipeline milestones.
Growth Catalysts
- FDA Accelerated Approval:Compressed review timelines for cell and gene therapies compress manufacturing scale-up schedules, pulling forward capacity investments by 18-24 months versus traditional biologics pathways.
- AAV Durability Profiles:Single-dose gene correction paradigms for inherited retinal and neuromuscular indications expand addressable patient populations beyond chronic protein replacement regimens.
- Massachusetts Cluster Density:The Boston-Cambridge corridor concentrates more GMP viral vector facilities per square mile than any other metropolitan region, creating supplier proximity effects that reduce logistics risk for Phase III programs.
Market Restraints
- Plasmid Supply Concentration:Fermentation-derived plasmid DNA for transient transfection protocols remains concentrated among three North American suppliers, creating input vulnerability for lentiviral batch release.
- Empty-to-Full Particle Ratios:AAV upstream productivity improvements have outpaced downstream separation technologies, forcing manufacturers to discard 60-70% of harvested material as empty capsids.
- EMA ATMP Batch Release Complexity:European pharmacovigilance obligations for advanced therapy medicinal products extend post-market surveillance timelines, delaying revenue recognition for cross-border commercial launches.
Strategic Opportunities
- India CDMO Expansion:The country's national pharmaceutical regulator has streamlined biosafety level-3 facility licensing, opening capacity for cost-sensitive early-phase viral vector programs.
- Synthetic DNA Convergence:Enzymatic DNA synthesis platforms are merging with cell-free protein expression systems, enabling same-week plasmid-to-vector turnaround for personalized cancer vaccines.
- Japan PMDA Sakigake Pathway:Priority review designation for regenerative medicines reduces regulatory lag for AAV-based rare disease therapies, attracting sponsor investment in Japanese manufacturing partnerships.
Industry Challenges
- Vector Analytical Scientist Shortage:Specialized expertise in digital droplet PCR and mass photometry for titer quantification commands 40% salary premiums over standard bioprocess roles, constraining QC hiring velocity.
- Multi-Product Facility Validation:Campaign changeover protocols for shared GMP suites require 6-8 week downtime between adenoviral and lentiviral runs, compressing net utilization rates.
- Patent Thicket Navigation:CRISPR-associated AAV delivery systems face overlapping licensing claims from academic institutions and tool companies, complicating freedom-to-operate assessments for genome editing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector Development Market |
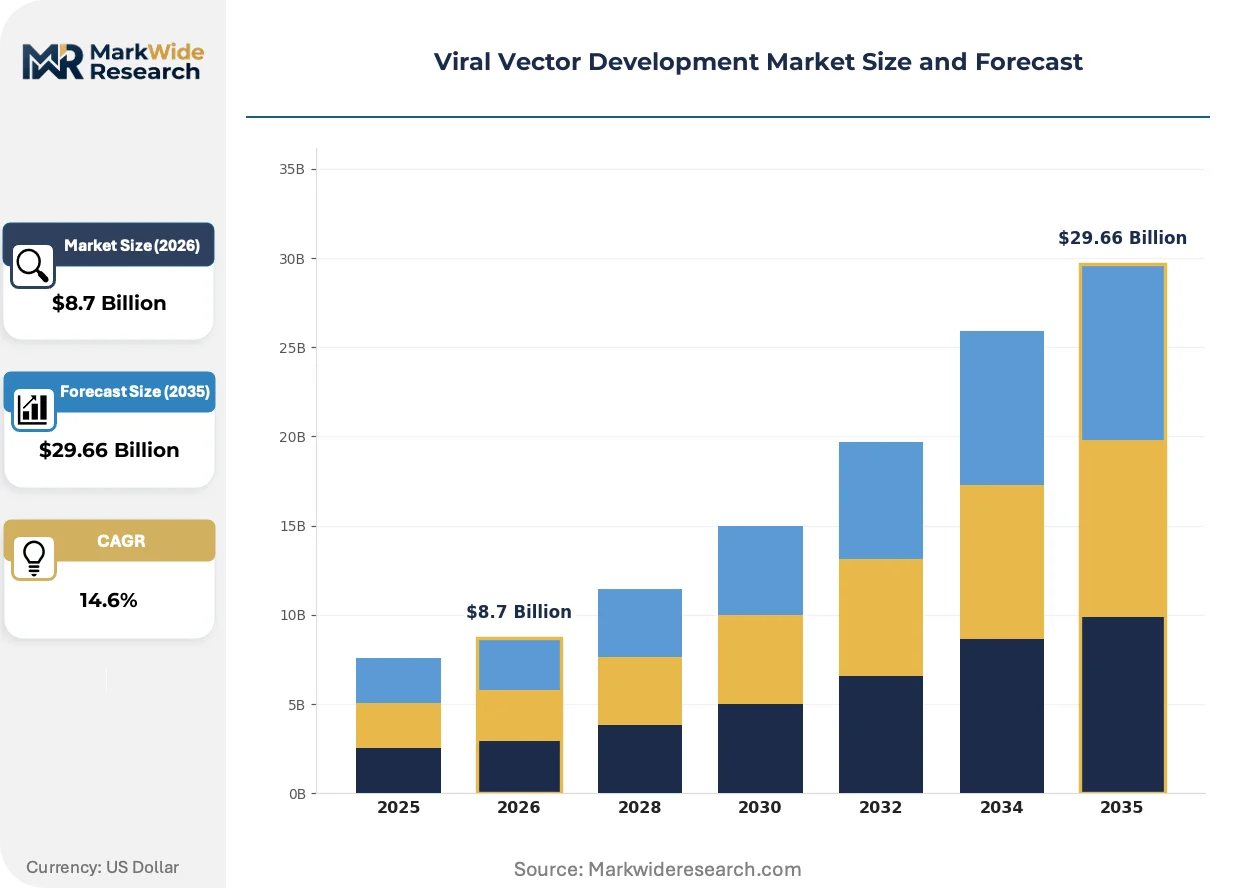
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Adenoviral Vectors, Lentiviral Vectors, AAV Vectors, Retroviral Vectors Application: Gene Therapy, Cancer Treatment, Vaccines, Regenerative Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Academic Labs Technology: Transfection, Electroporation, Viral Packaging, Site-Specific Integration |
| Companies Covered | Lonza Group AG, Thermo Fisher Scientific Inc., Merck KGaA, Charles River Laboratories International Inc., FUJIFILM Holdings Corporation, Oxford Biomedica plc, Catalent Biologics, Sanofi S.A., REGENXBIO Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector Development Market Evolving Landscape
Suspension-based production platforms are displacing adherent cell culture across all major vector modalities, rewriting facility design standards and capital allocation priorities for contract manufacturers.
Synthetic DNA templates are overtaking bacterial fermentation for plasmid supply in transient transfection workflows. Gene therapy developers at Phase II and beyond now specify enzymatically synthesized DNA to eliminate endotoxin contamination risks and compress batch release timelines. This shift is enabling same-month plasmid-to-vector production cycles that were previously impossible under E. coli-derived supply chains.
EMA's ATMP framework revisions are tightening post-authorization safety monitoring requirements for viral vector-delivered gene therapies. Manufacturers must now maintain dedicated pharmacovigilance infrastructure across all European commercial sites, increasing fixed cost burdens for mid-cap developers. The cell therapy segment is responding by consolidating European distribution partnerships with established hematology networks.
CDMO selection criteria now prioritize integrated analytical packages over unit-cost bidding for vector production. Sponsors are unbundling release testing from manufacturing contracts, retaining specialized testing laboratories for potency assays that require patient-derived cell lines. This pattern is most visible in United States-based rare disease programs where FDA interactions demand consistent assay methodology across clinical phases.
Viral Vector Development Market Segmentation
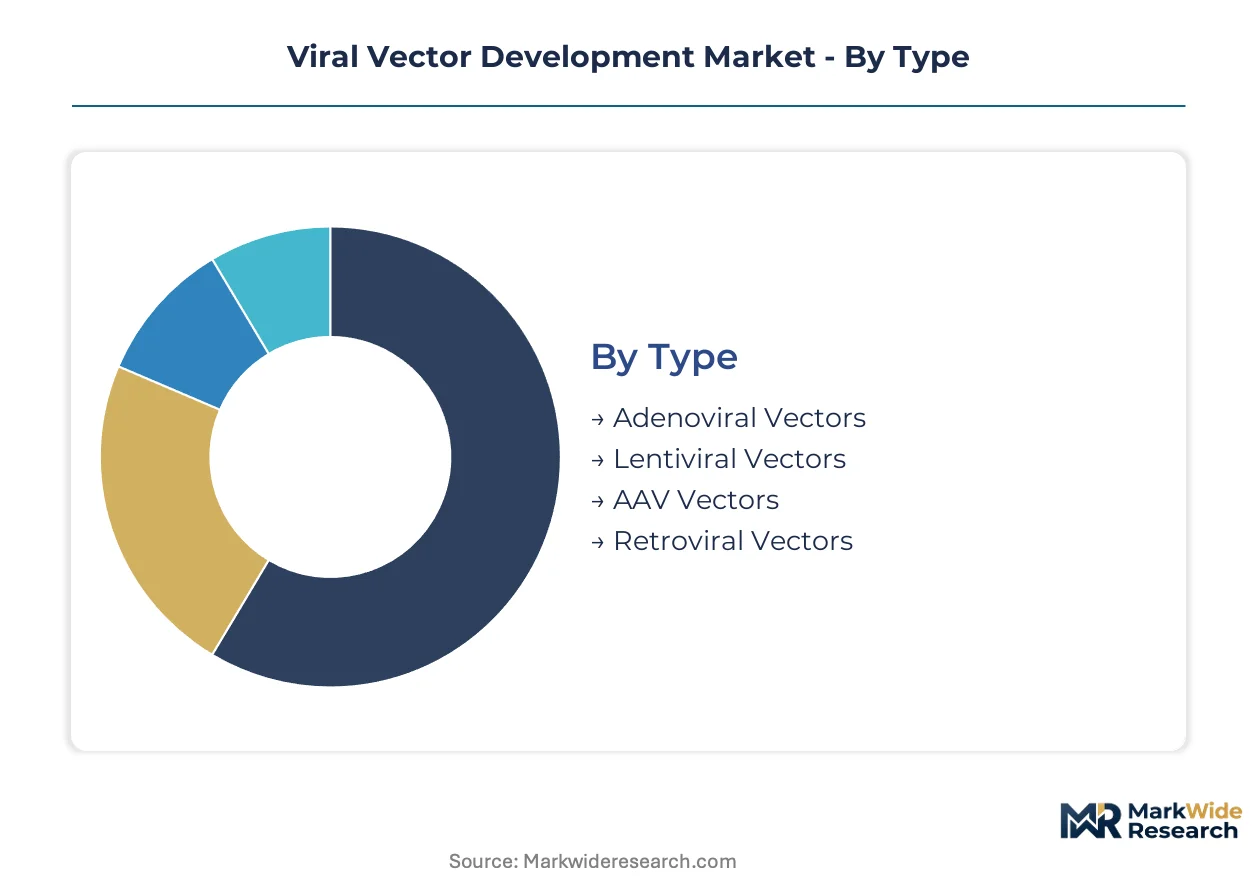
Viral vector development segments reflect distinct manufacturing footprints, regulatory pathways, and customer procurement behaviors. Platform selection determines facility capital requirements, analytical validation protocols, and partnership structures with contract manufacturers.
Type:
Vector platform replacement cycles accelerate as gene therapy developers abandon legacy systems for higher-yielding alternatives, compressing equipment depreciation schedules and forcing CDMOs to retire adherent infrastructure ahead of planned obsolescence.
- Adenoviral Vectors:These double-stranded DNA vectors tolerate high-titer suspension culture and withstand lyophilization stress, suiting thermostable vaccine distribution. Demand clusters in United States-based pandemic preparedness contracts where the Biomedical Advanced Research and Development Authority stockpiles outbreak-responsive manufacturing capacity.
- AAV Vectors:Single-stranded DNA constructs achieve durable transgene expression in non-dividing cells, enabling one-time dosing for inherited disorders. Procurement concentrates in Massachusetts and North Carolina gene therapy clusters where the FDA's accelerated approval pathway pulls forward Phase III manufacturing commitments.
- Lentiviral Vectors:RNA-based systems integrate into host genomes, mandatory for ex vivo CAR-T modification protocols. Stable integration profiles command premium pricing in contract manufacturing agreements.
- Retroviral Vectors:Gamma-retroviral platforms retain niche application in hematopoietic stem cell gene therapy, constrained by insertional mutagenesis risk profiles that limit addressable indications.
Adenoviral vectors sit at the top of the volume ranking, with AAV vectors climbing the fastest.
Application:
Application segments diverge sharply in reimbursement structure, with one-time curative therapies commanding different pricing negotiations than chronic intervention paradigms.
- Gene Therapy:In vivo and ex vivo approaches target monogenic diseases through permanent genetic correction. United States rare disease programs drive procurement, where the FDA's Breakthrough Therapy designation compresses development timelines and mandates early manufacturing scale-up.
- Cancer Treatment:Oncolytic viruses and CAR-T vectors require patient-specific or tumor-targeted manufacturing, creating batch-size constraints that favor flexible CDMO partnerships over captive facilities.
- Vaccines:Adenoviral platforms for infectious disease prophylaxis leverage existing regulatory precedent from Ebola and COVID-19 emergency authorizations, reducing validation burdens for new entrants.
- Regenerative Medicine:Vectors delivering reprogramming factors for iPSC generation face evolving potency assay requirements that extend analytical development timelines.
Gene Therapy captures the dominant revenue position, with Cancer Treatment expanding most quickly as solid tumor indications broaden addressable populations.
End User:
Customer procurement sophistication varies across organizational scale, with large pharmas demanding integrated analytical packages that smaller academic groups cannot specify.
- Pharmaceutical Companies:Multinational sponsors with approved gene therapies now specify end-to-end manufacturing platforms spanning plasmid synthesis through fill-finish, consolidating vendor relationships to reduce technology transfer risk.
- Biotechnology Firms:Venture-backed developers prioritize speed-to-IND over cost optimization, accepting premium CDMO pricing for dedicated manufacturing slots that de-risk clinical milestone achievement.
- Research Institutions:NIH-funded academic centers procure research-grade vectors under material transfer agreements, creating pricing pressure distinct from commercial GMP procurement.
- Academic Labs:Individual investigator grants support small-batch vector production, with procurement fragmented across institutional core facilities and specialized reagent distributors.
Pharmaceutical Companies anchor procurement volume, with Biotechnology Firms gaining share fastest as venture deployment into gene therapy accelerates.
Technology:
Technology selection determines upstream productivity ceilings and downstream purification burden, with enzymatic methods displacing traditional biological production across multiple vector modalities.
- Transfection:Calcium phosphate and lipid-based reagent systems dominate plasmid delivery into packaging cell lines, with synthetic DNA templates now displacing fermentation-derived inputs to reduce endotoxin contamination.
- Electroporation:High-voltage pulse systems achieve superior transfection efficiency in hard-to-transfect cell types, supporting lentiviral production in suspension-adapted HEK293 derivatives.
- Viral Packaging:Helper-dependent and helper-free systems segregate replication-competent virus risk, with third-generation lentiviral split-genome designs now standard for clinical applications.
- Site-Specific Integration:Engineered recombinase systems enable targeted genomic insertion, emerging as a manufacturing technology for producer cell line generation rather than therapeutic payload delivery.
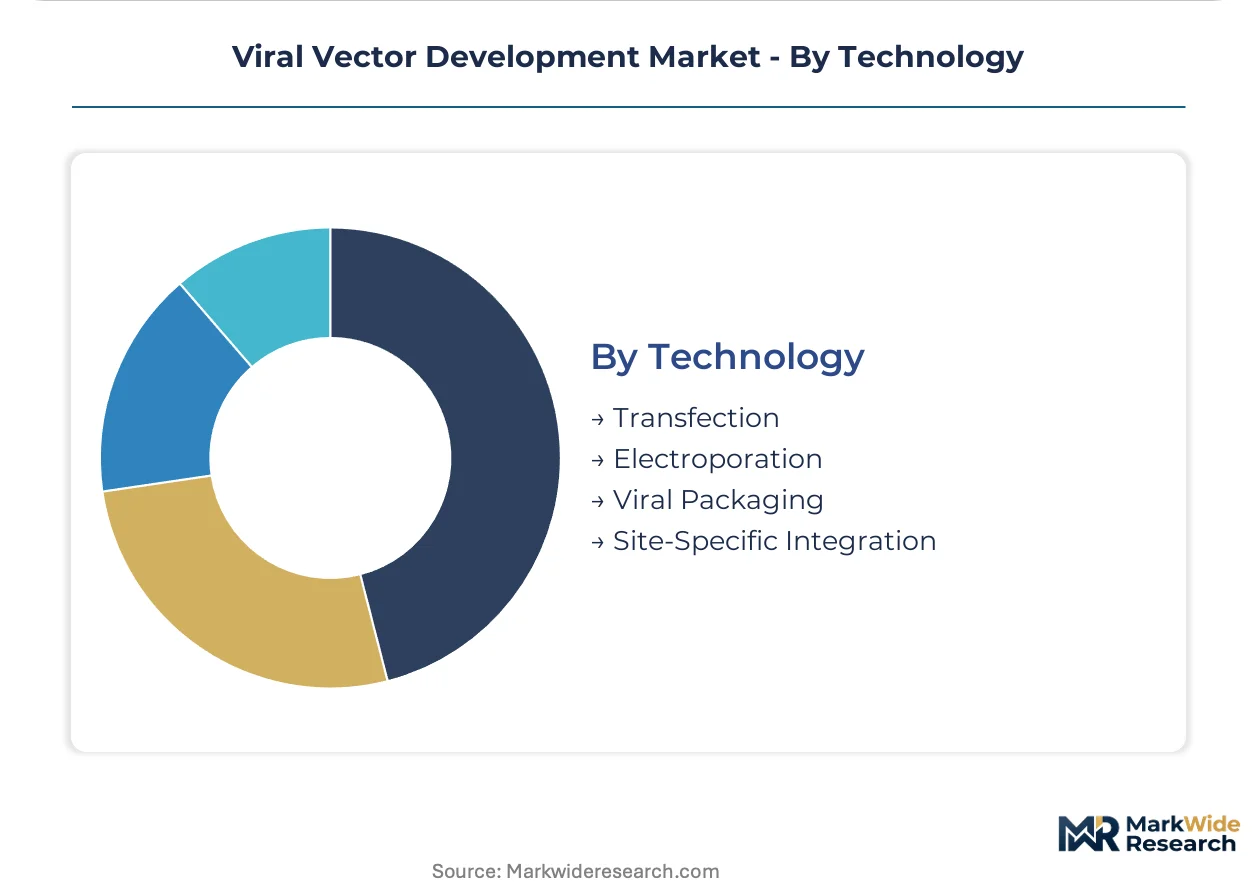
Transfection retains the dominant installed base, with Electroporation expanding most quickly as suspension culture platforms displace adherent systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors the densest concentration of GMP viral vector facilities worldwide, with the National Institutes of Health and private venture capital funding the infrastructure that supplies gene therapy developers across North America and Europe.
United States
FDA accelerated approval pathways for cell and gene therapies compress manufacturing scale-up schedules by 18-24 months versus traditional biologics. The Biomedical Advanced Research and Development Authority stockpiles outbreak-responsive adenoviral capacity. North Carolina's Research Triangle and Massachusetts' Kendall Square host the majority of new CDMO expansions.
Germany
EMA's ATMP framework defines batch release obligations that extend post-market surveillance timelines for advanced therapy medicinal products. The country's national pharmaceutical regulator enforces ISO 14644 cleanroom classifications alongside WHO biosafety standards. Heidelberg and Munich clusters concentrate lentiviral production for ex vivo cell therapy applications.
Switzerland
Swissmedic's alignment with EMA procedures enables seamless cross-border commercial launches while maintaining independent pharmacovigilance infrastructure. Basel's pharmaceutical hub hosts integrated plasmid-to-vector manufacturing platforms. The Lake Geneva region attracts sponsor investment through specialized lipid and transfection reagent portfolios.
Japan
PMDA's Sakigake priority review pathway reduces regulatory lag for AAV-based rare disease therapies. METI coordinates national manufacturing partnerships to secure domestic vector supply for regenerative medicine programs. The Kanto region around Tokyo concentrates the country's GMP viral vector capacity expansion.
India
The country's national pharmaceutical regulator streamlined biosafety level-3 facility licensing to capture cost-sensitive early-phase viral vector programs. CDSCO harmonization with ICH guidelines accelerates clinical trial approvals for foreign sponsors. Hyderabad and Bangalore clusters emerge as competitive alternatives to Western CDMO pricing.
Viral Vector Development Market Competitive Landscape
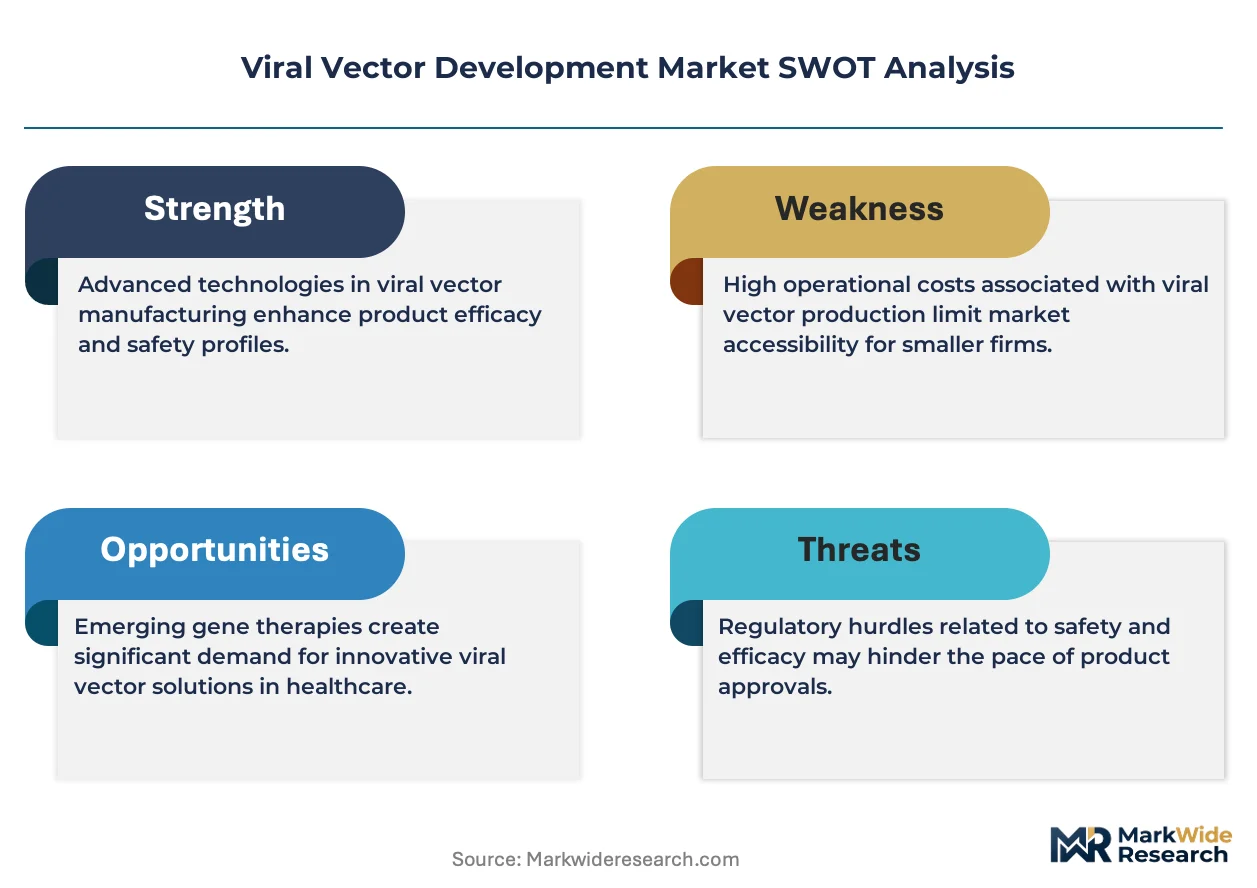
Capacity expansion dominates the current landscape as contract manufacturers commit capital ahead of confirmed pipeline milestones. The vendor base organizes around three tiers: integrated platform providers spanning plasmid synthesis through fill-finish, specialized vector-focused CDMOs, and diversified life science conglomerates with reagent portfolios. Strategic partnerships and technology licensing represent the dominant competitive moves as sponsors unbundle release testing from manufacturing contracts.
Within the integrated platform tier, Lonza Group AG and Thermo Fisher Scientific Inc. exemplify archetypes that anchor end-to-end manufacturing relationships. Lonza occupies a position defined by captive plasmid synthesis capabilities, while Thermo Fisher sits within the distribution-reach archetype spanning research-grade and GMP reagent portfolios. Merck KGaA represents the specialized inputs archetype through differentiated lipid and transfection reagent integration into upstream workflows.
| Leading Market Players |
|---|
| Lonza Group AG |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Charles River Laboratories International Inc. |
| FUJIFILM Holdings Corporation |
| Oxford Biomedica plc |
| Catalent Biologics |
| Sanofi S.A. |
| REGENXBIO Inc. |
| Others |
Value Network & Pricing Analysis
Captive plasmid synthesis capabilities anchor pricing power for integrated CDMOs while forcing pure-play vector manufacturers into premium spot-market sourcing for transient transfection inputs. The FDA's Chemistry, Manufacturing, and Controls guidance elevates release-testing costs that concentrate in Massachusetts and North Carolina GMP clusters, compressing margins for sponsors without backward integration into upstream DNA supply.
Pricing Analysis
Input-cost pass-through from fermentation-derived plasmid DNA and synthetic DNA templates dominates contract manufacturing agreements, with enzymatic synthesis commanding premium pricing over E. coli-derived alternatives. Pricing stratifies across GMP-certified, research-grade, and preclinical tiers based on FDA validation status and analytical package depth. Cost compression in research-grade vector production is intensifying as synthetic DNA platforms reduce per-batch material costs. Biotechnology firms with venture backing show lowest price sensitivity, while academic labs under NIH material transfer agreements drive economy-tier procurement.
Supply Chain Analysis
Dual-sourcing requirements for plasmid DNA now mandate qualification of at least two North American suppliers plus one European alternative for Phase III programs. Manufacturing concentrates in the United States, Germany, and Switzerland, with Switzerland's Basel corridor hosting integrated plasmid-to-vector platforms. Raw material dependencies center on HEK293 cell lines, transfection reagents, and chromatography resins. Single-source vulnerability in lipid nanoparticle formulation creates exposure for lentiviral vector programs. Distribution runs through temperature-controlled logistics networks serving Kendall Square and Research Triangle GMP facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viral vector development market has entered a late-cycle quality phase where gene therapy developers now prioritize integrated analytical packages over unit-cost bidding, reflecting demand-shift toward FDA-consistency across clinical phases.
For Market Incumbents: Extend analytical service bundling to capture release-testing relationships that sponsors are unbundling from manufacturing contracts. Consolidate European pharmacovigilance infrastructure ahead of EMA ATMP framework revisions tightening post-authorization obligations. Capacity addition in North Carolina's Research Triangle defends against Massachusetts cluster congestion. For New Entrants and Emerging Players: CDMO partnerships with Indian biosafety level-3 facilities offer the most penetrable entry path for cost-sensitive early-phase programs. Target synthetic DNA convergence opportunities where enzymatic synthesis platforms merge with cell-free expression systems. Position through same-week plasmid-to-vector turnaround capabilities for personalized cancer vaccine developers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap CDMOs with captive plasmid synthesis because FDA accelerated approval pathways compress manufacturing scale-up schedules and pull forward capacity commitments. Platform specialists with integrated fill-finish capabilities represent priority acquisition archetypes. Watch for inflection when empty-to-full particle ratio technologies materially improve AAV downstream yields.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | FDA accelerated approval compresses timelines, pulling forward 18-24 month capacity investments in Massachusetts. |
| Backward Integration | Captive plasmid synthesis eliminates endotoxin contamination risks and reduces reliance on three-supplier concentration. |
| Regulatory Approval Pathway | Japan PMDA Sakigake priority review reduces regulatory lag for AAV-based rare disease therapies. |
| Strategic Partnership | European distribution partnerships with hematology networks respond to EMA ATMP pharmacovigilance requirements. |
| Technology Licensing | Site-specific integration systems enable producer cell line generation, displacing transient transfection workflows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at CDMOs, formulary directors for rare disease therapies, and GMP facility operations managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and ISO 14644 cleanroom certification databases. Bottom-up vector production capacity estimates triangulated against top-down gene therapy pipeline valuations.
Segment-weighting across vector type, application, end user, and technology dimensions structured the analytical framework, with AAV, lentiviral, adenoviral, and retroviral platforms each assigned production-volume coefficients derived from GMP facility utilization rates. CAGRs were computed from facility expansion announcements, venture deployment into gene therapy, and regulatory approval velocity. Forecast inputs incorporated synthetic DNA adoption curves and suspension culture platform displacement rates.
Revisions become necessary when FDA guidance on genome editing-associated vectors materializes, when plasmid supply concentration shifts, or when EMA ATMP batch release protocols change. Deviation in empty-to-full particle separation technology timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market