
 Genome Sequencing Market | 2026-2036
Genome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Genome Sequencing Market Analysis
The capital-intensity divergence between short-read and long-read platforms is bifurcating competitive strategy across the industry. Illumina, Inc. leverages its installed base of high-throughput instruments to sustain recurring consumable revenue in population-scale genomics. Oxford Nanopore Technologies differentiates through portable, real-time sequencing devices that anchor point-of-care and field-based applications. Pacific Biosciences of California, Inc. specializes in high-fidelity long-read chemistry for complex structural variant detection in research settings.
Genome sequencing determines the precise order of nucleotides within DNA molecules using fluorescence-based detection, nanopore current modulation, or single-molecule real-time chemistry to generate digital readouts for analysis. The technology enables variant calling for inherited disease diagnosis, tumor mutational profiling, and pathogen identification across clinical and research environments. Next-Generation Sequencing occupies the dominant revenue position due to its throughput economics and established bioinformatics ecosystems. Third-Generation Sequencing captures expanding share in de novo assembly and epigenetic analysis where read length confers decisive analytical advantage. Whole Genome Sequencing commands premium positioning in neonatal intensive care and undiagnosed rare disease programs where comprehensive coverage outweighs cost sensitivity.
FDA oversight of laboratory-developed tests and in vitro diagnostics shapes validation requirements and commercialization timelines for clinical sequencing products. The EMA's In Vitro Diagnostic Regulation and Japan's PMDA quality management standards create parallel compliance obligations for multinational platform vendors. WHO guidance on genomic surveillance for emerging pathogens continues to influence national procurement priorities and sequencing infrastructure investments. Stakeholders must monitor evolving reimbursement codes for somatic and germline testing as payors recalibrate coverage criteria against demonstrated clinical utility.
Market Dynamics
Medicare coverage expansion for multi-cancer early detection tests is compressing reimbursement timelines and pulling sequencing infrastructure into community oncology networks at unprecedented velocity.
Growth Catalysts
- Companion Diagnostic Pathways:FDA accelerated approval tracks for tumor-agnostic biomarkers are shortening validation cycles for sequencing-based assays. Oncology drug developers now co-develop diagnostics with therapeutic candidates.
- Liquid Biopsy Integration:Cell-free DNA analysis is displacing tissue biopsy in metastatic monitoring workflows. Community hospitals adopt minimal residual disease testing for post-surgical surveillance.
- Pathogen Genomic Surveillance:WHO guidance on genomic epidemiology is mandating sequencing capacity in national public health laboratories. Emerging infectious disease programs fund instrument procurement directly.
Market Restraints
- Reagent Supply Concentration:Fluorescent dye chemistries and flow cell manufacturing concentrate among single-source suppliers in East Asian production clusters. Disruption propagates directly to sequencing run completion rates.
- Bioinformatics Bottleneck:Variant interpretation requires specialized computational infrastructure and curated knowledge bases. Clinical laboratories face persistent shortages of variant scientists and pipeline engineers.
- Reimbursement Uncertainty:Germline testing for healthy populations lacks established CPT codes in US commercial payor frameworks. Coverage determinations lag behind test availability by 18-36 months.
Strategic Opportunities
- Neonatal Intensive Care Penetration:Rapid whole genome sequencing for critically ill infants remains underdeployed outside academic medical centers. Point-of-care platforms could compress diagnostic odyssey timelines from years to days.
- Epigenetic Assay Expansion:Methylation profiling for minimal residual disease detection converges with circulating tumor DNA workflows. Multi-omics integration creates differentiated service offerings.
- Field-Based Deployments:Portable nanopore devices enable outbreak response in resource-limited settings. Agricultural and environmental monitoring applications expand addressable use cases beyond human health.
Industry Challenges
- Data Interoperability Friction:Electronic health record integration requires HL7 FHIR implementation across heterogeneous hospital IT environments. Siloed genomic data limits longitudinal patient tracking.
- Variant Classification Backlogs:Ambiguous clinical significance ratings accumulate in public databases faster than expert panels can adjudicate. Laboratories face liability exposure from reinterpretation events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genome Sequencing Market |
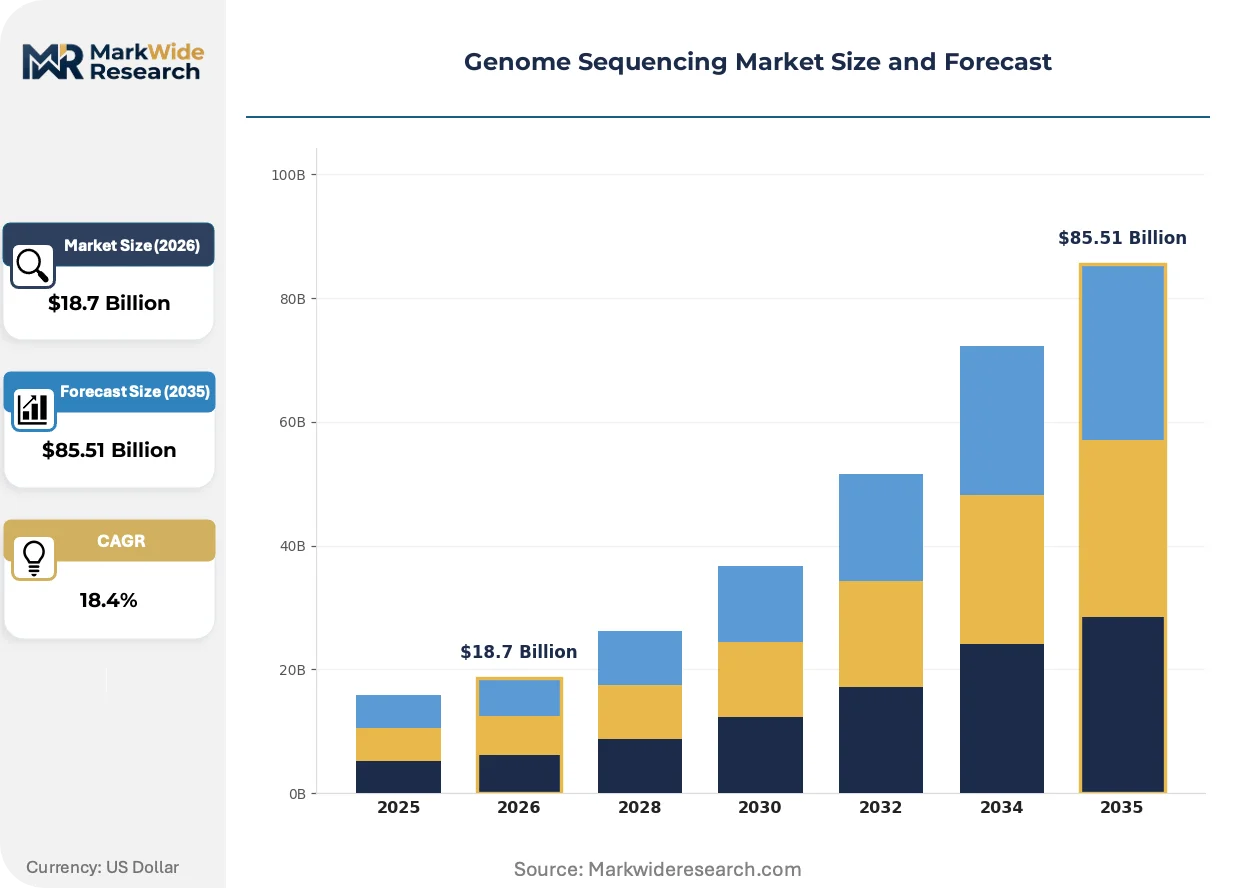
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanger Sequencing, Next-Generation Sequencing, Third-Generation Sequencing, Whole Genome Sequencing Technology: DNA Sequencing, RNA Sequencing, Whole Exome Sequencing, Targeted Sequencing Application: Clinical Diagnostics, Research, Drug Discovery, Personalized Medicine End User: Academic Institutes, Hospitals, Biotechnology Companies, Contract Research Organizations |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Inc., BGI Genomics, Oxford Nanopore Technologies, Pacific Biosciences of California, Inc., QIAGEN, Agilent Technologies, Inc., Macrogen, Inc., Azenta US, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genome Sequencing Market Emerging Trajectories
Sequencing chemistry diversification is fragmenting platform economics and forcing specialization across throughput tiers, read length requirements, and deployment environments.
Long-read sequencing is displacing short-read assemblies for complex structural variant detection in rare disease research. Academic genome centers and pharmaceutical target discovery groups now specify high-fidelity chemistry for de novo projects. The shift compresses false negative rates in diagnostic workflows where cryptic rearrangements drive phenotypes.
EMA's In Vitro Diagnostic Regulation imposes quality management system requirements on sequencing instrument manufacturers selling into European clinical markets. notified body capacity constraints are extending certification timelines. Platform vendors are consolidating EU authorized representative functions and harmonizing technical documentation across MDR and IVDR frameworks.
Hospital procurement committees now unbundle sequencing instruments from mandatory reagent contracts. Capital acquisition committees evaluate total cost of ownership across consumable pricing tiers and service agreement structures. This behavioral shift concentrates in US integrated delivery networks with centralized laboratory governance.
Genome Sequencing Market Segmentation
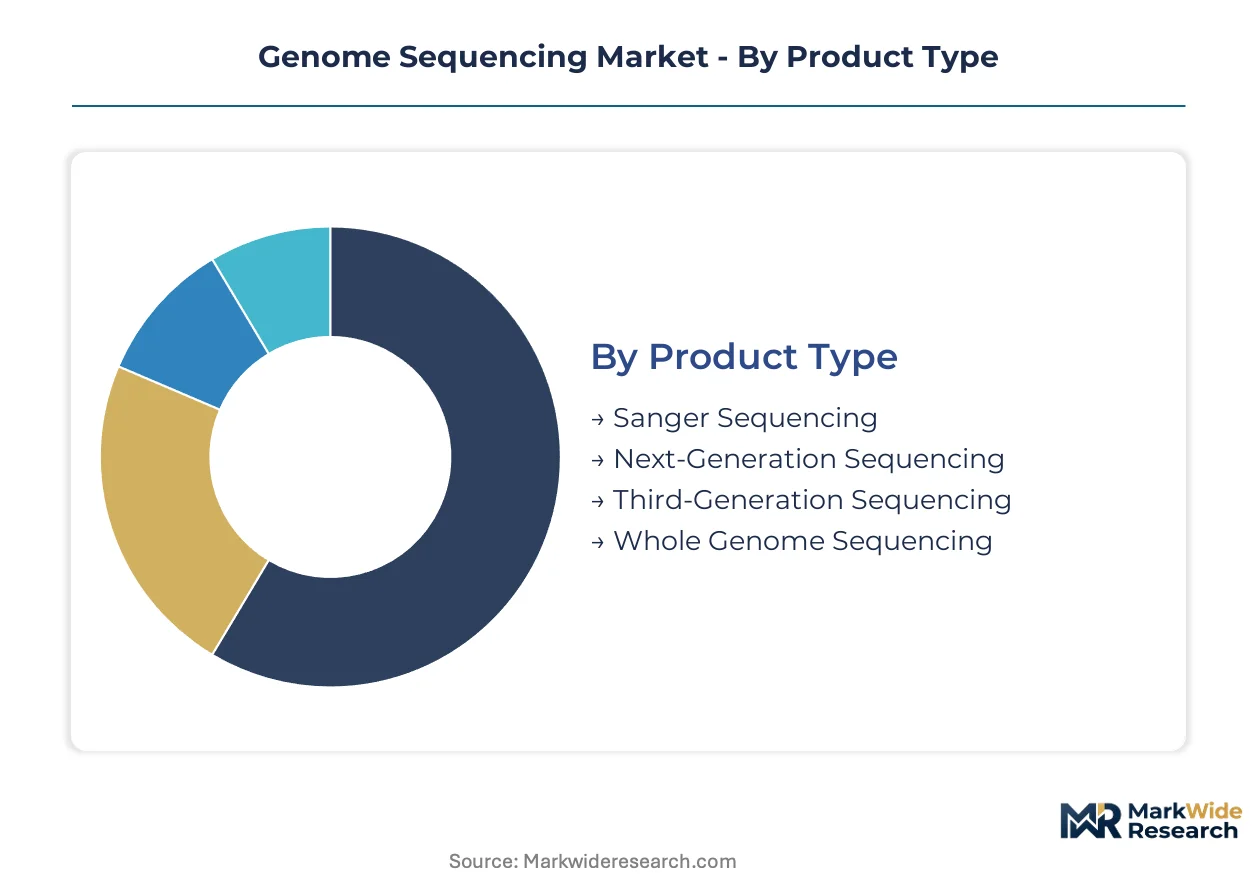
Platform heterogeneity in genome sequencing creates distinct regulatory pathways, reimbursement codes, and validation requirements that shape commercial strategy across each product category. Segmentation clarity enables stakeholders to align capital deployment with specific compliance frameworks and end-use demand concentrations.
Product Type:
FDA clearance pathways diverge sharply between established fluorescence-based chemistries and emerging nanopore or single-molecule platforms, compressing time-to-market for some segments while extending validation timelines for others.
- Next-Generation Sequencing:Fluorescence-based detection chemistry dominates throughput economics in population-scale genomics and oncology workflows. Hospital laboratories in the United States concentrate procurement around Illumina's installed base to secure Medicare reimbursement for companion diagnostic assays.
- Third-Generation Sequencing:Real-time nanopore and single-molecule chemistries enable portable deployment for field-based pathogen surveillance and point-of-care applications. Academic medical centers and public health laboratories in the United Kingdom and Australia fund instrument procurement for outbreak response capabilities.
- Sanger Sequencing:Capillary electrophoresis remains the gold standard for targeted variant confirmation in clinical laboratories requiring definitive diagnostic calls.
- Whole Genome Sequencing:Comprehensive nucleotide coverage commands premium positioning in neonatal intensive care and undiagnosed rare disease programs where diagnostic odyssey compression justifies cost sensitivity.
Established volume favors Next-Generation Sequencing; emerging adoption favors Third-Generation Sequencing.
Technology:
Cost tier stratification separates high-throughput population screening from focused exome or targeted panels in routine clinical workflows.
- DNA Sequencing:Germline and somatic variant detection anchors inherited disease diagnosis and tumor mutational profiling in hospital pathology departments. Payers in Germany and France maintain distinct reimbursement schedules for constitutional versus neoplastic testing.
- Targeted Sequencing:Amplicon and hybridization capture panels concentrate sequencing reads on clinically actionable gene sets, reducing per-sample cost for oncology drug selection. Community oncology networks in the United States adopt these panels for minimal residual disease monitoring.
- RNA Sequencing:Transcriptomic analysis enables fusion detection and expression quantification in hematologic malignancy classification.
- Whole Exome Sequencing:Protein-coding region coverage balances diagnostic yield against data burden in pediatric genetics programs.
DNA Sequencing captures the largest revenue base; Targeted Sequencing climbs the fastest as community hospitals expand molecular pathology capacity.
Application:
Customer type concentration determines whether procurement flows through hospital capital committees, pharmaceutical R&D budgets, or academic grant funding mechanisms.
- Clinical Diagnostics:FDA-cleared assays for hereditary cancer syndromes and pharmacogenomics drive recurring revenue through hospital laboratory service lines. Medicare coverage decisions for multi-cancer early detection tests are reshaping reimbursement dynamics in the United States.
- Drug Discovery:Pharmaceutical developers specify sequencing infrastructure for target identification, patient stratification, and biomarker validation in clinical trials. Contract research organizations in Switzerland and Singapore build sequencing capacity to capture outsourced genomics workflows.
- Research:Academic genome centers pursue de novo assembly and structural variant detection for publication-driven funding cycles.
- Personalized Medicine:Direct-to-consumer and physician-ordered testing platforms navigate varying state laboratory licensing requirements.
Clinical Diagnostics commands the deepest revenue pool; Drug Discovery shows the steepest expansion trajectory as oncology pipelines require companion diagnostic co-development.
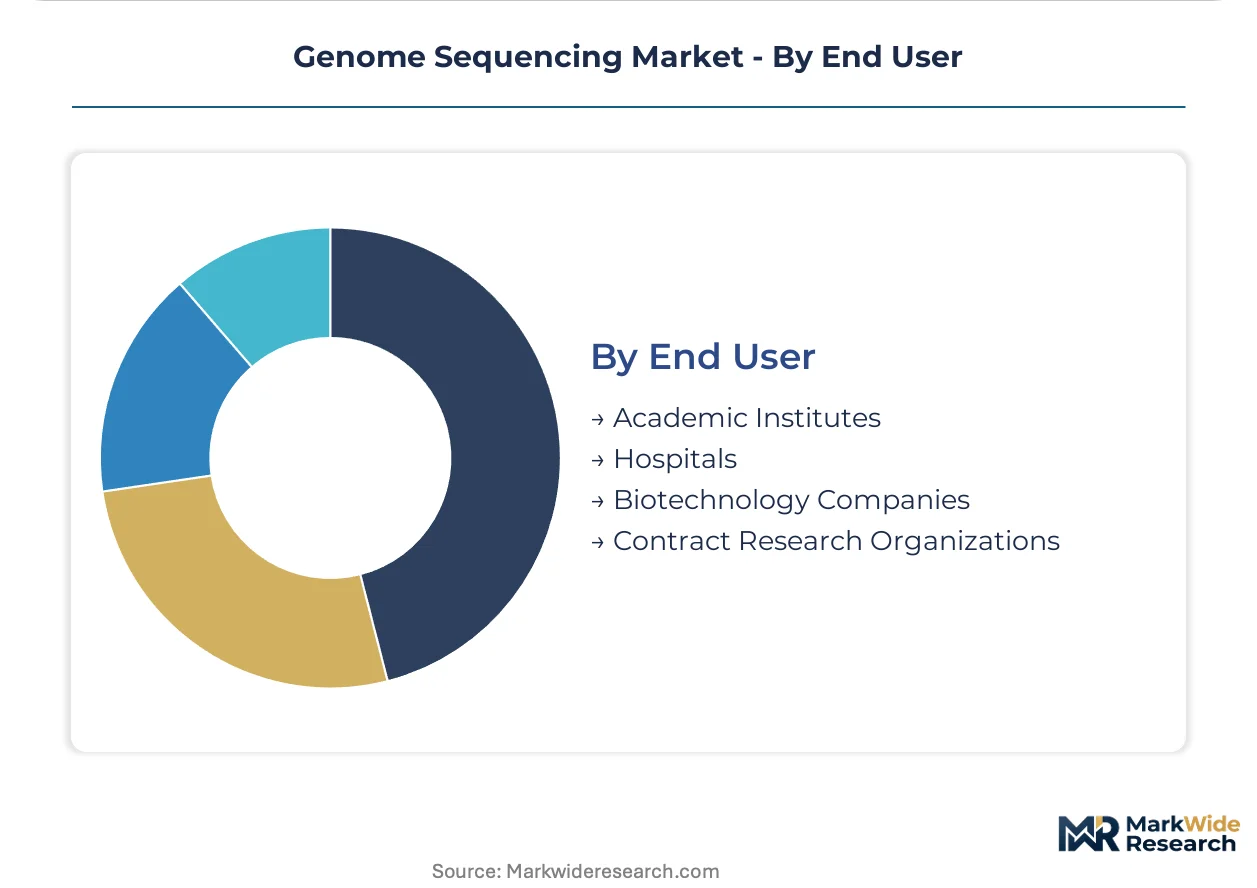
End User:
Procurement authority fragmentation across centralized health systems, independent research institutes, and outsourced service providers creates heterogeneous sales cycle dynamics.
- Hospitals:Integrated delivery networks consolidate sequencing procurement through centralized laboratory governance, evaluating total cost of ownership across consumable tiers and service agreements. US health systems with Medicare Advantage penetration prioritize FDA-cleared assays for risk-adjusted reimbursement.
- Biotechnology Companies:Cell therapy and gene editing developers build in-house sequencing capacity for quality control and regulatory submission support. Cambridge and South San Francisco clusters concentrate venture-funded platform investments.
- Academic Institutes:Grant-funded genome centers compete for National Institutes of Health and Wellcome Trust instrumentation awards.
- Contract Research Organizations:Outsourced sequencing services capture pharmaceutical demand for variable-capacity genomics without capital commitment.
Hospitals anchor installed base expansion; Biotechnology Companies drive the fastest capacity buildouts as therapeutic developers integrate sequencing into manufacturing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Academic laboratories in India and Southeast Asia prioritize per-run economics, while neonatal intensive care units in Germany and Switzerland accept premium pricing for diagnostic certainty.
United States
Medicare coverage decisions for multi-cancer early detection tests are compressing reimbursement timelines and pulling sequencing infrastructure into community oncology networks. FDA accelerated approval tracks for tumor-agnostic biomarkers shorten validation cycles for sequencing-based assays. The Greater Boston and San Francisco Bay Area clusters concentrate venture-funded biotechnology investments in cell therapy quality control applications.
Germany
Hospital procurement committees unbundle sequencing instruments from mandatory reagent contracts, evaluating total cost of ownership across consumable tiers. EMA's In Vitro Diagnostic Regulation imposes quality management system requirements on instrument manufacturers selling into clinical markets. The Munich and Heidelberg regions anchor academic genome centers pursuing de novo assembly for rare disease research.
China
National genomic surveillance programs for emerging pathogens mandate sequencing capacity in provincial public health laboratories. NMPA oversight of in vitro diagnostics shapes validation requirements for clinical sequencing products. The Beijing-Tianjin-Hebei corridor concentrates domestic platform development for population-scale screening initiatives.
United Kingdom
NHS England's genomic medicine service drives standardized procurement for rare disease and cancer testing across integrated care systems. WHO guidance on genomic epidemiology influences national sequencing infrastructure investments for outbreak response. The Cambridge and Oxford clusters specialize in nanopore device deployment for field-based pathogen surveillance.
Japan
PMDA quality management standards create parallel compliance obligations for multinational platform vendors seeking clinical market access. Pharmaceutical developers specify sequencing infrastructure for companion diagnostic co-development in oncology pipelines. The Kanto region around Tokyo concentrates contract research organization capacity for biomarker validation workflows.
Genome Sequencing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Short-read fluorescence-based platforms dominate throughput economics and installed base expansion, while long-read chemistries capture premium positioning in complex structural variant detection. The market stratifies into three archetypes: diversified life science conglomerates with broad analytical portfolios, pure-play sequencing specialists with platform-specific consumable ecosystems, and emerging portable device developers targeting point-of-care deployment. Competitive dynamics center on reagent contract unbundling and bioinformatics pipeline integration.
Within the pure-play sequencing specialist tier, Illumina, Inc. and Oxford Nanopore Technologies occupy positions representing contrasting technological philosophies. Illumina anchors the high-throughput, centralized laboratory archetype with recurring consumable revenue models. Oxford Nanopore exemplifies the portable, real-time deployment archetype for field-based and point-of-care applications. Pacific Biosciences of California, Inc. sits within the high-fidelity long-read segment serving academic and pharmaceutical research settings where read length confers analytical advantage.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| BGI Genomics |
| Oxford Nanopore Technologies |
| Pacific Biosciences of California, Inc. |
| QIAGEN |
| Agilent Technologies, Inc. |
| Macrogen, Inc. |
| Azenta US, Inc. |
| Others |
Supply Flow & Price Mechanics
High-throughput instrument depreciation schedules spanning seven-to-ten years anchor capital recovery models while compressing per-run cost floors for consumable-heavy sequencing platforms. This scale dynamic concentrates supply bargaining power among East Asian flow cell manufacturers and fluorescent dye chemistry suppliers, forcing platform vendors to absorb input volatility through reagent contract structures or pass through to hospital laboratory customers.
Pricing Analysis
Consumable pull-through revenue from flow cells and library preparation kits drives lifetime value economics across installed sequencing platforms. Pricing stratifies across premium, standard, and economy tiers based on read length fidelity and FDA clearance status, with clinical-grade assays commanding two-to-three-fold premiums over research-use-only equivalents. Cost compression in the research-tier segment intensifies as Chinese domestic platform vendors enter with aggressive per-run pricing. Academic genome centers exhibit highest price sensitivity, while neonatal intensive care units accept premium positioning for diagnostic certainty.
Supply Chain Analysis
Just-in-time inventory preferences dominate reagent procurement among high-throughput sequencing centers running continuous sample batches, though strategic stockpiling of flow cells persists among clinical laboratories facing Medicare reimbursement deadlines. Manufacturing concentration in China, South Korea, and Japan supplies flow cell substrates, fluorescent dye chemistries, and polymerase enzymes. Single-source dependency for modified nucleotide triphosphates creates vulnerability to export control restrictions. Distribution runs through authorized distributors with cold-chain logistics for temperature-sensitive reagents, supplemented by direct procurement relationships for high-volume hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genome sequencing market sits in early-cycle recovery as Medicare coverage expansion for multi-cancer early detection tests rebuilds demand visibility after reimbursement uncertainty compressed capital deployment.
For Market Incumbents: Consolidate installed base retention through extended service contracts and bioinformatics pipeline integration that raises switching costs for hospital laboratories. Lock in flow cell supply agreements with East Asian chemistry manufacturers to defend margin position against input cost volatility. Prioritize FDA companion diagnostic clearances that tether therapeutic approval pathways to platform-specific assays. For New Entrants and Emerging Players: Anchor in point-of-care deployment archetypes where portable nanopore devices bypass Illumina's centralized laboratory dominance. Target community oncology networks in the United States with minimal residual disease testing workflows that lack established vendor relationships. Pursue go-to-market partnerships with contract research organizations seeking variable-capacity genomics without capital commitment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play sequencing specialists with consumable ecosystems over diversified life science conglomerates with diluted R&D focus. Long-term viability hinges on epigenetic assay expansion and multi-omics integration capabilities rather than hardware commoditization. Watch FDA reimbursement determinations for liquid biopsy platforms as the inflection signal for demand acceleration in community settings.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA accelerated approval tracks shorten validation cycles for tumor-agnostic biomarker assays. |
| Flow Cell Supply Agreement | Long-term contracts with East Asian chemistry manufacturers buffer against reagent cost volatility. |
| Point-of-Care Platform Deployment | Portable nanopore devices penetrate neonatal intensive care units outside academic medical centers. |
| Epigenetic Assay Expansion | Methylation profiling converges with circulating tumor DNA workflows for minimal residual disease detection. |
| Bioinformatics Pipeline Integration | HL7 FHIR implementation reduces electronic health record friction for longitudinal patient tracking. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital laboratory directors, molecular pathologists, pharmaceutical biomarker strategists, and sequencing platform engineers and refined through secondary validation against FDA 510(k) filings, CMS Medicare coverage determinations, ClinicalTrials.gov protocol disclosures, and EMA In Vitro Diagnostic Regulation guidance documents. Bottom-up instrument installation counts and consumable throughput estimates were triangulated against top-down healthcare expenditure flows and pharmaceutical R&D allocation surveys.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension: platform chemistry type, application workflow, end-user procurement authority, and regional reimbursement framework. CAGRs were derived from logistic adoption curves fitted to Medicare coverage expansion timelines and pharmaceutical pipeline companion diagnostic requirements. Forecast inputs incorporate WHO genomic surveillance procurement commitments and national public health laboratory instrument deployment schedules.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and continued FDA accelerated approval pathway availability; material deviation in regulatory timelines or coverage determinations would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
DNA Gene Chip Market
Genomics
UAE Genetic Testing Market
Genomics
Genetic Testing Service Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
DNA Sequencing Services Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Genetic Testing Market
Genomics
Point-Of-Care Genetic Testing Market