
 Global Molecular Cytogenetics Market | 2026-2036
Global Molecular Cytogenetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Cytogenetics Market Foresight
Oncology research is repositioning molecular cytogenetics from a niche diagnostic tool to a standard component of tumor characterization workflows. Thermo Fisher Scientific leverages its chromosomal microarray analysis portfolio to anchor clinical laboratory partnerships across North America. Agilent Technologies sustains technology leadership in fluorescence in situ hybridization probe design through intensive R&D programs. Illumina competes by extending next-generation sequencing integration into cytogenetic interpretation pipelines.
Molecular cytogenetics encompasses techniques that visualize and map genetic material at the chromosomal level, employing fluorescent DNA probes, microarray platforms, and high-resolution imaging systems to detect structural abnormalities, copy number variations, and gene rearrangements with precision measured in kilobase to megabase resolution. These methods serve primary purposes in diagnosing constitutional genetic disorders, characterizing hematologic and solid tumor karyotypes, and guiding therapeutic selection in precision medicine. Fluorescence in situ hybridization dominates current revenue pools due to its established reimbursement and broad laboratory penetration, while comparative genomic hybridization arrays represent the fastest-expanding segment driven by adoption in developmental disorder evaluation and prenatal screening. Karyotyping retains significance in hematologic malignancy workups where whole-genome structural assessment remains clinically essential.
The FDA regulates molecular cytogenetic devices as in vitro diagnostics under premarket notification or approval pathways, with companion diagnostic designations creating stringent analytical validation requirements for oncology applications. EMA's In Vitro Diagnostic Medical Devices Regulation in Europe imposes enhanced conformity assessment procedures that reshape market access timelines for probe manufacturers and platform developers. ISO 15189 accreditation standards govern diagnostic laboratory quality management, directly influencing instrument procurement criteria and reagent supplier selection. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA guidance documents to anticipate validation burden shifts that will determine competitive positioning in transatlantic markets.
Market Dynamics
The molecular cytogenetics market is undergoing a fundamental restructuring as next-generation sequencing platforms absorb traditional cytogenetic workflows, compressing the addressable market for standalone FISH and microarray instruments while elevating analytical validation standards across clinical laboratories.
Growth Catalysts
- FDA Companion Diagnostic Pathway Refinement:The FDA's evolving guidance for oncology companion diagnostics is mandating cytogenetic assay validation for targeted therapy selection, pulling molecular cytogenetics into standard-of-care protocols across academic medical centers.
- Hematologic Malignancy Characterization:Leukemia and lymphoma diagnostic protocols continue to require karyotypic assessment for risk stratification, sustaining instrument replacement cycles in hospital-based laboratories.
- Prenatal Screening Expansion:Non-invasive prenatal testing adoption in the United States and Germany is creating downstream demand for confirmatory cytogenetic analysis using microarray platforms.
Market Restraints
- Fluorophore Supply Concentration:Specialized fluorescent dye production concentrates among a limited supplier base in Switzerland and Germany, exposing reagent costs to input volatility and single-source risk.
- Technical Resolution Ceiling:Conventional FISH probes cannot detect abnormalities below approximately 100 kilobases, creating a diagnostic gap for submicroscopic copy number variations that sequencing platforms address more comprehensively.
- EMA MDR Conformity Burden:Europe's In Vitro Diagnostic Medical Devices Regulation imposes enhanced technical documentation and notified body involvement, extending market access timelines for probe manufacturers by 12-18 months relative to prior directives.
Strategic Opportunities
- Liquid Biopsy Convergence:Integration of circulating tumor DNA analysis with cytogenetic interpretation pipelines enables serial monitoring applications in oncology, opening service revenue streams beyond initial diagnosis.
- India Diagnostic Laboratory Expansion:The country's PLI scheme for medical device manufacturing is attracting platform assembly investment, creating localized supply for a diagnostic market with underpenetrated genetic testing penetration.
- ISO 15189 Accreditation Tailwind:Laboratory quality management standardization across the Middle East and Southeast Asia is forcing instrument procurement upgrades, favoring vendors with integrated compliance documentation.
Industry Challenges
- Cytogeneticist Workforce Contraction:Training program closures in the United Kingdom and United States are reducing the pool of specialists capable of complex karyotype interpretation, creating diagnostic bottlenecks.
- Legacy System Integration Friction:Hospital information systems in Japan and France retain proprietary data formats that resist direct connectivity with modern imaging platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Cytogenetics Market |
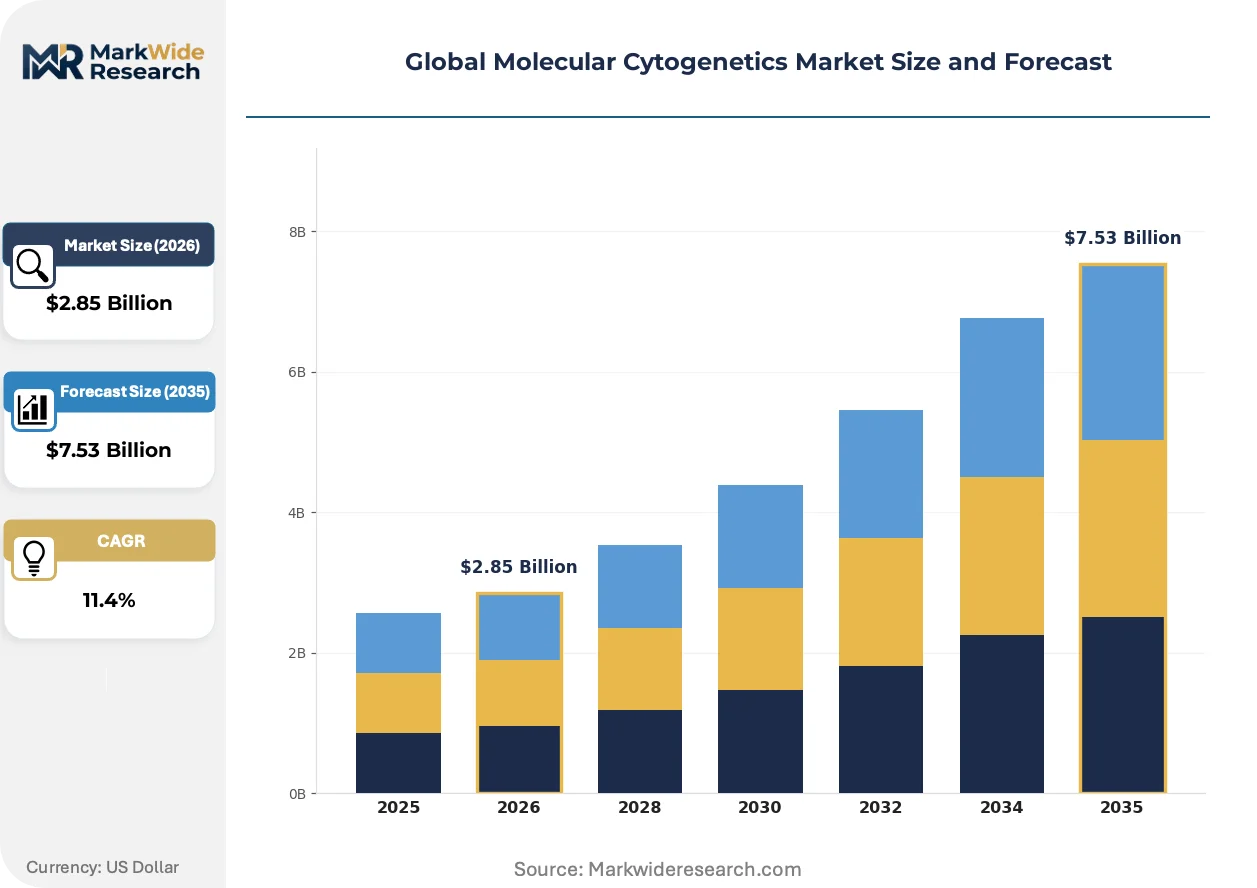
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence In Situ Hybridization, Comparative Genomic Hybridization, Karyotyping, Multiplex Ligation-dependent Probe Amplification Application: Genetic Disorder Diagnosis, Oncology Research, Prenatal Screening, Infectious Disease Analysis, Pharmacogenomics End User: Diagnostic Laboratories, Research Institutes, Academic Centers, Biotechnology Firms Technology: Chromosomal Microarray Analysis, Digital Image Analysis, Automated Scanning Systems, Signal Amplification Techniques |
| Companies Covered | Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Illumina, Inc., F. Hoffmann-La Roche Ltd, Danaher, Abbott, Bio-Rad Laboratories, Inc., PerkinElmer Inc., Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Cytogenetics Market Shifts & Advancements
Sequencing-cytogenetics convergence is collapsing traditional modality boundaries, forcing platform vendors to reposition around interpretive software and laboratory information management rather than instrument hardware alone.
Optical genome mapping is consolidating structural variant detection workflows by delivering megabase-resolution physical maps without culture-dependent sample preparation. Clinical cytogenetics laboratories in the United States and Germany are adopting this technology for constitutional disorder evaluation, displacing conventional karyotyping for cases requiring rapid turnaround. The technology is consolidating vendor competitive position around integrated sample-to-answer platforms that compress the total cost per case.
Europe's MDR and IVDR implementation is fragmentating conformity assessment pathways across notified body capacity constraints. Probe manufacturers face extended technical documentation reviews for fluorescence in situ hybridization reagents, compressing product launch cadences relative to pre-2022 timelines. Germany and France are experiencing the most severe bottlenecks, forcing vendors to prioritize CE-marking submissions by anticipated revenue contribution.
Consolidated purchasing by United States health system networks is compressing supplier margins through multi-year sole-source agreements. Academic medical centers and reference laboratories in California and Texas are aggregating cytogenetic testing volumes under centralized procurement committees, displacing decentralized laboratory autonomy. This concentration is most visible in oncology companion diagnostic contracts, where platforms must demonstrate LIS integration depth to secure preferred vendor status.
Global Molecular Cytogenetics Market Segmentation
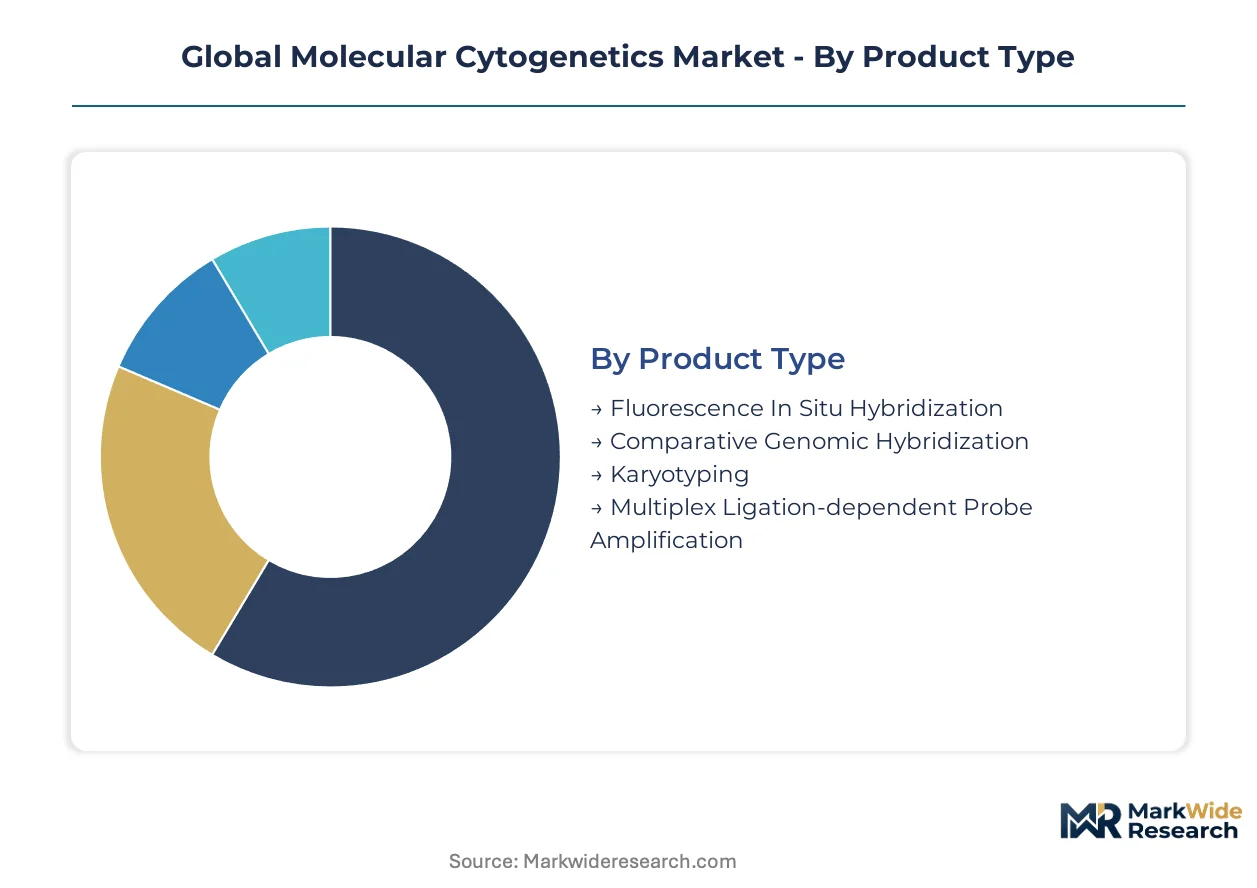
Molecular cytogenetics segmentation reflects divergent technical requirements across clinical and research environments. Product configurations range from standardized probe kits for high-volume screening to customized assay panels for rare disease investigation. Understanding these segment boundaries enables precise capacity planning and pricing architecture.
Product Type:
Customization intensity varies sharply across this category, from commodity reagent workflows to bespoke probe design services.
- Fluorescence In Situ Hybridization:DNA probes labeled with fluorescent dyes hybridize to specific chromosomal targets, enabling visualization of gene amplifications, deletions, and translocations through fluorescence microscopy. Clinical laboratories in the United States deploy FISH panels extensively for HER2 amplification testing in breast cancer and BCR-ABL1 detection in chronic myeloid leukemia, driven by established CPT reimbursement codes and CAP proficiency testing requirements. Most installed capacity flows through Fluorescence In Situ Hybridization. Expansion is steepest in Comparative Genomic Hybridization.
- Comparative Genomic Hybridization:Array-based platforms detect copy number variations across the genome by competitive hybridization of test and reference DNA samples. Germany's university hospitals are accelerating adoption for developmental disorder evaluation and prenatal diagnostic confirmation, supported by statutory health insurance coverage for postnatal microarray testing. The segment climbs fastest as laboratories replace karyotyping for cases requiring submicroscopic resolution.
- Karyotyping:G-banded chromosome analysis remains essential for hematologic malignancy workups requiring whole-genome structural assessment.
- Multiplex Ligation-dependent Probe Amplification:MLPA enables simultaneous detection of multiple target sequences through probe ligation and PCR amplification, serving niche applications in exon-level copy number analysis.
Revenue concentration favors hybridization-based methods. Array platforms gain share in constitutional disorder testing.
Application:
Volume distribution across applications correlates with disease prevalence and reimbursement density rather than technical complexity.
- Oncology Research:Tumor profiling applications dominate absolute spending as academic medical centers integrate cytogenetic platforms into precision medicine protocols. The FDA's companion diagnostic guidance mandates cytogenetic validation for targeted therapy approval, pulling molecular cytogenetics into standard-of-care workflows for lung cancer and hematologic malignancies. Most installed capacity flows through Oncology Research. Expansion is steepest in Prenatal Screening.
- Genetic Disorder Diagnosis:Constitutional cytogenetic evaluation for developmental delay, autism spectrum disorders, and congenital anomalies represents high-test-volume, lower-revenue-per-test segment. United States pediatric genetics clinics are consolidating referral patterns toward regional centers with integrated microarray and sequencing capabilities.
- Prenatal Screening:Confirmatory diagnostic testing following positive non-invasive prenatal screening results is expanding in Germany and the United States as NIPT adoption broadens.
- Infectious Disease Analysis:FISH-based pathogen detection occupies limited clinical niches in immunocompromised patient management.
- Pharmacogenomics:Cytogenetic biomarkers for drug response prediction remain underdeveloped relative to germline variant testing.
Oncology commands premium pricing. Prenatal applications scale through automated platform deployment.
End User:
Procurement sophistication separates institutional buyers, with integrated health systems extracting volume discounts unavailable to standalone facilities.
- Diagnostic Laboratories:Reference laboratories and hospital-based clinical labs generate the majority of reagent consumption through high-throughput screening programs. Quest Diagnostics and LabCorp in the United States are consolidating cytogenetic testing volumes under centralized procurement committees, displacing decentralized laboratory autonomy.
- Research Institutes:Academic and government research centers drive platform innovation adoption, though with elongated sales cycles and grant-dependent purchasing patterns. Germany's Max Planck Institutes and NIH-funded centers in Maryland and California represent concentrated demand for advanced imaging systems.
- Academic Centers:University-affiliated medical centers combine clinical service and research missions, requiring flexible platform configurations.
- Biotechnology Firms:Pharmaceutical and diagnostic developers purchase cytogenetic platforms for companion diagnostic development and cell line characterization.
Laboratory consolidation favors vendors with LIS integration depth. Research procurement remains fragmented.
Technology:
Platform automation levels determine labor cost structures and throughput scalability across customer segments.
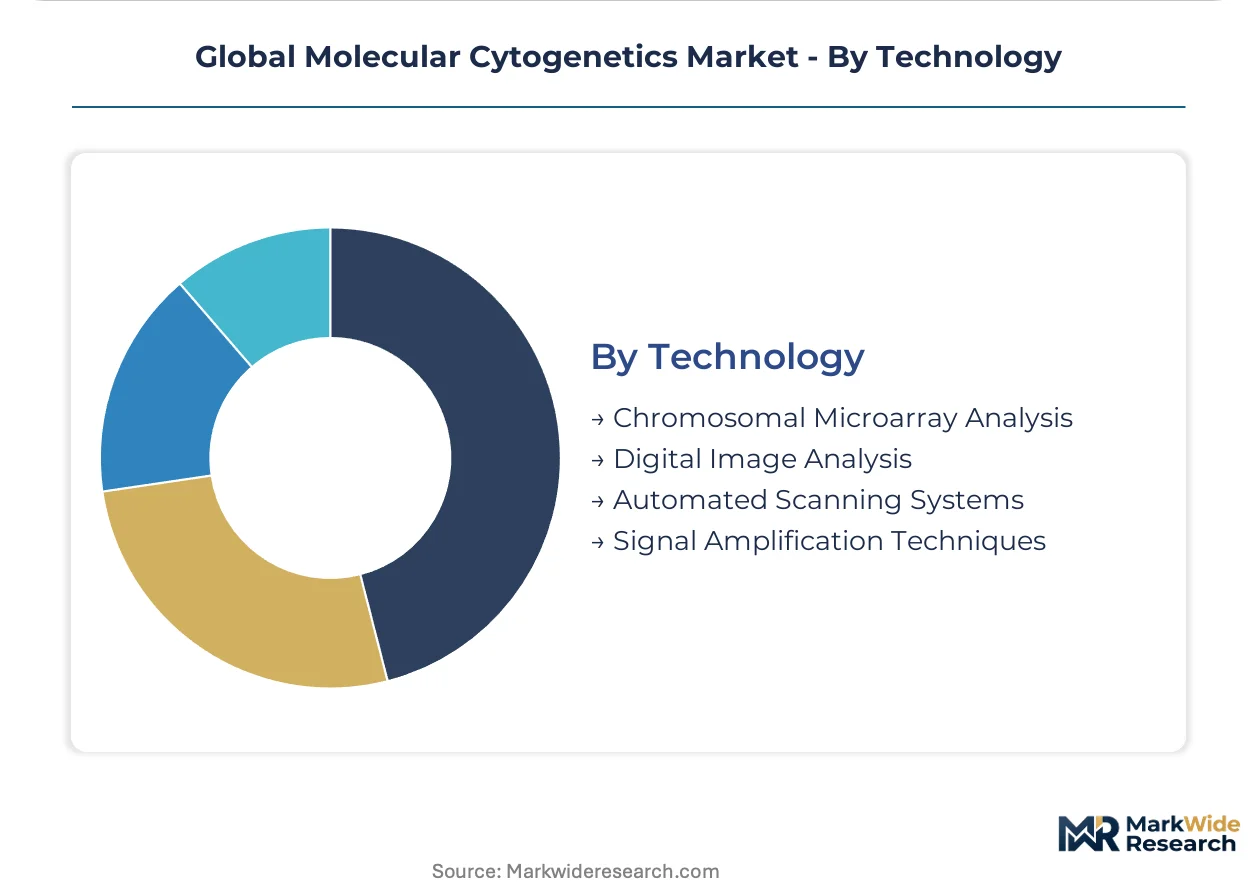
- Chromosomal Microarray Analysis:High-density oligonucleotide arrays enable genome-wide copy number and single nucleotide polymorphism detection with resolution approaching 5-10 kilobases. United States clinical laboratories are retiring older array platforms for updated designs with enhanced coverage of clinically relevant regions.
- Digital Image Analysis:Automated karyotype reconstruction and FISH signal enumeration reduce cytogeneticist interpretation burden. Japan's clinical laboratories face integration friction with proprietary hospital information system formats, requiring costly middleware development.
- Automated Scanning Systems:Slide-based imaging platforms enable unattended acquisition of metaphase spreads and interphase nuclei.
- Signal Amplification Techniques:Tyramide signal amplification and branched DNA methods enhance detection sensitivity for low-copy targets.
Digital analysis platforms displace manual workflows. Array technology faces substitution pressure from sequencing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping molecular cytogenetics manufacturing as vendors relocate production to jurisdictions with streamlined IVD approval pathways, exploiting the compliance cost differential between the FDA's premarket notification process and Europe's extended MDR conformity assessments.
United States
Academic medical centers in California and Texas are consolidating cytogenetic testing volumes under centralized procurement committees, extracting multi-year sole-source agreements from platform vendors. FDA companion diagnostic pathway refinement mandates cytogenetic assay validation for targeted therapy selection, pulling molecular cytogenetics into standard-of-care protocols. The NIH-funded research corridor spanning Maryland and Virginia anchors platform innovation adoption for advanced imaging systems.
Germany
University hospitals are accelerating comparative genomic hybridization adoption for developmental disorder evaluation and prenatal diagnostic confirmation, supported by statutory health insurance coverage for postnatal microarray testing. EMA's In Vitro Diagnostic Medical Devices Regulation imposes enhanced technical documentation and notified body involvement, extending market access timelines for probe manufacturers. The Max Planck Institutes cluster in Bavaria and Baden-Württemberg concentrates demand for high-resolution cytogenetic research platforms.
India
The country's PLI scheme for medical device manufacturing is attracting platform assembly investment, creating localized supply for a diagnostic market with underpenetrated genetic testing penetration. CDSCO regulatory harmonization with FDA guidance documents is accelerating clinical validation requirements for imported cytogenetic assays. Maharashtra and Karnataka host emerging diagnostic laboratory networks expanding molecular cytogenetic service capacity.
Japan
Clinical laboratories face integration friction between proprietary hospital information system formats and modern imaging platforms, requiring costly middleware development from vendors seeking market entry. PMDA regulatory pathways for IVD devices maintain stringent analytical validation standards that compress supplier margins. The Kanto region surrounding Tokyo concentrates hematologic malignancy diagnostic volume in hospital-based laboratories.
Switzerland
Specialized fluorescent dye production concentrates among limited suppliers in Basel and Zurich, exposing reagent costs to input volatility and single-source risk for global probe manufacturers. Swissmedic maintains rigorous conformity assessment procedures that align with EMA MDR implementation timelines. The country's precision chemical manufacturing base anchors fluorophore supply chains serving FISH reagent producers worldwide.
Global Molecular Cytogenetics Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform vendors reposition around interpretive software and laboratory information management rather than instrument hardware alone. The vendor base fragments across three tiers: multinational conglomerates with diversified life science portfolios, specialized cytogenetics firms with probe design expertise, and emerging optical genome mapping specialists. Two archetypes command attention: integrated platform providers bundling reagents with analytical software, and niche probe manufacturers serving customized assay development. Competitive moves concentrate on sequencing-cytogenetics convergence and LIS integration depth to secure preferred vendor status in consolidated purchasing environments.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc., Agilent Technologies, Inc., and Illumina, Inc. exemplify contrasting strategic positions. Thermo Fisher Scientific occupies the integrated platform provider archetype, anchoring clinical laboratory partnerships through chromosomal microarray analysis portfolios. Agilent Technologies represents the specialized probe design tradition, sustaining technology leadership in fluorescence in situ hybridization through intensive R&D programs. Illumina sits within the sequencing convergence vector, competing by extending next-generation sequencing integration into cytogenetic interpretation pipelines.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| F. Hoffmann-La Roche Ltd |
| Danaher |
| Abbott |
| Bio-Rad Laboratories, Inc. |
| PerkinElmer Inc. |
| Revvity |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up diagnostic platform specialists have consolidated reagent manufacturing footprints across Switzerland and Germany, creating captive supply discipline that anchors premium pricing for fluorescence in situ hybridization probes while compressing margins for non-integrated distributors in the United States and India.
Pricing Analysis
Distributor margin layers in clinical laboratory supply chains absorb 15-25 points before reaching hospital-based buyers, with direct-to-reference-laboratory contracts commanding steeper discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated companion diagnostic assays from research-use-only reagents and unbranded alternatives. Cost compression in the economy tier is intensifying because Indian diagnostic networks are localizing platform assembly under PLI scheme incentives. Academic medical centers in California and Texas demonstrate the lowest price sensitivity, while standalone pathology laboratories in emerging markets resist premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Quest Diagnostics and LabCorp in the United States, while specialized distributors serve fragmented research institute procurement in Germany and Japan. Fluorophore production concentrates in Switzerland and Germany, with array manufacturing anchored in the United States and China. Specialized fluorescent dyes, oligonucleotide libraries, and high-resolution imaging sensors constitute critical input dependencies. Single-source vulnerability in Basel-based dye suppliers exposes global probe manufacturers to input volatility. Distribution runs through regional laboratory supply consortia with stringent ISO 15189 compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Molecular Cytogenetics Market functions as a stable compounder, with FDA companion diagnostic pathway refinement creating durable pull-through demand for validated cytogenetic assays across academic medical centers.
For Market Incumbents: Anticipate sequencing-cytogenetics convergence by deepening interpretive software capabilities and securing LIS integration contracts with consolidated United States health system networks. Optical genome mapping specialists threaten displacement of conventional karyotyping in constitutional disorder evaluation. Backward integration into fluorophore supply through Swiss manufacturing partnerships defends margin position against dye cost volatility. For New Entrants and Emerging Players: Begin with optical genome mapping platform deployment in German university hospitals, where statutory health insurance coverage for microarray testing validates reimbursement pathways. India's underpenetrated genetic testing infrastructure offers the most penetrable geography for platform assembly investment under PLI scheme incentives. CDSCO regulatory harmonization with FDA guidance documents provides a streamlined go-to-market angle for imported assay validation. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized probe manufacturers with intensive R&D programs but limited software integration depth, as platform vendors capture premium multiples for LIS-connected offerings. The five-to-ten year viability window favors integrated sample-to-answer providers over standalone reagent suppliers. Watch FDA companion diagnostic designation velocity as the inflection indicator for cytogenetic assay revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Genome Mapping Platform Deployment | Consolidates structural variant detection workflows in United States and German clinical laboratories. |
| CDSCO Regulatory Harmonization Pathway | Accelerates clinical validation requirements for imported cytogenetic assays entering India. |
| LIS Integration Depth Investment | Secures preferred vendor status with centralized procurement committees in Texas and California. |
| Fluorophore Supply Backward Integration | Reduces single-source exposure to Swiss dye manufacturers for global probe producers. |
| Companion Diagnostic Validation Program | Aligns cytogenetic assay development with FDA oncology guidance for targeted therapy selection. |
Research Methodology
Multiple input streams — primary interviews with cytogenetic laboratory directors, regulatory affairs specialists at probe manufacturers, and hospital procurement managers — were reconciled against secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, and ISO 15189 accreditation databases. Conversations with biomedical engineers at academic medical centers in Maryland and California, GPO contracts managers at United States reference laboratories, and platform sales directors at German university hospitals informed demand-side assumptions. Bottom-up instrument installation counts and top-down reagent revenue estimates were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, application, technology, and end-user dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate blending weighted by current revenue contribution. FDA companion diagnostic designation timelines, EMA MDR conformity assessment bottlenecks, and PLI scheme uptake velocity in India served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including disruptive sequencing cost curves that could accelerate substitution beyond projected rates, and workforce contraction in cytogeneticist training programs that may create diagnostic bottlenecks. Forecasts reflect assumptions about regulatory harmonization stability and reimbursement code maintenance. Periodic stress-testing of base assumptions against fluorophore supply disruptions and health system consolidation velocity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Europe Whole Exome Sequencing Market
Genomics
Oligonucleotide Pool Market
Genomics
SNP Genotyping Market
Genomics
DNA Mass Ladder Market
Genomics
Immunogenetics Market
Genomics
Whole Genome Amplification Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Personal Genome Testing Market
Genomics
Europe Digital PCR Market
Genomics
Prenatal Genetic Testing Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Global Pharmacogenomics Market
Genomics
AI in Genomics Market
Genomics
Genomics Personalized Health Market
Genomics
Global Microbiome Sequencing Services Market