
 Forensic Genomics Market | 2026-2036
Forensic Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Forensic Genomics Market Intelligence
Buyer concentration among law enforcement agencies is hardening as national DNA database programs consolidate procurement authority under centralized forensic service providers. Illumina Inc. leverages its installed base of sequencing platforms to sustain recurring reagent revenue across government crime laboratories. Thermo Fisher Scientific Inc. competes through integrated sample-to-answer workflow systems that reduce turnaround time for evidentiary samples. QIAGEN anchors its position in automated DNA extraction, a bottleneck step where standardization reduces cross-laboratory variability.
Forensic genomics applies DNA analysis technologies to human identification for legal and investigative purposes, encompassing short tandem repeat profiling, single nucleotide polymorphism analysis, and mitochondrial sequencing with sensitivity thresholds below one nanogram of template DNA. Next-generation sequencing technology displaces capillary electrophoresis in criminal investigation applications by enabling simultaneous analysis of forensically relevant genetic markers from degraded or mixed-source samples. Reagents and kits capture the largest share of product type revenue due to consumable replenishment cycles tied to caseload volume, while software segments expand through probabilistic genotyping tools that interpret complex DNA mixtures. Instruments face longer replacement cycles but command higher capital commitment per unit, concentrating margin pools among vendors with captive reagent ecosystems.
The FBI CODIS program and state-level accreditation requirements under FBI Quality Assurance Standards shape procurement specifications for U.S. forensic laboratories. The European Network of Forensic Science Institutes enforces ENFSI guidelines that harmonize method validation across member countries, creating compliance barriers for non-validated platforms. The U.S. Department of Justice's Rapid DNA initiative and proposed legislative expansions of arrestee sampling authority will determine whether point-of-booking instruments penetrate local police operations or remain confined to centralized laboratories.
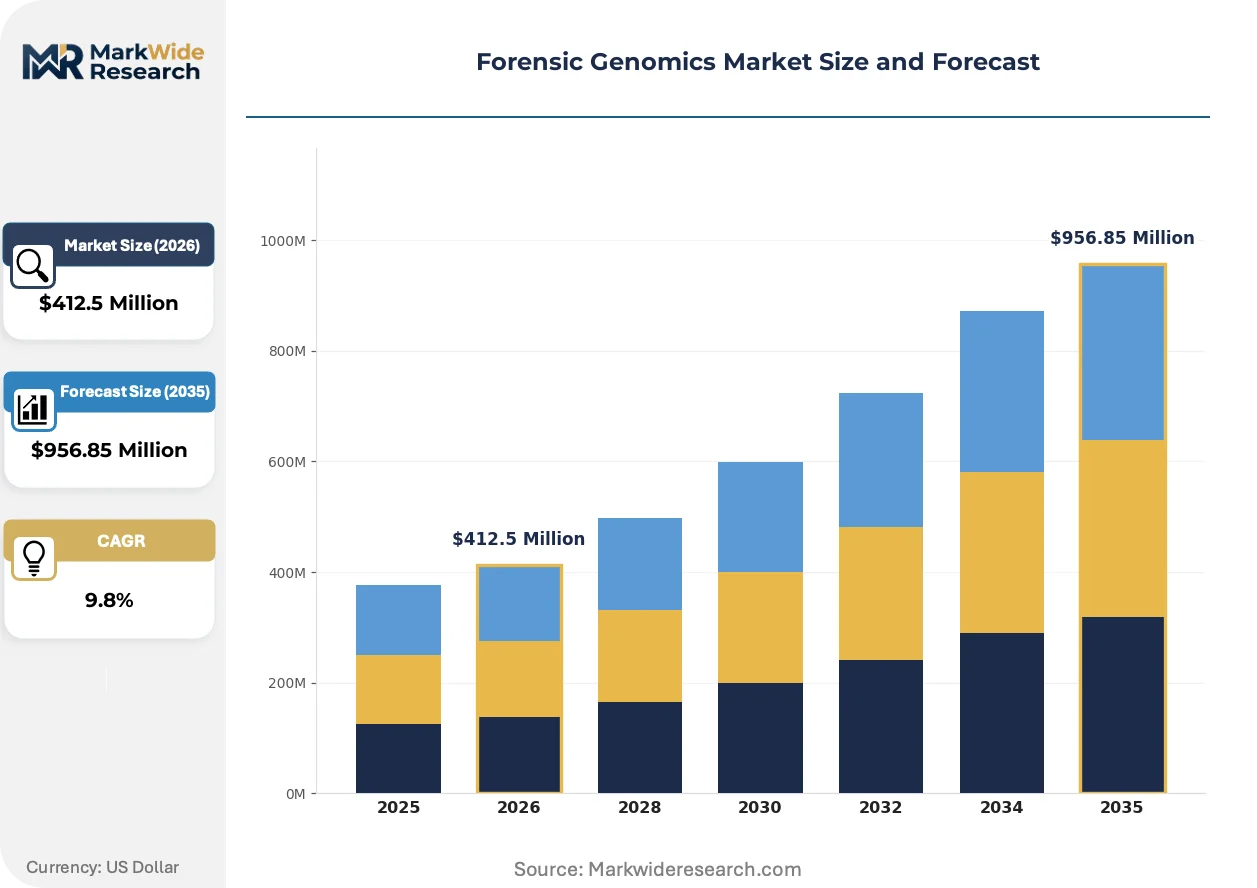
Market Dynamics
The migration from capillary electrophoresis to next-generation sequencing platforms is compressing instrument replacement cycles and reshaping vendor lock-in dynamics across government crime laboratories.
Growth Catalysts
- FBI CODIS Expansion:Federal funding for state DNA database infrastructure drives standardized procurement specifications and accelerates platform upgrades in U.S. forensic laboratories.
- Degraded Sample Recovery:Single nucleotide polymorphism analysis enables genetic identification from skeletal remains and environmental exposures that defeat traditional short tandem repeat methods.
- Probabilistic Genotyping Software:Advanced statistical interpretation tools resolve complex DNA mixtures from multiple contributors, expanding evidentiary utility in sexual assault and homicide casework.
Market Restraints
- Capital Intensity:Next-generation sequencing platforms require substantial upfront investment in instrumentation, bioinformatics infrastructure, and personnel training that constrains smaller regional laboratories.
- Validation Burden:FBI Quality Assurance Standards mandate extensive method validation studies that extend deployment timelines and increase compliance costs for new technology adoption.
- Reagent Dependency:Closed consumable ecosystems tied to specific instrument vendors limit price competition and create supply vulnerability during manufacturing disruptions.
Strategic Opportunities
- Rapid DNA at Booking:Point-of-arrest genetic identification systems could penetrate local law enforcement operations if legislative expansions of arrestee sampling authority proceed.
- Phenotypic Inference:Forensic DNA phenotyping for externally visible characteristics creates new investigative leads when database matches fail, though regulatory frameworks remain unsettled.
- Disaster Victim Identification:Mass casualty events and humanitarian emergencies drive demand for portable sequencing capabilities and international sample exchange protocols.
Industry Challenges
- Bioinformatics Expertise Gap:Shortage of analysts trained in probabilistic genotyping and mixture interpretation creates operational bottlenecks and extends report turnaround times.
- Interoperability Friction:Proprietary data formats and analysis pipelines complicate evidence sharing between laboratories using different vendor platforms.
- Quality Assurance Workforce:Compliance with accreditation standards requires dedicated technical leaders that smaller agencies struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forensic Genomics Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Software, Instruments Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing Application: Criminal Investigation, Paternity Testing, Missing Persons Identification, Disaster Victim Identification End User: Law Enforcement Agencies, Laboratories, Research Institutions, Government Agencies |
| Companies Covered | Verogen Inc., Danaher Corporation, Thermo Fisher Scientific Inc., GE HealthCare, F. Hoffmann-La Roche Ltd., Illumina Inc., QIAGEN, Eurofins Discovery, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forensic Genomics Market Strategic Shifts & Innovations
Forensic genomics is experiencing platform consolidation, regulatory harmonization pressures, and procurement centralization that favor vendors with integrated workflow capabilities over point-solution specialists.
Next-generation sequencing is consolidating analytical workflows previously split across multiple instruments. Capillary electrophoresis systems for short tandem repeat analysis, Sanger sequencing for mitochondrial DNA, and targeted PCR assays for single nucleotide polymorphisms are yielding to unified platforms. Major state crime laboratories in the United States are completing multi-year validation studies. This consolidation reduces laboratory footprint and standardizes interpretation protocols across evidentiary sample types.
The European Network of Forensic Science Institutes is harmonizing method validation requirements through ENFSI guidelines that create compliance barriers for non-validated platforms. Member countries must demonstrate equivalent performance to reference methods before adopting new technologies. Laboratories in Germany, the Netherlands, and the United Kingdom are coordinating parallel validation studies. This regulatory alignment favors established vendors with resources to navigate multi-jurisdictional approval processes.
Buyer concentration among centralized forensic service providers is compressing vendor negotiation leverage. National DNA database programs in the United States, United Kingdom, and Australia are consolidating procurement authority under umbrella purchasing agreements. Regional laboratories lose autonomy to select platforms based on local preferences. This shift rewards vendors offering comprehensive service contracts and penalizes specialists lacking field support infrastructure.
Forensic Genomics Market Segmentation
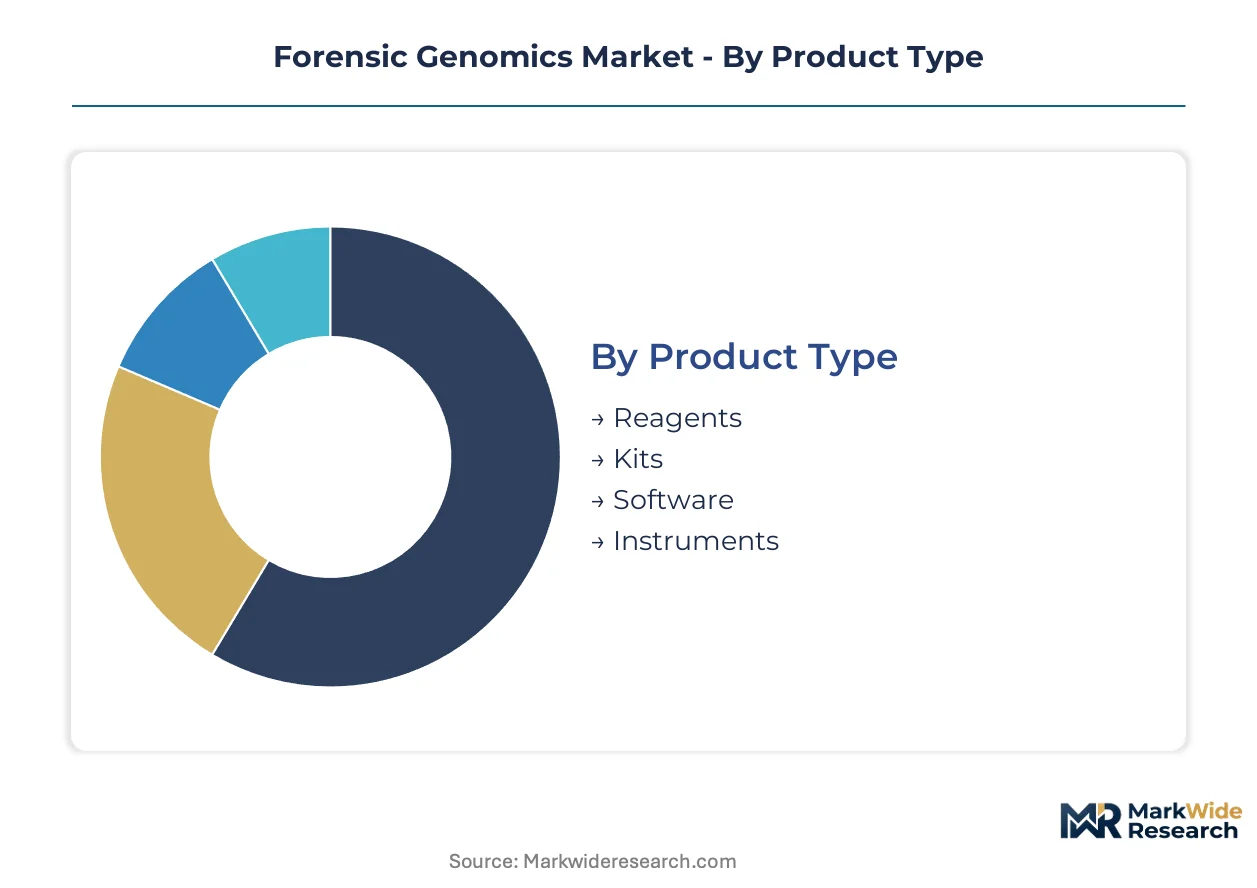
Forensic genomics segmentation reveals how procurement authority concentrates among centralized laboratories while technology transitions reshape vendor economics across product categories. Distinct demand profiles emerge between high-throughput criminal casework operations and specialized identification applications.
Product Type:
Consumables dominate transaction volume while instruments anchor capital commitment, creating divergent margin structures across the procurement cycle.
- Reagents:Enzymatic preparations, nucleotides, and buffer solutions consumed during DNA extraction, amplification, and sequencing workflows. FBI CODIS-funded state laboratories in the United States drive replenishment volumes through sustained caseload processing, though reagent dependency on proprietary instrument ecosystems limits supplier switching.
- Kits:Pre-formulated assay panels containing primers, probes, and master mixes for targeted forensic marker analysis. European Network of Forensic Science Institutes validation requirements favor kit manufacturers with multi-jurisdictional approval documentation, compressing market access for newer entrants.
- Software:Probabilistic genotyping platforms and laboratory information management systems. Interpretation tools for complex DNA mixture deconvolution face extended validation timelines under FBI Quality Assurance Standards.
- Instruments:Sequencing platforms, capillary electrophoresis systems, and automated extraction workstations. Replacement cycles compress as next-generation sequencing displaces legacy PCR infrastructure.
Today's leader: Reagents. Tomorrow's challenger: Software.
Technology:
Platform transitions favor integrated analytical capabilities over discrete methodological specializations.
- Next-Generation Sequencing:Massively parallel sequencing platforms enabling simultaneous analysis of short tandem repeats, single nucleotide polymorphisms, and mitochondrial markers from single-source samples. United Kingdom Forensic Science Service and Netherlands Forensic Institute lead European validation efforts for unified workflow adoption.
- PCR:Polymerase chain reaction amplification of targeted DNA regions for capillary electrophoresis sizing. Smaller regional laboratories in Australia and Canada retain PCR infrastructure for cost-constrained operations with lower sample throughput.
- Microarray:Solid-phase hybridization platforms for high-throughput single nucleotide polymorphism screening. Research applications predominate as forensic validation remains limited.
- Sanger Sequencing:Chain-termination method for mitochondrial DNA analysis and sequence confirmation. Specialized applications in degraded skeletal remains identification sustain niche demand.
Next-generation sequencing expands most quickly across major government crime laboratories.
Application:
Criminal casework generates recurring revenue while episodic identification events create demand spikes.
- Criminal Investigation:DNA profiling of biological evidence from violent crimes, property offenses, and cold case reviews. Sexual assault kit backlogs in United States state laboratories sustain high-throughput processing demand.
- Paternity Testing:Relationship verification for immigration, inheritance, and civil proceedings. Commercial laboratory networks compete with government providers in jurisdictions permitting private sector participation.
- Missing Persons Identification:Kinship analysis and direct reference sample comparison for unresolved disappearances. Argentina's national genetic database program exemplifies sustained government commitment.
- Disaster Victim Identification:Mass casualty genetic identification requiring rapid sample processing and international data exchange. International Committee of the Red Cross protocols standardize cross-border collaboration.
Criminal investigation commands current procurement budgets; disaster victim identification presents episodic expansion potential.
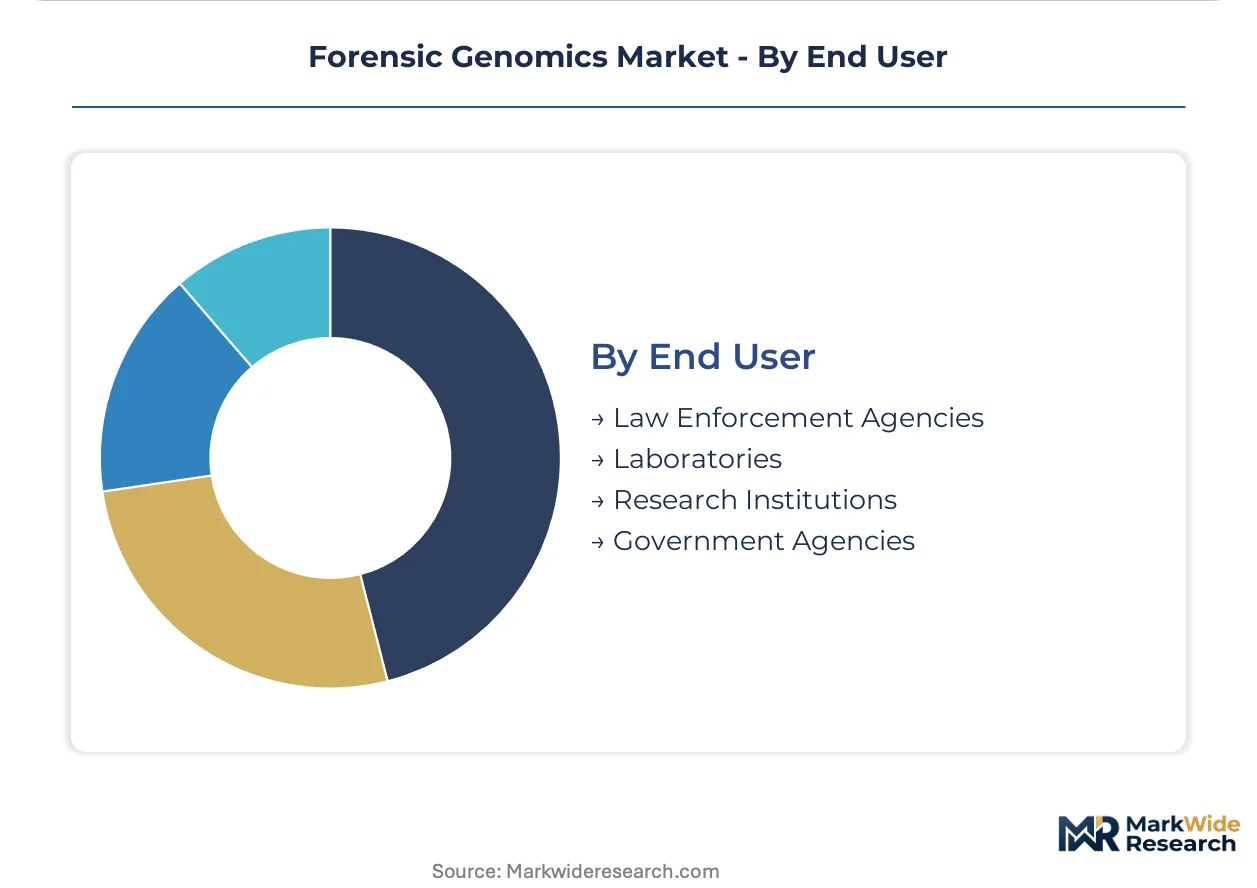
End User:
Centralized procurement authority is compressing vendor negotiation leverage across buyer categories.
- Law Enforcement Agencies:Police departments and sheriff's offices operating point-of-arrest Rapid DNA systems or submitting evidence to external laboratories. United States Department of Justice funding priorities determine local adoption timelines.
- Laboratories:Accredited forensic service providers performing DNA analysis under FBI Quality Assurance Standards or ENFSI guidelines. Consolidated purchasing agreements in Australia and the United Kingdom reduce individual laboratory autonomy.
- Research Institutions:Academic centers developing novel analytical methods and population genetic databases. Grant-funded validation studies precede operational deployment in government facilities.
- Government Agencies:National DNA database administrators and policy-setting bodies including FBI CODIS and Interpol DNA monitoring units. Regulatory specifications cascade through downstream procurement requirements.
Laboratories currently dominate instrument procurement; law enforcement agencies represent the emerging point-of-need frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates forensic genomics procurement through FBI CODIS expansion, while Germany enforces ENFSI validation standards that shape European technology adoption timelines.
United States
FBI CODIS database growth and sexual assault kit backlog processing drive sustained instrument procurement across state crime laboratories. The Department of Justice Rapid DNA initiative shapes point-of-arrest technology deployment. Texas and California state forensic systems anchor high-throughput sequencing adoption through centralized purchasing agreements.
Germany
ENFSI guideline compliance requirements and federal police DNA database expansion sustain demand for validated analytical platforms. The Federal Criminal Police Office (BKA) coordinates multi-state validation studies for next-generation sequencing adoption. Bavaria's forensic science institutes lead European method standardization efforts alongside Netherlands and United Kingdom counterparts.
United Kingdom
Forensic Science Service restructuring and Home Office DNA database investments concentrate procurement authority under national frameworks. The UK Accreditation Service (UKAS) enforces ISO/IEC 17025 standards for forensic testing laboratories. London and Birmingham forensic hubs drive platform consolidation through umbrella service contracts.
Australia
National Criminal Investigation DNA Database (NCIDD) expansion and state police forensic service consolidation shape instrument procurement. The National Association of Testing Authorities (NATA) accreditation requirements filter technology adoption. New South Wales and Victoria state laboratories anchor high-volume criminal casework processing demand.
Netherlands
Netherlands Forensic Institute (NFI) validation leadership and European cross-border data sharing protocols sustain specialized technology demand. The Dutch Ministry of Justice and Security funds DNA database infrastructure expansion. The Hague forensic science cluster coordinates ENFSI-wide method harmonization studies.
Forensic Genomics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and software segments. The vendor base stratifies between integrated workflow providers and point-solution specialists. Three archetypes dominate: sequencing platform incumbents with captive reagent ecosystems, sample-to-answer system integrators, and bioinformatics software specialists. Competitive positioning hinges on multi-year service contracts and regulatory validation documentation rather than unit pricing alone.
Within the integrated workflow tier, Thermo Fisher Scientific Inc. and Danaher Corporation represent diversified life science conglomerates with forensic application portfolios. Illumina Inc. anchors the sequencing platform segment. QIAGEN exemplifies the sample preparation specialist archetype with automated extraction systems.
| Leading Market Players |
|---|
| Verogen Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| GE HealthCare |
| F. Hoffmann-La Roche Ltd. |
| Illumina Inc. |
| QIAGEN |
| Eurofins Discovery |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Next-generation sequencing platform consolidation simultaneously compresses per-sample cost economics and concentrates procurement leverage among centralized forensic service providers. FBI CODIS-funded state laboratories in the United States negotiate multi-year reagent supply agreements that lock in volume discounts while constraining supplier switching.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for validated forensic kits across European markets. Three-tier pricing structure across premium, standard, and economy levels reflects FBI Quality Assurance Standards certification tier and after-sales technical support bundling. Pricing pressure stems from reagent dependency on proprietary instrument ecosystems that limit competitive bidding. Smaller regional laboratories exhibit highest price sensitivity due to constrained capital budgets, while national DNA database programs command lowest unit costs through consolidated purchasing authority.
Supply Chain Analysis
FBI Quality Assurance Standards and ENFSI guideline compliance create qualification gating that filters supplier participation. Manufacturing concentrates in the United States, Germany, and China for sequencing platforms, extraction automation, and consumable production. Supply chains draw from semiconductor components, optical detection modules, and enzymatic reagent formulations. Single-source vulnerability persists for proprietary flowcell technologies. Distribution runs through direct government procurement channels and specialized life science distributors serving accredited forensic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forensic genomics functions as a stable compounder anchored by recurring reagent consumption tied to criminal caseload processing and DNA database expansion mandates.
For Market Incumbents: Anchor defensive positioning through captive reagent ecosystems that increase switching costs for government crime laboratories. Deepen backward integration into nucleotide and enzyme production to mitigate supply disruption exposure. Counter emerging rapid DNA point-of-need systems by embedding service contracts that extend platform replacement cycles. For New Entrants and Emerging Players: The mid-market price-point gap between Illumina premium sequencing systems and economy-tier PCR infrastructure creates white-space opportunity. Target underpenetrated state laboratories in Australia and Canada with validated kit offerings that reduce method development burden. Pursue go-to-market partnerships with existing forensic service providers lacking in-house bioinformatics capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among automated sample preparation specialists with ENFSI validation documentation. Five-to-ten year viability rests on recurring consumable revenue streams rather than instrument replacement cycles. Monitor FBI legislative expansions of arrestee sampling authority as the signal indicating rapid DNA market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ENFSI Validation Documentation Investment | Multi-jurisdictional approval unlocks European procurement channels across Germany, Netherlands, and United Kingdom. |
| Reagent Ecosystem Expansion | Consumable lock-in secures recurring revenue from FBI CODIS-funded state laboratory operations. |
| Rapid DNA Platform Development | Point-of-arrest instrumentation penetrates local law enforcement if legislative sampling authority expands. |
| Probabilistic Genotyping Software Licensing | Advanced mixture interpretation tools address sexual assault kit backlog processing demand. |
| Forensic Phenotyping Capability Buildout | Externally visible characteristic inference creates new investigative lead generation revenue stream. |
Research Approach
Bottom-up law enforcement agency modeling reconciled against top-down sequencing platform shipment tracking forms the analytical core of this study. Primary interviews with forensic laboratory directors, DNA technical leaders, government procurement officers, and bioinformatics specialists combined with secondary validation from FBI CODIS program documentation, ENFSI guideline publications, and state budget appropriation records. Triangulation across instrument vendor disclosures and accredited laboratory certification databases ensures demand-side and supply-side alignment.
Input-output matrices map reagent consumption rates to criminal caseload volumes across the projection horizon. Segmentation dimensions include product type, technology platform, application category, and end-user archetype. CAGRs derive from regression analysis of historical procurement cycles and policy-driven database expansion trajectories. Forecast inputs incorporate sexual assault kit backlog clearance timelines and Rapid DNA legislative authorization probability assessments.
Caveats apply where FBI funding appropriation delays or ENFSI validation timeline extensions could materially shift the outlook. Forecasts reflect assumptions regarding sustained law enforcement DNA database investment and technology platform consolidation trajectories. A model refresh is warranted upon material change in federal procurement authorization or international method harmonization protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Molecular Breeding Market
Genomics
Short-Read Sequencing Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Mitochondrial DNA Market
Genomics
Global Metagenomics Market
Genomics
Global Nutrigenomics Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
DNA Mass Ladder Market
Genomics
Dna Polymerase Market
Genomics
NGS Automation Market
Genomics
Gene Sequencing Market
Genomics
North America DNA Sequencing Products Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Europe DNA Sequencing Products Market