
 Global Single-Cell Genome Sequencing Market | 2026-2036
Global Single-Cell Genome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single-Cell Genome Sequencing Market Foresight
Next-generation sequencing integration with droplet microfluidics is reconfiguring how single-cell genomic data is generated at scale. 10x Genomics leverages its Chromium platform architecture to dominate commercial droplet-based workflows. Illumina sustains instrument placement across core sequencing facilities worldwide. Oxford Nanopore Technologies differentiates through long-read single-cell applications that bypass amplification bias.
Single-cell genome sequencing isolates individual cells to profile genomic variation—copy number, structural variants, or mutations—at single-cell resolution, typically requiring picogram-scale DNA amplification and library preparation prior to sequencing. The technology serves cancer heterogeneity studies, developmental lineage tracing, and microbial ecology where bulk sequencing obscures cellular diversity. Droplet-based sequencing leads commercial volume due to throughput economics, while nanopore sequencing captures fastest growth in structural variant detection. Sequencing kits and library preparation reagents concentrate margin pools because consumables drive recurring revenue per instrument installed base.
FDA oversight of laboratory-developed tests shapes diagnostic commercialization pathways for single-cell assays in the United States, while EMA's In Vitro Diagnostic Regulation in Europe raises compliance barriers for kit manufacturers seeking CE marking. China's NMPA accelerates review pathways for innovative sequencing instruments under priority review channels. Stakeholders must monitor regulatory divergence between jurisdictions when designing multi-region clinical validation strategies.
Market Dynamics
Droplet microfluidics consolidation around Chromium-class platforms is compressing instrument margins while consumables capture recurring revenue pools. Academic core facilities now standardize on workflow-integrated solutions that lock in reagent spend.
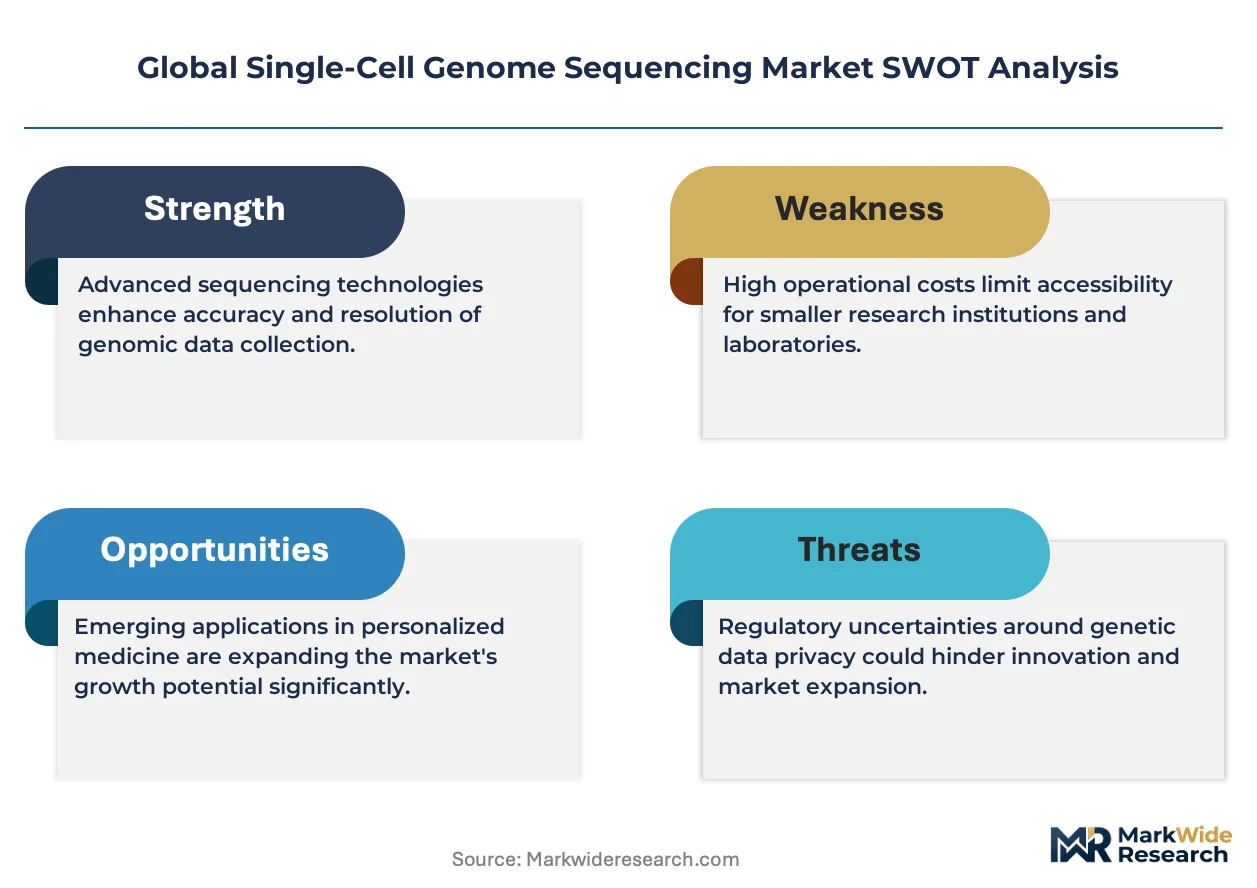
Growth Catalysts
- NMPA Priority Review:China's accelerated pathways for innovative sequencing instruments reduce time-to-market for droplet-based platforms entering clinical research.
- Cancer Immunology Workflows:Academic institutes expand single-cell adoption for tumor microenvironment profiling, driving kit volume through core facility centralization.
- CRISPR-Compatible Protocols:Library preparation innovations that integrate perturbation screening with genomic readout are expanding experimental design possibilities in functional genomics.
Market Restraints
- Illumina Instrument Concentration:Sequencing hardware dependency on a dominant supplier creates supply vulnerability and limits negotiation leverage for core facilities.
- Picogram-Scale Amplification Costs:Whole-genome amplification reagents and specialized polymerases constitute 40-60% of per-cell processing expense, constraining large cohort studies.
- EMA IVDR Compliance Burden:European kit manufacturers face extended validation timelines and notified body bottlenecks for CE marking of research-use-only products.
Strategic Opportunities
- Long-Read Structural Variant Detection:Nanopore sequencing convergence with single-cell isolation is opening clinical cytogenetics applications currently underserved by short-read platforms.
- Germany's Bioeconomy Strategy:Federal funding for precision medicine infrastructure creates instrument placement opportunities in Heidelberg and Munich research clusters.
- Microbial Single-Cell Genomics:Uncultured organism profiling in environmental and infectious disease research represents a greenfield application with limited incumbent competition.
Industry Challenges
- Bioinformatics Pipeline Integration:Core facilities struggle to hire computational biologists capable of deploying cellranger-class workflows, creating service bottlenecks.
- Multi-Jurisdictional Validation:Kit manufacturers must run parallel FDA LDT and EMA IVDR studies, duplicating clinical sample requirements and extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single-Cell Genome Sequencing Market |
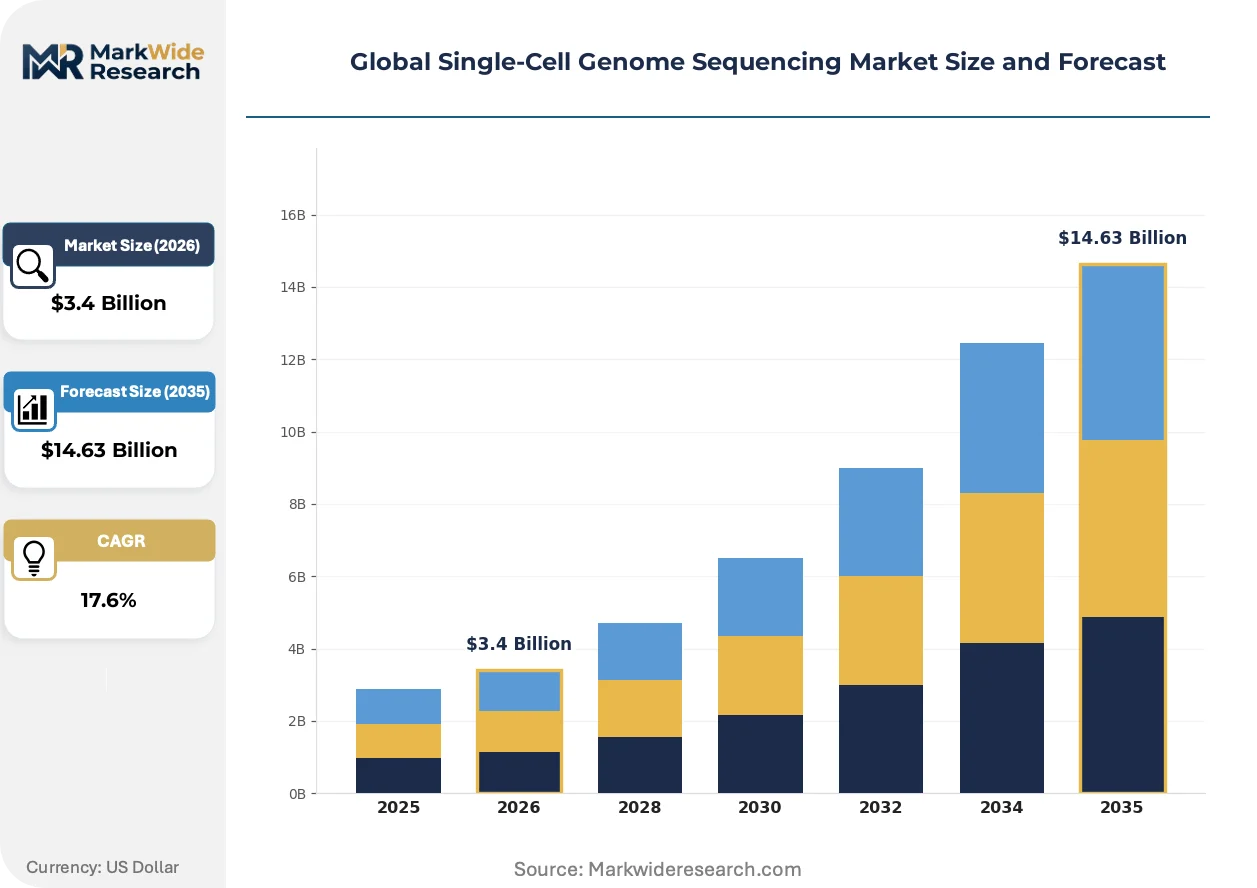
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $14.63 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics Platforms, Sequencing Kits, Library Preparation Reagents, Amplification Systems, Microarrays Technology: Next-Generation Sequencing, Droplet-Based Sequencing, Imaging-Based Sequencing, Nanopore Sequencing, Digital PCR Application: Cancer Research, Developmental Biology, Immunology Studies, Neuroscience Research, Microbial Analysis End User: Academic Research Institutes, Pharmaceutical & Biotechnology Companies, Diagnostic Laboratories, Contract Research Organizations |
| Companies Covered | 10x Genomics, Illumina, Thermo Fisher Scientific, BD Biosciences, QIAGEN, Oxford Nanopore Technologies, Bio-Rad Laboratories, Standard BioTools (Fluidigm), Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single-Cell Genome Sequencing Market Shifts & Advancements
Single-cell workflows are fragmenting into specialized modalities that trade breadth for resolution, with platform economics favoring integrated consumable-instrument bundles over open systems.
Combinatorial indexing methods that eliminate microfluidic hardware requirements are rendering obsolete the capital-intensive droplet generator model for mid-throughput applications. Smaller academic labs in Germany and the Netherlands adopt split-pool ligation protocols to bypass Chromium-class instrument queues. The structural consequence compresses addressable market for entry-level droplet platforms while expanding reagent-only supplier opportunities.
EMA's In Vitro Diagnostic Regulation is tightening quality management system requirements for kit manufacturers seeking CE marking. Notified body capacity constraints extend review timelines for single-cell library preparation products. European distributors now demand IVDR-compliant documentation before adding research-use reagents to clinical-adjacent catalogs, forcing suppliers to front-load validation investment.
Core facility directors in the United States are unbundling sequencing from upstream sample processing, contracting specialized single-cell service providers for droplet encapsulation and library preparation. This disintermediation shifts margin from instrument vendors to fee-for-service operators in Boston and San Francisco research corridors. Contract research organizations capture workflow expertise that institutional cores struggle to retain.
Global Single-Cell Genome Sequencing Market Segmentation
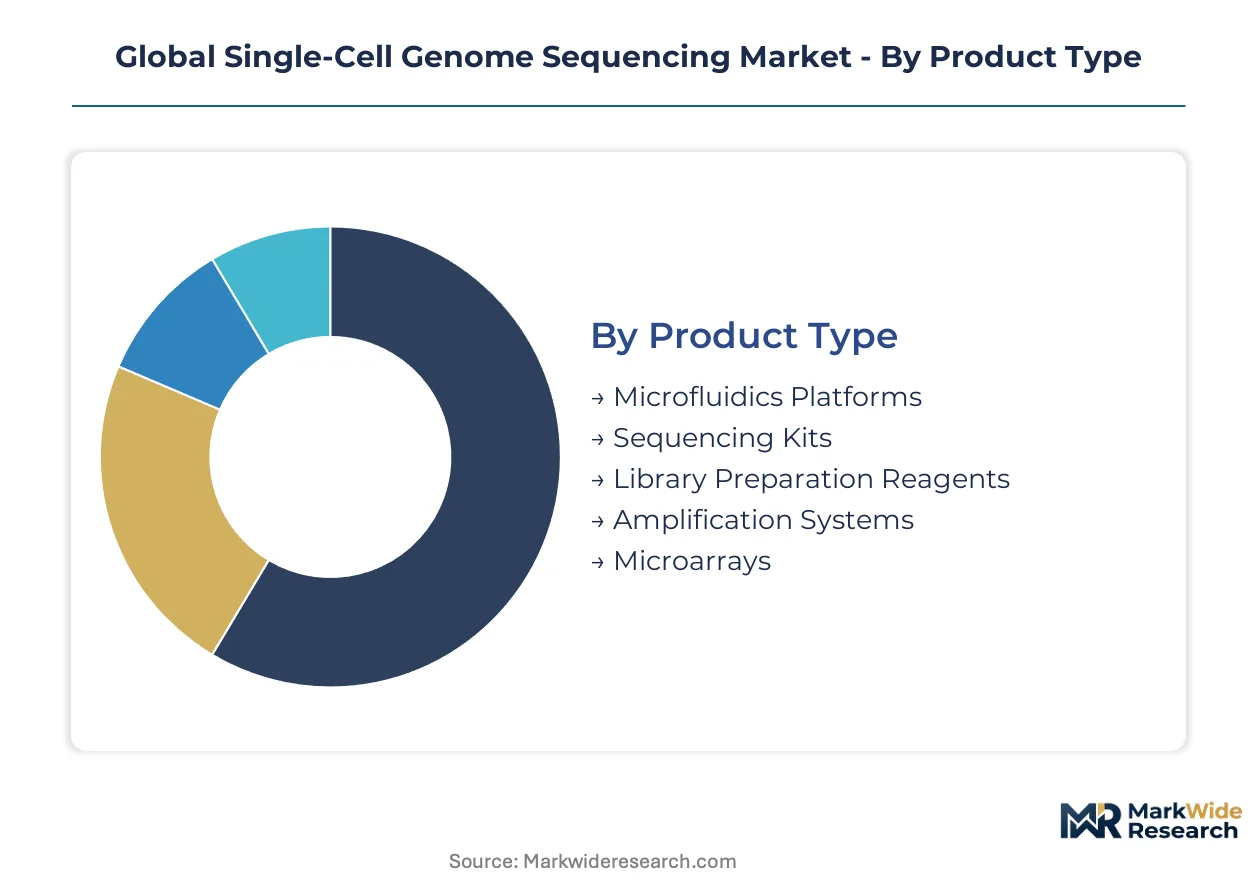
Single-cell genome sequencing workflows fragment across specialized modalities that trade capital intensity for throughput. Platform economics favor integrated consumable-instrument bundles, while open systems retain footholds in method-development environments.
Product Type:
Droplet microfluidics consolidation is compressing instrument margins while consumables capture recurring revenue pools across the use-case spectrum.
- Microfluidics Platforms:Chromium-class droplet generators dominate commercial volume through workflow integration. Academic core facilities in the United States standardize on these systems to lock in reagent spend and reduce protocol variability.
- Sequencing Kits:Bundled reagent sets for short-read and long-read chemistries constitute the largest recurring revenue pool. China's NMPA priority review pathways accelerate kit registration for clinical research applications.
- Library Preparation Reagents:CRISPR-compatible protocols are expanding experimental design possibilities.
- Amplification Systems:Whole-genome amplification reagents and specialized polymerases drive 40-60% of per-cell processing expense.
- Microarrays:Legacy genotyping platforms retain niche applications in copy number profiling.
Established volume favors microfluidics platforms; emerging adoption favors sequencing kits.
Technology:
Cost tier differentiation separates capital-intensive droplet systems from reagent-only combinatorial methods.
- Next-Generation Sequencing:Short-read platforms from Illumina sustain instrument placement across core facilities worldwide. Bulk sequencing infrastructure repurposing lowers entry barriers for single-cell adaptation.
- Droplet-Based Sequencing:Throughput economics dominate commercial volume. 10x Genomics leverages Chromium architecture to capture workflow standardization in cancer immunology studies.
- Imaging-Based Sequencing:Spatial transcriptomics integration preserves tissue architecture.
- Nanopore Sequencing:Long-read applications bypass amplification bias in structural variant detection.
- Digital PCR:Absolute quantification supports rare mutation validation.
Capital deployment concentrates in droplet-based sequencing; method innovation favors nanopore sequencing.
Application:
Customer type segmentation reveals divergent purchasing authority between grant-funded academics and procurement-driven pharmaceutical operations.
- Cancer Research:Tumor microenvironment profiling drives the largest kit volume through core facility centralization. Academic institutes in Germany's Heidelberg and Munich clusters expand single-cell adoption for immunotherapy resistance studies.
- Developmental Biology:Lineage tracing applications require highest cell throughput. Droplet microfluidics consolidation directly serves embryonic time-course experiments demanding tens of thousands of cells per study.
- Immunology Studies:T-cell receptor repertoire analysis expands rapidly.
- Neuroscience Research:Cellular heterogeneity mapping in brain tissue advances slowly due to sample preparation complexity.
- Microbial Analysis:Uncultured organism profiling represents greenfield expansion with limited incumbent competition.
Grant funding favors cancer research; pharmaceutical sponsorship favors developmental biology.
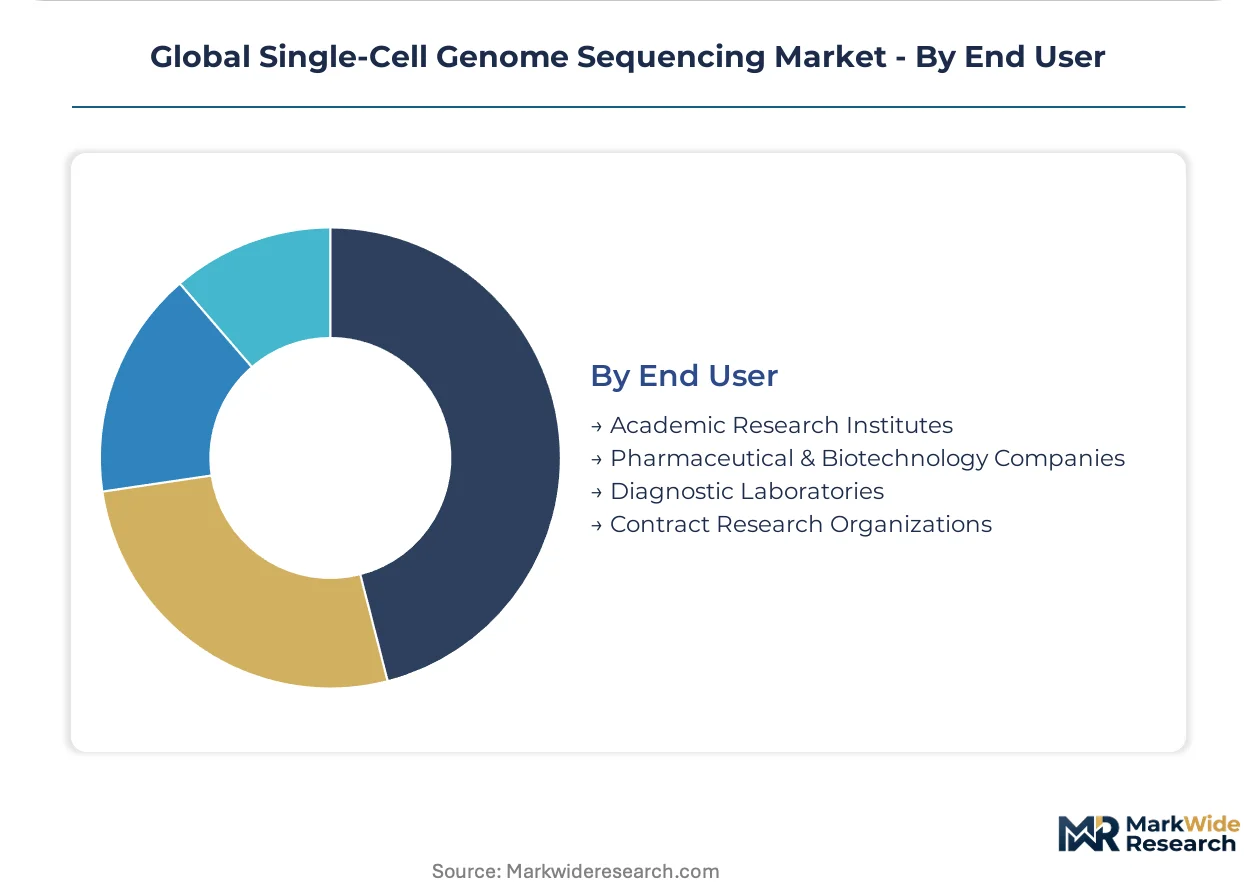
End User:
Supply concentration in reagent manufacturing shapes procurement leverage across institutional categories.
- Academic Research Institutes:Grant-funded cores standardize on workflow-integrated solutions. Bioinformatics pipeline integration challenges create service bottlenecks as computational biologist hiring lags instrument deployment.
- Pharmaceutical & Biotechnology Companies:Internal target validation groups build captive single-cell capabilities. EMA IVDR compliance burdens extend validation timelines for kit manufacturers serving clinical-adjacent research.
- Diagnostic Laboratories:FDA LDT oversight shapes commercialization pathways in the United States.
- Contract Research Organizations:Fee-for-service operators in Boston and San Francisco capture workflow expertise that institutional cores struggle to retain.
Instrument placement concentrates in academic institutes; margin capture shifts toward contract research organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic core facilities concentrate purchasing authority in the United States, Germany, and China, with pharmaceutical sponsors driving secondary demand in Switzerland and Japan. Grant-funded institutes in Heidelberg and Boston standardize on integrated workflow platforms. China's NMPA accelerates instrument registration timelines for clinical research applications.
United States
FDA oversight of laboratory-developed tests shapes diagnostic commercialization pathways for single-cell assays. Core facility directors in Boston and San Francisco research corridors unbundle sequencing from upstream sample processing, contracting specialized service providers for droplet encapsulation. The National Institutes of Health sustains grant funding for cancer immunology workflows.
Germany
Federal funding through the Bioeconomy Strategy creates instrument placement opportunities in Heidelberg and Munich research clusters. EMA's In Vitro Diagnostic Regulation raises compliance barriers for kit manufacturers seeking CE marking. Academic institutes in Baden-Württemberg expand single-cell adoption for tumor microenvironment profiling.
China
NMPA priority review channels reduce time-to-market for droplet-based platforms entering clinical research. Domestic instrument manufacturers capture share in tier-two city core facilities. Beijing and Shanghai academic medical centers drive adoption of CRISPR-compatible library preparation protocols for functional genomics studies.
Switzerland
Swissmedic regulates clinical-grade sequencing applications with alignment to EMA frameworks. Pharmaceutical sponsors in Basel build captive single-cell capabilities for target validation. The ETH Zurich and University of Geneva clusters concentrate method-development expertise in combinatorial indexing approaches.
Japan
PMDA review pathways shape commercialization timelines for sequencing instruments in clinical research. METI funding supports precision medicine infrastructure in the Kanto region. Tokyo and Osaka academic cores standardize on workflow-integrated solutions that lock in reagent spend.
Global Single-Cell Genome Sequencing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument, consumable, and service layers. The vendor base stratifies into three tiers: integrated platform providers capturing workflow standardization, reagent specialists supplying open-system compatibility, and fee-for-service operators disintermediating institutional cores. Dominant competitive moves include strategic partnerships between instrument and sequencing technology providers, plus geographic expansion through distributor networks in Asia-Pacific markets.
Within the integrated platform tier, 10x Genomics and Illumina exemplify channel-controlling archetypes that capture recurring revenue through consumable-instrument bundles. Oxford Nanopore Technologies occupies a position representing long-read specialization, differentiating through structural variant detection applications that bypass amplification bias. These three companies anchor the competitive structure, with 10x Genomics representing droplet microfluidics consolidation, Illumina exemplifying short-read sequencing infrastructure dominance, and Oxford Nanopore Technologies anchoring the fastest-growing modality in clinical cytogenetics.
| Leading Market Players |
|---|
| 10x Genomics |
| Illumina |
| Thermo Fisher Scientific |
| BD Biosciences |
| QIAGEN |
| Oxford Nanopore Technologies |
| Bio-Rad Laboratories |
| Standard BioTools (Fluidigm) |
| Takara Bio |
| Others |
Supply & Pricing Matrix
Overcapacity in Chromium-class droplet generators across United States academic cores is compressing instrument margins while forcing suppliers toward consumable-anchored revenue models. This utilization imbalance grants pricing power to reagent manufacturers even as hardware vendors absorb discount pressure.
Pricing Analysis
Cost-plus contracts with polymerase indexation dominate library preparation reagent procurement. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade clinical reagents from research-use kits and bulk unbundled chemistries. Cost compression in standard-tier kits is intensifying because combinatorial indexing methods eliminate microfluidic hardware requirements. Academic core facilities exhibit highest price sensitivity due to grant-funded budget constraints, while pharmaceutical internal target validation groups absorb premium pricing for regulatory-compliant documentation.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized polymerase foundries in Germany, Singapore, and the United States holding picogram-scale amplification reagent capacity. Raw material dependencies center on recombinant Taq polymerases, modified nucleotides, and microfluidic chip substrates. Single-source vulnerability concentrates in droplet generator nozzle fabrication, where two European precision machining houses control specialty glass supply. Distribution runs through authorized distributors in China and direct sales teams in Germany and the United States serving core facility procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where workflow integration creates switching costs that lock academic cores into consumable streams. Regulatory entrenchment through FDA LDT and EMA IVDR compliance pathways further deepens incumbent advantage.
For Market Incumbents: Build switching-cost moats by embedding bioinformatics pipeline support into reagent bundles, addressing the computational biologist hiring gap that constrains core facility autonomy. Threat from combinatorial indexing methods demands counter-investment in cloud-based analysis platforms that preserve workflow stickiness. Capacity addition in China's tier-two cities captures NMPA priority review momentum before domestic manufacturers consolidate regional distribution. For New Entrants and Emerging Players: Microbial single-cell genomics in environmental and infectious disease research represents the most penetrable entry point, with limited incumbent competition and grant funding availability from federal bioeconomy programs. Germany's Heidelberg and Munich clusters offer geographic concentration for method-development partnerships with academic methodologists. Go-to-market angle should emphasize open-system compatibility with existing Illumina infrastructure to bypass hardware placement barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fee-for-service operators in Boston and San Francisco research corridors that capture workflow expertise through specialized single-cell service provision. Long-term viability across the analysis window favors acquisition targets with CRISPR-compatible protocol libraries and established EMA IVDR technical documentation. Signal to watch is notified body capacity expansion in Europe, which would accelerate CE marking timelines and revalue compliant kit manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | 10x Genomics' Chromium architecture locks academic cores into consumable-anchored revenue streams. |
| Regulatory Approval Pathway | NMPA priority review channels in China compress time-to-market for clinical research applications. |
| Strategic Partnership | Combinatorial indexing collaborations with ETH Zurich bypass capital-intensive droplet generator requirements. |
| Acquisition of Specialist Firm | Bioinformatics pipeline providers address computational biologist scarcity constraining core facility autonomy. |
| Geographic Expansion | Domestic instrument manufacturers capture tier-two city share under China's precision medicine infrastructure push. |
Research Methodology
A spread of perspectives from core facility directors, reagent procurement managers, computational biologists, regulatory affairs specialists, and sequencing instrument engineers converged on the working assumptions. Primary interviews combined with secondary validation against SEC 10-K filings, NMPA registration databases, EMA IVDR technical documentation, and NIH grant award records. Bottom-up instrument placement counts and top-down consumable revenue estimates were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology modality, application area, end-user category, and regional regulatory cluster. CAGRs were derived from instrument installed base expansion rates cross-referenced with consumable pull-through per system. Industry-specific forecast inputs incorporated NMPA review timeline acceleration and EMA notified body capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in NIH grant funding levels, Chinese RMB exchange rates, or European research infrastructure budgets would shift the trajectory. Forecasts reflect documented assumptions regarding CRISPR protocol adoption curves and droplet microfluidics consolidation velocity. Quarterly review of NMPA priority review queue lengths and EMA IVDR certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
NGS Automation Market
Genomics
Antisense Oligonucleotides Market
Genomics
Oligonucleotide Pool Market
Genomics
Molecular Breeding Market
Genomics
Genetic Testing Panels Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Gene Sequencing Market
Genomics
Latin America Gene Expression Market
Genomics
Microarray Scanners Market
Genomics
Europe Genetic Testing Market
Genomics
Omics Lab Services Market
Genomics
Global NGS Sample Preparation Market
Genomics
Retail Genomics Market
Genomics
Single-Cell Omics Market
Genomics
North America Genetic Testing Market