
 Kearns-Sayre Syndrome Market | 2026-2036
Kearns-Sayre Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Kearns-Sayre Syndrome Market Analysis
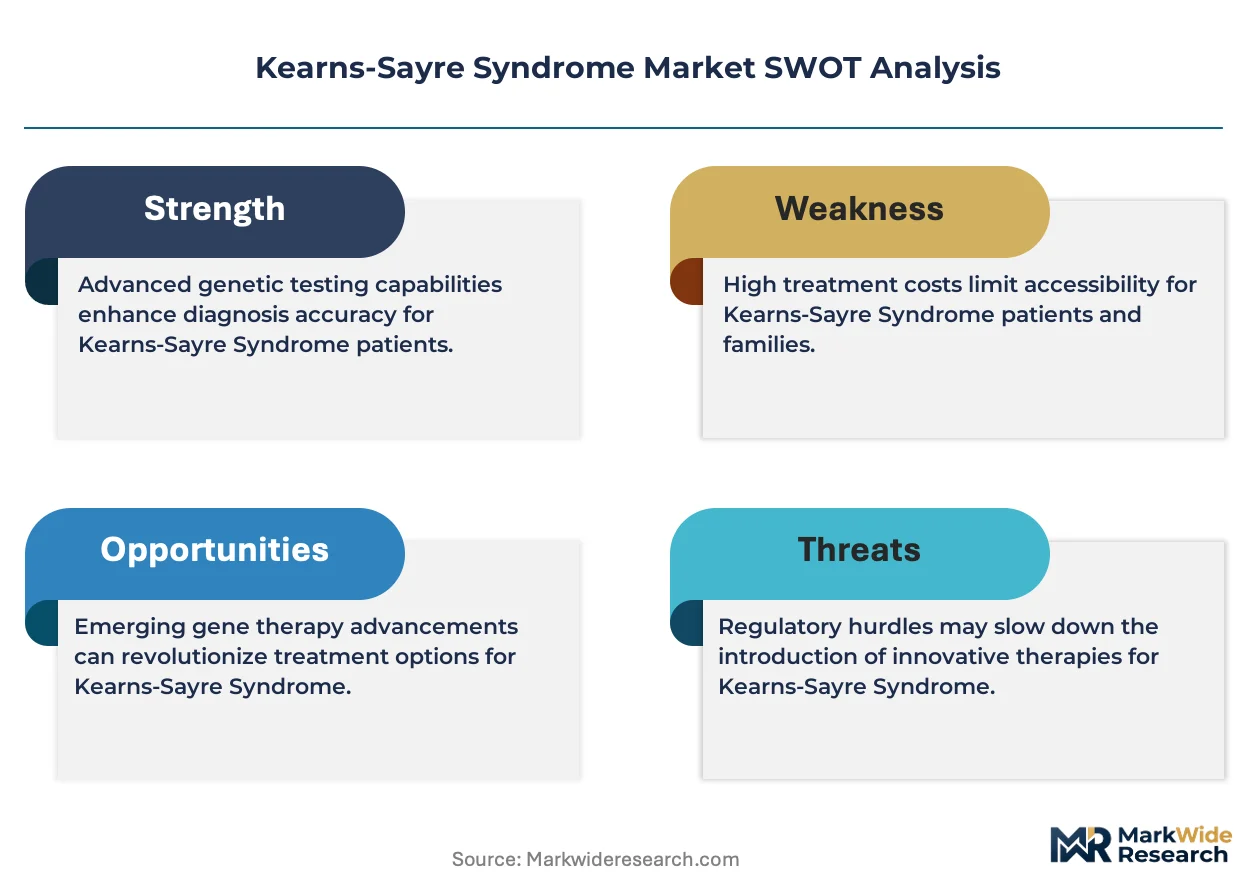
Modular trial design is hardening as the dominant packaging configuration for Kearns-Sayre Syndrome drug development, enabling sponsors to bundle biomarker endpoints with adaptive regulatory submissions. Abliva leverages its mitochondrial medicine platform to sustain early-stage programs across multiple rare disease indications. Stealth BioTherapeutics anchors its competitive position through elamipretide, a late-stage candidate targeting primary mitochondrial myopathies. Alexion Pharmaceuticals competes via its established rare disease commercial infrastructure and complement-mediated disorder expertise.
Kearns-Sayre Syndrome constitutes a mitochondrial cytopathy characterized by chronic progressive external ophthalmoplegia, retinitis pigmentosa, and cardiac conduction defects before age twenty, with diagnosis confirmed through skeletal muscle biopsy demonstrating ragged-red fibers or single large-scale mitochondrial DNA deletion. The condition demands specialized therapeutics addressing energy metabolism dysfunction rather than conventional symptomatic approaches alone. Therapeutics and gene therapy segments command premium valuation multiples due to unmet medical need and orphan drug exclusivity potential, while diagnostic kits occupy a mature, reimbursement-constrained position. Advanced therapies and biologics technology platforms attract disproportionate R&D capital allocation relative to small molecules, reflecting mechanistic alignment with mitochondrial pathophysiology.
FDA orphan drug designation and EMA priority medicines pathways shape clinical trial investment thresholds and market access timelines for developers. Reimbursement negotiations with national health technology assessment bodies in Germany, France, and England determine commercial viability for premium-priced therapies. Stakeholders must monitor regulatory precedent for mitochondrial replacement therapies and evolving gene therapy manufacturing standards to anticipate competitive entry dynamics.
Market Dynamics
Gene therapy manufacturing scale-up is compressing clinical timelines for mitochondrial disease developers while FDA and EMA orphan pathways simultaneously lower capital barriers for rare disease sponsors.
Growth Catalysts
- FDA Orphan Drug Designation:Developers receive tax credits for clinical trials and seven years of market exclusivity upon approval, accelerating investment in Kearns-Sayre Syndrome programs.
- Single Large-Scale mtDNA Deletion Detection:Improved skeletal muscle biopsy protocols and next-generation sequencing are shortening diagnostic odysseys from years to months in specialized mitochondrial centers.
- Japan:METI funding for regenerative medicine infrastructure and PMDA streamlined review pathways for serious rare diseases are drawing sponsor investment toward Asia-Pacific expansion.
Market Restraints
- AAV Vector Manufacturing Bottlenecks:Viral vector production capacity concentrates among three contract manufacturers in the United States and Europe, creating queue delays for mitochondrial gene therapy candidates.
- Reimbursement Threshold Rigidity:Germany's G-BA and England's NICE apply standard health technology assessment criteria to ultra-rare diseases, compressing acceptable price bands for single-administration therapies.
- Cardiac Conduction Monitoring Burden:Mandatory pacemaker implantation surveillance requirements extend trial durations and inflate per-patient costs in cardiac-impaired Kearns-Sayre cohorts.
Strategic Opportunities
- EMA Priority Medicines (PRIME) Pathway:Early eligibility for accelerated assessment and enhanced regulatory dialogue shortens time-to-market for first-in-class mitochondrial therapeutics.
- Allogeneic Mitochondrial Transplantation:Converging cell therapy and mitochondrial isolation technologies are opening non-viral delivery routes for organ-specific metabolic restoration.
- Specialized Distribution Through Academic Medical Centers:Direct-to-center dispensing bypasses traditional wholesale channels, capturing margin and ensuring cold-chain integrity for biologics.
Industry Challenges
- Mitochondrial Biology Expertise Scarcity:Recruitment of translational scientists with organelle-specific drug development experience lags program expansion, inflating compensation benchmarks.
- Multi-Organ Endpoint Harmonization:Discordant regulatory expectations between ophthalmologic, cardiac, and neuromuscular divisions at FDA complicate unified trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kearns-Sayre Syndrome Market |
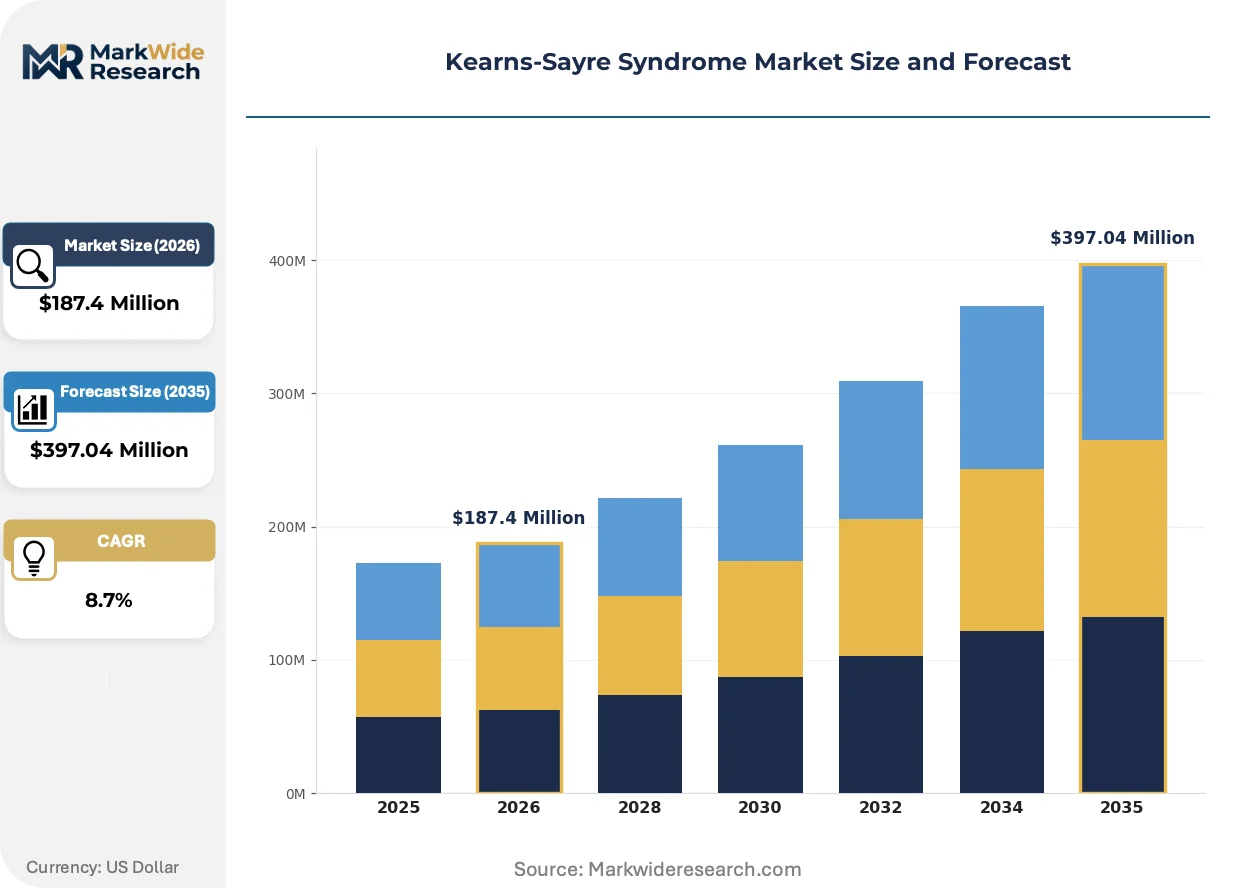
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutics, Diagnostic Kits, Gene Therapy, Supportive Care End User: Hospitals, Clinics, Research Laboratories, Homecare Application: Genetic Testing, Disease Management, Symptomatic Treatment, Clinical Research Technology: Biologics, Small Molecules, Advanced Therapies, Diagnostic Imaging |
| Companies Covered | Abliva, CENTOGENE, Stealth BioTherapeutics, Alexion Pharmaceuticals, GeneDx, Reata Pharmaceuticals, NeuroVive Pharmaceutical, PTC Therapeutics, Khondrion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kearns-Sayre Syndrome Market Emerging Trajectories
Biological understanding of heteroplasmy dynamics is reshaping therapeutic targeting strategies, while manufacturing and regulatory innovations are compressing development cycles for previously intractable mitochondrial conditions.
AAV-delivered mitochondrial genome editing is electrifying preclinical pipelines by enabling precise correction of pathogenic deletions without nuclear genome disruption. Academic medical centers in Boston and Heidelberg are advancing first-in-human protocols. This technology is compressing the viable therapeutic window from symptomatic management to disease modification.
EMA's PRIME designation eligibility criteria now explicitly recognize mitochondrial diseases as areas of unmet medical need, triggering enhanced scientific advice and accelerated assessment pathways. Sponsors are restructuring regulatory submission timelines to align with these provisions. Gene therapy developers targeting Kearns-Sayre Syndrome are prioritizing European parallel filings to capture these benefits.
Patient advocacy organizations are consolidating procurement influence through dedicated foundation investment funds that directly finance early-stage trials. Traditional venture capital is yielding to this concentrated demand-side capital in rare mitochondrial indications. This shift is most visible in the United States, where the United Mitochondrial Disease Foundation channels donor capital into platform technology companies.
Kearns-Sayre Syndrome Market Segmentation
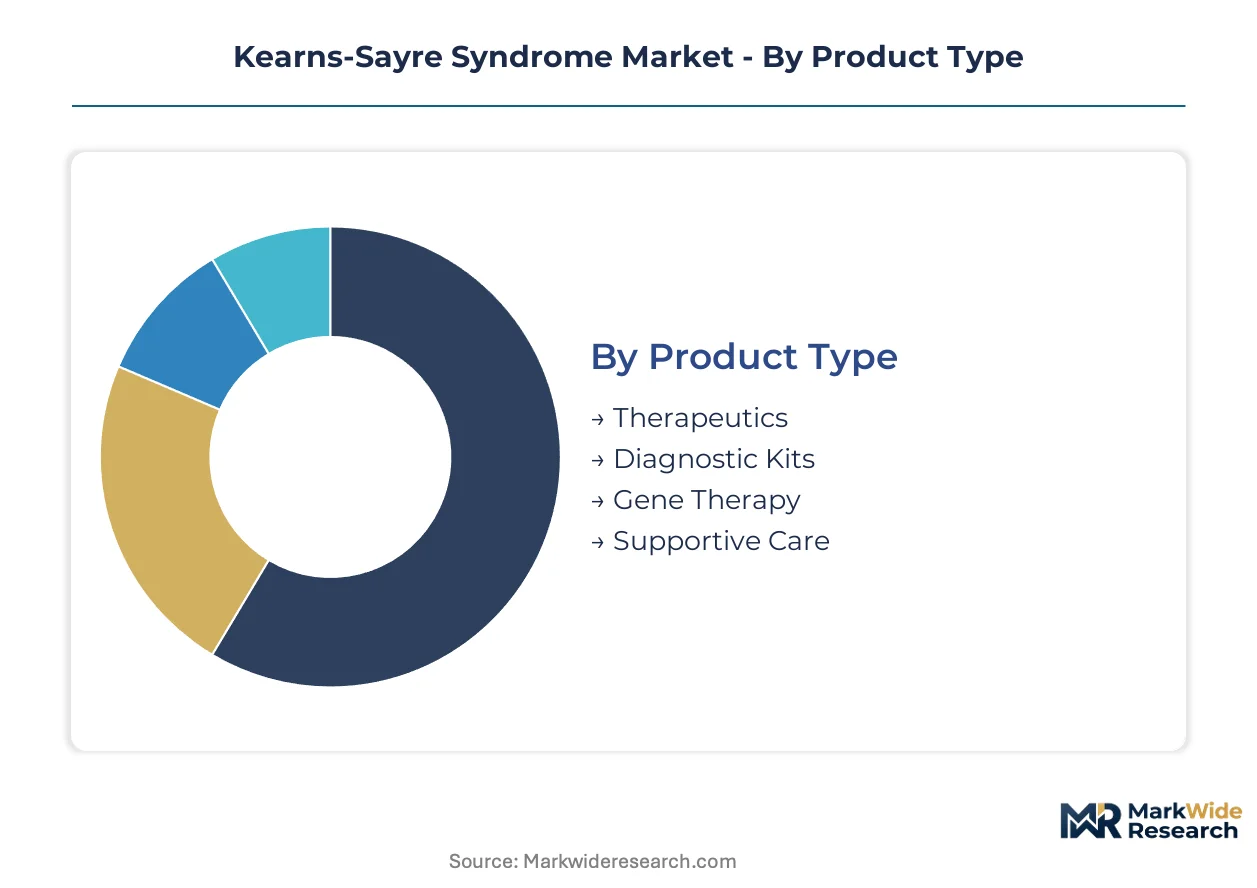
Kearns-Sayre Syndrome segmentation reflects divergent regulatory pathways and reimbursement architectures. Product type determines FDA orphan drug exclusivity eligibility, while technology choice shapes manufacturing scale and vector supply requirements.
Product Type:
Gene therapy candidates require FDA Biologics License Application pathways and EMA centralized procedures, while diagnostic kits navigate 510(k) premarket notification or CE-IVD conformity assessment. Therapeutics and supportive care products split between orphan drug incentives and standard reimbursement frameworks.
- Therapeutics:Pharmacological interventions targeting mitochondrial dysfunction span metabolic cofactors, antioxidants, and electron transport chain modulators. Demand concentrates in United States academic medical centers where specialized mitochondrial disease clinics anchor prescriber access. FDA orphan drug designation accelerates development timelines for sponsors addressing energy metabolism defects.
- Gene Therapy:AAV-delivered mitochondrial genome editing and allotopic expression vectors represent disease-modifying approaches. Manufacturing queues at United States and European contract manufacturers constrain program initiation rates. EMA PRIME designation eligibility triggers enhanced regulatory dialogue for first-in-class candidates.
- Diagnostic Kits:Skeletal muscle biopsy protocols and next-generation sequencing panels for single large-scale mtDNA deletion detection occupy mature regulatory positions. Reimbursement constraints in German statutory health insurance and England's NHS limit pricing flexibility for confirmatory testing.
- Supportive Care:Pacemaker implantation supplies, ophthalmologic aids, and physical therapy equipment address symptomatic manifestations. Procurement runs through hospital networks and specialized mitochondrial disease centers in Japan and Germany.
Therapeutics sits at the top of the volume ranking, with gene therapy climbing the fastest.
End User:
Hospital procurement power concentrates in tertiary referral networks with dedicated mitochondrial disease programs. Cost tiers separate academic medical centers with research infrastructure from community clinics managing stable patients.
- Hospitals:Tertiary centers with specialized mitochondrial disease clinics command patient volume and clinical trial enrollment capacity. United States institutions in Boston and Baltimore anchor regional referral patterns. FDA-regulated investigational new drug protocols require institutional review board infrastructure concentrated in these settings.
- Clinics:Community neurology and ophthalmology practices manage stable patients between acute episodes. Reimbursement fragmentation across German regional associations and Japanese prefectural health bureaus complicates cross-border care coordination.
- Research Laboratories:Academic and contract research organizations conduct biomarker validation and natural history studies. METI funding in Japan and NIH grants in the United States sustain preclinical program expansion.
- Homecare:Cardiac monitoring devices and respiratory support equipment enable outpatient management. Distribution runs through durable medical equipment suppliers with cold-chain capabilities for biologic supportive therapies.
Hospitals capture the dominant revenue share, with research laboratories expanding most quickly.
Application:
Application segmentation tracks the patient journey from molecular diagnosis through longitudinal disease modification. Margin structures favor clinical research and genetic testing over commoditized symptomatic treatment.
- Genetic Testing:Molecular confirmation of single large-scale mtDNA deletion through skeletal muscle biopsy or blood-based assays. United States reference laboratories and German university hospitals concentrate specialized diagnostic capacity. PMDA streamlined review pathways in Japan accelerate companion diagnostic co-development.
- Disease Management:Coordinated multidisciplinary care spanning cardiology, ophthalmology, neurology, and endocrinology. Academic medical centers in Heidelberg and Tokyo organize dedicated mitochondrial disease programs. Reimbursement negotiations with Germany's G-BA determine sustainable care model economics.
- Symptomatic Treatment:Pacemaker implantation, ptosis surgery, and hormone replacement address organ-specific manifestations. Volume concentrates in cardiac and ophthalmologic service lines with mitochondrial disease familiarity.
- Clinical Research:Natural history studies and interventional trials generate regulatory-grade evidence. Patient advocacy foundation funding in the United States displaces traditional venture capital for early-phase programs.
Disease management commands the largest patient volume, with clinical research gaining share fastest.
Technology:
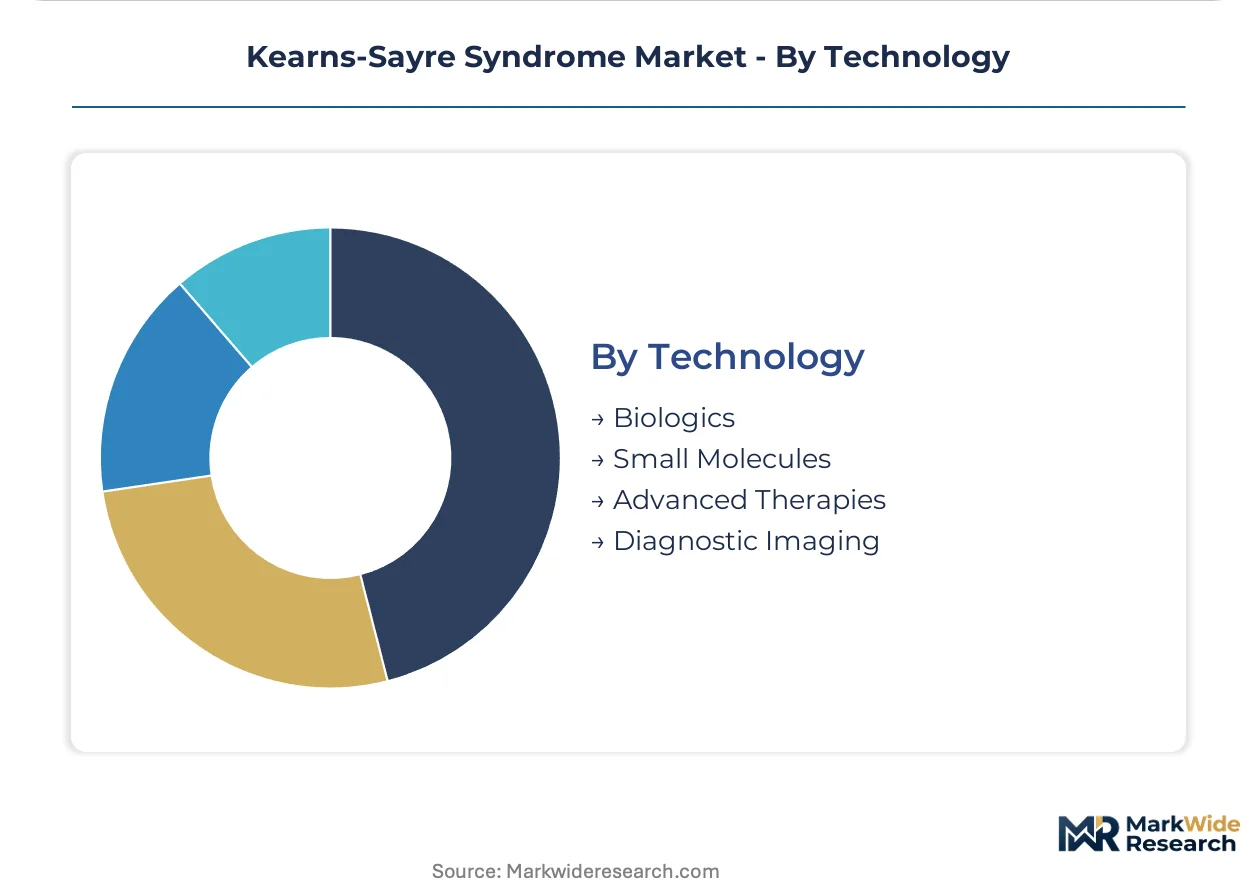
Technology platforms stratify by manufacturing complexity and regulatory novelty. Advanced therapies and biologics attract disproportionate R&D capital allocation relative to small molecules.
- Biologics:Recombinant proteins and monoclonal antibodies targeting mitochondrial quality control pathways. Contract manufacturing capacity constraints in the United States and Europe limit sponsor pipeline expansion.
- Small Molecules:Oral metabolic cofactors and electron transport chain modulators with established pharmacokinetic profiles. Generic competition in coenzyme Q10 and idebenone segments compresses pricing power.
- Advanced Therapies:Gene therapy, allogeneic mitochondrial transplantation, and cell-based interventions. AAV vector manufacturing bottlenecks at three dominant contract manufacturers create queue delays. EMA advanced therapy medicinal product classification triggers centralized procedure requirements.
- Diagnostic Imaging:Cardiac MRI and retinal imaging for disease monitoring and trial endpoint quantification. Equipment procurement concentrates in German and Japanese university hospitals with research imaging cores.
Advanced therapies occupy the steepest expansion trajectory, with biologics maintaining volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in Boston and Baltimore pioneered mitochondrial disease specialization during the 1990s, establishing the clinical infrastructure that now anchors patient access across three continents.
United States
Specialized mitochondrial disease clinics at Massachusetts General Hospital and Johns Hopkins University concentrate patient volume and clinical trial enrollment capacity. FDA orphan drug designation provides tax credits and seven-year exclusivity, accelerating sponsor investment in Kearns-Sayre programs. Patient advocacy foundation funding through the United Mitochondrial Disease Foundation channels donor capital into platform technology companies in Boston and San Diego.
Germany
Heidelberg University Hospital organizes dedicated mitochondrial disease programs with integrated cardiology, ophthalmology, and neurology service lines. Germany's G-BA applies standard health technology assessment criteria to ultra-rare diseases, compressing acceptable price bands for single-administration therapies. The university hospital cluster in Baden-Württemberg anchors regional referral patterns for skeletal muscle biopsy and genetic confirmation.
Japan
METI funding for regenerative medicine infrastructure and PMDA streamlined review pathways for serious rare diseases draw sponsor investment toward Asia-Pacific expansion. Tokyo Medical and Dental University and Keio University Hospital organize dedicated mitochondrial disease centers with cardiac conduction monitoring capabilities. Prefectural health bureaus manage reimbursement fragmentation across regional associations.
United Kingdom
England's NICE applies standard health technology assessment criteria to ultra-rare diseases, limiting pricing flexibility for premium therapies. Newcastle University and the Wellcome Centre for Mitochondrial Research anchor academic clinical trial infrastructure. The NHS specialized commissioning framework concentrates patient access in designated mitochondrial disease centers in London and Newcastle.
Kearns-Sayre Syndrome Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the gene therapy-symptomatic care divide, with disease-modifying candidates commanding valuation multiples that diagnostic and supportive products cannot match. The competitive terrain stratifies into three tiers: platform technology developers with mitochondrial medicine expertise, rare disease commercial infrastructure operators, and specialized diagnostic service providers. Dominant competitive moves include strategic partnerships between gene therapy developers and contract manufacturers, plus portfolio diversification into adjacent mitochondrial cytopathies.
Within the platform technology tier, Abliva exemplifies the mitochondrial medicine specialist archetype, while Stealth BioTherapeutics occupies a position among late-stage therapeutic developers. Alexion Pharmaceuticals represents the established rare disease commercial infrastructure archetype. These three entities collectively illustrate the competitive spectrum from early-stage platform breadth to regulatory-stage asset concentration.
| Leading Market Players |
|---|
| Abliva |
| CENTOGENE |
| Stealth BioTherapeutics |
| Alexion Pharmaceuticals |
| GeneDx |
| Reata Pharmaceuticals |
| NeuroVive Pharmaceutical |
| PTC Therapeutics |
| Khondrion |
| Others |
Supply Flow & Price Mechanics
Tertiary academic medical centers in Boston, Heidelberg, and Tokyo concentrate procurement power for Kearns-Sayre Syndrome therapeutics, anchoring value-based pricing negotiations for single-administration gene therapies against standardized reimbursement benchmarks.
Pricing Analysis
Orphan-drug premium pricing stratifies across disease-modifying, maintenance, and supportive care tiers. Price differentiation hinges on FDA exclusivity status and EMA PRIME designation tier, with vector manufacturing scale determining cost floors. Pricing pressure stems from NICE and G-BA health technology assessment rigidity in England and Germany. Hospital pharmacy committees exhibit highest price sensitivity; research laboratories with foundation funding show lowest.
Supply Chain Analysis
GMP certification for AAV vector production gates supplier entry to three dominant contract manufacturers in the United States and Europe. Plasmid DNA, HEK293 cell lines, and specialized bioreactor hardware feed production queues. Single-source vulnerability concentrates at viral vector filling-finish sites. Distribution runs through cold-chain logistics partners to academic medical center pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kearns-Sayre Syndrome therapeutics function as a stable compounder, with FDA orphan drug exclusivity and EMA priority pathways insulating revenue streams from competitive erosion.
For Market Incumbents: Deploy manufacturing queue priority rights to secure AAV vector slots before competitor program initiation. Gene therapy developers face substitution risk from allogeneic mitochondrial transplantation platforms; anchor position through backward integration into plasmid production and captive GMP facility investment. For New Entrants and Emerging Players: Launch via direct-to-center distribution partnerships with Japanese prefectural health bureaus and German university hospital clusters. White-space concentrates in cardiac conduction monitoring devices and homecare respiratory support, segments where reimbursement fragmentation has deterred incumbent focus. For Investors and Strategic Acquirers: Large-cap rare disease pharmaceutical companies are the most active acquirers in this space, seeking mitochondrial medicine platform capabilities. Long-term viability rests on heteroplasmy modulation science maturation. Watch for EMA advanced therapy medicinal product classification precedents as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Modular adaptive protocols accelerate FDA orphan pathway timelines for mitochondrial genome editing candidates. |
| Manufacturing Scale-Up | AAV vector capacity expansion at United States contract manufacturers decompresses program initiation queues. |
| Regulatory Approval Pathway | EMA PRIME designation triggers enhanced scientific advice for first-in-class allotopic expression vectors. |
| Pipeline Diversification | Platform extension into Pearson syndrome and progressive external ophthalmoplegia leverages shared mitochondrial biology. |
| Licensing Agreement | Academic medical center technology transfer deals in Boston and Heidelberg secure genome editing IP access. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down gene therapy pipeline tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and payer access specialists combined with secondary validation against FDA orphan drug designations, EMA PRIME eligibility decisions, ClinicalTrials.gov entries, and German G-BA assessment reports. Top-down supply-side analysis triangulates against bottom-up demand aggregation.
Input-output matrices map gene therapy manufacturing capacity, patient prevalence estimates, and reimbursement negotiation outcomes to volume and value projections across the analysis window. Segmentation dimensions include product type, end user tier, application stage, and technology platform. CAGRs derive from fitted growth curves anchored to regulatory approval probability-weighted launch dates. Forecast inputs incorporate AAV vector queue wait times and foundation funding disbursement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under mitochondrial replacement therapy regulatory restriction or cardiac endpoint harmonization failure at FDA. Forecasts reflect documented assumptions regarding heteroplasmy correction durability and vector immunogenicity profiles. A model refresh is warranted upon material change in EMA advanced therapy classification precedent or G-BA ultra-rare disease pricing methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Single-Cell Omics Market
Genomics
United States DNA Sequencing Products Market
Genomics
Genetic Testing Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
AI in Genomics Market
Genomics
Hereditary Testing Market
Genomics
DNA Mass Ladder Market
Genomics
Rare Disease Genetic Testing Market
Genomics
DNA Sequencing Services Market
Genomics
Global Nutrigenomics Market
Genomics
Reproductive Genetics Market
Genomics
Global Mirna Sequencing and Assay Market