
 Europe Rett Syndrome Market | 2026-2036
Europe Rett Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rett Syndrome Market Foresight
The pricing and access divide between premium gene therapy candidates and established supportive care protocols is hardening across Europe. Neuren Pharmaceuticals Limited leverages its trofinetide platform to anchor leadership in disease-modifying therapeutics, while Biogen competes through its rare disease neurology infrastructure and established European hospital networks. AMO Pharma Limited differentiates by targeting specific behavioral symptom clusters with novel small-molecule approaches.
Rett syndrome constitutes a severe X-linked dominant neurodevelopmental disorder caused by MECP2 gene mutations, characterized by arrested development after apparently normal early infancy, progressive motor dysfunction, and autonomic nervous system impairment; its primary purpose in clinical practice is to identify intervention targets that preserve neurological function and extend independent living capacity. The therapeutics segment leads value generation as developers pursue disease-modifying mechanisms beyond symptomatic management, while the diagnostics segment sustains growth through expanded newborn screening and genetic testing integration into pediatric neurology workflows. Motor dysfunction within the therapy area classification occupies the largest addressable need given its profound impact on patient autonomy and caregiver burden.
EMA's orphan drug designation framework and the EU's Paediatric Regulation shape clinical trial obligations and exclusivity incentives for Rett syndrome developers, while national health technology assessment bodies in Germany, France, and England determine reimbursement thresholds that directly constrain market access. The Medical Device Regulation governs diagnostic and monitoring tools used in Rett syndrome management, adding compliance layers for neurophysiological assessment technologies. Stakeholders must monitor how evolving EU pharmaceutical legislation on rare disease incentives intersects with member-state pricing negotiations to determine sustainable commercialization pathways.
Market Dynamics
The EMA's accelerated assessment pathways for rare neurological disorders are compressing development timelines and redistributing risk capital toward disease-modifying therapeutics, fundamentally altering how developers sequence clinical investments across European markets.
Growth Catalysts
- EU Orphan Drug Regulation:Extended market exclusivity provisions incentivize pediatric neurology developers to prioritize Rett syndrome programs despite small addressable populations.
- Expanded newborn screening:National health systems in Germany, France, and the United Kingdom are integrating MECP2 genetic testing into standard pediatric workflows, compressing diagnostic delays.
- Specialized pediatric clinic networks:Western European academic medical centers are consolidating Rett syndrome expertise into dedicated care pathways that attract clinical trial sponsorship.
Market Restraints
- Gene therapy manufacturing capacity:Viral vector production bottlenecks in European contract manufacturing organizations constrain supply scalability for disease-modifying candidates.
- Health technology assessment divergence:Germany's IQWiG, France's HAS, and England's NICE apply inconsistent cost-effectiveness thresholds that fragment pricing negotiations.
- Caregiver workforce limitations:Specialized nursing and rehabilitation therapist shortages in Southern and Eastern European markets restrict supportive care protocol adoption.
Strategic Opportunities
- Central and Eastern Europe:Underserved rare disease infrastructure in Poland, Czech Republic, and Hungary creates first-mover advantages for diagnostic and monitoring platform deployment.
- Digital biomarker integration:Wearable autonomic monitoring and eye-tracking technologies are converging with telemedicine platforms to enable decentralized clinical trial endpoints.
- EU Paediatric Regulation incentives:Mandatory pediatric investigation plans and associated rewards are redirecting neurology pipeline resources toward Rett syndrome indications.
Industry Challenges
- Cross-border patient mobility:Regulatory fragmentation across EU member states complicates centralized treatment authorization and reimbursement portability for gene therapy candidates.
- Natural history data scarcity:Incomplete longitudinal registries in Southern Europe impede comparator arm construction for pivotal trials.
- Medical Device Regulation compliance:Neurophysiological assessment technologies face extended conformity assessment timelines under MDR's stricter clinical evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rett Syndrome Market |
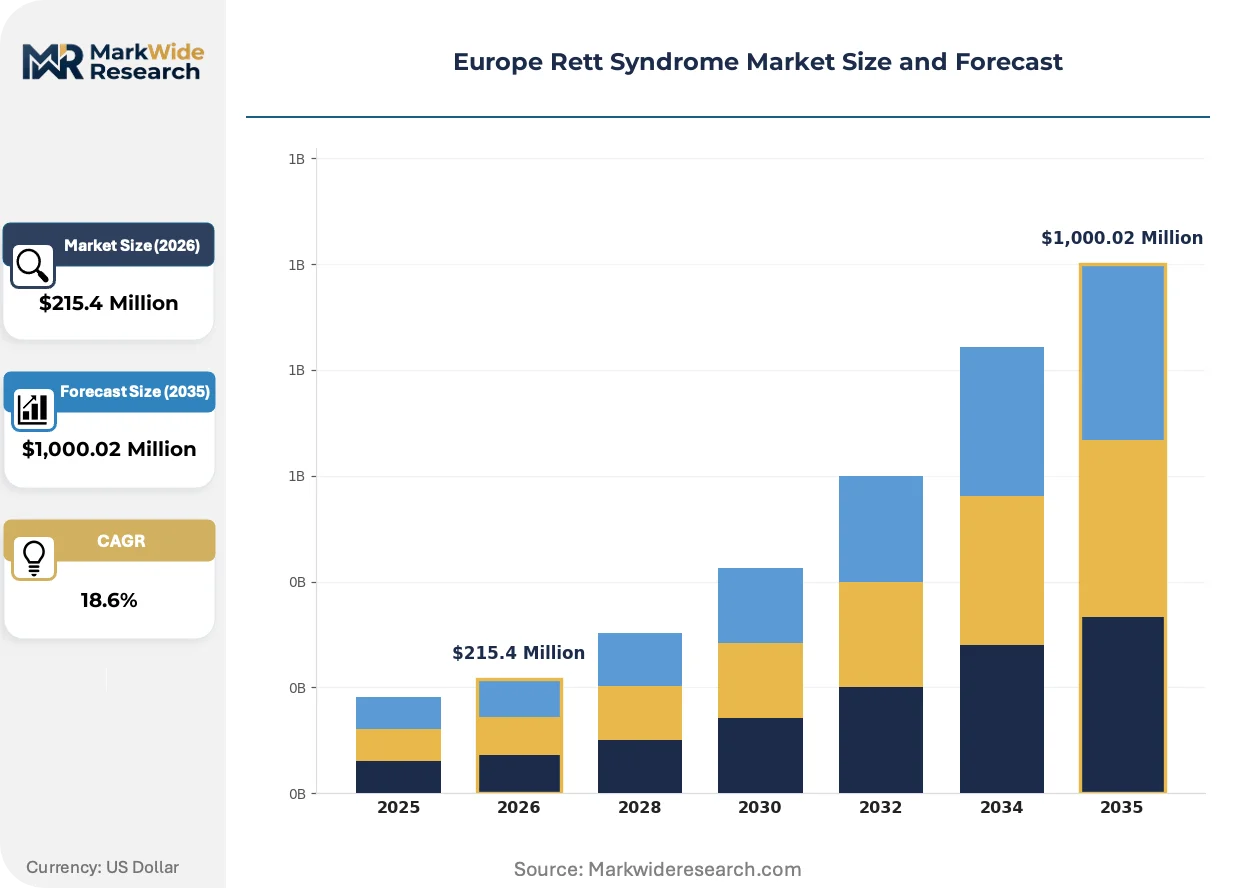
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,000.02 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Therapeutics, Supportive Care, Nutritional Products End User: Pediatric Clinics, Hospitals, Home Care Settings, Rehabilitation Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation Therapy Area: Cognitive Impairment, Motor Dysfunction, Behavioral Issues, Sleep Disorders |
| Companies Covered | Neuren Pharmaceuticals Limited, AMO Pharma Limited, Biogen, AstraZeneca, Anavex Life Sciences, Taysha Gene Therapies, Vyant Bio, GW Pharmaceuticals, Prilenia Therapeutics Development, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rett Syndrome Market Shifts & Advancements
Gene therapy platforms and digital health infrastructure are converging to reshape how Rett syndrome interventions are developed, evaluated, and delivered across European care systems.
Antisense oligonucleotide and gene editing technologies are expanding into Rett syndrome therapeutic development as developers target MECP2 gene reactivation or protein replacement. Academic medical centers in Germany and the United Kingdom are establishing dedicated gene therapy treatment units to manage anticipated regulatory approvals. This expansion is compressing the traditional gap between preclinical proof-of-concept and first-in-human studies.
EMA's priority medicines scheme and adaptive pathway frameworks are streamrolling rare neurological disorder assessments, reducing regulatory review timelines for disease-modifying candidates. Developers are pre-positioning real-world evidence collection systems to satisfy post-authorization efficacy requirements. France and Germany are responding with early access programs that permit conditional reimbursement pending confirmatory trials.
Patient advocacy organizations are consolidating purchasing influence through pan-European rare disease alliances that negotiate bundled diagnostic and therapeutic access agreements. Hospital pharmacy procurement committees in the Netherlands and Belgium are unbundling supportive care protocols from gene therapy administration services. This concentration is most visible in Benelux markets where payer-producer direct contracting is displacing traditional wholesale distribution.
Europe Rett Syndrome Market Segmentation
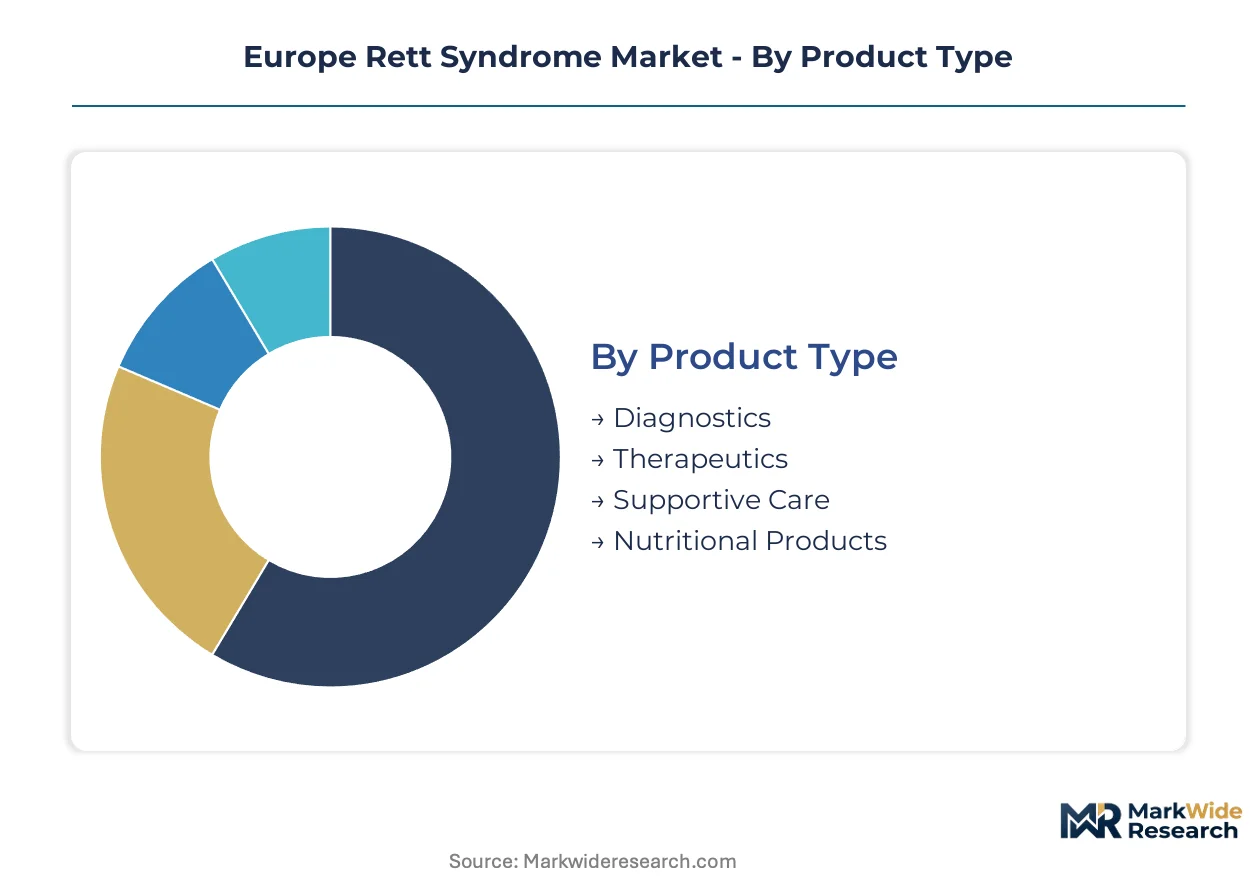
Segmentation reveals how capital deployment and clinical workflows fragment across the Europe Rett syndrome landscape. Each dimension exposes distinct margin structures and regulatory touchpoints that determine viable commercial pathways.
Product Type:
Capital intensity peaks in segments requiring manufacturing infrastructure, regulatory dossiers, and post-market surveillance systems. Therapeutics and diagnostics command the heaviest upfront investment.
- Therapeutics:Disease-modifying candidates demand viral vector manufacturing facilities and EMA centralized marketing authorization pathways. German and French hospital networks concentrate early adoption for gene therapy administration.
- Diagnostics:MECP2 genetic testing platforms require CLIA-equivalent laboratory accreditation and integration into national newborn screening programs. United Kingdom and Netherlands health systems drive volume through expanded pediatric neurology referrals.
- Supportive Care:Seizure management and respiratory support devices face MDR conformity assessment timelines.
- Nutritional Products:Enteral feeding formulations compete on pharmacy tender pricing.
Most installed capacity flows through Therapeutics. Expansion is steepest in Diagnostics.
End User:
Customer concentration varies by care complexity and reimbursement authorization requirements. Academic medical centers and specialized clinics gatekeep access to premium interventions.
- Pediatric Clinics:Dedicated Rett syndrome programs in Germany, France, and the United Kingdom coordinate multidisciplinary care and clinical trial enrollment. These sites attract sponsor investment through established patient registries.
- Hospitals:Tertiary centers manage acute complications and gene therapy inpatient administration. Capacity constraints in Southern Europe limit protocol penetration.
- Home Care Settings:Family-managed supportive care protocols depend on nursing workforce availability.
- Rehabilitation Centers:Motor function interventions require specialized therapist training.
Pediatric Clinics anchor prescription volume. Home Care Settings are expanding most quickly as reimbursement shifts toward decentralized management.
Delivery Mode:
Route selection determines manufacturing scale, cold chain requirements, and caregiver training burdens. Parenteral formats face stricter pharmacy controls.
- Intravenous:Gene therapy candidates require infusion center infrastructure and intensive monitoring protocols. German university hospitals are establishing dedicated treatment units.
- Oral:Small-molecule disease-modifying agents like trofinetide leverage existing retail pharmacy distribution. France and Spain show concentration in ambulatory prescription volume.
- Subcutaneous:Depot formulations reduce dosing frequency but require injection training.
- Inhalation:Respiratory symptom management devices face MDR device classification.
Intravenous delivery captures the highest value per patient. Oral formulations are gaining share fastest through pharmacy channel expansion.
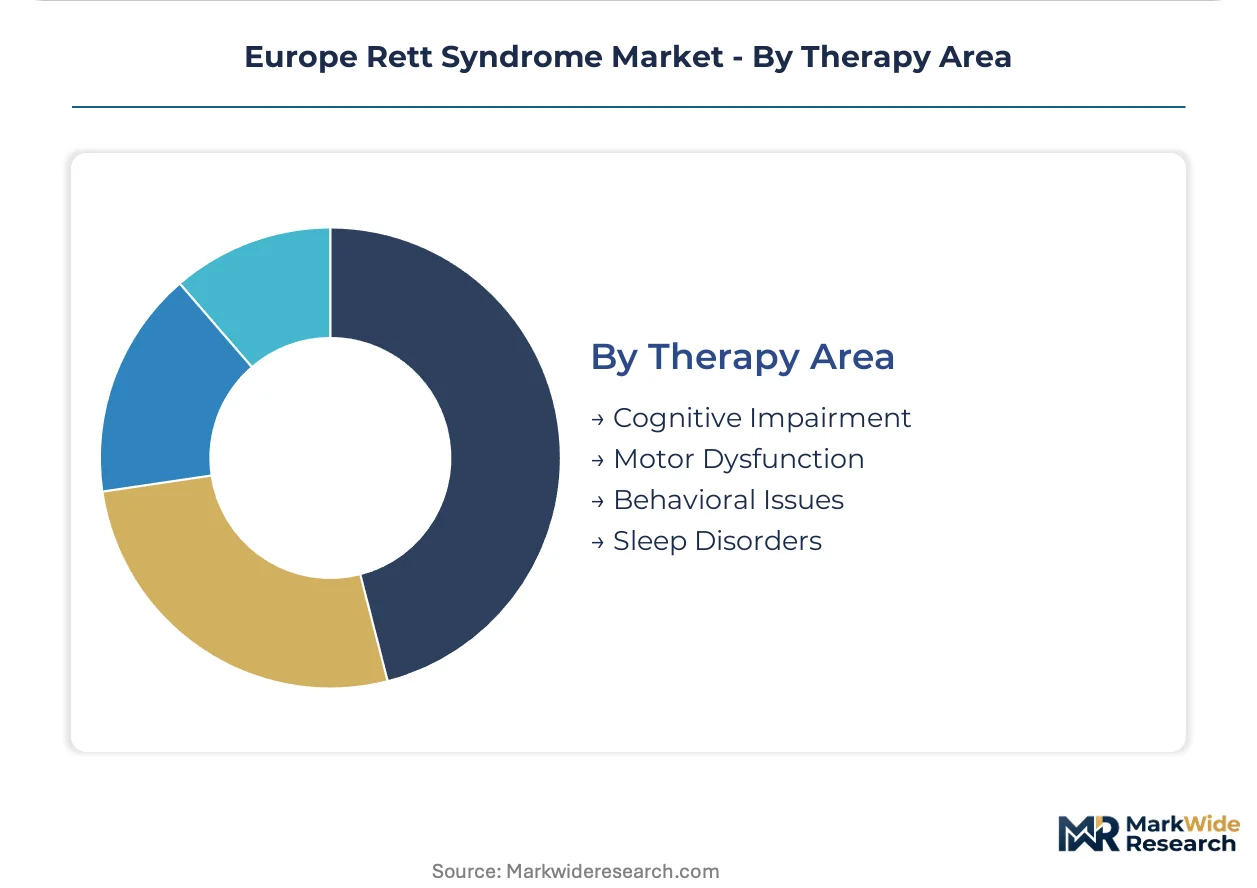
Therapy Area:
Symptom-specific development prioritizes measurable endpoints and caregiver-relevant outcomes. Motor and behavioral domains offer the clearest regulatory pathways.
- Motor Dysfunction:Gait and hand function deterioration drives the largest unmet need and attracts the deepest pipeline investment. United Kingdom and Scandinavian registries provide natural history data for trial design.
- Behavioral Issues:Anxiety and social withdrawal symptoms are addressable through novel small-molecule mechanisms. Benelux markets show payer willingness for symptom-specific reimbursement.
- Cognitive Impairment:Assessment tool standardization remains inconsistent across member states.
- Sleep Disorders:Autonomic dysfunction management lacks validated endpoints.
Motor Dysfunction commands the majority of clinical trial resources. Behavioral Issues show the steepest expansion trajectory as digital biomarkers validate endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany captures deeper gene therapy infrastructure than France, while the United Kingdom accelerates newborn screening integration faster than Southern European counterparts. National reimbursement frameworks and specialized clinic density determine where pharmaceutical sponsors prioritize clinical trial placement.
Germany
IQWiG assessment protocols and statutory health insurance frameworks govern access to disease-modifying Rett syndrome therapeutics. Bavarian university hospitals in Munich and Heidelberg anchor dedicated pediatric neurology centers that coordinate multi-site trials. North Rhine-Westphalia's hospital networks concentrate inpatient gene therapy administration capacity.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning determine reimbursement for novel neurological interventions. London's Great Ormond Street Hospital and Manchester's pediatric neurology clusters maintain Rett syndrome patient registries. Scotland's health boards participate in pan-European natural history data collection.
France
HAS evaluation frameworks and early access programs accelerate conditional reimbursement for rare disease therapies. Parisian academic medical centers in Île-de-France coordinate national reference center networks for neurodevelopmental disorders. Lyon and Marseille host specialized rehabilitation facilities for motor dysfunction management.
Netherlands
Hospital pharmacy procurement committees and bundled care contracts reshape how diagnostic and therapeutic services are purchased. Rotterdam and Amsterdam pediatric hospitals integrate digital biomarker platforms into Rett syndrome monitoring protocols. Dutch patient advocacy organizations coordinate Benelux-wide access negotiations.
Italy
AIFA pricing negotiations and regional health system fragmentation create variable access across Northern and Southern markets. Lombardy's Milan-based pediatric neurology centers concentrate specialized expertise and clinical trial enrollment. Rome and Naples face caregiver workforce shortages that limit supportive care protocol expansion.
Europe Rett Syndrome Market Competitive Landscape
Top-tier vendors anchor disease-modifying therapeutic development, while mid-tier specialists concentrate on symptomatic management and diagnostic platforms. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with rare disease neurology infrastructure, biotechnology firms pursuing gene therapy platforms, and regional diagnostic service providers. Consolidation pressures favor entities with EMA regulatory expertise and established European hospital pharmacy relationships. Competitive moves center on orphan drug exclusivity positioning and pan-European patient registry partnerships.
Within the gene therapy archetype, Taysha Gene Therapies and Anavex Life Sciences exemplify development-stage positioning predicated on MECP2-targeted mechanisms. Among established pharmaceutical entities, Biogen occupies a position leveraging existing rare disease neurology infrastructure and hospital network relationships. Neuren Pharmaceuticals Limited represents the disease-modifying small-molecule approach through trofinetide platform development. AMO Pharma Limited sits within the behavioral symptom specialization tier targeting anxiety and social withdrawal clusters.
| Leading Market Players |
|---|
| Neuren Pharmaceuticals Limited |
| AMO Pharma Limited |
| Biogen |
| AstraZeneca |
| Anavex Life Sciences |
| Taysha Gene Therapies |
| Vyant Bio |
| GW Pharmaceuticals |
| Prilenia Therapeutics Development |
| Others |
Supply & Pricing Matrix
Viral vector manufacturing costs cascade through gene therapy pricing tiers, with European contract manufacturing organization capacity constraints amplifying premium positioning for disease-modifying Rett syndrome candidates while oral small-molecule alternatives exploit established pharmaceutical distribution economics.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for intravenous gene therapy administration, though viral vector production bottlenecks sustain premium tier positioning. Three-tier pricing structure across gene therapy, disease-modifying small-molecule, and supportive care levels reflects reimbursement authorization intensity and manufacturing complexity. Pricing pressure stems from health technology assessment divergence across IQWiG, HAS, and NICE frameworks. Pediatric clinics demonstrate lowest price sensitivity given specialized commissioning budgets, while home care settings face tightening pharmacy tender constraints.
Supply Chain Analysis
Dual-sourcing requirements for MECP2 genetic testing platforms mandate multi-laboratory qualification across Germany, the United Kingdom, and the Netherlands. Raw material dependencies center on viral vector production reagents, specialized neurophysiological device components, and enteral feeding formulations. Single-source vulnerability concentrates in viral vector manufacturing capacity. Distribution runs through hospital pharmacy procurement committees in Benelux markets and specialized pediatric clinic networks in German academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Rett syndrome market represents a late-cycle quality story as demand shifts decisively toward disease-modifying therapeutics with demonstrated neurological function preservation endpoints.
For Market Incumbents: Anticipate gene therapy manufacturing capacity constraints by securing captive viral vector production through backward integration into European contract manufacturing organizations. EMA accelerated assessment pathway compression threatens first-mover exclusivity windows; defend position by deepening pan-European patient registry partnerships that anchor natural history data advantages for comparator arm construction.
For New Entrants and Emerging Players: The EU Paediatric Regulation and associated pediatric investigation plan incentives open a window for behavioral symptom specialization in underserved Southern and Eastern European markets. Target Poland, Czech Republic, and Hungary for diagnostic platform deployment where rare disease infrastructure remains underdeveloped. Pursue digital biomarker integration as the primary go-to-market angle, leveraging wearable autonomic monitoring to differentiate from established supportive care protocols.
For Investors and Strategic Acquirers: Roll-up economics work for specialized pediatric neurology service providers because health system consolidation is concentrating purchasing influence through pan-European rare disease alliances. Five-to-ten year viability hinges on EMA regulatory expertise and established hospital pharmacy relationships. Watch EMA priority medicines scheme designations as the critical inflection signal for pipeline value realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Viral vector production capacity expansion in Bavarian university hospital networks addresses supply bottlenecks constraining patient access. |
| EMA Priority Medicines Pathway Navigation | Accelerated assessment framework exploitation compresses regulatory review timelines for MECP2-targeted candidates. |
| Pan-European Patient Registry Partnership | Natural history data consolidation across German, French, and United Kingdom academic medical centers enables trial comparator arm construction. |
| Digital Biomarker Platform Integration | Wearable autonomic monitoring and eye-tracking technologies validate decentralized clinical trial endpoints for behavioral symptom interventions. |
| Health Technology Assessment Pre-Positioning | Early engagement with IQWiG, HAS, and NICE frameworks shapes reimbursement thresholds before pivotal trial completion. |
Research Methodology
Bottom-up pediatric neurology workflow modeling reconciled against top-down pharmaceutical pipeline tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against EMA submissions, ClinicalTrials.gov records, national health technology assessment databases, and formulary status registries. Cross-referencing manufacturer capacity disclosures with hospital pharmacy tender documentation enables supply-side triangulation against demand projections.
Historical trendline analysis of newborn screening integration rates, specialized clinic network expansion, and gene therapy regulatory approval timelines informs projection mechanics across the analysis window. Segmentation modeling incorporates product type, delivery mode, therapy area, and end-user facility tier dimensions. CAGRs derive from fitted growth curves applied to diagnosed patient population expansion and therapy penetration assumptions, with EMA orphan drug exclusivity provisions and national reimbursement authorization timelines as key forecast inputs.
Revisions become necessary when EMA regulatory pathway modifications, health technology assessment framework harmonization, or gene therapy manufacturing capacity expansions materialize beyond modeled assumptions. Deviation in viral vector production scalability or cross-border patient mobility regulation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Fabry Disease Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market