
 Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market | 2026-2036
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
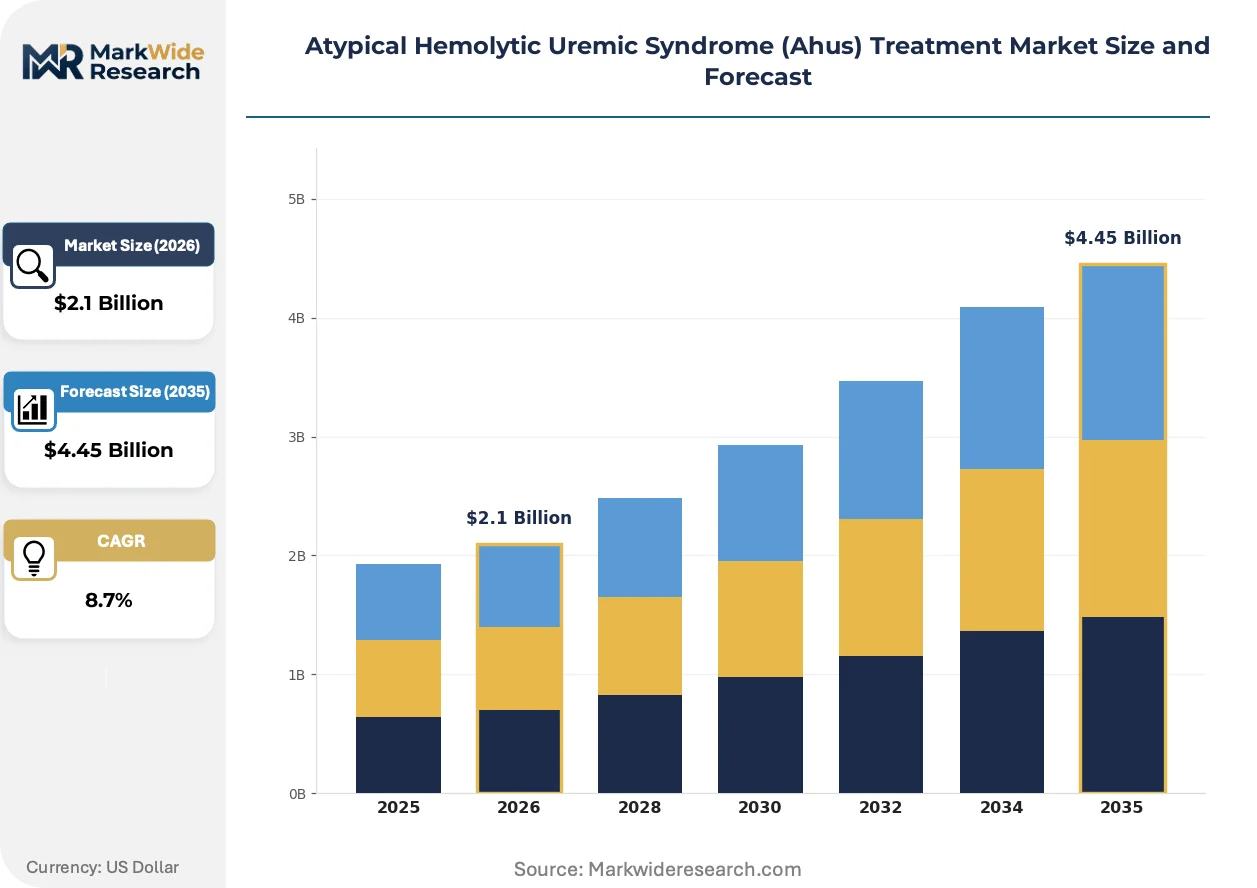
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market Outlook
Chronic management service revenue is reconfiguring margin pools away from acute emergency interventions toward sustained outpatient protocols. Novartis Pharmaceuticals anchors its position through deep specialization in complement pathway therapeutics. AstraZeneca leverages its biologics manufacturing scale to secure supply chain continuity for long-term patient regimens. Hoffmann-La Roche differentiates through integrated diagnostic-to-treatment platforms that streamline physician decision workflows.
Atypical Hemolytic Uremic Syndrome treatment encompasses therapeutic interventions targeting uncontrolled complement activation that destroys red blood cells, platelets, and renal tissue, with monoclonal antibodies and complement inhibitors representing the primary pharmacologic modalities designed to interrupt the terminal complement cascade. The pediatric treatment segment leads clinical investment due to earlier disease onset and longer lifetime therapy horizons, while the intravenous delivery mode retains structural dominance in hospital settings despite emerging subcutaneous alternatives that promise reduced infusion center burden. Complement inhibitors command the deepest margin pools as patent-protected biologics, whereas plasma exchange occupies a mature, cost-constrained position in emergency protocols.
FDA orphan drug designations and EMA priority medicine pathways shape development incentives and accelerate market access for novel complement-targeting agents in the United States and European Union. Reimbursement frameworks administered by national health technology assessment bodies in Germany, France, and England determine patient access thresholds and manufacturer pricing latitude across European markets. Stakeholders must monitor evolving biosimilar entry timelines for established complement inhibitors and prepare portfolio decisions around next-generation subcutaneous formulations.
Market Dynamics
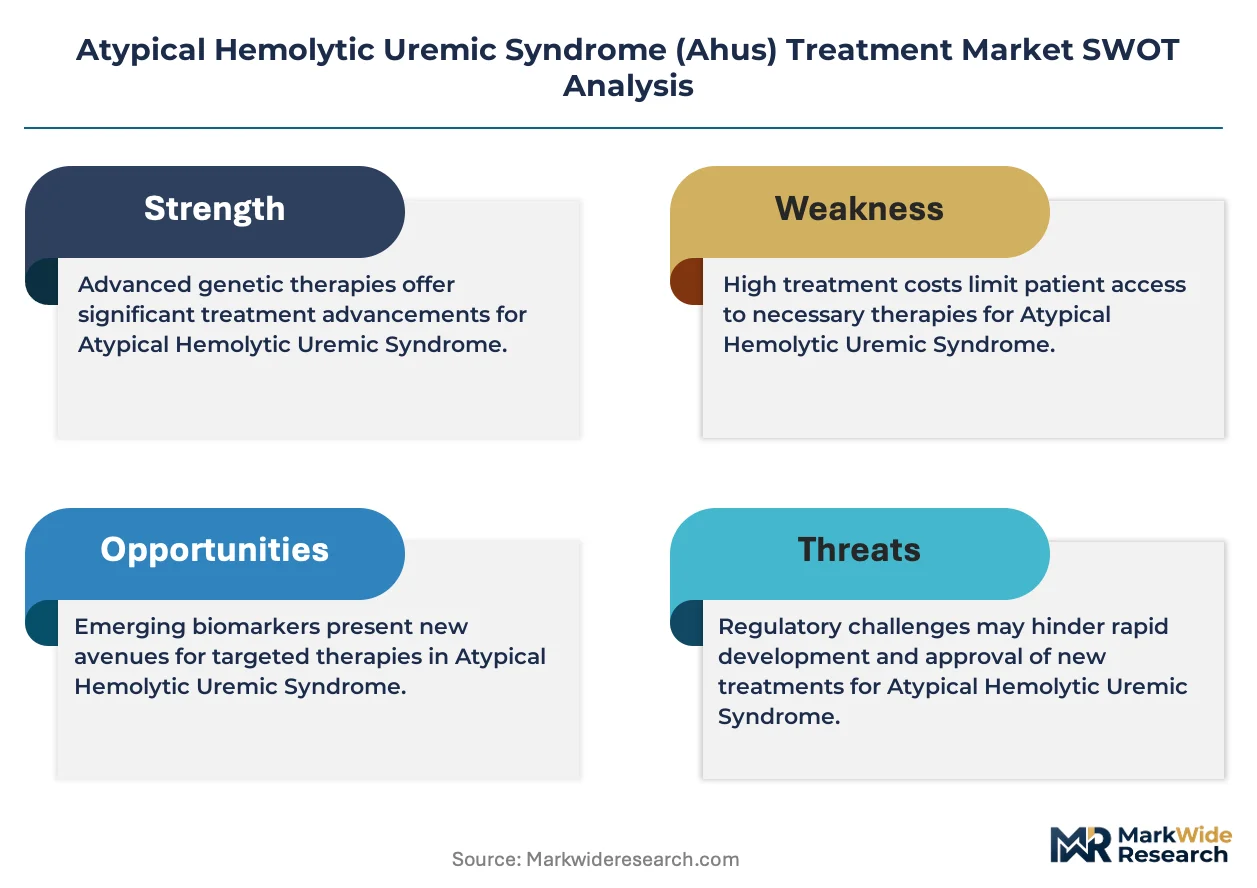
Pediatric treatment protocols are driving a structural reconfiguration toward chronic outpatient management, compressing emergency intervention volumes while extending therapy horizons across lifetime patient cohorts.
Growth Catalysts
- FDA orphan drug pathways:Accelerated review timelines for complement-targeting biologics reduce development-to-commercialization cycles, incentivizing pipeline investment in rare disease modalities.
- Plasma exchange substitution:First-line emergency protocols increasingly favor complement inhibitors over mechanical filtration, elevating biologic utilization in acute presentation settings.
- Germany's AMNOG process:Early benefit assessments for orphan drugs create predictable reimbursement frameworks that stabilize manufacturer pricing power across European hospital procurement.
Market Restraints
- Biologic manufacturing concentration:Single-source fill-finish capacity for monoclonal antibodies creates supply vulnerability concentrated in Belgian and Swiss contract manufacturing networks.
- EMA conditional marketing authorization:Post-approval efficacy confirmation requirements impose revenue clawback risks that constrain pricing latitude for novel entrants.
- Plasma-derived therapy persistence:Emergency department formulary inertia and familiarity with established protocols slow complement inhibitor penetration in acute care settings.
Strategic Opportunities
- Subcutaneous formulation development:Self-administration protocols eliminate infusion center dependency, opening home-based therapy models that reduce healthcare system overhead.
- France's ATU nominative access:Named-patient programs for pre-approval biologics create early revenue streams and real-world evidence generation ahead of formal reimbursement.
- Diagnostic-treatment integration:Complement biomarker testing platforms bundled with therapeutic protocols streamline physician decision workflows and accelerate treatment initiation.
Industry Challenges
- Specialized infusion nursing shortage:Complement inhibitor administration requires trained personnel for adverse event monitoring, constraining site-of-care expansion.
- Biosimilar transition planning:Patent cliff management demands portfolio restructuring around next-generation formulations before reference product exclusivity expires.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Complement Inhibitors, Plasma Exchange, Supportive Care Application: Pediatric Treatment, Adult Treatment, Emergency Care, Chronic Management End User: Hospitals, Specialty Clinics, Home Healthcare, Research Laboratories Delivery Mode: Intravenous, Subcutaneous, Oral, Others |
| Companies Covered | AstraZeneca, Novartis Pharmaceuticals, Hoffmann-La Roche, Omeros Corporation, Chugai Pharmaceutical, Apellis Pharmaceuticals, BioCryst Pharmaceuticals, ChemoCentryx, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market Strategic Shifts
Complement therapeutics are undergoing modality evolution that compresses treatment burden while regulatory frameworks accelerate access pathways for rare disease innovations.
Subcutaneous delivery systems are virtualizing the traditional hospital-based infusion model. Pediatric treatment centers in the United States are piloting home administration programs that reduce center visit frequency from biweekly to monthly intervals. This virtualization is compressing site-of-care revenue pools while shifting margin capture toward device-drug combination products.
REACH authorization requirements for novel biologic substances are tightening environmental release monitoring across European manufacturing facilities. EMA guidance on persistent organic pollutant thresholds now extends to monoclonal antibody production waste streams. Contract manufacturers in Ireland and the Netherlands are investing in closed-loop solvent recovery systems to maintain production licenses.
Hospital pharmacy committees are consolidating orphan biologic purchasing through centralized tender processes that aggregate volume across health system networks. Academic medical centers in England are forming procurement consortia that extract price concessions in exchange for sole-source formulary placement. This concentration is most visible in the NHS England specialized commissioning framework for complement-mediated diseases.
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market Segmentation
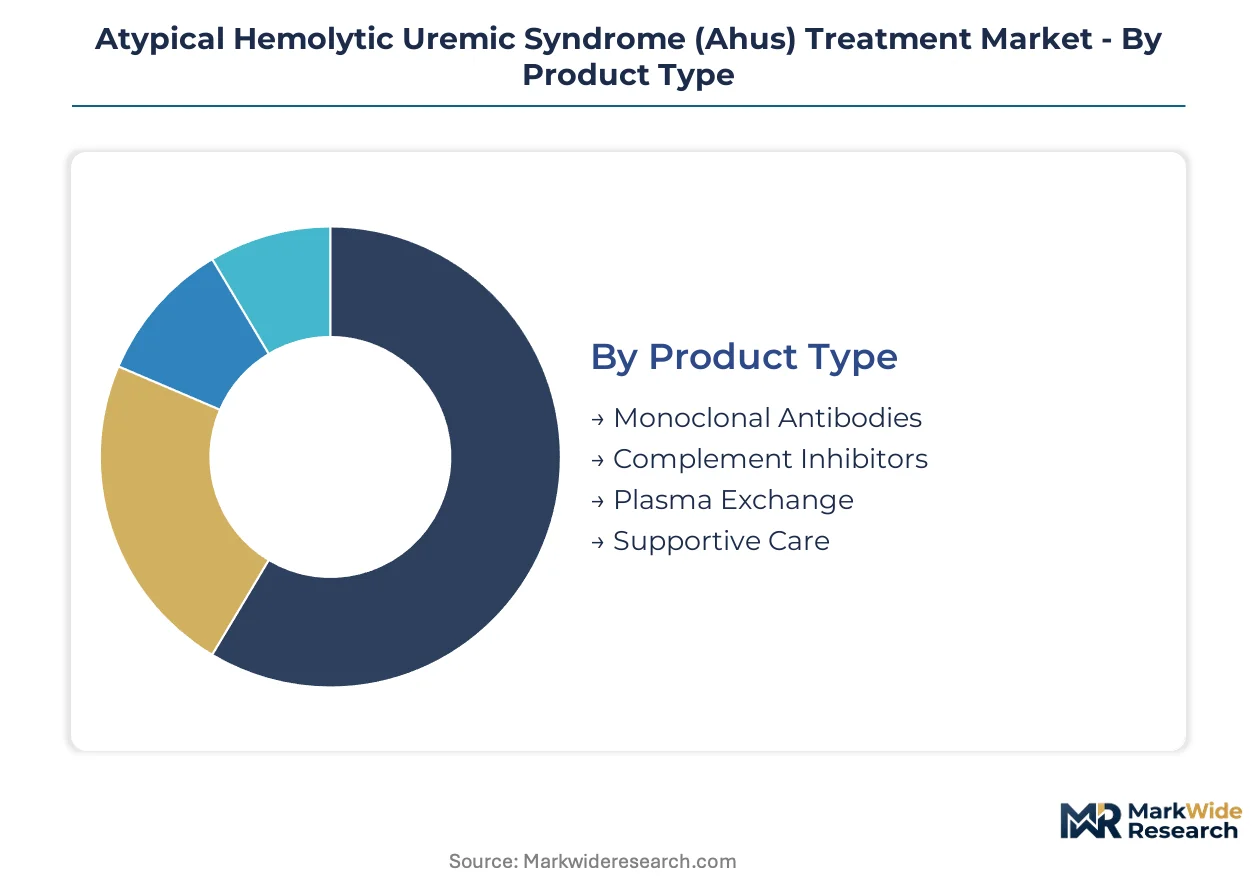
Treatment modality selection in Ahus care hinges on disease acuity, patient age, and site-of-care infrastructure, with each segment demanding distinct service intensity levels across the therapy lifecycle. Segmentation reveals how chronic management protocols are restructuring revenue allocation away from emergency interventions.
Product Type:
After-sales service intensity varies sharply across product categories, with biologics requiring specialized adverse event monitoring and plasma exchange demanding intensive technical support.
- Complement Inhibitors:These biologic agents interrupt the terminal complement cascade through targeted pathway blockade. Demand concentrates in pediatric treatment centers across the United States where lifetime therapy horizons justify premium pricing and dedicated nursing support infrastructure.
- Monoclonal Antibodies:Engineered immunoglobulins bind specific complement proteins to halt hemolytic progression. Germany's university hospitals drive adoption through integrated diagnostic platforms that streamline biomarker-guided dosing protocols.
- Plasma Exchange:Mechanical filtration modality for acute presentations retains established emergency department workflows.
- Supportive Care:Adjunctive interventions including transfusion and renal replacement therapy.
Complement inhibitors hold the largest share; momentum sits with monoclonal antibodies.
Application:
Cost tier stratification separates emergency interventions from chronic outpatient regimens, with pediatric cases commanding sustained investment due to extended treatment durations.
- Pediatric Treatment:Early-onset disease in children necessitates lifetime therapeutic management with specialized dosing protocols. North American academic medical centers anchor demand through dedicated complement-mediated disease programs that coordinate multidisciplinary care teams.
- Chronic Management:Long-term outpatient protocols sustain patient stability through scheduled biologic administration. France's ATU nominative access programs accelerate adoption by enabling pre-approval therapy initiation for stable patients transitioning from acute care.
- Adult Treatment:Later-onset cases requiring individualized dosing adjustments.
- Emergency Care:Acute presentation stabilization in hospital settings.
Pediatric treatment holds the largest share; momentum sits with chronic management.
End User:
Volume concentration shifts toward outpatient venues as subcutaneous formulations reduce hospital dependency, though infusion complexity preserves institutional dominance for high-acuity cases.
- Hospitals:Acute care sites retain structural importance for emergency presentations and initial biologic loading doses. England's NHS specialized commissioning framework aggregates purchasing power across hospital networks, extracting price concessions for sole-source formulary placement.
- Home Healthcare:Self-administration protocols eliminate infusion center burden for stable patients. Pilot programs in United States pediatric centers reduce visit frequency from biweekly to monthly intervals, compressing site-of-care revenue pools.
- Specialty Clinics:Dedicated centers for rare disease management.
- Research Laboratories:Sites for biomarker development and clinical trial execution.
Hospitals hold the largest share; momentum sits with home healthcare.
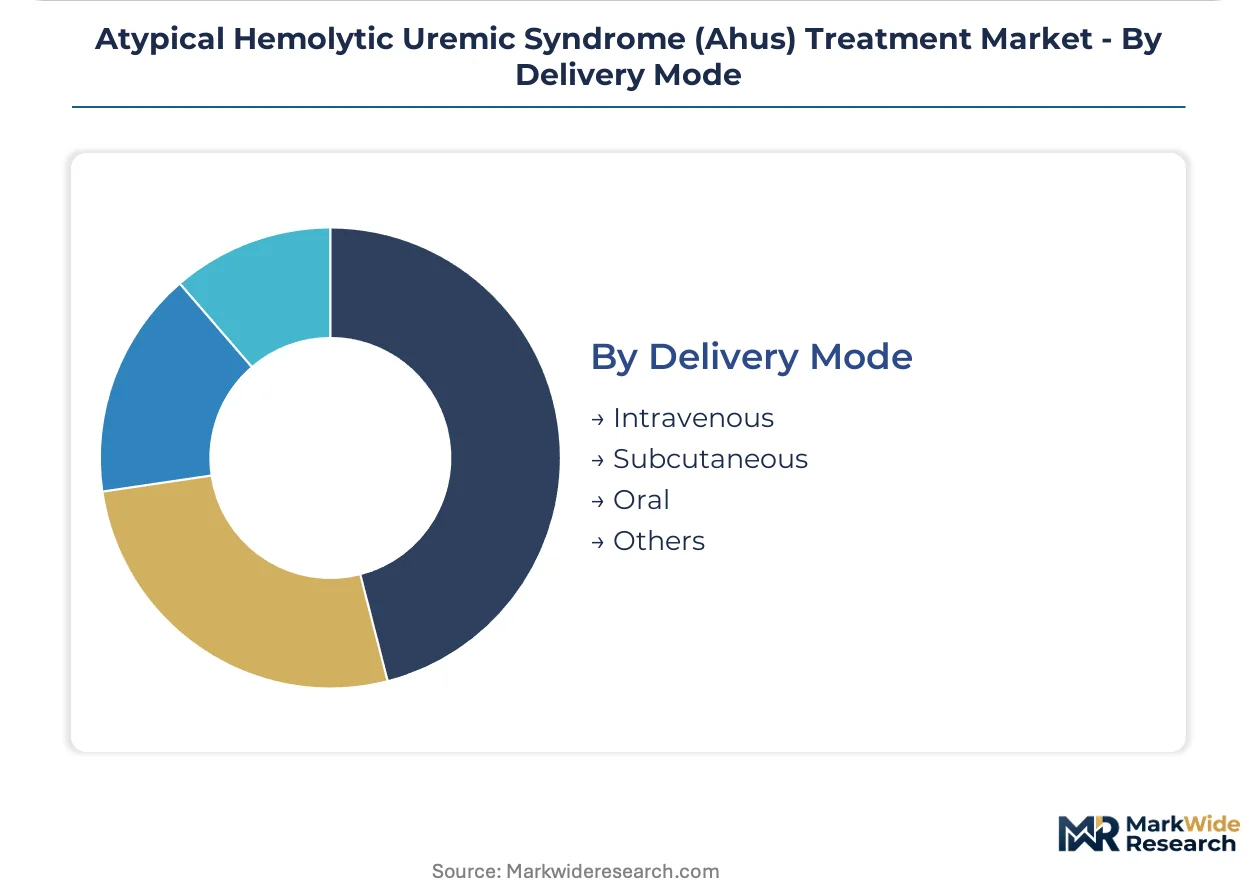
Delivery Mode:
Margin profiles diverge across administration routes, with intravenous formulations commanding premium pricing tied to site-of-care infrastructure while subcutaneous alternatives promise cost reduction through virtualization.
- Intravenous:Hospital-based infusion retains dominance for complement inhibitors requiring adverse event monitoring. Belgian and Swiss contract manufacturing networks concentrate fill-finish capacity for monoclonal antibody production.
- Subcutaneous:Device-drug combinations enable patient self-administration with reduced healthcare system overhead. EMA guidance on REACH authorization requirements is tightening environmental monitoring for manufacturing facilities producing these formulations.
- Oral:Emerging small-molecule alternatives in development pipelines.
- Others:Investigational delivery technologies including depot formulations.
Intravenous holds the largest share; momentum sits with subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with European health technology assessment bodies extracting steeper discounts than US payers who grant broader orphan biologic access. Germany and France demonstrate intermediate sensitivity where early access programs offset formal pricing pressure. The United Kingdom presents the most constrained environment where specialized commissioning frameworks aggregate purchasing power.
United States
Pediatric treatment centers in Boston and Philadelphia anchor North American demand through dedicated complement-mediated disease programs. FDA orphan drug pathways accelerate review timelines for novel biologics, reducing development-to-commercialization cycles. New York and California academic medical centers coordinate multidisciplinary care teams that drive adoption of chronic outpatient protocols.
Germany
University hospitals in Munich and Heidelberg integrate diagnostic platforms that streamline biomarker-guided dosing for monoclonal antibodies. The AMNOG process creates predictable reimbursement frameworks that stabilize manufacturer pricing power across hospital procurement. Bavarian and Baden-Württemberg medical centers concentrate fill-finish capacity for biologic production.
France
Named-patient programs through ATU nominative access generate early revenue streams ahead of formal reimbursement decisions. Paris and Lyon treatment centers pilot home administration programs that reduce infusion center visit frequency. The national health technology assessment body evaluates complement inhibitors through distinct rare disease pathways.
United Kingdom
NHS England specialized commissioning frameworks aggregate purchasing power across hospital networks to extract price concessions. London and Manchester academic medical centers form procurement consortia that secure sole-source formulary placement. NICE technology appraisals impose stringent cost-effectiveness thresholds for orphan biologics.
Switzerland
Swissmedic maintains accelerated authorization pathways for rare disease therapeutics that align with EMA conditional marketing frameworks. Basel and Zurich house contract manufacturing networks that concentrate monoclonal antibody fill-finish capacity. The country's pricing authority references German and French benchmarks while permitting premium positioning for breakthrough therapies.
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market Competitive Environment
Capability concentration sits with specialized biologic developers; scale advantage sits with diversified pharmaceutical conglomerates. The market structures around three tiers: patent-protected originators commanding premium pricing, mid-cap specialists pursuing subcutaneous formulation differentiation, and emerging entrants targeting biosimilar transition windows. Consolidation pressure intensifies as manufacturing capacity constraints favor players with captive Belgian and Swiss fill-finish networks. Portfolio diversification and diagnostic-treatment integration represent the dominant competitive vectors.
Among diversified pharmaceutical conglomerates, Novartis Pharmaceuticals and AstraZeneca occupy positions that exemplify scale-driven archetypes, while Hoffmann-La Roche anchors the integrated diagnostic-to-treatment tier. These three entities represent contrasting strategic postures: deep specialization in complement pathway therapeutics, biologics manufacturing scale securing supply chain continuity, and bundled biomarker testing platforms streamlining physician workflows.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis Pharmaceuticals |
| Hoffmann-La Roche |
| Omeros Corporation |
| Chugai Pharmaceutical |
| Apellis Pharmaceuticals |
| BioCryst Pharmaceuticals |
| ChemoCentryx |
| Regeneron Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Single-source fill-finish dependency for monoclonal antibodies determines both pricing tier spreads and supply chain shape across the Ahus treatment landscape. Belgian and Swiss contract manufacturing concentration creates premium pricing power for originator biologics while exposing purchasers to supply interruption risks that compress margin pools for downstream stakeholders.
Pricing Analysis
After-sales service revenue through dedicated nursing support and adverse event monitoring drives lifetime value capture for complement inhibitors. Three-tier pricing structure across originator biologics, authorized generics, and plasma exchange alternatives separates premium patent-protected agents from cost-constrained emergency modalities. Cost compression in plasma exchange tiers is intensifying because hospital formulary committees increasingly favor biologic substitution. Pediatric treatment centers demonstrate the lowest price sensitivity due to lifetime therapy horizons and orphan drug reimbursement guarantees.
Supply Chain Analysis
Upstream cell culture media and single-use bioreactor systems draw from specialized chemical suppliers concentrated in Germany, Switzerland, and the United States. Belgian fill-finish networks and Swiss packaging operations rest on monoclonal antibody active pharmaceutical ingredient streams sourced from Irish fermentation facilities. Single-source vulnerability pervades the terminal sterilization and aseptic processing stages where regulatory qualification timelines prevent rapid supplier switching. Distribution runs through hospital pharmacy consortia and specialty pharmacy channels that aggregate purchasing power across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized infusion nursing capacity and Belgian-Swiss manufacturing certification constitute binding constraints that determine competitive outcomes. Capability scarcity in these domains rewards early-mover investment and penalizes late entrants lacking established relationships.
For Market Incumbents: Harden supply chain resilience through captive fill-finish capacity expansion in Switzerland before biosimilar entry windows compress originator pricing power. Secure exclusive infusion nursing training partnerships with pediatric academic medical centers in Boston and Philadelphia to lock out emerging subcutaneous competitors from site-of-care expansion. For New Entrants and Emerging Players: Build out home healthcare administration capabilities targeting stable chronic patients in France's ATU nominative access programs where reimbursement pathways remain underdeveloped. France offers the most penetrable geography for subcutaneous formulation entry due to early access program flexibility and limited incumbent nursing infrastructure. For Investors and Strategic Acquirers: The market sits at a formulation-transition phase that favors device-drug combination specialists over pure-play biologic developers. Long-term viability across the next decade hinges on subcutaneous delivery platform ownership rather than monoclonal antibody asset accumulation. Watch EMA conditional marketing authorization revocation rates as the critical signal for pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | REACH authorization compliance in Irish manufacturing facilities enables European market entry. |
| Diagnostic-Treatment Integration | Bundled biomarker platforms with Novartis therapeutic protocols streamline physician prescribing workflows. |
| Infusion Nursing Training Partnerships | Exclusive contracts with Boston pediatric centers lock in site-of-care access against subcutaneous competitors. |
| Belgian Fill-Finish Capacity Expansion | Captive supply of monoclonal antibody finishing reduces single-source vulnerability ahead of biosimilar transitions. |
| ATU Nominative Access Program Entry | Early revenue generation in France precedes formal AMNOG-style reimbursement negotiations. |
Study Parameters
Cross-validation between regulatory filing analysis and hospital procurement database review anchors the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists combined with secondary validation against FDA orphan drug designations, EMA priority medicine pathways, ClinicalTrials.gov entries, and NHS England specialized commissioning frameworks. Bottom-up patient volume modeling and top-down manufacturer revenue analysis provided triangulation across independent estimation approaches.
Calibration against historical biologic launch curves and plasma exchange utilization trends informed the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment modality, patient age cohort, administration route, site-of-care setting, and regional regulatory cluster. CAGRs were derived from S-curve adoption modeling for complement inhibitors and elasticity-adjusted pricing trajectories for plasma exchange alternatives. Biosimilar entry timelines and REACH authorization requirement tightening served as industry-specific forecast inputs.
Sensitivities concentrate around EMA conditional marketing authorization revocation rates, Belgian manufacturing disruption scenarios, and subcutaneous formulation adoption velocity. Forecasts reflect assumptions regarding orphan drug pricing durability and infusion center capacity expansion that could require revision if home administration protocols accelerate beyond modeled penetration rates. Cross-checking against IQVIA national prescription audit data and hospital purchasing consortium contract disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Arthrogryposis Management Market