
 Rett Syndrome Market | 2026-2036
Rett Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Rett Syndrome Market Analysis
Antisense oligonucleotide chemistry is recalibrating drug economics for Rett syndrome interventions, replacing conventional small-molecule approaches with sequence-targeted modalities that command premium pricing and extended exclusivity. Neurogene Inc leverages proprietary gene therapy platforms to sustain a differentiated pipeline position in MECP2-targeted interventions. Acadia Pharmaceuticals anchors its competitive stance through deep psychiatric-neurology channel control, while Anavex Life Sciences Corp specializes in sigma-1 receptor modulation for neurodevelopmental disorders.
Rett syndrome constitutes an X-linked dominant neurodevelopmental disorder caused by mutations in the MECP2 gene, characterized by apparently normal early development followed by regression of acquired skills, stereotypic hand movements, and autonomic dysfunction; therapeutic interventions target MECP2 gene expression modulation, symptomatic management of seizures and respiratory irregularities, and restoration of synaptic function. Gene therapy segments occupy the highest margin pools due to one-time administration profiles and orphan drug pricing frameworks, while symptomatic treatment segments maintain volume leadership through chronic prescribing patterns across pediatric care and rehabilitation applications. Diagnostic kits segments are accelerating fastest as newborn screening panels expand MECP2 testing inclusion across genetic testing laboratories.
FDA accelerated approval pathways and EMA orphan drug designations shape clinical trial investment and market access timelines for developers targeting MECP2-related disorders. The EU AI Act and GDPR frameworks impose data governance requirements on multi-site Rett syndrome natural history studies and real-world evidence collection across European research institutions. Stakeholders must monitor regulatory precedent for adeno-associated virus vector therapies in neurodevelopmental indications, as FDA and EMA decisions on manufacturing consistency and long-term follow-up protocols will determine capital allocation thresholds for platform expansion.
Market Dynamics
Antisense oligonucleotide chemistry is recalibrating therapeutic economics, replacing small-molecule paradigms with sequence-targeted modalities that command extended exclusivity and reshape capital allocation across MECP2 intervention pipelines.
Growth Catalysts
- FDA Accelerated Approval Pathways:Orphan disease frameworks compress clinical trial timelines for gene therapy candidates, reducing time-to-market for MECP2-targeted interventions and attracting venture capital into pediatric neurology development.
- Pediatric Neurology Clinic Expansion:Specialized treatment centers in Boston, New York, and Philadelphia cluster gene therapy expertise, creating referral networks that concentrate patient access and accelerate real-world evidence generation.
- Newborn Screening Panel Integration:MECP2 diagnostic kit inclusion across genetic testing laboratories expands addressable patient identification, shifting intervention windows toward presymptomatic stages.
Market Restraints
- Adeno-Associated Virus Manufacturing Bottlenecks:Limited contract development and manufacturing organization capacity for neurodevelopmental gene therapy vectors constrains batch consistency and scales production costs.
- EU AI Act Data Governance:Multi-site natural history studies face compliance friction from GDPR and artificial intelligence regulations, slowing real-world evidence collection across European research institutions.
- One-Time Gene Therapy Pricing Compression:Orphan drug reimbursement frameworks face payer resistance to seven-figure single-administration therapies, creating access barriers despite clinical efficacy.
Strategic Opportunities
- Presymptomatic Intervention Windows:Expanded newborn screening creates addressable populations before developmental regression, enabling disease-modifying therapies prior to neuronal damage accumulation.
- Sigma-1 Receptor Modulation Adjuncts:Combination regimens pairing gene expression restoration with synaptic function stabilizers offer differentiated positioning in symptomatic management segments.
- EMA Orphan Drug Incentives:European regulatory designations provide protocol assistance, fee reductions, and market exclusivity extensions that improve gene therapy program economics.
Industry Challenges
- Neurodevelopmental Gene Therapy Talent Scarcity:Clinical investigators with pediatric central nervous system viral vector delivery expertise remain concentrated at a handful of academic medical centers, limiting trial site expansion.
- Long-Term Follow-Up Protocol Complexity:FDA and EMA requirements for fifteen-year post-administration safety monitoring create data infrastructure burdens and patient retention costs that strain development-stage budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rett Syndrome Market |
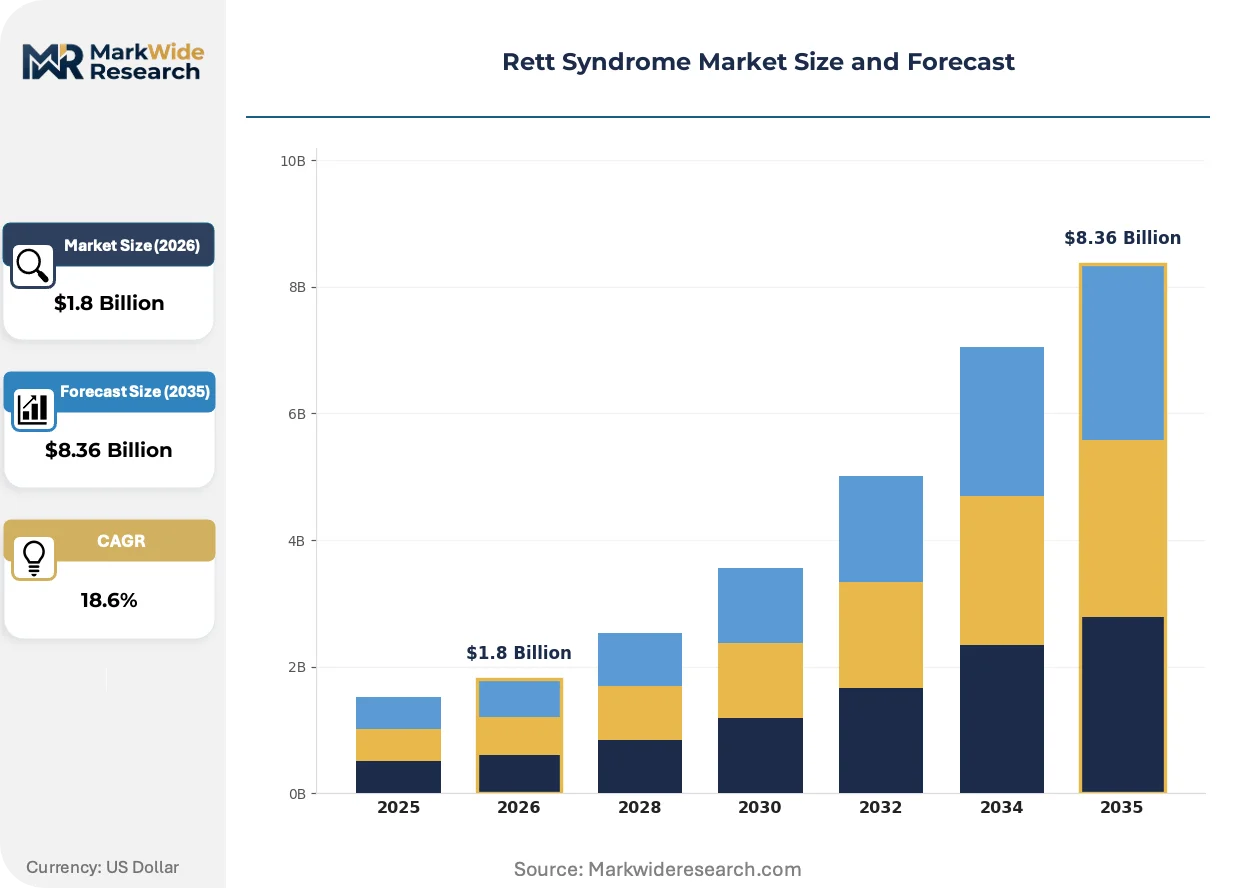
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Symptomatic Treatment, Diagnostic Kits, Research Tools Application: Pediatric Care, Genetic Testing, Rehabilitation, Clinical Trials Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Specialty Clinics, Research Institutions, Home Care |
| Companies Covered | Neurogene Inc, Acadia Pharmaceuticals, Anavex Life Sciences Corp, Amorsa Therapeutics Inc, Biohaven Pharmaceutical Holding Company Ltd, AMO Pharma Ltd, Taysha Gene Therapies Inc, AveXis Inc, Neuren Pharmaceuticals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rett Syndrome Market Emerging Trajectories
Gene therapy platforms are absorbing manufacturing and regulatory complexity, while diagnostic modalities expand presymptomatic detection capabilities and reshape intervention timing across the therapeutic landscape.
Antisense oligonucleotide chemistry is absorbing development investment from traditional small-molecule programs. Sequence-targeted modalities enable MECP2 transcript modulation with precision unavailable to conventional pharmacology. Pediatric neurology clinics are absorbing these compounds into early-phase protocols, compressing the timeline between genetic diagnosis and therapeutic intervention.
EMA orphan drug designations are reshaping European clinical trial investment patterns. Protocol assistance and fee reductions improve program economics for MECP2-targeted developers. EU AI Act and GDPR frameworks are forcing data governance investments across multi-site natural history studies, with research institutions in Germany and France deploying compliant infrastructure ahead of regulatory enforcement.
Diagnostic kit procurement is rotating toward integrated newborn screening panels. State-level public health laboratories are absorbing MECP2 testing into standard genetic screening arrays, displacing reactive family-history-based testing. This behavioral shift concentrates demand in the United States, where specialized treatment center networks align with expanded screening mandates to compress time-to-diagnosis intervals.
Rett Syndrome Market Segmentation
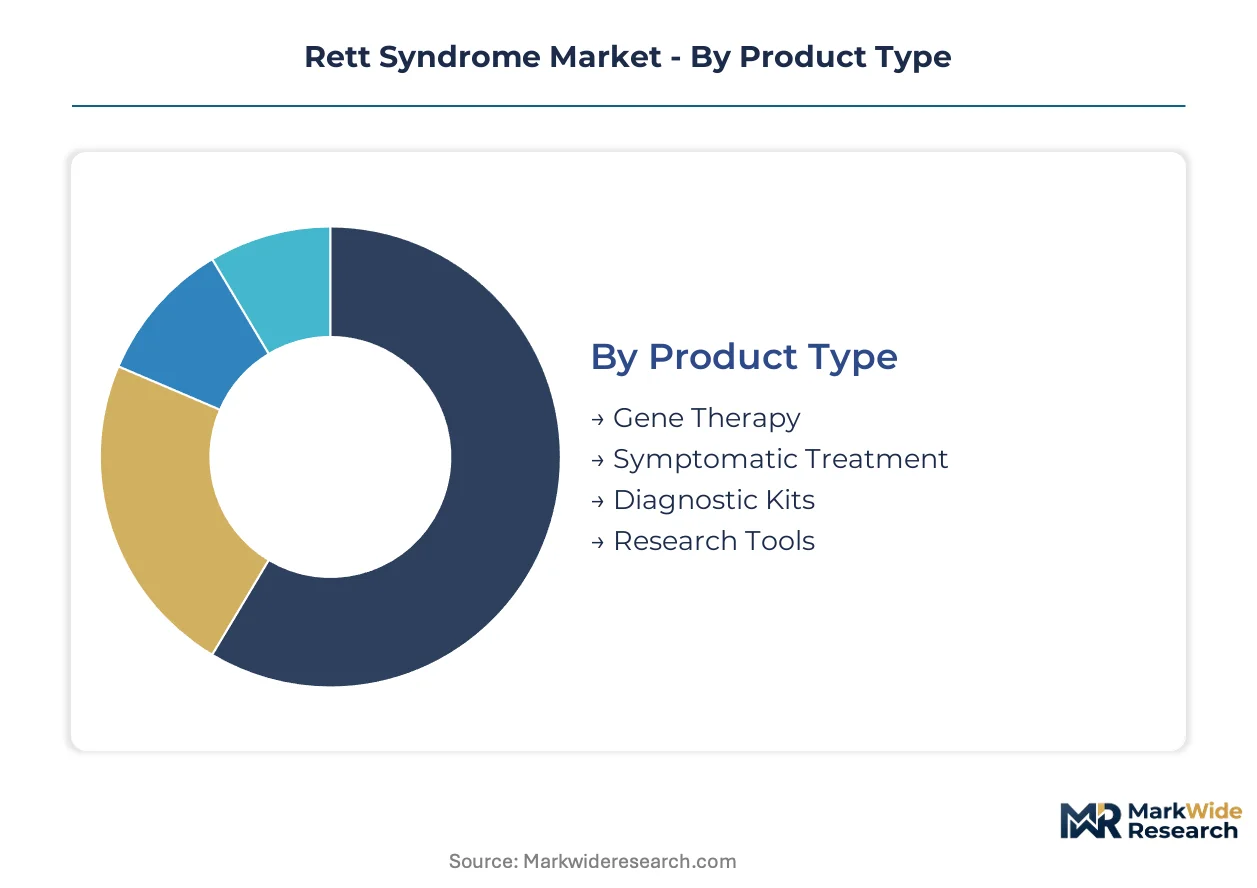
Segmentation in the Rett syndrome market tracks how capital flows across distinct therapeutic modalities and care settings. Each category reveals where pricing power concentrates and which intervention windows command premium investment.
Product Type:
Supply concentration for MECP2-targeted interventions tilts toward viral vector manufacturing hubs in Massachusetts and Pennsylvania.
- Gene Therapy:Adeno-associated viral vectors deliver functional MECP2 copies directly to neuronal populations. Demand clusters at Boston Children's Hospital and Children's Hospital of Philadelphia gene therapy centers, where surgical expertise for intrathecal administration creates referral bottlenecks.
- Symptomatic Treatment:Chronic prescribing of antiepileptics, respiratory stabilizers, and gastrointestinal motility agents sustains volume across pediatric neurology practices. Prescription concentration follows Medicaid reimbursement patterns in states with expanded rare disease coverage.
- Diagnostic Kits:qPCR and sequencing-based MECP2 mutation detection platforms.
- Research Tools:iPSC-derived neuronal models and MECP2 reporter cell lines for preclinical screening.
Gene Therapy absorbs the bulk of installed capacity; Diagnostic Kits are expanding most quickly.
Application:
Cost tier stratification separates one-time disease-modifying interventions from chronic symptomatic management across care pathways.
- Pediatric Care:Multidisciplinary teams coordinate neurology, gastroenterology, and orthopedics for progressive symptom management. Care concentration at Rett Syndrome Center at Texas Children's Hospital and similar specialized units drives protocol standardization.
- Genetic Testing:Newborn screening integration and family cascade testing expand presymptomatic identification. State public health laboratories in New York and California anchor procurement volume through mandated screening panels.
- Rehabilitation:Physical, occupational, and communication therapy for retained and regained function.
- Clinical Trials:Natural history studies and interventional protocols for regulatory submission.
Pediatric Care commands the highest per-patient expenditure; Genetic Testing is climbing the fastest as screening mandates proliferate.
Delivery Mode:
Volume distribution across administration routes reflects the anatomical constraints of blood-brain barrier penetration and patient tolerance.
- Intravenous:Systemic AAV9 delivery for broad CNS transduction requires specialized infusion centers with ICU backup. Site accreditation by the American Society of Gene and Cell Therapy concentrates capacity at academic medical centers.
- Oral:Small-molecule sigma-1 receptor modulators and symptomatic agents sustain chronic compliance. Formulation development targets palatability and swallowing coordination challenges in the Rett patient population.
- Subcutaneous:Antisense oligonucleotide depot formulations for sustained MECP2 transcript modulation.
- Inhalation:Respiratory-targeted delivery for autonomic dysfunction management.
Intravenous absorbs the bulk of gene therapy investment; Oral maintains volume leadership through chronic prescribing patterns.
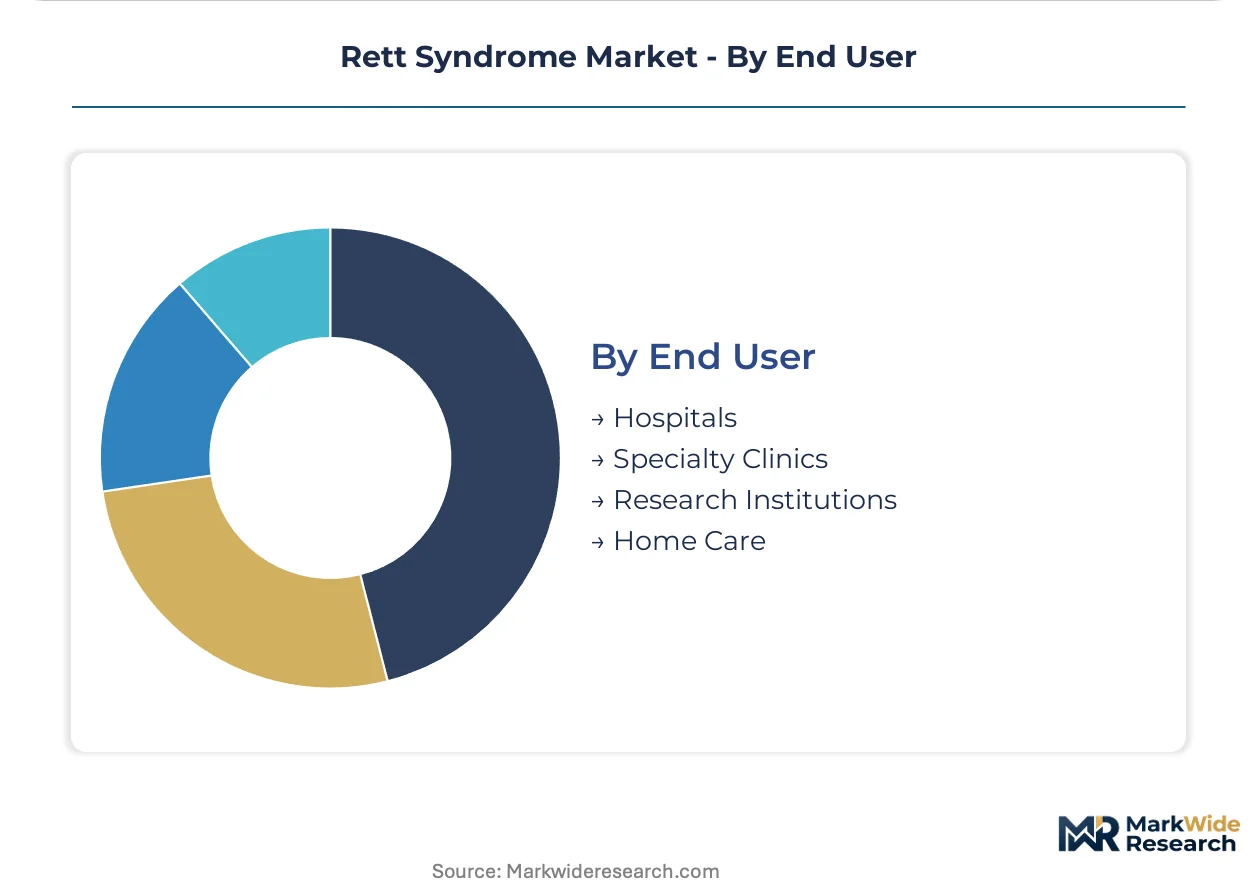
End User:
Customer type determines procurement sophistication, with research institutions demanding technical specifications that hospitals rarely require.
- Hospitals:Inpatient gene therapy administration and acute complication management anchor high-acuity revenue. Capacity constraints at Boston-area academic medical centers create waitlist dynamics for FDA-approved interventions.
- Specialty Clinics:Dedicated Rett syndrome centers in New York, Philadelphia, and Chicago coordinate longitudinal care. These sites generate real-world evidence through systematic outcome tracking and natural history data collection.
- Research Institutions:University-based gene therapy programs and natural history study sites.
- Home Care:Family-administered symptomatic therapies and monitoring equipment.
Hospitals absorb the bulk of acute intervention capacity; Specialty Clinics are gaining share fastest through care coordination mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized Rett syndrome treatment centers concentrate patient access and research infrastructure in specific metropolitan clusters across four countries, with regulatory frameworks and reimbursement policies determining commercial viability in each market.
United States
FDA accelerated approval pathways compress gene therapy development timelines for MECP2-targeted interventions. The Orphan Drug Act provides seven-year market exclusivity and tax credits for clinical trial expenditures. Boston, New York, and Philadelphia anchor specialized pediatric neurology networks where gene therapy expertise clusters at academic medical centers.
Germany
EMA orphan drug designations attract protocol assistance and fee reductions for Rett syndrome developers seeking European market access. The country's national pharmaceutical regulator maintains stringent manufacturing standards for adeno-associated viral vectors. Heidelberg and Munich host university-based gene therapy programs with established pediatric neurology research infrastructure.
United Kingdom
NHS England's specialized commissioning framework determines reimbursement for one-time gene therapies in rare neurodevelopmental disorders. The Medicines and Healthcare products Regulatory Agency participates in EMA centralized procedures while maintaining national flexibility. London's Great Ormond Street Hospital anchors pediatric gene therapy expertise with established intrathecal administration protocols.
Japan
PMDA's regenerative medicine and gene therapy consultation pathways provide early regulatory guidance for MECP2-targeted developers. The country's national health insurance system faces adaptation challenges for seven-figure single-administration therapies. Tokyo and Osaka concentrate pediatric neurology research at university hospitals with longitudinal natural history study capabilities.
Canada
Health Canada's priority review pathways for rare neurological disorders align with FDA timelines for gene therapy submissions. Provincial drug plan negotiations create reimbursement fragmentation across the national market. Toronto's Hospital for Sick Children maintains pediatric gene therapy expertise with established viral vector manufacturing partnerships.
Rett Syndrome Market Vendor Landscape
Strategic partnerships dominate the current landscape as developers secure manufacturing capacity and regulatory expertise for MECP2-targeted programs. The vendor base organizes around three tiers: gene therapy platform specialists, psychiatric-neurology incumbents with channel control, and sigma-1 receptor modulation researchers. Two archetypes define competitive positioning: viral vector delivery innovators and symptomatic management incumbents. Portfolio diversification into presymptomatic intervention windows and combination regimens represents the dominant competitive move alongside geographic expansion into European markets through EMA orphan drug pathways.
Among gene therapy platform specialists, Neurogene Inc exemplifies the viral vector delivery archetype with MECP2-targeted intervention capabilities. Acadia Pharmaceuticals anchors the psychiatric-neurology channel control position. Anavex Life Sciences Corp occupies a differentiated research position focused on sigma-1 receptor modulation for neurodevelopmental applications. These three entities represent distinct strategic approaches to Rett syndrome therapeutic development without overlapping core technological platforms.
| Leading Market Players |
|---|
| Neurogene Inc |
| Acadia Pharmaceuticals |
| Anavex Life Sciences Corp |
| Amorsa Therapeutics Inc |
| Biohaven Pharmaceutical Holding Company Ltd |
| AMO Pharma Ltd |
| Taysha Gene Therapies Inc |
| AveXis Inc |
| Neuren Pharmaceuticals Ltd |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing of adeno-associated viral vectors at academic medical centers in Massachusetts and Pennsylvania anchors supply security for gene therapy developers while simultaneously constraining pricing flexibility through high fixed-cost absorption. This integration pattern concentrates bargaining power with contract development and manufacturing organizations serving symptomatic treatment segments, where outsourced production enables competitive pricing against chronic prescribing alternatives.
Pricing Analysis
Volume leadership in symptomatic treatment segments contrasts with margin concentration in gene therapy, where one-time administration profiles command orphan drug premiums. Price differentiation hinges on FDA breakthrough therapy designation status and intrathecal delivery complexity, with certified gene therapy centers extracting service premiums for surgical administration. Pricing pressure stems from Medicaid reimbursement negotiations for seven-figure single-administration therapies, creating access friction despite clinical efficacy. State public health laboratories exhibit highest price sensitivity for diagnostic kit procurement, while specialized pediatric neurology clinics demonstrate lowest sensitivity for disease-modifying interventions.
Supply Chain Analysis
Domestic-content mandates for critical biologics manufacturing are reshaping sourcing patterns for viral vector production, with FDA guidance on chemistry, manufacturing, and controls driving facility investment toward United States-based capacity. Geographic supply concentration centers on Massachusetts, Pennsylvania, and North Carolina for AAV vector manufacturing, with Germany and Switzerland anchoring European production through EMA-certified facilities. Raw material dependencies include plasmid DNA, HEK293 cell lines, and specialized chromatography resins. Single-source vulnerability for high-purity reagents creates supply chain risk. Distribution runs through cold-chain logistics networks serving academic medical centers with gene therapy accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
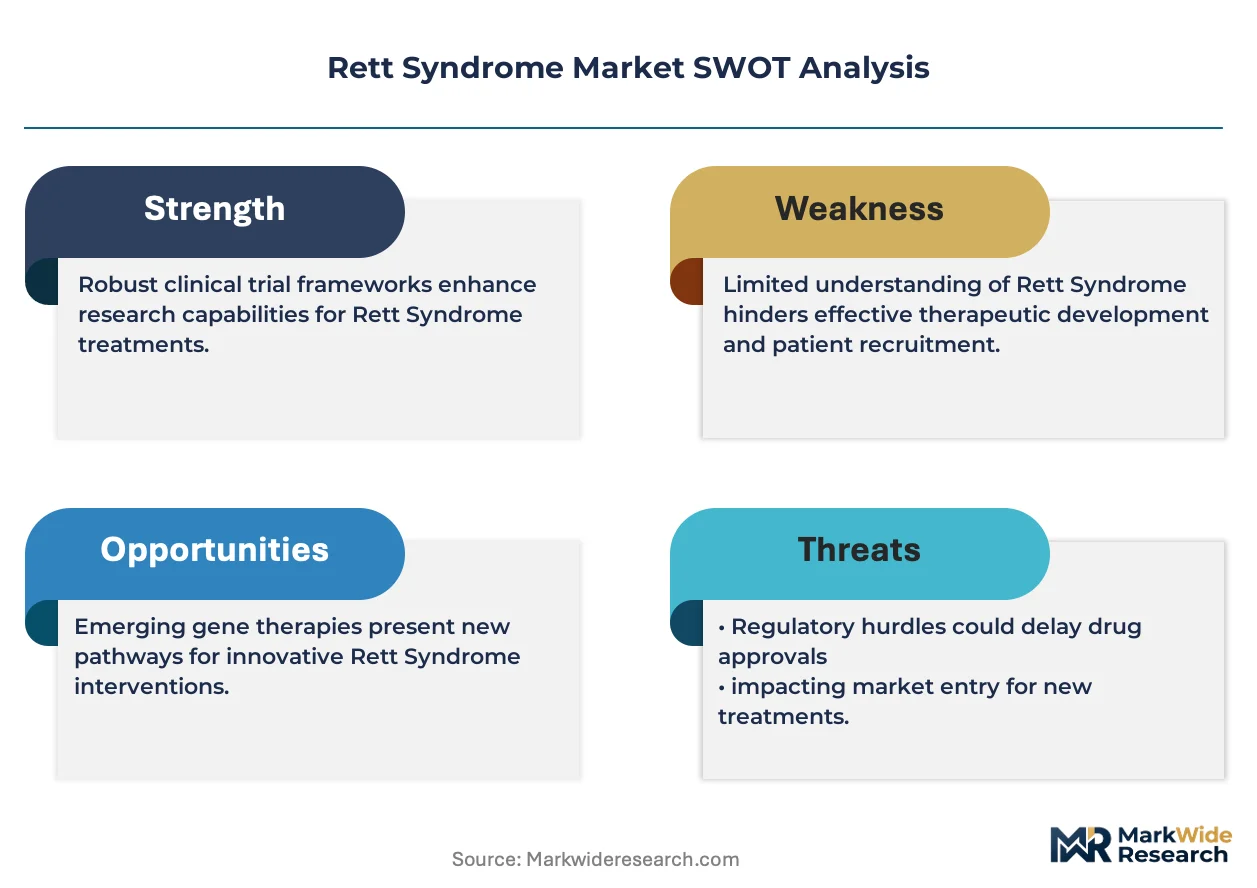
This market represents a consolidation play as manufacturing scale requirements and fifteen-year post-administration safety monitoring protocols force capital-constrained developers toward strategic exit or acquisition.
For Market Incumbents: Extend manufacturing capacity through backward integration into plasmid DNA production, reducing dependency on single-source suppliers for critical viral vector inputs. Deepen channel control by establishing exclusive partnerships with Boston Children's Hospital and Children's Hospital of Philadelphia gene therapy centers, creating referral network lock-in against emerging antisense oligonucleotide competitors. Invest in FDA breakthrough therapy designation pursuit to secure accelerated approval timelines and pricing premiums. For New Entrants and Emerging Players: Antisense oligonucleotide manufacturing expertise offers a technology-first wedge into the presymptomatic intervention window created by expanded newborn screening panels. Target state public health laboratory diagnostic kit procurement, where MECP2 testing integration into mandated screening arrays creates volume expansion opportunity with lower regulatory barriers than therapeutic development. Pursue sigma-1 receptor modulation combination regimens as a go-to-market angle, positioning alongside gene therapy rather than competing directly. For Investors and Strategic Acquirers: Exit pathways concentrate in gene therapy platform acquisitions by psychiatric-neurology incumbents seeking pipeline diversification. Long-term viability over the next decade hinges on successful navigation of fifteen-year post-administration safety monitoring infrastructure requirements and payer reimbursement frameworks for one-time therapies. Target acquisition archetype: developers with EMA orphan drug designation and established intrathecal administration protocols. Watch FDA decisions on AAV vector manufacturing consistency as the critical inflection signal for capital allocation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses development timelines for MECP2-targeted interventions. |
| Manufacturing Scale-Up | Captive AAV vector production at Boston and Philadelphia academic centers reduces batch-to-batch variability. |
| Regulatory Approval Pathway | EMA orphan drug designation provides protocol assistance and fee reductions for European market entry. |
| Pipeline Diversification | Sigma-1 receptor modulation adjuncts create differentiated positioning in symptomatic management segments. |
| Strategic Partnership | Exclusive referral networks with specialized Rett syndrome centers concentrate patient access and real-world evidence generation. |
Methodological Framework
Multi-period observation of newborn screening panel integration, gene therapy clinical trial enrollment, and antisense oligonucleotide development investment anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and state public health laboratory procurement databases. Bottom-up patient population estimates and top-down therapeutic category spend analysis were triangulated for market sizing.
Input-output matrices modeled gene therapy, symptomatic treatment, diagnostic kit, and research tool segments across pediatric care, genetic testing, rehabilitation, and clinical trial applications. Treatment line, administration route, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from patient identification rate trajectories, intervention timing shifts, and pricing evolution assumptions. Forecast inputs included FDA accelerated approval pathway utilization rates and EMA orphan drug designation timelines.
Several conditions sit outside the modeled scope, including regulatory rejection of AAV vector therapies for neurodevelopmental indications, manufacturing contamination events forcing clinical holds, and payer coverage denials for seven-figure single-administration therapies. Forecasts reflect assumptions documented across these parameters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Arthrogryposis Management Market