
 Global Pediatric Drugs Market | 2026-2036
Global Pediatric Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Drugs Market Foresight
Hospital pharmacy procurement is fragmenting as integrated delivery networks in the United States and Western Europe negotiate direct contracts with manufacturers, bypassing traditional wholesale intermediaries. Sanofi leverages its established pediatric vaccine infrastructure to sustain long-term institutional relationships across multiple continents. Pfizer competes through backward integration into active pharmaceutical ingredient production for pediatric formulations, reducing supply vulnerability. Merck anchors its position in the infectious disease segment through sustained investment in pediatric antimicrobial development programs.
Pediatric drugs encompass pharmaceutical agents formulated, dosed, and evaluated specifically for neonatal, infant, child, and adolescent populations, with bioavailability adjusted for developmental pharmacokinetics including hepatic enzyme maturation and renal clearance rates. These products serve the clinical imperative of treating conditions in age groups historically excluded from adult-centric drug development, ensuring therapeutic efficacy without toxicity from inappropriate dosing. Vaccines occupy the largest revenue pool within product type segmentation due to universal immunization schedules and bulk procurement by national health programs, while respiratory drugs represent the fastest-expanding category driven by rising pediatric asthma prevalence and biologic therapy penetration. Within therapy area segmentation, infectious diseases maintains mature volume leadership though neurological disorders commands superior pricing power due to orphan drug designations and limited therapeutic alternatives.
The FDA's Pediatric Research Equity Act and the EMA's Paediatric Regulation collectively mandate pediatric investigation plans as conditions of market authorization, forcing sponsors to allocate R&D resources earlier in development cycles or face delayed approvals. WHO prequalification standards for pediatric formulations shape access dynamics in low-income countries by determining which products qualify for bulk procurement through global health initiatives. Stakeholders must monitor evolving regulatory convergence between the FDA and EMA on extrapolation frameworks, as harmonized approaches to adult-to-pediatric efficacy bridging will reshape trial design economics and competitive timelines for sponsors operating across both jurisdictions.
Market Dynamics
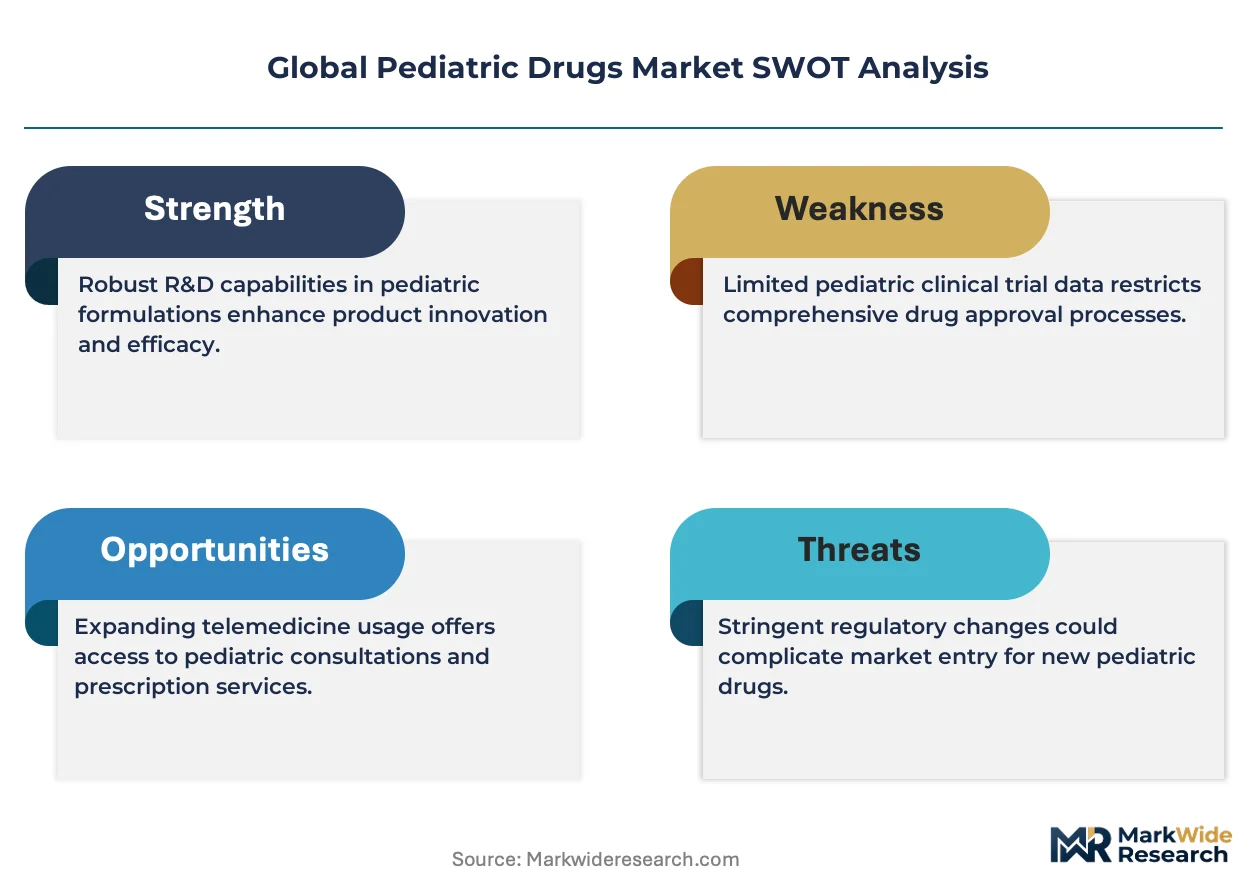
Hospital formulary committees are intensifying scrutiny of pediatric antibiotic procurement, prioritizing narrow-spectrum agents over broad-spectrum alternatives. This shift is compressing margins for legacy manufacturers while rewarding sponsors with targeted development programs.
Growth Catalysts
- FDA Pediatric Research Equity Act:Mandates pediatric study plans for all new drug applications, forcing sponsors to allocate R&D resources earlier in development cycles and expanding the addressable trial population.
- Neonatal intensive care unit expansion:Academic medical centers in the United States are scaling NICU bed capacity, creating sustained demand for age-appropriate formulations with adjusted bioavailability profiles.
- Biologic therapy penetration:Monoclonal antibodies targeting pediatric asthma and atopic conditions are capturing formulary slots previously reserved for small-molecule corticosteroids.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for pediatric formulations clusters in China and India, exposing sponsors to geopolitical friction and customs delays.
- Formulation complexity costs:Taste-masking technologies and age-appropriate dosing vehicles require specialized excipients with volatile pricing tied to petrochemical feedstocks.
- Extrapolation limitations:EMA and FDA divergence on adult-to-pediatric efficacy bridging forces redundant trial designs, inflating development timelines for sponsors operating across both jurisdictions.
Strategic Opportunities
- WHO prequalification pathway:Pediatric formulations meeting WHO standards gain access to bulk procurement through Gavi and UNICEF supply agreements, opening volume contracts in low-income African and South Asian markets.
- Rare disease orphan designations:Neurological disorder indications in pediatric populations command premium pricing and extended exclusivity periods due to limited therapeutic alternatives.
- Integrated delivery network direct contracting:United States hospital systems are bypassing wholesale intermediaries, creating channel for manufacturers with institutional sales infrastructure.
Industry Challenges
- Pediatric pharmacokinetic modeling expertise:Qualified investigators capable of designing developmental pharmacology trials remain concentrated at select academic medical centers, creating recruitment bottlenecks.
- Legacy manufacturing line retrofitting:Adult-dose production facilities require capital-intensive reconfiguration to handle low-volume, high-SKU pediatric batches with distinct stability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Drugs Market |
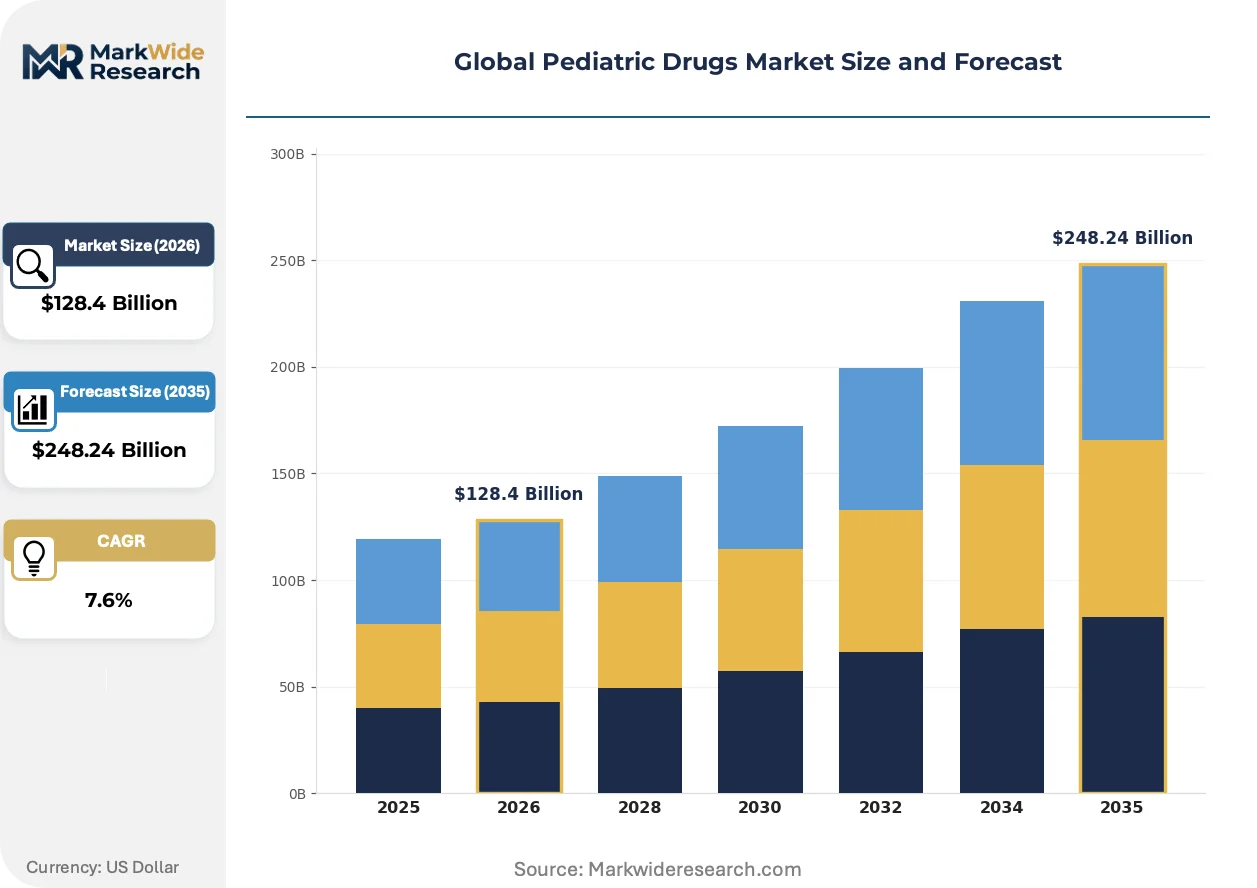
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $248.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Analgesics, Respiratory Drugs, Antipyretics, Hormones Therapy Area: Respiratory Disorders, Infectious Diseases, Neurological Disorders, Gastrointestinal Conditions, Endocrine Disorders, Dermatological Conditions End User: Hospitals, Pediatric Clinics, Rehabilitation Centers, Specialty Pharmacies, Ambulatory Care Centers, Community Health Centers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Direct Sales, Wholesale Distributors, Mail Order Pharmacies |
| Companies Covered | Sanofi, Merck, Pfizer, AstraZeneca, Roche, Novartis, Johnson & Johnson, Abbott Laboratories, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Drugs Market Shifts & Advancements
Developmental pharmacology modeling is replacing traditional dose-finding studies, compressing trial timelines while maintaining regulatory rigor. Three interconnected shifts are reshaping how pediatric therapies reach commercialization.
Physiologically-based pharmacokinetic modeling is collapsing the traditional age-stratified trial design paradigm. PBPK platforms simulate drug absorption and clearance across neonatal, infant, and adolescent maturation stages. Sponsors at Roche and Novartis are embedding these tools into Phase I protocols, reducing the number of pediatric subjects required for dosing validation. The structural consequence is a compression of ethical review timelines and faster enrollment at sites with limited pediatric populations.
EMA's Paediatric Investigation Plan deadlines are hardening enforcement of pediatric study completion before adult market authorization. The regulation now triggers automatic deferral penalties for sponsors missing agreed timelines. Oncology and infectious disease programs face the steepest compliance burdens, with sponsors in Germany and France accelerating internal PIP submission teams to avoid launch delays.
Integrated delivery networks in the United States are consolidating antibiotic procurement under centralized pharmacy and therapeutics committees. These committees now mandate therapeutic interchange protocols that favor narrow-spectrum agents with documented resistance profiles. The shift is most visible in Texas and California health systems, where formulary restrictions have displaced legacy broad-spectrum pediatric antibiotics within 18-month implementation windows.
Global Pediatric Drugs Market Segmentation
Pediatric drug segmentation reveals distinct commercial architectures across formulation types, clinical applications, and procurement channels. Each category carries unique margin profiles, regulatory burdens, and customer loyalty dynamics that reshape competitive strategy.
Product Type:
After-sales service intensity varies sharply across pediatric formulations, with biological products demanding cold chain maintenance and adverse event monitoring that small-molecule generics cannot match.
- Vaccines:Temperature-sensitive biological formulations requiring continuous cold chain integrity from manufacturing through administration. Demand concentrates in national immunization programs across India, Brazil, and Nigeria where bulk procurement through Gavi partnerships shapes pricing. WHO prequalification status determines supplier eligibility for these volume contracts.
- Respiratory Drugs:Inhalation devices and nebulized formulations calibrated for pediatric lung capacity and coordination development. Pediatric asthma clinics in Texas, California, and England drive formulary adoption of biologic monoclonal antibodies. Device training requirements create stickier prescriber relationships than oral alternatives.
- Antibiotics:Narrow-spectrum agents prioritized by hospital antimicrobial stewardship committees.
- Analgesics:Weight-based dosing formulations with taste-masking technologies for compliance.
- Antipyretics:Liquid suspensions dominating over-the-counter pediatric segments.
- Hormones:Growth hormone and thyroid replacement therapies requiring specialty pharmacy dispensing.
By volume, Vaccines leads. By growth pace, Respiratory Drugs is ahead.
Therapy Area:
Cost tier stratification separates premium biologic therapies from commoditized acute care categories, with neurological and endocrine indications commanding 10-15x pricing multiples over infectious disease treatments.
- Infectious Diseases:Antimicrobial and antiviral agents addressing bacterial, viral, and parasitic infections in immunologically immature populations. Hospital formulary committees in Germany, France, and Japan intensify scrutiny of resistance profiles. Narrow-spectrum development programs now outcompete legacy broad-spectrum portfolios.
- Neurological Disorders:Antiepileptics, ADHD medications, and rare disease therapies with orphan drug designations. Academic medical centers in Massachusetts, Pennsylvania, and Switzerland anchor prescriber influence. Limited therapeutic alternatives sustain premium pricing and extended exclusivity.
- Respiratory Disorders:Asthma, cystic fibrosis, and bronchopulmonary dysplasia treatments spanning maintenance and rescue categories.
- Gastrointestinal Conditions:Acid suppression, antiemetics, and motility agents for functional disorders.
- Endocrine Disorders:Growth hormone deficiency, diabetes, and thyroid conditions requiring chronic monitoring.
- Dermatological Conditions:Eczema, psoriasis, and acne formulations with age-appropriate vehicle selection.
By revenue concentration, Neurological Disorders leads. By patient volume, Infectious Diseases dominates.
End User:
Customer type fragmentation creates divergent procurement rhythms, with integrated delivery networks consolidating hospital purchasing while community health centers depend on public program reimbursement.
- Hospitals:Inpatient and emergency departments with pharmacy and therapeutics committee oversight. Academic medical centers in the United States, England, and Australia concentrate Phase I-II trial enrollment. Neonatal intensive care unit expansion drives demand for age-appropriate formulations.
- Pediatric Clinics:Outpatient settings with chronic disease management and preventive care focus. Private practice networks in Ontario, Quebec, and Bavaria represent high-volume prescription channels. Vaccine administration anchors recurring patient visits.
- Rehabilitation Centers:Post-acute and developmental therapy settings with specialized medication needs.
- Specialty Pharmacies:Limited distribution networks for biologics and orphan drugs requiring REMS compliance.
- Ambulatory Care Centers:Same-day surgical and infusion settings with formulary alignment to parent health systems.
- Community Health Centers:Federally qualified sites serving Medicaid-eligible populations with 340B pricing access.
By procurement scale, Hospitals lead. By prescription growth, Pediatric Clinics is expanding most quickly.
Distribution Channel:
Supply concentration in wholesale and retail intermediaries is fragmenting as direct contracting and digital platforms displace traditional channel structures.
- Hospital Pharmacies:Captive dispensing integrated with electronic health record systems and clinical decision support. Centralized procurement across Texas, California, and New York health systems bypasses wholesale markups. Therapeutic interchange protocols favor contracted manufacturers.
- Online Pharmacies:Digital platforms with home delivery and subscription models for chronic therapies. Regulatory frameworks in Germany, the Netherlands, and Switzerland determine cross-border dispensing permissions. Convenience positioning captures caregiver loyalty for refill medications.
- Retail Pharmacies:Community-based dispensing with pharmacist counseling and over-the-counter adjacencies.
- Direct Sales:Manufacturer-to-institution contracts for vaccines and biologics with cold chain requirements.
- Wholesale Distributors:Traditional intermediaries facing margin compression from channel disintermediation.
- Mail Order Pharmacies:PBM-affiliated dispensing for 90-day maintenance prescriptions.
By transaction volume, Hospital Pharmacies leads. By channel growth, Online Pharmacies shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric study mandates anchor commercial strategy in the United States, while EMA Paediatric Investigation Plans reshape development timelines across European sponsors. Academic medical centers in Massachusetts, Basel, and Cambridge concentrate Phase I-II trial enrollment. Manufacturing scale clusters in Indian API hubs and Chinese formulation centers.
United States
Neonatal intensive care unit expansion across Texas and California health systems drives demand for age-appropriate formulations. The FDA's Pediatric Research Equity Act mandates pediatric study plans for all new drug applications, compressing development timelines. Academic medical centers in Boston and Philadelphia anchor the majority of Phase I-II pediatric investigations.
Germany
Hospital antimicrobial stewardship committees in Bavaria and North Rhine-Westphalia prioritize narrow-spectrum pediatric antibiotics over legacy broad-spectrum alternatives. The EMA's Paediatric Regulation enforces automatic deferral penalties for sponsors missing investigation plan deadlines. Pharmaceutical development clusters in Frankfurt-Rhine-Main and Munich sustain contract research organization density.
India
Domestic vaccine procurement through the Universal Immunization Program generates volume demand for WHO-prequalified formulations. The national pharmaceutical regulator enforces pediatric labeling standards aligned with CDSCO guidelines. API manufacturing concentrates in Hyderabad and Ahmedabad, supplying global generic pediatric formulation sponsors.
Japan
Pediatric asthma biologic penetration accelerates formulary adoption in Tokyo and Osaka metropolitan hospital systems. PMDA pediatric trial guidelines emphasize extrapolation frameworks for adult-to-pediatric efficacy bridging. Developmental pharmacology expertise clusters at Nagoya and Kyoto academic medical centers.
Switzerland
Orphan drug designation pathways for pediatric neurological disorders sustain premium pricing in Zurich and Geneva specialty pharmacy networks. Swissmedic pediatric investigation requirements align with EMA Paediatric Investigation Plan deadlines. Basel anchors Roche and Novartis headquarters with embedded physiologically-based pharmacokinetic modeling capabilities.
Global Pediatric Drugs Market Competitive Landscape
Global vaccine infrastructure sponsors and integrated API manufacturers split the market along vertical control vectors. Consolidation characterizes the biological segment, while generic oral formulations fragment across regional players. Three archetypes dominate: multinational vaccine platform operators, backward-integrated API producers, and rare disease biologic specialists. Capacity expansion in cold chain distribution and strategic partnerships for developmental pharmacology modeling represent the primary competitive moves.
Within the vaccine platform tier, Sanofi and Merck exemplify multinational infrastructure scale, with Sanofi leveraging established pediatric immunization networks and Merck anchoring infectious disease segment positions. Pfizer occupies the integrated manufacturing archetype through backward integration into active pharmaceutical ingredient production. Among Swiss-based biologic developers, Roche and Novartis represent the modeling-intensive developmental pharmacology approach, embedding physiologically-based pharmacokinetic platforms into early-phase protocols.
| Leading Market Players |
|---|
| Sanofi |
| Merck |
| Pfizer |
| AstraZeneca |
| Roche |
| Novartis |
| Johnson & Johnson |
| Abbott Laboratories |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
API supply concentration in China and India determines both pricing tier spreads and supply chain shape, with single-source dependencies for narrow-spectrum pediatric antibiotics creating vulnerability premiums that compress margins for non-integrated sponsors while rewarding backward-integrated manufacturers with captive production.
Pricing Analysis
The customization-premium spread separates standard oral suspensions from configured-to-order biologic formulations with cold chain requirements. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity and regulatory certification tier. Cost compression in generic oral categories stems from formulary committee therapeutic interchange mandates. Community health centers exhibit highest price sensitivity due to 340B pricing constraints, while specialty pharmacies serving orphan neurological indications demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for pediatric formulation sponsors. Active pharmaceutical ingredient production clusters in China, India, and Switzerland, with formulation finishing distributed across Germany, the United States, and Japan. Supply chains draw from petrochemical-derived excipients for taste-masking technologies and temperature-controlled logistics for biologics. Single-source vulnerability in hepatic enzyme maturation modeling expertise creates recruitment bottlenecks at academic medical centers. Distribution runs through hospital pharmacies with electronic health record integration and direct manufacturer contracting for vaccine volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Pediatric Research Equity Act mandates reshape competitive timelines, compressing development cycles and forcing R&D resource reallocation earlier in sponsor pipelines.
For Market Incumbents: Build regulatory submission infrastructure moats by embedding physiologically-based pharmacokinetic modeling capabilities into Phase I protocols. Accelerate internal pediatric investigation plan submission teams to preempt EMA automatic deferral penalties. Add cold chain distribution capacity in Texas and California health systems to capture NICU expansion demand. Consolidate formulary relationships through therapeutic interchange protocol compliance for narrow-spectrum antibiotic portfolios.
For New Entrants and Emerging Players: Pursue WHO prequalification pathways for bulk procurement eligibility in Gavi and UNICEF supply agreements. Target low-income African and South Asian markets with volume-contracted vaccine formulations where incumbent infrastructure gaps persist. Enter through developmental pharmacology modeling services for sponsors lacking in-house PBPK capabilities. Capture pediatric asthma biologic market share in Texas and California ambulatory settings with device training bundled offerings.
For Investors and Strategic Acquirers: EMA Paediatric Investigation Plan deadline enforcement reshapes the acquisition landscape by penalizing sponsors with compliance gaps. Long-term viability centers on rare disease neurological disorder portfolios with orphan drug exclusivity extensions. Target acquisition archetypes include Swiss-based biologic developers with embedded modeling platforms and Indian API manufacturers with WHO-prequalified pediatric formulation capabilities. Signal to monitor: FDA-EMA convergence on extrapolation frameworks that would compress redundant trial designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Paediatric Investigation Plan submission accelerates market authorization timelines across European jurisdictions. |
| Manufacturing Scale-Up | Cold chain distribution expansion in Texas and California captures NICU bed capacity growth. |
| Backward Integration | Captive API production in India reduces exposure to China-India customs friction and tariff volatility. |
| Clinical Trial Advancement | PBPK modeling embedding at Basel and Boston academic centers compresses ethical review timelines. |
| Strategic Partnership | WHO prequalification alliances unlock Gavi and UNICEF bulk procurement volume contracts. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up modeling triangulated against top-down market sizing anchored the projections.
Forecast inputs span product type, therapy area, end user, and distribution channel dimensions across the analysis window. CAGRs derive from segment-level growth trajectory modeling incorporating regulatory mandate compliance timelines, NICU capacity expansion patterns, and biologic therapy penetration rates. Patient population epidemiology and procurement channel shift assumptions inform volume projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by API-integrated generic sponsors or PBPK platform specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Global Montelukast Sodium Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market