
 Metachromatic Leukodystrophy Market | 2026-2036
Metachromatic Leukodystrophy Market Size, Share, and Industry Trends Forecast 2026-2036
Metachromatic Leukodystrophy Market Intelligence
Specialized gene therapy manufacturing capacity is collapsing across contract development organizations, forcing pharmaceutical developers to internalize vector production or face multi-year enrollment delays. Orchard Therapeutics anchors European clinical infrastructure for metachromatic leukodystrophy programs. Bluebird Bio sustains US-based lentiviral vector manufacturing for rare disease indications. Takeda Pharmaceuticals leverages Japanese regulatory relationships to accelerate Asia-Pacific trial access.
Metachromatic leukodystrophy is a lysosomal storage disorder caused by arylsulfatase A deficiency, resulting in sulfatide accumulation and progressive demyelination of the central and peripheral nervous systems; treatment aims to halt neurodegeneration through enzyme restoration or functional gene correction. Gene therapy segments command premium reimbursement due to one-time administration and curative intent, while enzyme replacement therapy maintains stable demand for late-diagnosed patients with existing neurological damage. Supportive care occupies substantial service revenue pools across rehabilitation centers and home nursing networks, though margin accretion remains limited by genericized intervention protocols.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for metachromatic leukodystrophy candidates, though post-approval pharmacovigilance obligations intensify long-term follow-up costs. The EU AI Act and GDPR impose data governance requirements on predictive biomarker algorithms used for patient stratification in gene therapy trials. Stakeholders must monitor evolving manufacturing standards from ISO and national gene therapy regulators to secure supply chain continuity for personalized viral vector production.
Market Dynamics
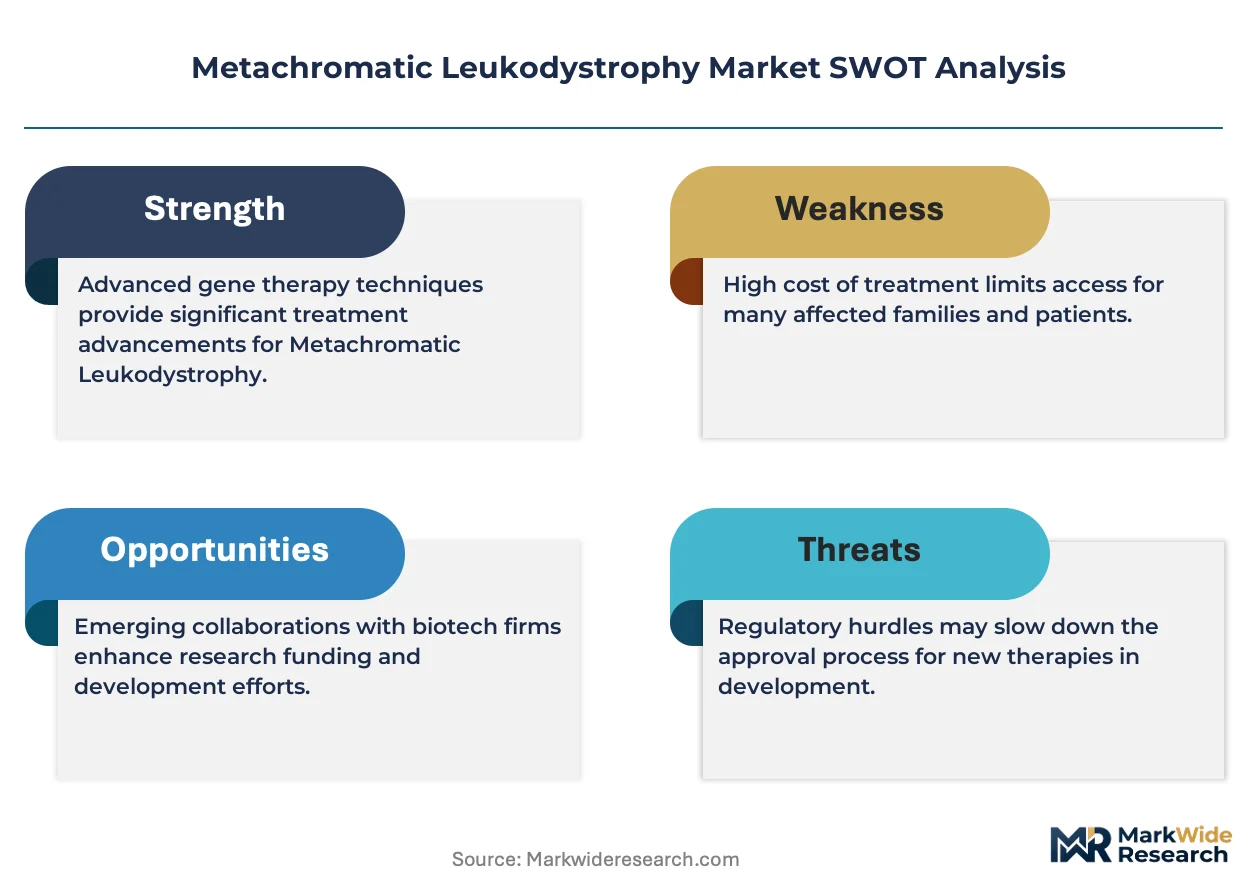
Gene therapy manufacturing capacity constraints are compressing clinical trial timelines and forcing developers to secure captive vector production, fundamentally restructuring competitive positioning in rare disease therapeutics.
Growth Catalysts
- FDA breakthrough therapy designation:This pathway accelerates review timelines for metachromatic leukodystrophy candidates, compressing development cycles and enabling earlier patient access.
- Pediatric treatment centers:Specialized leukodystrophy clinics in the United States, Germany, and Japan are consolidating patient referral networks and streamlining gene therapy enrollment.
- EMA PRIME eligibility:Enhanced regulatory support from the European Medicines Agency reduces approval risk and attracts venture investment into European clinical infrastructure.
Market Restraints
- Viral vector supply concentration:Contract development organizations face multi-year backlogs for lentiviral vector manufacturing, forcing developers to internalize production at substantial capital cost.
- Post-approval pharmacovigilance obligations:Long-term follow-up requirements for gene therapies intensify cost structures and complicate reimbursement negotiations with payers.
- EU AI Act compliance:Predictive biomarker algorithms for patient stratification face stringent data governance requirements, extending validation timelines.
Strategic Opportunities
- Japanese regulatory relationships:Takeda Pharmaceuticals demonstrates how established PMDA engagement can accelerate Asia-Pacific trial access for orphan indications.
- Late-diagnosed patient enzyme replacement:Patients with existing neurological damage represent stable demand for enzyme replacement therapy where gene therapy is contraindicated.
- Home nursing networks:Supportive care service revenue pools expand through decentralized rehabilitation models, though margin accretion remains constrained by genericized protocols.
Industry Challenges
- Specialized gene therapy talent scarcity:Vector process development and analytical characterization expertise concentrates at a handful of academic medical centers and specialized contract manufacturers.
- ISO manufacturing standard evolution:Changing international standards for personalized viral vector production require continuous facility requalification and supply chain revalidation.
- GDPR clinical data architecture:European data protection requirements complicate multi-site trial data integration and long-term patient monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metachromatic Leukodystrophy Market |
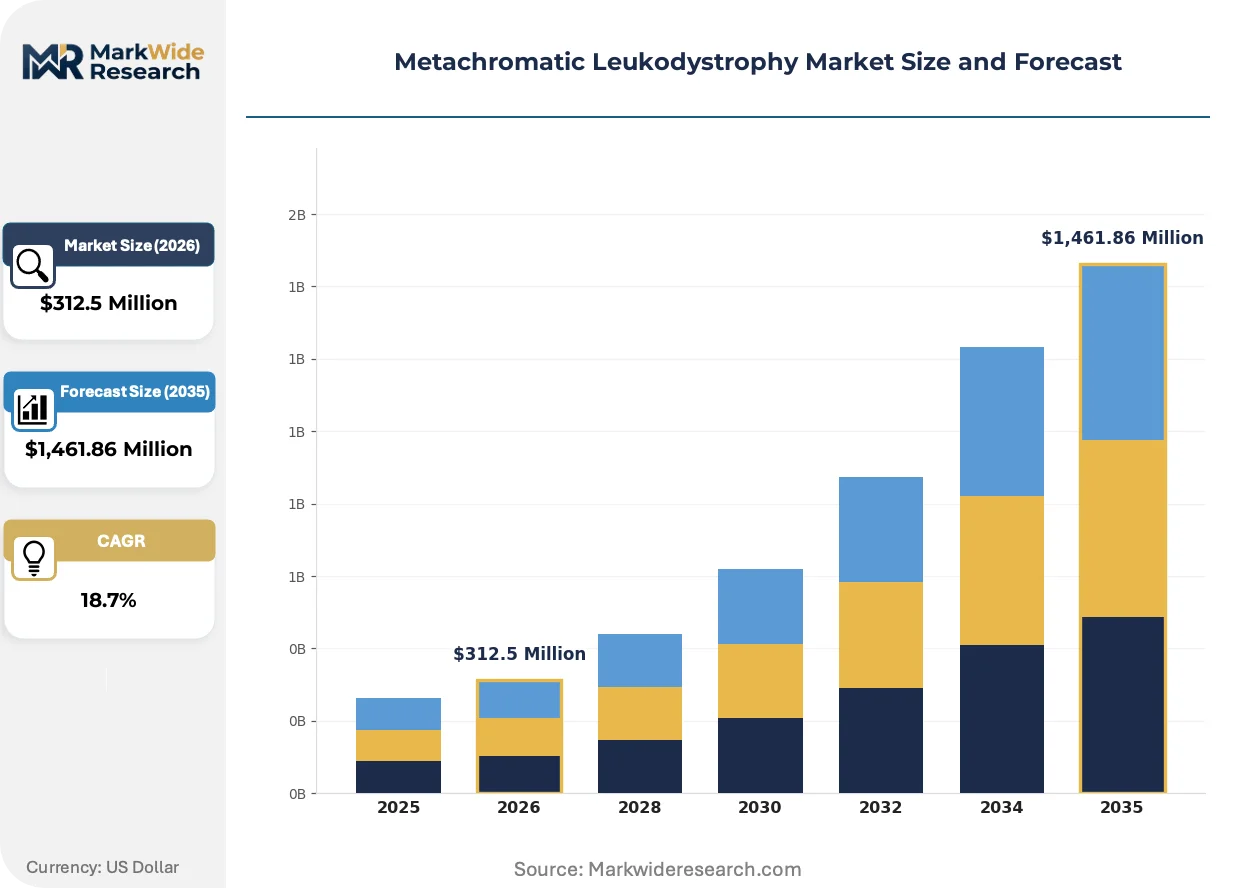
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Supportive Care, Antisense Oligonucleotides Application: Pediatrics, Adults, Clinical Trials, Research End User: Hospitals, Rehabilitation Centers, Home Care, Research Institutions Treatment Method: Intravenous Infusion, Subcutaneous Injection, Oral Administration, Gene Editing |
| Companies Covered | Sanofi, Orchard Therapeutics, BioMarin Pharmaceutical, Bluebird Bio, JCR Pharmaceuticals, GSK plc, Takeda Pharmaceuticals, Recursion Pharmaceuticals, REGENXBIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metachromatic Leukodystrophy Market Strategic Shifts & Innovations
Advanced therapy medicinal products are reshaping competitive positioning through manufacturing sophistication, regulatory pathway innovation, and patient access model redesign across pediatric neurodegenerative indications.
Lentiviral vector production is bifurcating between centralized GMP facilities and distributed point-of-care manufacturing systems. Pediatric gene therapy centers in Boston and London are adopting rapid-turnaround vector release protocols. This technology compression is enabling trial sponsors to reduce patient screening-to-treatment intervals from months to weeks.
EMA's PRIME scheme and FDA's breakthrough therapy designation are converging to create harmonized accelerated assessment frameworks. Developers now design single protocols satisfying both agencies' evidentiary requirements. Gene therapy segments for metachromatic leukodystrophy are responding with unified global pivotal trials rather than sequential regional submissions.
Hospital procurement departments are unbundling gene therapy administration from bundled payment models. Specialized leukodystrophy centers in Munich and Philadelphia are negotiating carve-out contracts separating the therapeutic product from infusion and monitoring services. This purchasing pattern shift is most visible in the United States where Medicare Advantage plans pilot indication-based pricing for one-time curative therapies.
Metachromatic Leukodystrophy Market Segmentation
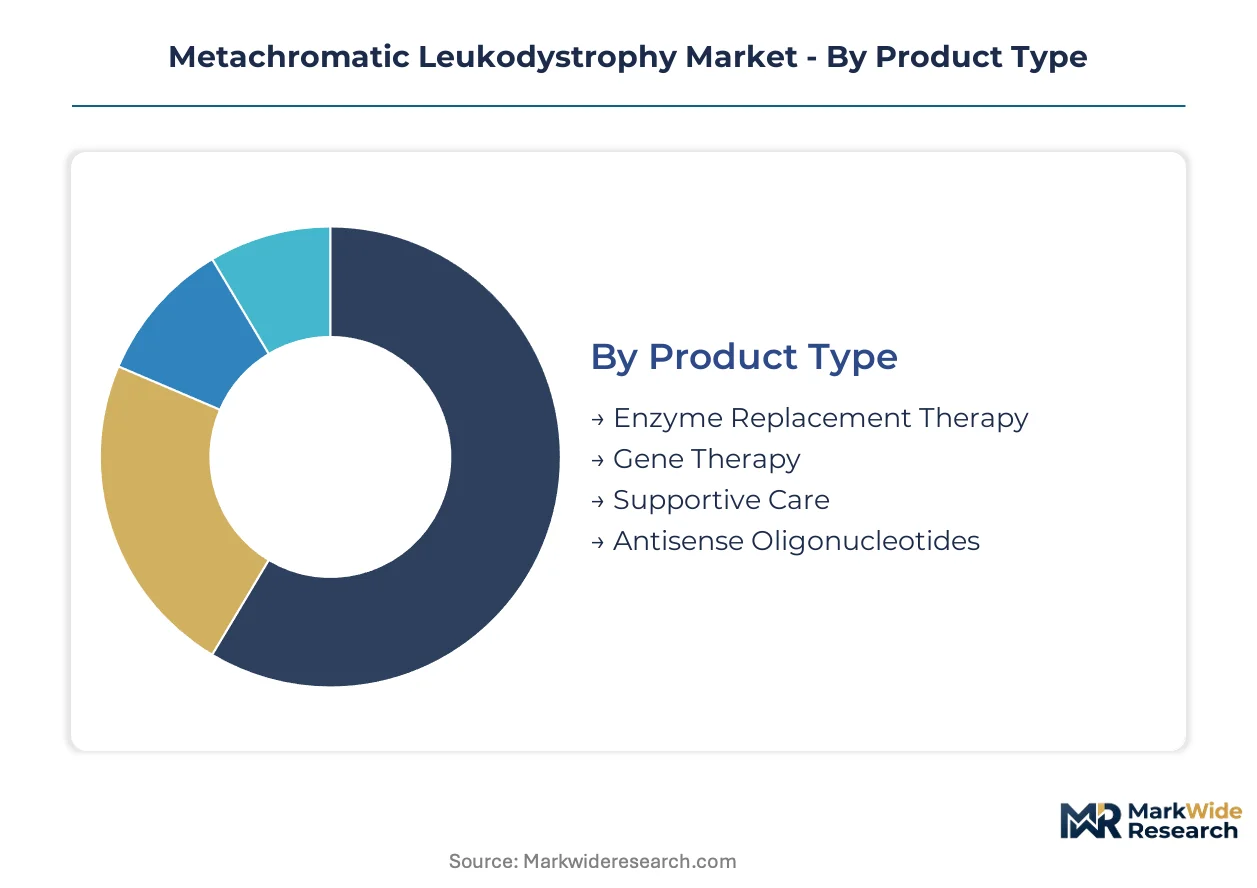
Segmentation in the metachromatic leukodystrophy market reveals distinct margin architectures across therapeutic modalities and care delivery settings. Gene therapy commands premium pricing structures while supportive care generates recurring service revenue pools across decentralized networks.
Product Type:
Margin pools concentrate in one-time curative interventions, while chronic maintenance therapies sustain predictable cash flows across extended treatment horizons.
- Gene Therapy:Lentiviral vector-mediated gene correction delivers functional arylsulfatase A expression through hematopoietic stem cell modification. Demand concentrates at specialized pediatric centers in the United States, Germany, and Japan where FDA and EMA accelerated pathways compress screening-to-treatment intervals. Reimbursement negotiations center on outcomes-based contracts with single-administration premium structures.
- Enzyme Replacement Therapy:Recombinant arylsulfatase A enzyme administration temporarily reduces sulfatide accumulation in peripheral tissues. Demand stabilizes among late-diagnosed patients with established central nervous system involvement where gene therapy carries contraindicated risk profiles. Manufacturing scale economies at established biologics facilities support competitive pricing.
- Supportive Care:Rehabilitation protocols and symptom management across multidisciplinary care teams.
- Antisense Oligonucleotides:Emerging splice-modulation approaches targeting specific ARSA mutations in development pipelines.
Gene therapy holds installed capacity. Enzyme replacement therapy is rotating up the share rankings among symptomatic adult populations.
Application:
Patient age at intervention determines therapeutic eligibility and reimbursement pathway complexity across regulatory jurisdictions.
- Pediatrics:Pre-symptomatic or early-symptomatic children represent the addressable population for curative gene therapy with intact neurodevelopmental trajectories. Enrollment concentrates at Boston Children's Hospital, University Hospital Heidelberg, and Tokyo Metropolitan Children's Medical Center where specialized leukodystrophy diagnostic protocols enable rapid genetic confirmation.
- Adults:Late-onset metachromatic leukodystrophy patients with progressive motor decline drive enzyme replacement and supportive care demand. Clinical heterogeneity complicates standardized outcome measurement for payer contracts.
- Clinical Trials:Natural history studies and interventional protocols requiring biomarker-validated endpoints.
- Research:Academic laboratory investigations into disease mechanisms and vector optimization.
Pediatrics captures protocol-driven volume. Adults are gaining eligibility through expanded access programs.
End User:
Care delivery setting shapes reimbursement mechanics and patient monitoring intensity across the treatment continuum.
- Hospitals:Tertiary academic medical centers with specialized gene therapy infrastructure perform hematopoietic stem cell harvest, conditioning chemotherapy, and vector infusion under controlled isolation protocols. Philadelphia and Munich hospital systems pilot unbundled procurement separating therapeutic product from administration services.
- Rehabilitation Centers:Neurological rehabilitation facilities manage spasticity, gait abnormalities, and adaptive equipment needs. Medicare Advantage plans in the United States increasingly cover indication-based bundled payments for multidisciplinary care.
- Home Care:Nursing support for feeding assistance, respiratory management, and mobility adaptation.
- Research Institutions:Academic centers conducting natural history studies and biomarker validation.
Hospitals anchor high-complexity revenue. Home care is climbing the fastest as decentralized models expand.
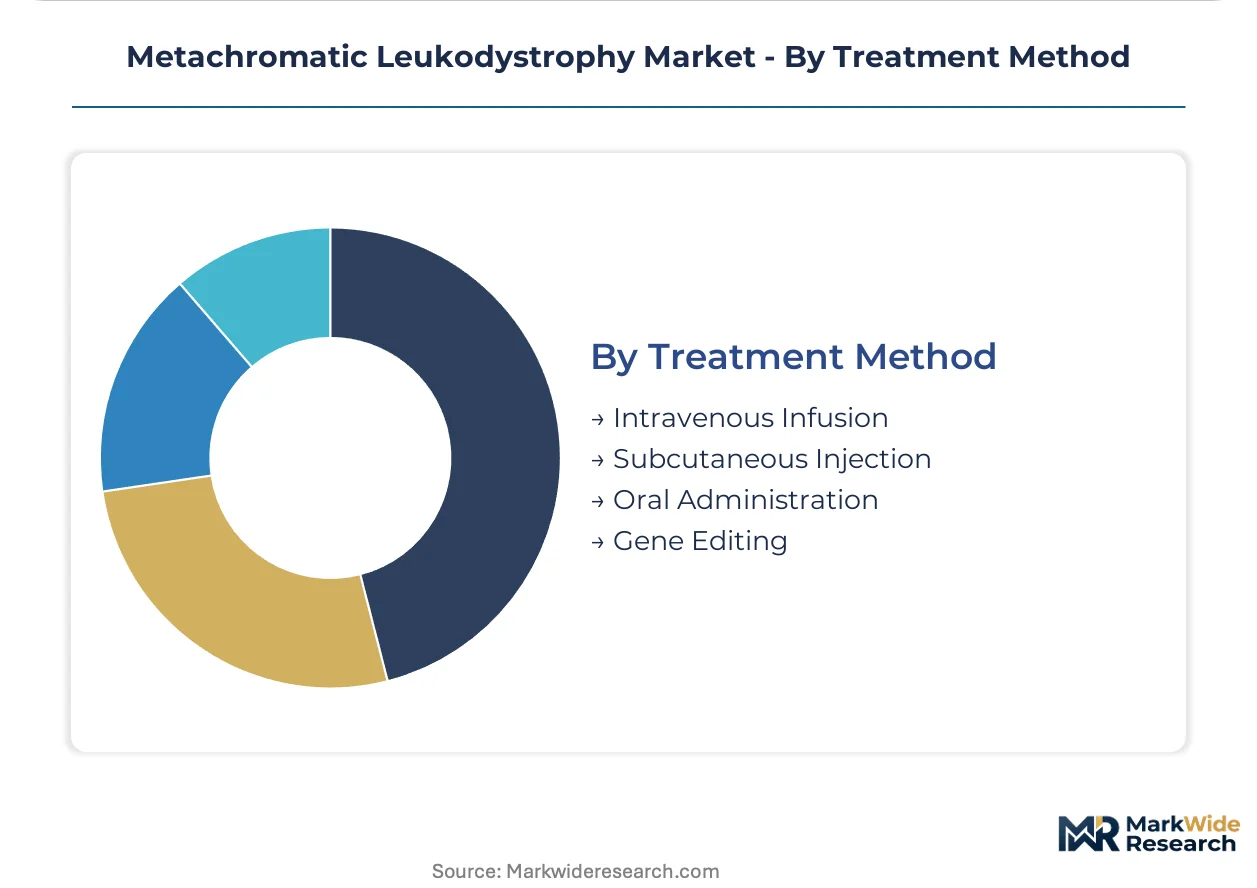
Treatment Method:
Route of administration and mechanism of action determine manufacturing requirements and clinical infrastructure investment.
- Intravenous Infusion:Systemic enzyme delivery and hematopoietic stem cell transplantation require specialized infusion centers with cardiac monitoring capabilities. United States and German hospital networks maintain dedicated rare disease infusion suites with pharmacy compounding integration.
- Gene Editing:CRISPR-based in vivo or ex vivo genetic modification approaches are advancing through preclinical and early clinical stages. Manufacturing complexity exceeds current lentiviral vector production capacity, forcing developers toward captive facility investment.
- Subcutaneous Injection:Peripheral enzyme administration with limited central nervous system penetration.
- Oral Administration:Small-molecule substrate reduction approaches in investigative development.
Intravenous infusion maintains established infrastructure. Gene editing is rotating up the share rankings through pipeline advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where specialized leukodystrophy treatment infrastructure commands premium reimbursement, while Japan leverages regulatory relationships to accelerate Asia-Pacific trial access despite smaller addressable populations.
United States
FDA breakthrough therapy designation compresses development timelines for metachromatic leukodystrophy candidates, attracting venture investment into Boston and Philadelphia pediatric gene therapy centers. Medicare Advantage plans pilot indication-based pricing for one-time curative therapies, unbundling product procurement from infusion services. Hospital systems in these cities negotiate carve-out contracts separating therapeutic administration from bundled payment models.
Germany
EMA PRIME eligibility reduces approval risk for European clinical infrastructure, with University Hospital Heidelberg anchoring specialized leukodystrophy diagnostic protocols. The EU AI Act and GDPR impose data governance requirements on predictive biomarker algorithms used for patient stratification. Munich hospital procurement departments separate gene therapy product purchasing from conditioning and monitoring service fees.
Japan
PMDA engagement accelerates Asia-Pacific trial access for orphan indications through established regulatory relationships. METI supports domestic advanced therapy manufacturing capacity expansion. Tokyo Metropolitan Children's Medical Center consolidates patient referral networks for pediatric neurodegenerative disease intervention.
United Kingdom
NHS England's specialized commissioning framework determines access to high-cost gene therapies for rare diseases. London pediatric centers participate in unified global pivotal trials rather than sequential regional submissions. MHRA post-Brexit regulatory pathways align with FDA and EMA accelerated assessment frameworks for advanced therapy medicinal products.
Switzerland
Swissmedic maintains rigorous pharmacovigilance standards for gene therapy post-approval follow-up obligations. Basel anchors European clinical infrastructure through proximity to specialized contract development organizations. Federal pricing negotiations for one-time curative therapies establish reference points for neighboring jurisdictions.
Metachromatic Leukodystrophy Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the metachromatic leukodystrophy therapeutic landscape. The market structure concentrates around integrated gene therapy developers with captive vector manufacturing capabilities and established biologics manufacturers with enzyme replacement scale economies. Three archetypes dominate: lentiviral vector specialists, recombinant enzyme producers, and emerging gene editing platform companies. Competitive moves center on backward integration into vector production and strategic partnerships to secure hematopoietic stem cell processing infrastructure.
Within the integrated gene therapy tier, Orchard Therapeutics and Bluebird Bio exemplify archetypes pursuing captive manufacturing strategies to circumvent contract development organization backlogs. Takeda Pharmaceuticals occupies a position representing established pharmaceutical companies leveraging regulatory relationships to accelerate orphan disease program access. These three entities anchor distinct competitive approaches: European clinical infrastructure concentration, US-based lentiviral production, and Asia-Pacific regulatory pathway optimization.
| Leading Market Players |
|---|
| Sanofi |
| Orchard Therapeutics |
| BioMarin Pharmaceutical |
| Bluebird Bio |
| JCR Pharmaceuticals |
| GSK plc |
| Takeda Pharmaceuticals |
| Recursion Pharmaceuticals |
| REGENXBIO |
| Others |
Cost & Logistics Intelligence
Lentiviral vector production internalization is displacing contract manufacturing reliance across gene therapy developers, simultaneously concentrating supply geography in captive US and European facilities while collapsing the customization-premium spread that previously separated boutique CMO batches from standardized vector tiers.
Pricing Analysis
The customization-premium spread between patient-specific lentiviral vector configurations and standardized enzyme replacement lots has compressed as Orchard Therapeutics and Bluebird Bio internalize manufacturing. Gene therapy segments command three-tier pricing structure across premium, standard, and economy levels based on treatment timing and neurological status at intervention. Pricing pressure stems from Medicare Advantage indication-based pilot programs demanding outcomes-based contracts. Late-diagnosed adult patients exhibit highest price sensitivity due to enzyme replacement alternatives, while pre-symptomatic pediatric cases show lowest sensitivity given curative intent.
Supply Chain Analysis
Plasmid DNA supply from North American academic centers underwrites lentiviral vector production for metachromatic leukodystrophy programs, creating single-source vulnerability as GMP-grade plasmid concentrates at three US and German production nodes. Manufacturing draws from hematopoietic stem cell apheresis capacity, cryopreservation logistics, and specialized infusion pharmacy compounding. Supply chain risk centers on ISO manufacturing standard evolution requiring continuous facility requalification. Distribution runs through tertiary academic medical centers with gene therapy infrastructure in Boston, Heidelberg, and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector process development expertise concentrates at fewer than ten academic medical centers globally, creating acute bottlenecks for developers lacking in-house analytical characterization capabilities or captive manufacturing footprints.
For Market Incumbents: Secure captive lentiviral vector production capacity in the United States or Germany to circumvent CMO backlogs exceeding thirty-six months. Deepen backward integration into plasmid DNA supply through academic partnerships or facility acquisition. Lock hematopoietic stem cell processing infrastructure at Boston Children's Hospital and University Hospital Heidelberg through exclusive service agreements. For New Entrants and Emerging Players: Anchor in Japanese regulatory pathways through PMDA pre-submission meetings for orphan indication status, accelerating Asia-Pacific trial access relative to sequential FDA-EMA submissions. Target late-diagnosed adult enzyme replacement segments where gene therapy contraindications create stable demand pools. Pursue antisense oligonucleotide development partnerships with established leukodystrophy centers to leverage existing patient referral networks. For Investors and Strategic Acquirers: The market sits at a manufacturing-capacity-constrained phase that favors developers with validated vector production capabilities over discovery-stage platform companies. Five-to-ten year viability hinges on successful navigation of post-approval pharmacovigilance cost structures and reimbursement negotiation outcomes. Monitor FDA breakthrough therapy designation awards and EMA PRIME eligibility decisions as inflection indicators for portfolio prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Vector Manufacturing Buildout | Orchard Therapeutics and Bluebird Bio demonstrate how internalized production circumvents CMO capacity constraints. |
| Regulatory Acceleration Pathway | FDA breakthrough therapy and EMA PRIME eligibility compress development timelines for pediatric neurodegenerative candidates. |
| Outcomes-Based Reimbursement Negotiation | Medicare Advantage indication-based pilots in Philadelphia and Munich reshape gene therapy procurement mechanics. |
| Biomarker Algorithm Validation | EU AI Act compliance requirements extend predictive patient stratification timelines for European trial enrollment. |
| Asia-Pacific Regulatory Relationship | Takeda Pharmaceuticals leverages established PMDA engagement to accelerate Japanese and regional orphan disease access. |
Research Approach
Desk research of FDA breakthrough therapy designation records, EMA PRIME eligibility databases, and ClinicalTrials.gov protocol filings preceded structured interviews with gene therapy development executives, regulatory affairs leads at advanced therapy developers, hospital procurement managers at tertiary pediatric centers, and payer access specialists at Medicare Advantage plans. Secondary validation drew from formulary databases, GPO contract filings, and SEC 10-K disclosures from publicly traded biopharmaceutical firms. Bottom-up patient population estimates triangulated against top-down reimbursement expenditure projections.
Variance decomposition across therapeutic modality, patient age segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment mechanism, application timing relative to symptom onset, end-user care setting, and route of administration. CAGRs were derived from epidemiological incidence projections, treatment penetration assumptions, and pricing evolution scenarios. Forecast inputs incorporated hematopoietic stem cell transplant capacity expansion timelines and vector manufacturing yield improvements.
Material uncertainties — regulatory pathway reversals, manufacturing standard changes, and reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding accelerated approval sustainability and pharmacovigilance cost trajectories. Practitioners should keep alternative scenarios live as FDA and EMA evidentiary requirements for gene therapy durability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Rare Disease Clinical Trials Market