
 Gaucher Disease Drugs Market | 2026-2036
Gaucher Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Gaucher Disease Drugs Market Analysis
The gap between intravenous enzyme replacement and oral substrate reduction therapies is expanding as patient convenience preferences diverge from clinical efficacy benchmarks. Sanofi leverages its manufacturing scale to dominate recombinant glucocerebrosidase supply chains across North American infusion centers. Takeda Pharmaceutical Company Limited anchors its position through specialized rare-disease distribution networks that reach pediatric hematology clinics. Amicus Therapeutics, Inc. differentiates via chaperone technology platforms targeting specific Gaucher genotypes with oral delivery formats.
Gaucher disease drugs comprise biologic and small-molecule therapeutics that modulate glucocerebroside metabolism through enzyme supplementation, substrate reduction, or protein stabilization, with intravenous formulations requiring cold-chain logistics and oral agents demanding gastric pH management for bioavailability. Enzyme Replacement Therapy occupies the largest revenue pool due to decades of clinical validation and prescriber familiarity, though Substrate Reduction Therapy captures faster growth as adult patients seek home-administered alternatives. Oral administration routes are gaining structural importance as pharmacy benefit managers prioritize therapies that reduce hospital-based infusion costs.
The FDA's orphan drug program and EMA's priority medicines pathway shape development incentives by granting market exclusivity and accelerated review timelines for novel Gaucher modalities. National regulators in France and Germany enforce distinct reimbursement proof requirements that filter which therapies reach hospital formularies. Stakeholders must monitor how gene therapy pipelines reposition existing enzyme products within treatment algorithms and payer contracting frameworks.
Market Dynamics
The Gaucher Disease Drugs Market is experiencing a structural pull toward oral therapeutics as patient preference for home-based administration clashes with established clinical protocols favoring intravenous enzyme replacement. This tension between convenience and efficacy is reshaping prescriber decision-making and payer reimbursement frameworks.
Growth Catalysts
- Newborn Screening Mandates:Germany's national screening program identifies Gaucher patients at birth, creating early intervention demand that drives sustained prescription volumes for enzyme therapies.
- Oral Formulation Advances:Substrate reduction chemistry enables gastric-stable small molecules that eliminate cold-chain logistics and expand treatment access to rural infusion deserts.
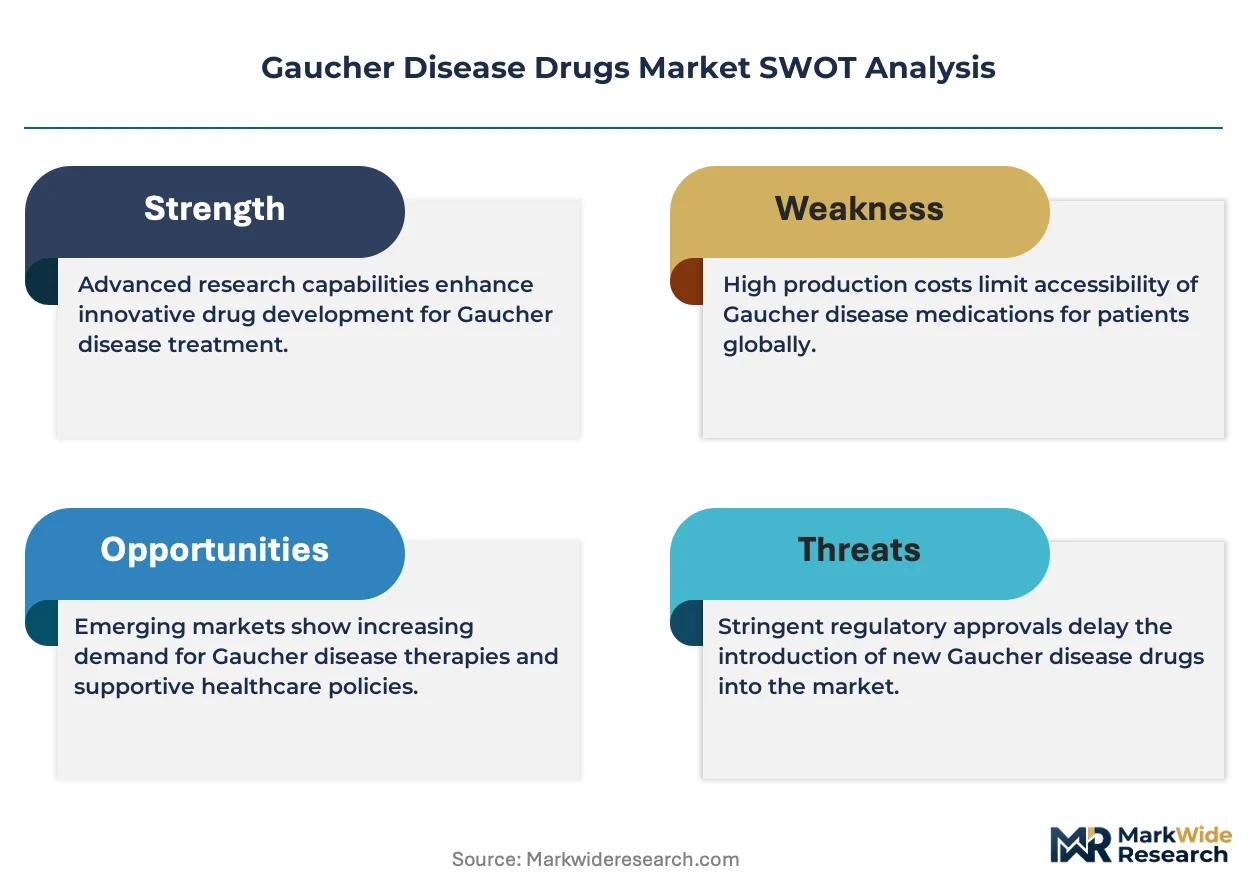
- Orphan Drug Incentives:The FDA's exclusivity framework grants seven-year market protection and tax credits that accelerate biologics development timelines for rare disease indications.
Market Restraints
- Biologic Manufacturing Concentration:Recombinant glucocerebrosidase production clusters in a handful of mammalian cell culture facilities, creating supply vulnerability from single-source dependencies.
- Reimbursement Heterogeneity:France's ANSM and Germany's G-BA enforce divergent health technology assessment criteria that fragment market access across European hospital formularies.
- Gene Therapy Substitution Threat:Lentiviral vector platforms targeting hematopoietic stem cells promise functional cures that could displace chronic enzyme administration entirely.
Strategic Opportunities
- Pediatric Formulation Gaps:Weight-based dosing requirements for infants create demand for concentrated enzyme vials that reduce infusion volume and clinic time.
- Home Infusion Channel Expansion:Reimbursed nursing services in the United States enable hospital-grade enzyme delivery in residential settings, capturing patients who abandon treatment due to travel burden.
- Chaperone-Platform Convergence:Pharmacological chaperones combined with substrate reduction is reshaping combination therapy protocols for specific genotype subsets.
Industry Challenges
- Specialized Hematology Talent Scarcity:Lysosomal storage disease expertise concentrates in academic medical centers, limiting prescriber capacity in community hospital settings.
- Multinational Trial Complexity:Rare patient populations necessitate cross-border clinical protocols that strain regulatory harmonization between the FDA and EMA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaucher Disease Drugs Market |
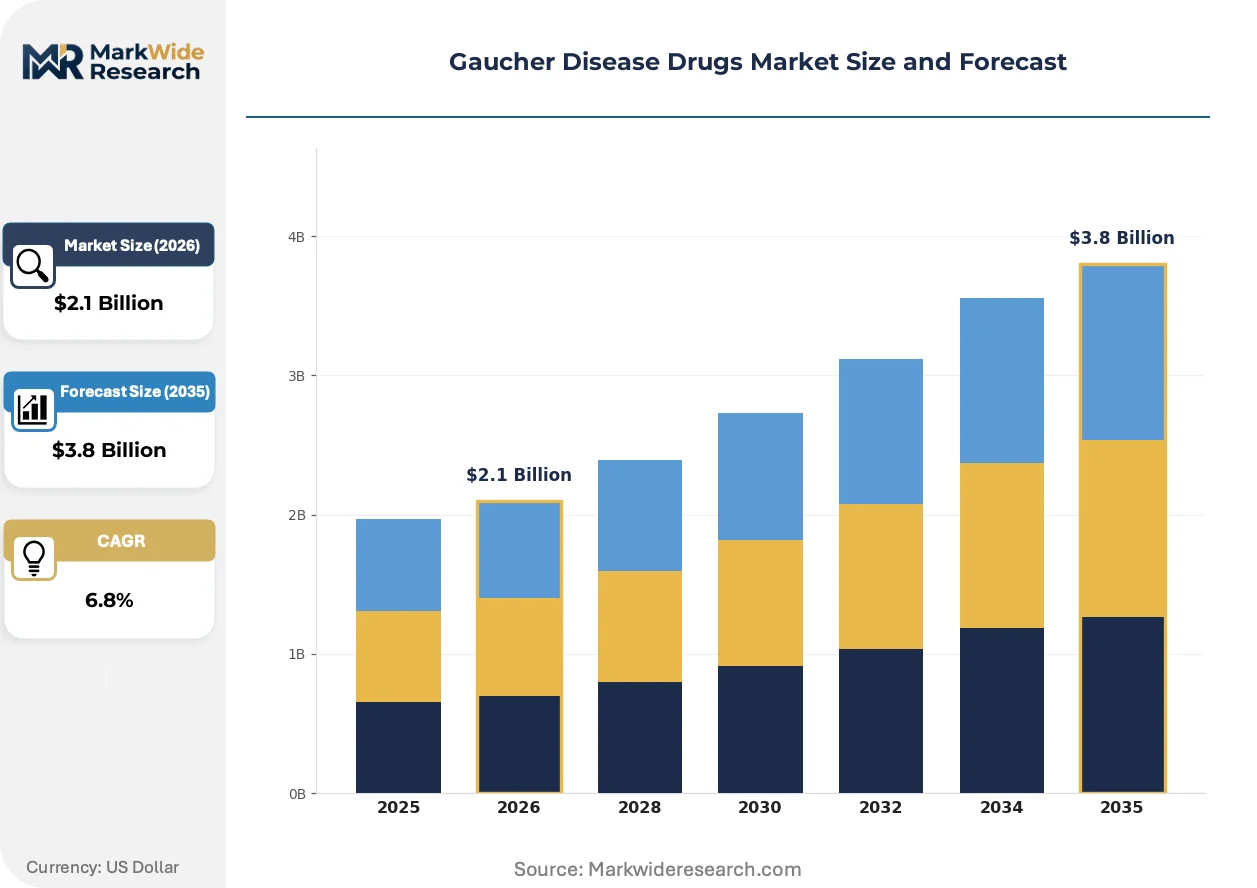
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Symptomatic Treatment, Other Approaches Administration Route: Intravenous, Oral, Subcutaneous, Other Delivery Methods Age Group: Pediatric, Adult, Geriatric, Mixed Population Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Direct Sales |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, Johnson & Johnson, Pfizer Inc, AbbVie, Amicus Therapeutics, Inc., Protalix BioTherapeutics, Actelion Pharmaceuticals, Shire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaucher Disease Drugs Market Emerging Trajectories
Oral therapeutic formats are gaining structural importance as pharmacy benefit managers prioritize therapies that reduce hospital-based infusion costs and enable patient self-administration. Three developments are actively reshaping competitive positioning.
Substrate reduction therapy is decentralizing treatment delivery from infusion centers to home settings. Small-molecule chemistry enables gastric absorption without enzymatic degradation. Adult patients with Type 1 Gaucher are switching from biweekly intravenous infusions to daily oral regimens at accelerating rates. This shift is compressing revenue concentration among traditional enzyme manufacturers while expanding pharmacy-dispensed prescription volumes.
EMA's priority medicines pathway is accelerating review timelines for novel Gaucher modalities that demonstrate substantial benefit over existing standards. The framework grants scientific advice and accelerated assessment that compress development timelines by twelve to eighteen months. Biologics targeting neuronopathic variants are capturing these regulatory tailwinds, with manufacturers prioritizing European launch sequences to leverage the pathway's commercial advantages.
Patient advocacy organizations are consolidating purchasing influence through dedicated pharmacy benefit structures that negotiate directly with manufacturers. The National Gaucher Foundation in the United States aggregates treatment demand across member patients to secure volume-based contracting terms. This concentration is displacing traditional physician-led prescribing autonomy and shifting price negotiation leverage toward organized patient collectives.
Gaucher Disease Drugs Market Segmentation
Patient migration from hospital-based infusions toward home-administered alternatives is fragmenting traditional revenue pools across multiple segmentation axes. Drug manufacturers must now optimize formulations simultaneously for clinical efficacy, reimbursement compatibility, and self-administration feasibility.
Drug Type:
Upgrade cycles between therapeutic modalities accelerate as patients cycle through first-line enzyme replacement, second-line substrate reduction, and emerging chaperone combinations based on genotype and tolerability profiles.
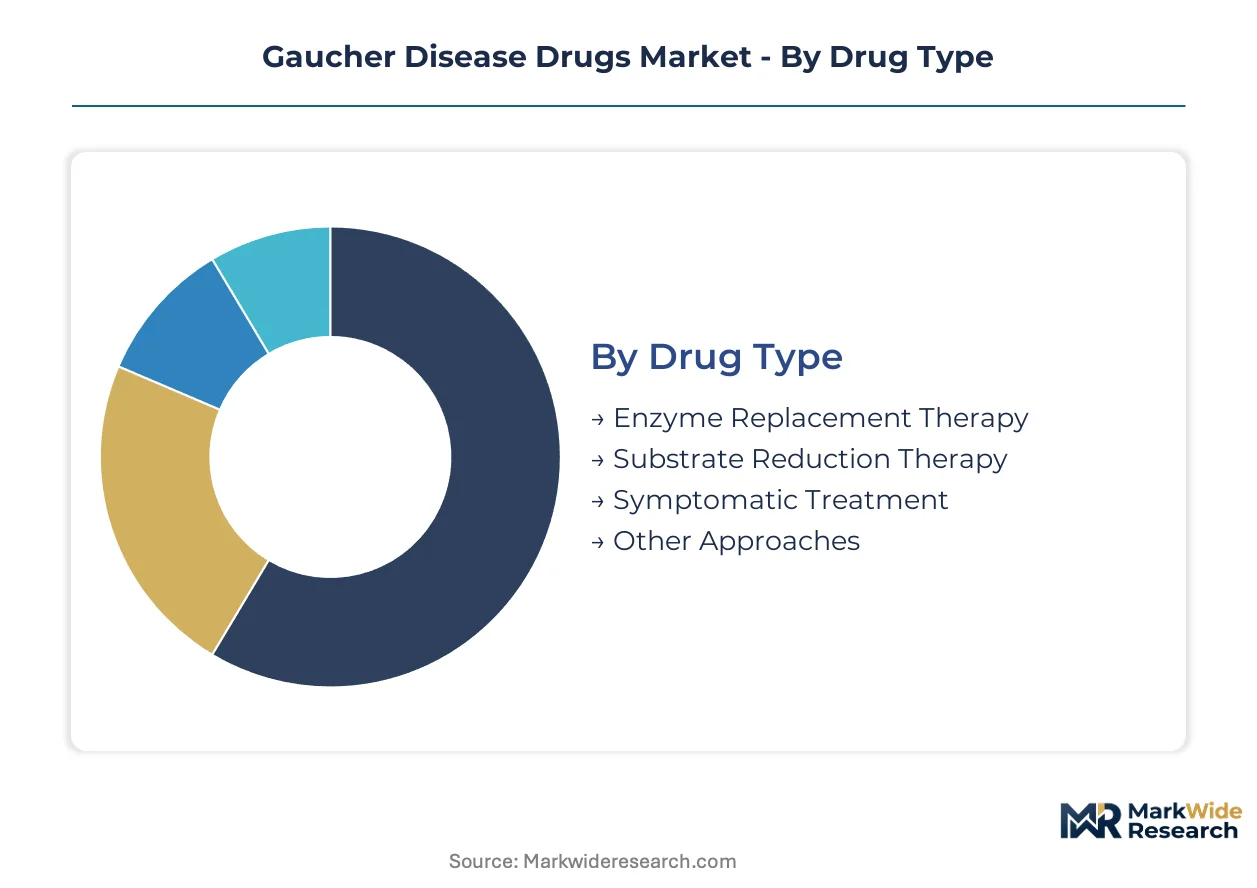
- Enzyme Replacement Therapy:Recombinant glucocerebrosidase infusions require cold-chain logistics and specialized infusion nursing. Demand concentrates in Germany's reimbursed home-infusion networks and United States pediatric treatment centers where prescriber familiarity sustains protocol dominance despite convenience limitations.
- Substrate Reduction Therapy:Small-molecule inhibitors of glucosylceramide synthase enable gastric absorption without enzymatic degradation. Adult Type 1 patients in France and Germany are switching from biweekly infusions to daily oral regimens, compressing hospital pharmacy volumes while expanding retail pharmacy dispensing.
- Symptomatic Treatment:Bisphosphonates, analgesics, and anti-inflammatory agents address bone pain and splenomegaly complications without modifying disease progression.
- Other Approaches:Gene therapy candidates and pharmacological chaperones remain developmental, targeting neuronopathic variants with functional cure potential.
Enzyme Replacement Therapy sits at the top of the volume ranking, with Substrate Reduction Therapy climbing the fastest.
Administration Route:
Cost tier stratification separates premium intravenous biologics from mid-tier oral small molecules and emerging economy-positioned subcutaneous formulations.
- Intravenous:Hospital-grade infusion delivery via peripheral or central venous access demands refrigeration, nursing supervision, and infusion center capacity. United States payers increasingly require step-therapy failure before authorizing hospital-based administration.
- Oral:Gastric pH management and food-effect timing constrain bioavailability. Germany's G-BA and France's ANSM apply divergent health technology assessment criteria to oral versus intravenous cost-effectiveness calculations.
- Subcutaneous:Enzyme formulations enabling home self-injection are penetrating United States markets through reimbursed nursing support programs.
- Other Delivery Methods:Intrathecal and intracerebroventricular routes target central nervous system involvement in neuronopathic variants.
Intravenous administration retains the largest patient base, though oral routes are gaining share fastest among treatment-naive adults.
Age Group:
Application-specific dosing requirements create distinct formulation and packaging demands across developmental stages.
- Pediatric:Weight-based dosing necessitates concentrated enzyme vials and fractionated tablet strengths. Germany's national newborn screening mandate identifies patients at birth, creating early intervention demand.
- Adult:Stable dosing regimens and employment constraints drive preference for home-administered alternatives. Adult patients demonstrate highest switching rates between therapeutic modalities.
- Geriatric:Comorbidity burden and polypharmacy interactions complicate treatment selection in aging Gaucher populations with long disease duration.
- Mixed Population:Clinical trial designs and real-world evidence studies increasingly enroll across age strata to capture lifecycle treatment patterns.
Adult patients constitute the largest addressable population, with pediatric segments expanding most quickly through screening program expansion.
Distribution Channel:
Supply concentration in specialty pharmacy networks is displacing traditional hospital procurement autonomy.
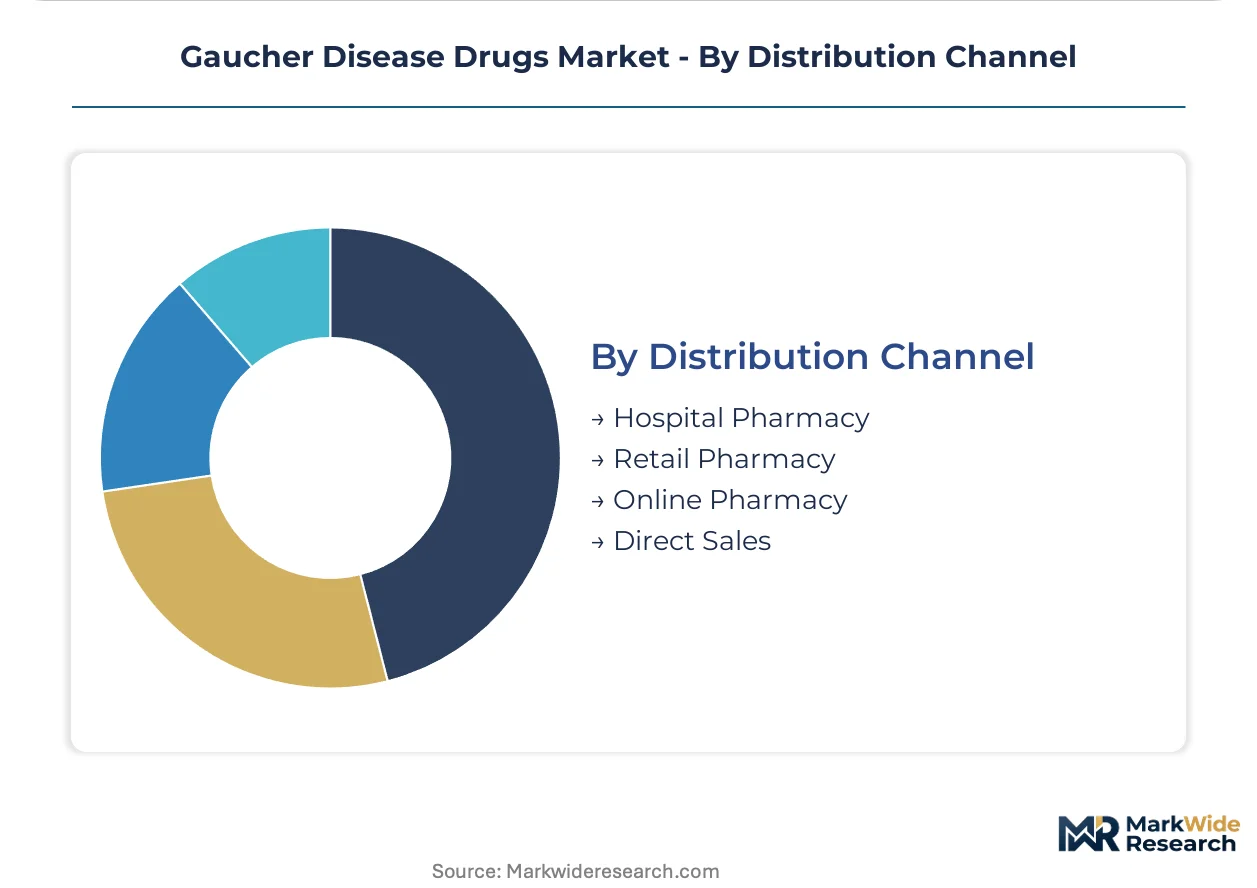
- Hospital Pharmacy:Academic medical centers with lysosomal storage disease expertise maintain formulary control for complex infusion therapies. France's hospital-centric reimbursement reinforces this channel's dominance for enzyme replacement.
- Retail Pharmacy:Oral substrate reduction therapies dispense through standard pharmacy networks, enabling geographic expansion beyond infusion center catchment areas.
- Online Pharmacy:Direct-to-patient shipping of temperature-stable oral medications reduces travel burden for rural and disabled patients.
- Direct Sales:Manufacturer-managed specialty pharmacies coordinate prior authorization, nursing dispatch, and adherence monitoring for high-touch biologic therapies.
Hospital Pharmacy remains the highest-volume channel, with Retail Pharmacy demonstrating the steepest expansion trajectory as oral therapies proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematology specialists cluster in academic medical centers across five countries, anchoring treatment access and clinical trial recruitment for enzyme and substrate-reduction therapies.
United States
Pediatric treatment centers in Boston and New York Metro expand adoption of enzyme replacement infusions. The FDA's orphan drug exclusivity framework accelerates biologics development timelines. Philadelphia's specialty pharmacy networks coordinate reimbursed home-nursing services that capture patients abandoning hospital-based care.
Germany
National newborn screening mandates identify Gaucher patients at birth, creating early intervention demand. The G-BA enforces distinct health technology assessment criteria that filter which therapies reach hospital formularies. Munich's reimbursed home-infusion programs concentrate prescriber expertise and sustain protocol dominance for intravenous biologics.
France
Hospital-centric reimbursement reinforces academic medical center control over complex infusion therapies. ANSM applies divergent cost-effectiveness calculations to oral versus intravenous modalities. Parisian lysosomal storage disease clinics anchor regional referral patterns and maintain formulary gatekeeper status.
United Kingdom
NHS specialized commissioning concentrates treatment authorization in designated centers of excellence. NICE technology appraisals determine which Gaucher modalities receive routine commissioning. London's pediatric hematology units coordinate cross-border clinical protocols for rare patient populations.
Switzerland
Swissmedic's accelerated assessment pathways compress review timelines for novel rare disease modalities. Zurich and Geneva host reference laboratories for glucocerebrosidase genotyping that guide chaperone therapy selection. Cantonal reimbursement harmonization enables earlier access to oral substrate reduction alternatives.
Gaucher Disease Drugs Market Vendor Landscape
Capital-heavy biologic manufacturers compete with asset-light small-molecule developers for prescriber mindshare and payer formulary slots. The market structure concentrates revenue among three recombinant enzyme suppliers while fragmenting across oral therapy specialists. Strategic archetypes include mammalian cell culture scale operators, substrate reduction chemists, and pharmacological chaperone platform builders. Dominant competitive moves center on manufacturing capacity expansion and specialized rare-disease distribution network partnerships.
Among the scale-driven biologic producers, Sanofi anchors North American supply chains through recombinant glucocerebrosidase manufacturing. Takeda Pharmaceutical Company Limited occupies a position within specialized distribution networks reaching pediatric hematology clinics. Amicus Therapeutics, Inc. exemplifies the chaperone-platform archetype with oral delivery formats targeting genotype-specific patient subsets.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson |
| Pfizer Inc |
| AbbVie |
| Amicus Therapeutics, Inc. |
| Protalix BioTherapeutics |
| Actelion Pharmaceuticals |
| Shire |
| Others |
Supply Flow & Price Mechanics
Specialty pharmacy benefit managers in the United States concentrate purchasing power for enzyme replacement therapies, locking in contract-based pricing that bundles drug acquisition with reimbursed nursing services. This buyer consolidation forces manufacturers to compete on total cost of care rather than unit price alone.
Pricing Analysis
Service bundling versus unbundling splits the market into two pricing regimes. Hospital-based infusion centers charge premium rates for cold-chain biologics with nursing supervision, while retail-dispensed oral substrate reduction therapies compete on pharmacy benefit manager formulary placement. Price differentiation hinges on administration convenience and genotype-specific efficacy data. Cost compression in the intravenous tier intensifies as home-infusion programs capture volume from academic medical centers. Pediatric treatment centers demonstrate lowest price sensitivity due to prescriber protocol loyalty, while adult Type 1 patients switching modalities show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with mammalian cell culture facilities in the United States, Belgium, and Ireland that produce recombinant glucocerebrosidase. Manufacturing draws from fetal bovine serum, specialized bioreactor systems, and viral filtration technologies. Tariff exposure on imported raw materials creates margin pressure for European-sourced production. Distribution runs through manufacturer-managed specialty pharmacies that coordinate temperature-controlled logistics and patient adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Gaucher therapeutics rests on shifting volume toward oral formulations that eliminate nursing costs and cold-chain infrastructure. Home-administered substrate reduction therapies command premium pharmacy benefit positioning while collapsing per-patient service delivery expenses.
For Market Incumbents: Acquire pharmacological chaperone platforms to defend against gene therapy substitution threats. Backward integration into viral vector manufacturing capacity secures pipeline optionality for neuronopathic variants. Lock in exclusive distribution partnerships with pediatric hematology networks to protect enzyme replacement volumes from oral switching. For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy channels that bypass hospital formulary gatekeepers. White-space concentration in reimbursed home-infusion services for rural Medicaid populations offers fastest penetration. Target genotype-specific chaperone combinations underserved by current one-size-fits-all enzyme protocols. For Investors and Strategic Acquirers: Large-cap rare disease specialists are the most active acquirers in this space, consolidating chaperone and gene therapy assets ahead of patent cliffs. Five-to-ten year viability favors platform companies with multiple lysosomal storage disease indications rather than single-asset developers. Watch FDA breakthrough therapy designations for neuronopathic Gaucher candidates as inflection signals for therapeutic modality displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Pipeline Advancement | Lentiviral vector platforms targeting hematopoietic stem cells threaten chronic enzyme administration revenue pools. |
| Home-Infusion Channel Expansion | Reimbursed nursing services in the United States capture patients abandoning hospital-based care due to travel burden. |
| Pharmacological Chaperone Development | Oral delivery formats targeting specific Gaucher genotypes differentiate from commoditized enzyme replacement. |
| Pediatric Formulation Investment | Concentrated enzyme vials reduce infusion volume and clinic time for weight-based infant dosing requirements. |
| Patient Advocacy Partnership | The National Gaucher Foundation aggregates treatment demand to secure volume-based contracting terms with manufacturers. |
Methodological Framework
Bottom-up patient-level demand modeling reconciled against top-down manufacturer supply tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists cross-validate assumptions. Secondary sources include FDA orphan drug designations, EMA priority medicines pathway submissions, ClinicalTrials.gov protocols, and national formulary databases across Germany, France, and the United States.
Input-output matrices connect treatment-eligible population estimates to prescription volume projections across enzyme replacement, substrate reduction, and emerging chaperone segments. The analytical framework models administration route, patient age strata, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from patient flow analysis and therapy switching probability matrices. Forecast inputs incorporate newborn screening expansion timelines and gene therapy clinical readouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy approval acceleration or reimbursement restriction scenarios. Outcomes reflect documented assumptions regarding screening program adoption and prescriber protocol persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Krabbe Disease Treatment Market