
 Sarcoidosis Therapeutics Market | 2026-2036
Sarcoidosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Sarcoidosis Therapeutics Market Outlook
Specialty pulmonology and rheumatology clinics is broadening as the primary channel for sarcoidosis drug administration, shifting volume away from general hospital wards. Johnson & Johnson leverages its immunology infrastructure to sustain corticosteroid and biologic supply chains across North American academic medical centers. AbbVie competes through its inflammation franchise, while aTyr Pharma positions its pipeline around novel immunomodulatory mechanisms for refractory cases.
Sarcoidosis therapeutics comprise pharmaceutical agents designed to suppress granulomatous inflammation, modulate T-cell responses, and prevent progressive organ fibrosis in affected tissues. These treatments primarily function through corticosteroid-mediated cytokine suppression, calcineurin inhibition, or targeted biologic interference with tumor necrosis factor and interleukin pathways to halt disease progression in lungs, skin, eyes, and cardiac tissue. Corticosteroids still anchor first-line protocols, though biologics represent the fastest-expanding margin pool as refractory and steroid-intolerant patient identification improves. Immunosuppressants occupy a narrowing middle tier where generic pressure compresses returns, while subcutaneous delivery modes are gaining share against intravenous infusion due to site-of-care economics.
FDA orphan drug designation and EMA PRIME eligibility frameworks shape clinical trial investment by reducing regulatory risk for developers targeting pulmonary and cardiac sarcoidosis subtypes. The EPA and OSHA indirectly influence market access through occupational exposure guidelines that drive diagnostic screening in high-risk worker populations. Stakeholders must monitor how payer evidence requirements for extrapulmonary indication expansion evolve against existing pulmonary-focused reimbursement benchmarks.
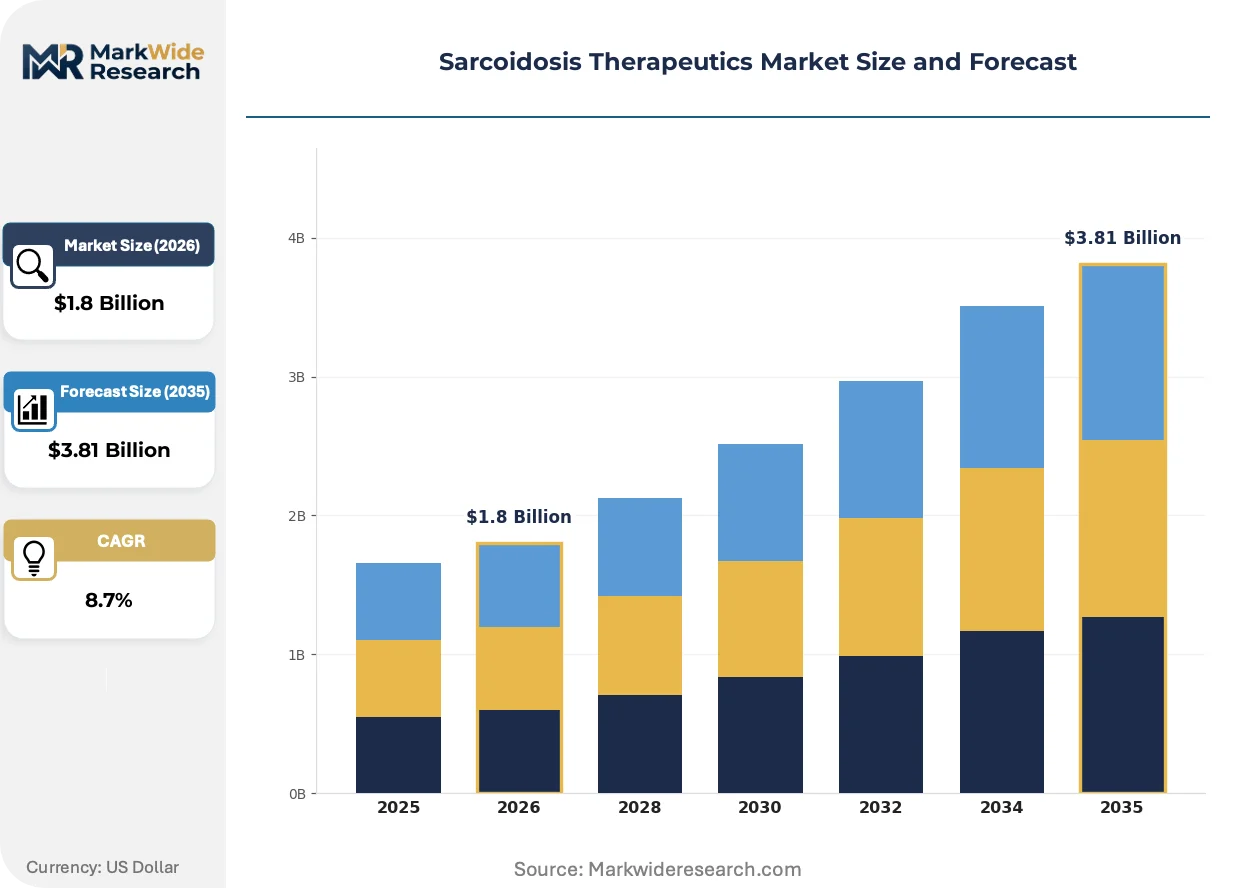
Market Dynamics
Biologic penetration into refractory sarcoidosis cases is compressing the traditional corticosteroid-first treatment paradigm, forcing payers to recalibrate reimbursement tiers and site-of-care economics around subcutaneous administration models.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and extended exclusivity provisions for pulmonary and cardiac sarcoidosis subtypes are accelerating clinical trial enrollment timelines for developers targeting rare inflammatory indications.
- Japan's Rare Disease Framework:PMDA's Sakigake designation system prioritizes sarcoidosis biologics in regulatory review, creating faster market access for refractory case therapies in East Asian academic medical centers.
- Subcutaneous Delivery Platforms:Self-administration devices for TNF-alpha inhibitors are shifting administration from infusion centers to home settings, reducing site-of-care costs and expanding patient eligibility pools.
Market Restraints
- Biologic Manufacturing Concentration:Contract manufacturing for monoclonal antibodies concentrates among a limited supplier base in Ireland and Singapore, creating vulnerability to single-source disruptions.
- EMA Parallel Assessment Complexity:Divergent evidentiary requirements between centralized and national reimbursement pathways for extrapulmonary indications extend time-to-market for developers.
- Corticosteroid Generic Saturation:Prednisone and methylprednisolone commoditization compresses pricing power for first-line protocols, limiting revenue contribution from the largest patient volume segment.
Strategic Opportunities
- Cardiac Sarcoidosis Biomarker Development:FDG-PET imaging protocols combined with novel serologic markers create diagnostic white space in a historically underdiagnosed extrapulmonary subtype with high unmet need.
- Germany's AMNOG Fast-Track:Early benefit assessment pathways for orphan indications enable premium pricing capture before standard HTA benchmarks apply to biologic therapies.
- Telemedicine-Integrated Monitoring:Remote patient monitoring platforms for steroid-sparing protocols enable rural and suburban patient enrollment previously excluded from specialty center access.
Industry Challenges
- Granuloma Pathology Heterogeneity:Disease phenotyping across pulmonary, cutaneous, and cardiac manifestations complicates endpoint standardization for registrational trials, fragmenting development programs.
- Biorepository Infrastructure Gaps:Limited tissue banking for multi-organ sarcoidosis specimens constrains translational research and companion diagnostic co-development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sarcoidosis Therapeutics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Adjunct Therapies Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation End User: Hospitals, Clinics, Homecare, Research Institutions Indication: Pulmonary Sarcoidosis, Extrapulmonary Sarcoidosis, Systemic Sarcoidosis, Asymptomatic Sarcoidosis |
| Companies Covered | Johnson & Johnson, United Therapeutics Corporation, Novartis AG, Mallinckrodt Pharmaceuticals, aTyr Pharma, Inc., AbbVie Inc., Roche Holding AG, GlaxoSmithKline plc, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sarcoidosis Therapeutics Market Strategic Shifts
Precision immunomodulation is displacing broad immunosuppression as the dominant development philosophy, with novel mechanisms targeting specific T-cell activation pathways rather than blanket cytokine suppression.
JAK-STAT pathway inhibitors are rewriting therapeutic sequencing for steroid-refractory cases. Academic medical centers in the United States and Germany are piloting these agents ahead of formal label expansion. The technology is compressing the historical corticosteroid-to-biologic transition window from years to months.
EMA's PRIME eligibility framework is accelerating assessment timelines for cardiac sarcoidosis therapies. Developers gain enhanced scientific advice and accelerated review pathways that reduce regulatory uncertainty. Pulmonary-focused developers are pivoting pipeline priorities toward extrapulmonary indications to capture these incentives.
Site-of-care economics are driving preference shifts toward subcutaneous biologics over intravenous infusion. Rheumatology and pulmonology clinics in the United States are consolidating administration volume away from hospital outpatient departments. Payer contracts in Germany and Japan increasingly differentiate reimbursement rates by delivery mode.
Sarcoidosis Therapeutics Market Segmentation
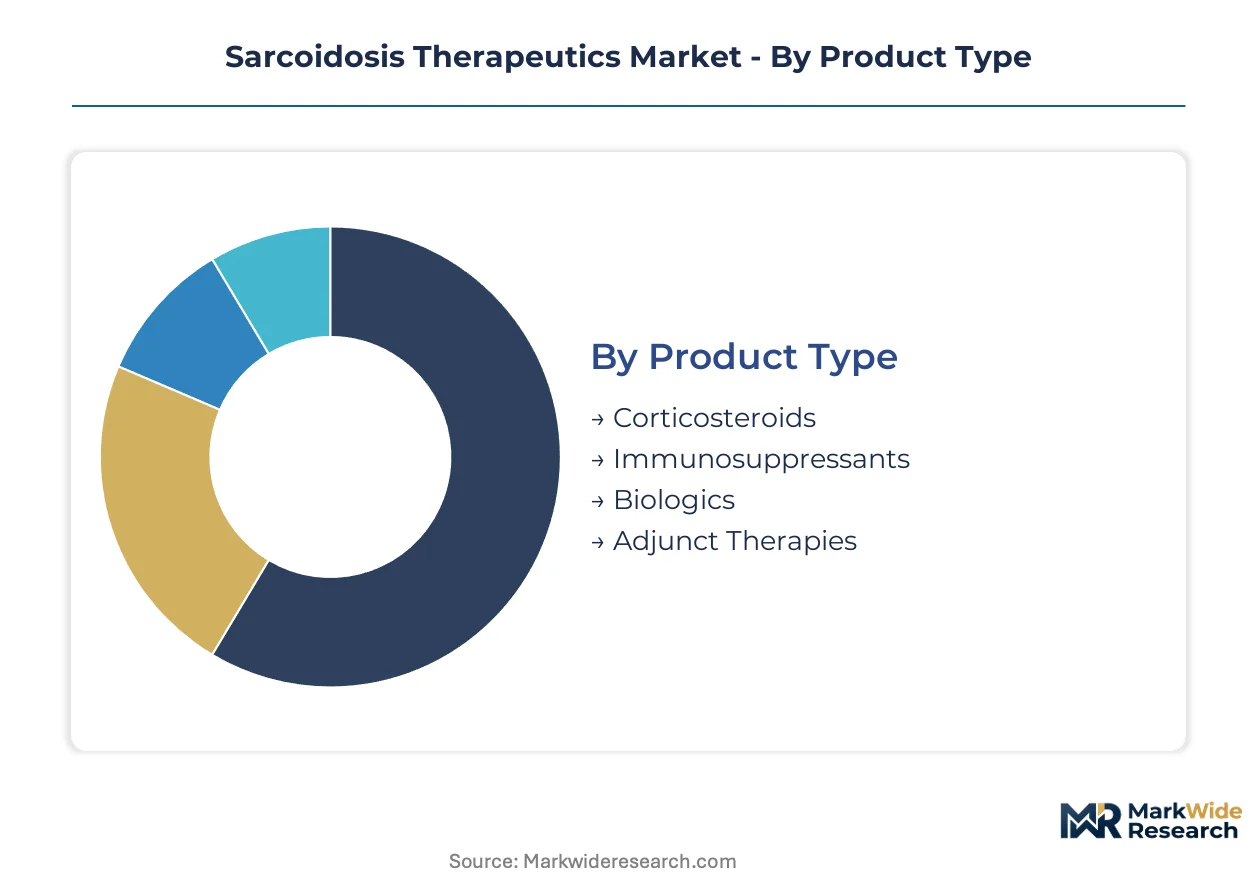
Sarcoidosis therapeutics segmentation reflects divergent clinical pathways: corticosteroid-tolerant versus refractory patients, hospital-dependent versus home-manageable administration, and organ-specific versus systemic disease phenotypes. Treatment selection hinges on granuloma burden, organ involvement pattern, and payer reimbursement tiers for biologic access.
Product Type:
Cost tier and margin structure differentiate prescribing behavior across patient acuity levels and reimbursement environments.
- Corticosteroids:Prednisone and methylprednisolone protocols suppress T-cell mediated granuloma formation through broad cytokine inhibition. Demand concentrates in United States community hospital systems where generic pricing enables high-volume first-line deployment despite steroid-sparing pressure from payers.
- Biologics:TNF-alpha inhibitors and emerging IL-17 pathway antagonists deliver targeted immunomodulation for refractory pulmonary and cardiac manifestations. Germany's AMNOG fast-track and Japan's Sakigake designation accelerate market access for these premium therapies in academic medical centers managing complex extrapulmonary cases.
- Immunosuppressants:Methotrexate and azathioprine occupy the steroid-to-biologic transition window with calcineurin-independent mechanisms. Prescribing concentrates where biologic prior authorization creates access friction.
- Adjunct Therapies:Topical corticosteroids, ophthalmic preparations, and supportive care agents address cutaneous and ocular manifestations without systemic immunosuppression. Demand tracks dermatology and ophthalmology referral patterns.
Corticosteroids lead volumes today; biologics are gaining share fastest.
Delivery Mode:
Administration setting economics and patient self-management capability determine channel preference and reimbursement tier placement.
- Oral:Tablet and liquid formulations of corticosteroids and small-molecule immunosuppressants enable outpatient initiation without infusion infrastructure. United States rheumatology clinics leverage oral pathways to reduce hospital outpatient department dependency and capture site-of-care savings.
- Subcutaneous:Prefilled autoinjector devices for adalimumab biosimilars and emerging biologics shift administration from infusion centers to home settings. Germany's G-BA reimbursement differentials favor subcutaneous delivery for maintenance therapy in stable pulmonary sarcoidosis patients.
- Intravenous:Hospital-based infusion of infliximab and investigational biologics retains dominance for acute cardiac sarcoidosis decompensation and induction dosing. Concentration in United States academic medical centers with advanced cardiac imaging capabilities.
- Inhalation:Nebulized corticosteroid formulations target localized pulmonary inflammation with reduced systemic exposure. Limited uptake outside Japan where PMDA has approved specific inhaled protocols for mild pulmonary disease.
Oral delivery dominates prescription counts; subcutaneous routes are climbing the fastest as self-administration devices proliferate.
End User:
Care setting specialization and biologic administration infrastructure determine patient routing and therapy selection.
- Hospitals:Inpatient and outpatient departments manage acute sarcoidosis decompensation, cardiac monitoring, and intravenous biologic induction. United States health systems consolidate complex extrapulmonary cases in quaternary centers with FDG-PET and electrophysiology capabilities.
- Clinics:Specialty pulmonology and rheumatology practices handle maintenance therapy, steroid tapering, and subcutaneous biologic administration. Germany's ambulatory care reimbursement framework enables clinic-based biologic delivery at lower cost than hospital settings.
- Homecare:Nursing services and patient self-administration support chronic maintenance in stable disease. Expansion in Japan's aging population where hospital avoidance carries payer incentives.
- Research Institutions:Academic medical centers conduct interventional trials for refractory phenotypes and novel mechanism biologics. Concentration in United States NIH-funded centers and European EMA PRIME-eligible sites.
Hospitals anchor acute and complex case management; clinics capture the steepest expansion trajectory as site-of-care economics shift maintenance volume.
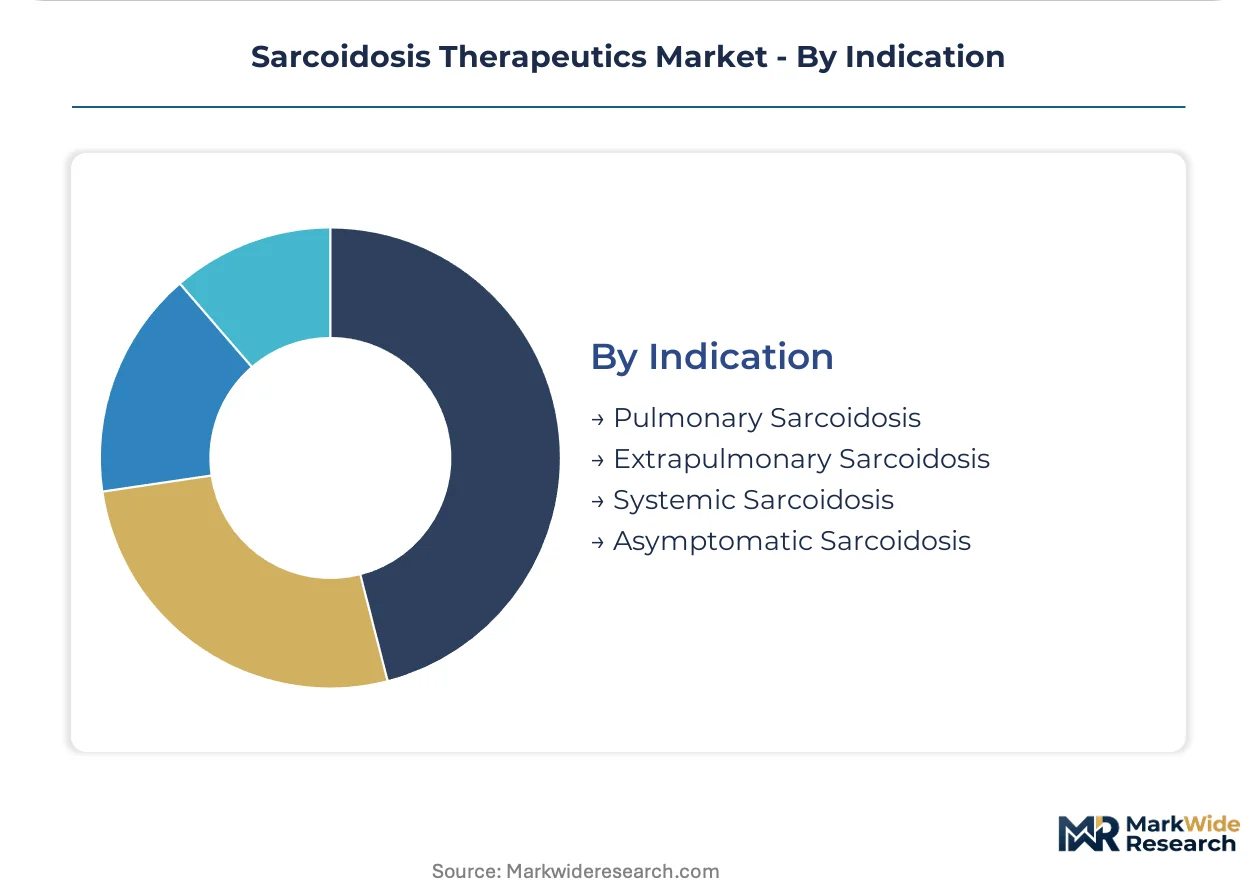
Indication:
Organ involvement pattern and disease severity stratify unmet need, endpoint requirements, and regulatory pathway eligibility.
- Pulmonary Sarcoidosis:Parenchymal lung involvement drives the majority of corticosteroid prescriptions and clinical trial enrollment. United States pulmonology practices manage progression risk through forced vital capacity monitoring and bronchoalveolar lavage biomarker assessment.
- Cardiac Sarcoidosis:Arrhythmogenic granulomatous infiltration carries highest mortality risk and drives biologic urgency. FDA orphan drug incentives and EMA PRIME eligibility accelerate development for this historically underdiagnosed extrapulmonary subtype.
- Extrapulmonary Sarcoidosis:Cutaneous, ocular, and neurologic manifestations require organ-specific therapeutic approaches beyond pulmonary protocols. Germany's dermatology and ophthalmology referral networks concentrate management of refractory cases.
- Systemic Sarcoidosis:Multi-organ involvement demands coordinated immunosuppression with organ-specific adjuncts. Complexity drives referral to United States and European academic centers with multidisciplinary sarcoidosis programs.
- Asymptomatic Sarcoidosis:Incidentally detected granulomatous disease on imaging creates watchful waiting and diagnostic uncertainty. Limited pharmacologic intervention; monitoring protocols vary by healthcare system screening intensity.
Pulmonary sarcoidosis generates the highest prescription volumes; cardiac sarcoidosis shows the most rapid therapeutic innovation uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States anchor the highest-value sarcoidosis treatment corridors, with Germany and Japan following as concentrated biologic adoption markets where orphan drug frameworks accelerate access.
United States
NIH-funded sarcoidosis research centers in Baltimore and New York City drive biologic trial enrollment for refractory pulmonary cases. FDA orphan drug tax credits incentivize cardiac sarcoidosis development programs. Cleveland Clinic and Mayo Clinic anchor multi-organ management protocols that consolidate complex referrals from community pulmonology practices.
Germany
AMNOG fast-track pathways enable premium biologic pricing before standard HTA benchmarks apply to orphan indications. G-BA reimbursement differentials favor subcutaneous delivery in ambulatory settings over hospital outpatient departments. Heidelberg and Berlin academic clusters concentrate FDG-PET diagnostic capacity for cardiac sarcoidosis phenotyping.
Japan
PMDA Sakigake designation prioritizes sarcoidosis biologics in regulatory review, compressing time-to-market for refractory therapies. Aging demographics and hospital avoidance incentives expand homecare nursing for maintenance biologic administration. Tokyo and Osaka academic centers lead East Asian enrollment in TNF-alpha inhibitor post-marketing surveillance.
United Kingdom
NICE technology appraisals for rare inflammatory diseases create evidence thresholds that favor biologics with pulmonary-specific outcome data. NHS England's specialized commissioning framework concentrates cardiac sarcoidosis management in London and Manchester quaternary centers. Manchester University NHS Foundation Trust operates one of Europe's largest extrapulmonary sarcoidosis registries.
France
ANSM early access programs for orphan indications enable compassionate use of investigational biologics ahead of formal marketing authorization. Réseau Sarcoidose reference centers in Paris and Lyon coordinate multi-organ case management and biorepository tissue banking. French pulmonology societies publish granuloma phenotyping guidelines that influence EMA endpoint standardization discussions.
Sarcoidosis Therapeutics Market Competitive Environment
Strategic partnerships dominate the current landscape as developers seek immunology infrastructure and rare disease commercialization expertise. The market structures around three tiers: diversified pharmaceutical conglomerates with inflammation franchises, mid-cap biotechs with novel mechanism pipelines, and generic manufacturers supplying corticosteroid commoditization. Two archetypes anchor competitive positioning: immunology platform extenders leveraging existing biologic supply chains, and mechanism innovators targeting refractory case white space. M&A activity and pipeline prioritization toward extrapulmonary indications constitute the dominant competitive moves.
Within the diversified pharmaceutical tier, Johnson & Johnson and AbbVie exemplify immunology platform extension strategies, while aTyr Pharma occupies a position among mechanism innovators targeting novel T-cell activation pathways. Johnson & Johnson leverages its North American hospital infrastructure to sustain corticosteroid and biologic distribution across academic medical centers. AbbVie competes through its established inflammation franchise and rheumatology clinic relationships. aTyr Pharma represents the pipeline-driven archetype focused on refractory case segments where existing biologics demonstrate insufficient response rates.
| Leading Market Players |
|---|
| Johnson & Johnson |
| United Therapeutics Corporation |
| Novartis AG |
| Mallinckrodt Pharmaceuticals |
| aTyr Pharma, Inc. |
| AbbVie Inc. |
| Roche Holding AG |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
EMA's PRIME eligibility framework for rare inflammatory diseases gates qualified supply of cardiac sarcoidosis biologics and unlocks premium-tier pricing corridors in European academic medical centers. Payers in Germany and Japan condition reimbursement rates on manufacturing compliance with these accelerated assessment pathways, compressing margin capture for developers lacking validated contract manufacturing relationships.
Pricing Analysis
Hospital procurement markup layers dominate biologic pricing, with United States academic medical centers capturing 15-25% distribution margins on intravenous infliximab against subcutaneous adalimumab delivered through specialty pharmacy channels. Price differentiation hinges on orphan drug designation tier and site-of-care administration mode, with cardiac indication premiums substantially exceeding pulmonary benchmarks. Cost compression in corticosteroid generics is intensifying because methylprednisolone commoditization has eliminated brand pricing power, making community hospital systems the most price-sensitive buyers while quaternary cardiac centers remain least sensitive due to urgency-driven procurement protocols.
Supply Chain Analysis
Monoclonal antibody production rests on contract manufacturing organizations concentrated in Ireland, Singapore, and Puerto Rico, with fill-finish capacity anchoring downstream biologic supply security. Active pharmaceutical ingredient sourcing draws from Swiss and Japanese specialty chemical producers for TNF-alpha inhibitor cell culture media, while single-use bioreactor components feed from German engineering suppliers. Single-source vulnerability concentrates in viral filter membrane supply, where one Irish manufacturer controls 60% of qualified lots for orphan indication batches. Distribution runs through cold-chain logistics partners certified for EMA GDP compliance, with hospital-owned specialty pharmacies consolidating last-mile delivery for academic center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through FDA orphan drug tax credits and EMA PRIME acceleration, with cardiac sarcoidosis designation emerging as the pivotal milestone restructuring development prioritization across the competitive landscape.
For Market Incumbents: Extend biologic manufacturing capacity into Singapore and Puerto Rico to defuse single-source concentration risk from Irish CMO dependence. Deepen formulary relationships with United States quaternary cardiac centers before JAK-STAT inhibitors erode TNF-alpha inhibitor positioning in steroid-refractory sequencing protocols. Lock in G-BA reimbursement contracts for subcutaneous delivery modes to preempt hospital outpatient department margin compression. For New Entrants and Emerging Players: Begin with cardiac sarcoidosis biomarker development partnerships in German FDG-PET imaging clusters, where diagnostic white space precedes therapeutic entry. Target Japan's Sakigake designation pathway for fastest regulatory validation among refractory case biologics. Pursue telemedicine-integrated monitoring platforms as the go-to-market angle for rural United States pulmonology practices excluded from specialty center access. For Investors and Strategic Acquirers: Roll-up economics work for mechanism innovators with validated immunomodulatory targets because biorepository infrastructure gaps constrain translational research timelines and create captive value in tissue banking assets. Mid-cap biotechs with EMA PRIME-eligible cardiac programs represent the priority acquisition archetype over pulmonary-focused developers facing HTA benchmark compression. Watch FDA breakthrough therapy designation grants to JAK-STAT inhibitors as the inflection signal for therapeutic sequencing disruption.| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Eligibility Pursuit | Accelerated assessment timelines reduce regulatory uncertainty for cardiac sarcoidosis developers targeting orphan indications. |
| Subcutaneous Delivery Platform Investment | Self-administration devices shift site-of-care economics toward clinic-based reimbursement in Germany's G-BA framework. |
| Cardiac Sarcoidosis Biomarker Development | FDG-PET imaging protocols combined with serologic markers unlock diagnostic white space in underdiagnosed extrapulmonary cases. |
| Biorepository Infrastructure Partnership | Multi-organ tissue banking partnerships constrain translational research bottlenecks and accelerate companion diagnostic timelines. |
| Telemedicine-Integrated Monitoring Launch | Remote patient platforms expand enrollment in rural United States markets previously excluded from specialty center access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States academic medical centers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and hospital formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored market sizing across corticosteroid, immunosuppressant, and biologic product tiers.
Segment-weighting approaches distributed value across treatment line, administration route, organ involvement pattern, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from epidemiological prevalence projections, biologic penetration assumptions in refractory case identification, and payer reimbursement elasticity estimates for subcutaneous versus intravenous delivery modes. Forecast inputs incorporated PMDA Sakigake designation velocity, AMNOG fast-track pricing capture windows, and NIH-funded trial enrollment trends at Baltimore and New York City research centers.
Caveats apply where FDA breakthrough therapy designation grants to novel mechanisms, EMA parallel assessment pathway divergences for extrapulmonary indications, or biologic manufacturing disruptions from Irish CMO concentration could materially shift the outlook. A small set of named triggers—including JAK-STAT inhibitor label expansion timing and cardiac sarcoidosis diagnostic protocol adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Behcets Disease Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Churg Strauss Syndrome Market