
 Pure Red Cell Aplasia Market | 2026-2036
Pure Red Cell Aplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Pure Red Cell Aplasia Market Analytics
Modular combination kits pairing erythropoietin with corticosteroid taper protocols is repositioning how hematologists structure treatment episodes. Amgen leverages its recombinant protein manufacturing scale to dominate the erythropoietin supply chain. Roche differentiates through diagnostic-therapeutic integration in anemia management workflows. CSL Behring anchors its position via plasma-derived immunoglobulin portfolios that address autoimmune-mediated PRCA subtypes.
Pure Red Cell Aplasia denotes a rare hematologic disorder characterized by selective disappearance of erythroid precursors in bone marrow, yielding severe normocytic anemia with absolute reticulocyte counts below 10,000 per microliter. The condition demands exogenous erythropoietin stimulation, immunosuppressive intervention, or periodic transfusion support to restore physiologic oxygen-carrying capacity. Injectable delivery modes lead the product landscape due to bioavailability requirements for biologic agents, while subcutaneous administration represents the fastest-growing delivery category as patients transition from hospital-based infusion to self-managed home therapy. Pharmacotherapy commands the dominant treatment approach share, though stem cell transplant adoption accelerates in refractory autoimmune cases where first-line immunosuppression fails.
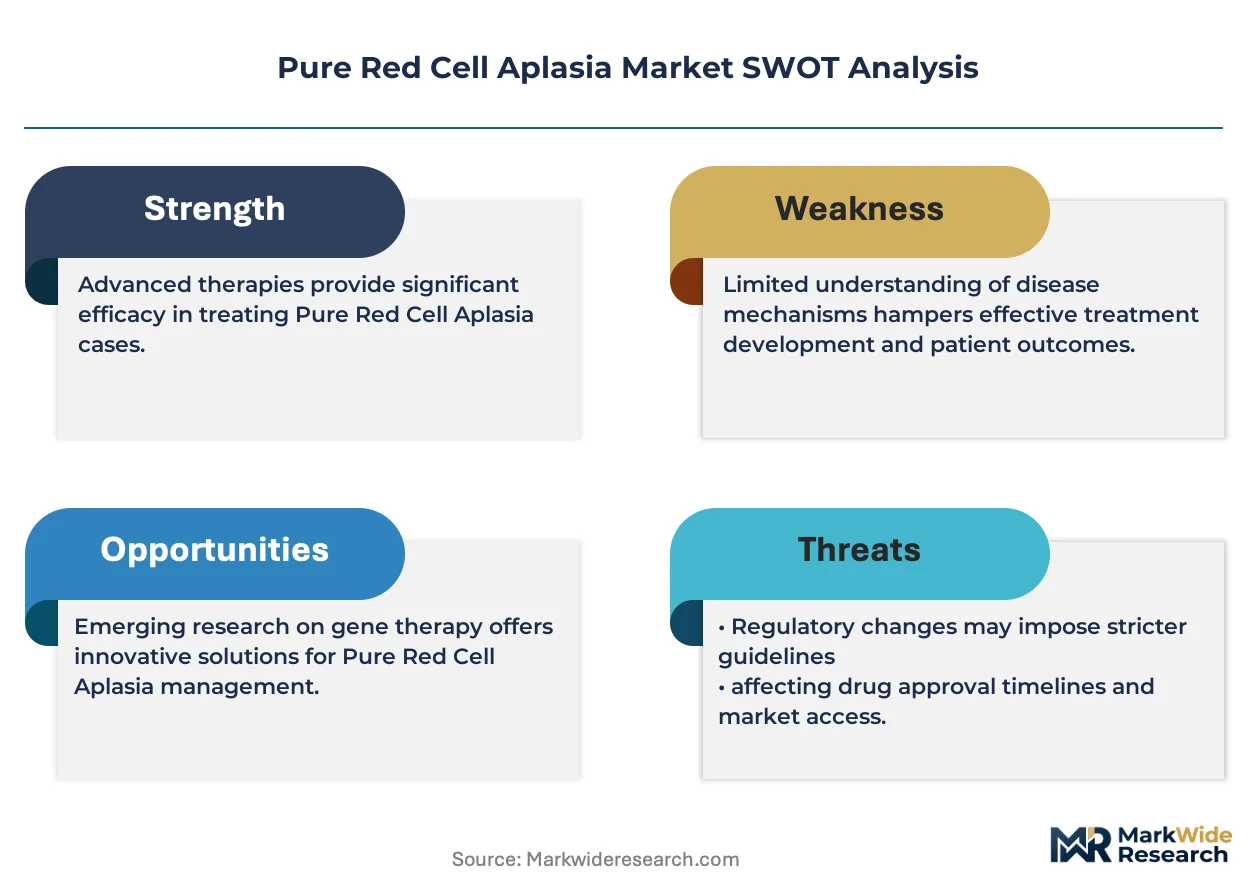
FDA, EMA, and Japan's PMDA govern biologic licensing, orphan drug designation, and post-market surveillance for PRCA therapeutics, with each agency tightening immunogenicity monitoring requirements for erythropoietin products. The EU's MDR and GDPR additionally shape clinical trial conduct and patient registry data handling across European treatment centers. Stakeholders must monitor evolving biosimilar interchangeability standards and country-specific reimbursement thresholds for combination immunosuppressive regimens.
Market Dynamics
Hospital procurement departments are consolidating erythropoietin contracts around single-source biologic suppliers, compressing vendor diversity and amplifying price leverage for high-volume academic medical centers. This concentration dynamic is reshaping how immunosuppressive combination therapies reach treatment sites.
Growth Catalysts
- Orphan Drug Incentives:FDA's seven-year market exclusivity and tax credit provisions for rare disease indications accelerate PRCA therapeutic development pipelines. Biotechnology firms prioritize these accelerated pathways over conventional indications.
- Japan:PMDA's Sakigake designation system fast-tracks regenerative medicine and biologic innovations, reducing review timelines for erythropoietin receptor agonists. Domestic manufacturers leverage this to outpace Western competitors in Asian market entry.
- Subcutaneous Delivery Platforms:Prefilled syringe and auto-injector technologies enable hematology patients to self-administer erythropoietin at home. This modality shift reduces infusion center burden while improving treatment adherence metrics.
Market Restraints
- Plasma Supply Volatility:Immunoglobulin production for autoimmune-mediated PRCA depends on fractionated human plasma collections. Collection disruptions in the United States and Germany create batch-to-batch availability gaps.
- Biosimilar Substitution Limits:FDA's interchangeability standards for erythropoietin biosimilars remain unsettled, blocking automatic pharmacy substitution. Physicians retain prescribing control, slowing cost reduction trajectories.
- Transfusion Dependency:Refractory PRCA patients requiring chronic red cell transfusions face iron overload complications. Chelation therapy adds cost layers without addressing underlying erythroid failure.
Strategic Opportunities
- Germany:The country's dense network of university-affiliated hematology centers creates concentrated access points for novel combination protocols. Manufacturers can pilot risk-sharing agreements with statutory health insurers.
- Gene Therapy Convergence:CRISPR-based erythropoietin receptor modification and lentiviral vector delivery systems are converging toward curative approaches. Early-stage programs target transfusion-independent remission.
- EMA's PRIME Scheme:Priority Medicines designation offers enhanced regulatory support for PRCA therapies addressing unmet medical need. Applicants gain accelerated assessment and scientific advice access.
Industry Challenges
- Immunogenicity Surveillance:Anti-erythropoietin antibody development requires mandatory pharmacovigilance protocols. Treatment centers must maintain specialized laboratory capacity for neutralizing antibody detection.
- Cold Chain Integrity:Biologic immunosuppressants and recombinant proteins demand continuous temperature-controlled distribution. Last-mile delivery failures in rural treatment networks compromise product efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pure Red Cell Aplasia Market |
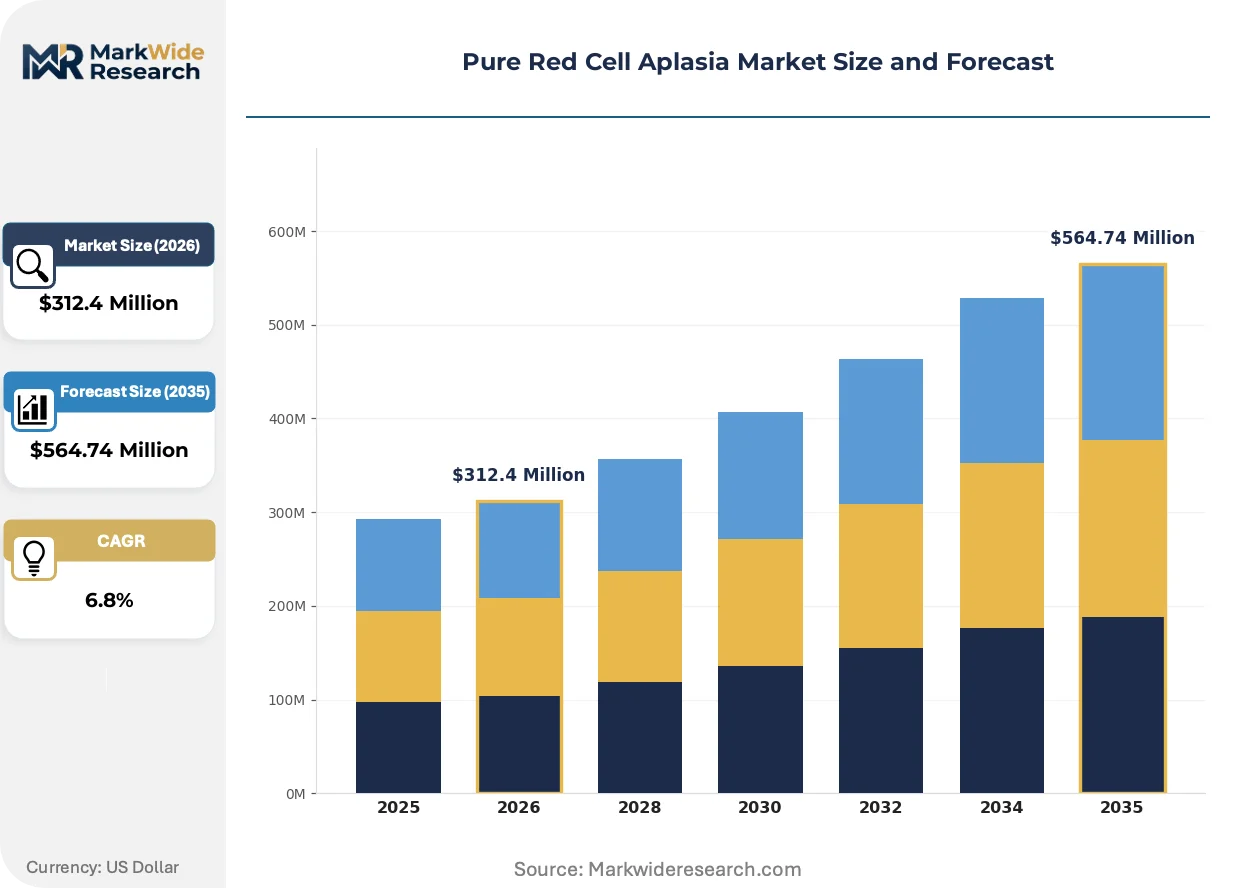
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythropoietin, Blood Transfusion, Immunosuppressants, Corticosteroids End User: Hospitals, Specialty Clinics, Blood Banks, Research Institutes Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous Treatment Approach: Supportive Care, Stem Cell Transplant, Pharmacotherapy, Therapeutic Apheresis |
| Companies Covered | Amgen, Johnson & Johnson, Roche, Novartis, Pfizer, AbbVie, Bristol Myers Squibb, Sanofi, CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pure Red Cell Aplasia Market Evolving Landscape
Biologic manufacturing is pivoting toward continuous processing platforms that compress batch cycle times and reduce facility footprint requirements. This operational shift is altering capital deployment patterns across the erythropoietin supply base.
Continuous bioprocessing technology is electrifying recombinant protein production economics. Contract development and manufacturing organizations in Switzerland and Singapore are retrofitting legacy fed-batch facilities. The technology is enabling 40-60% reduction in cost of goods for high-volume erythropoietin analogs.
EMA's Medical Device Regulation (MDR) reclassification of drug-device combination products is forcing auto-injector manufacturers to submit enhanced clinical evidence. Prefilled syringe suppliers face notified body capacity constraints. German and French hematology centers are delaying procurement decisions pending MDR certificate availability.
Patient advocacy networks are consolidating purchasing influence through disease-specific foundations in the United States and Japan. These organizations negotiate formulary placement and prior authorization support directly with payers. The channel is most visible in Medicare Advantage plans and Japan's regional health insurance associations.
Pure Red Cell Aplasia Market Segmentation
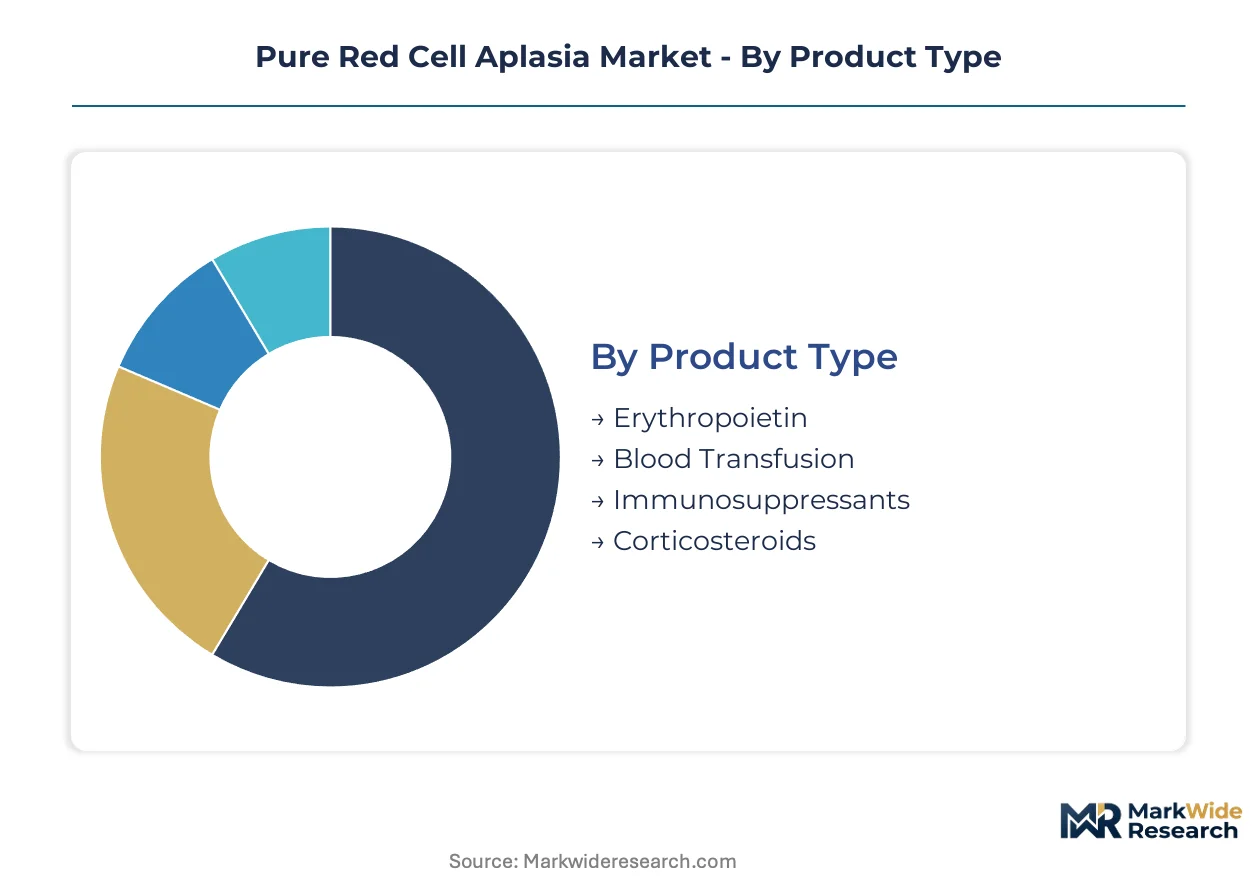
Pure Red Cell Aplasia treatment selection hinges on autoimmune etiology versus parvovirus-driven pathology, with each indication demanding distinct therapeutic combinations. Supply concentration around recombinant biologics and plasma-derived immunoglobulins shapes how hematologists access first-line versus salvage protocols across institutional settings.
Product Type:
Manufacturing scale and cold chain infrastructure determine which therapeutic classes achieve consistent availability across treatment networks.
- Erythropoietin:Recombinant human erythropoietin and its analogs stimulate erythroid progenitor proliferation in bone marrow. United States academic medical centers concentrate procurement around single-source biologic contracts, amplifying price leverage while compressing vendor diversity. FDA immunogenicity monitoring requirements add compliance layers to distribution.
- Immunosuppressants:Cyclosporine, tacrolimus, and rituximab target T-cell and B-cell mediated erythroid precursor destruction. German university hospitals pilot risk-sharing agreements with statutory insurers for combination protocols, creating concentrated access points for novel regimens.
- Blood Transfusion:Leukoreduced packed red cells provide immediate oxygen-carrying capacity restoration. Japanese regional health insurance associations negotiate formulary placement through patient advocacy foundations.
- Corticosteroids:Prednisone and methylprednisolone serve as first-line immunosuppressive bridge therapy. Plasma supply volatility in United States and German collection networks creates intermittent availability constraints.
Today's leader: Erythropoietin. Tomorrow's challenger: Immunosuppressants.
End User:
Institutional purchasing power and specialized laboratory capacity segment the market into distinct procurement tiers.
- Hospitals:Tertiary care centers manage refractory cases requiring multimodal intervention and transfusion support. Consolidated erythropoietin contracting around high-volume academic medical centers reshapes vendor access.
- Specialty Clinics:Outpatient hematology practices in Germany and Japan enable self-administered subcutaneous therapy transitions. Prefilled syringe and auto-injector technologies reduce infusion center burden while improving adherence metrics.
- Blood Banks:Transfusion services coordinate chronic red cell support for refractory patients. Iron overload complications from dependency add chelation therapy cost layers.
- Research Institutes:CRISPR-based erythropoietin receptor modification and lentiviral vector programs target curative approaches. EMA's PRIME Scheme offers accelerated assessment for transfusion-independent remission candidates.
Procurement gravity centers on hospital systems. Patient migration toward home-based administration is accelerating specialty clinic expansion.
Delivery Mode:
Bioavailability requirements and patient self-management capabilities drive modality selection across treatment episodes.
- Injectable:Intramuscular and subcutaneous recombinant protein delivery dominates biologic agent administration. Continuous bioprocessing platforms in Swiss and Singaporean contract manufacturing organizations compress batch cycle times.
- Subcutaneous:Prefilled syringe and auto-injector formats enable hematology patients to self-administer erythropoietin at home. EMA's MDR reclassification of drug-device combinations forces enhanced clinical evidence submissions, delaying German and French procurement decisions.
- Intravenous:Hospital-based infusion delivers immunosuppressive biologics requiring controlled administration settings. Cold chain integrity failures in rural treatment networks compromise product efficacy.
- Oral:Corticosteroid taper protocols and small-molecule immunosuppressants offer patient convenience. Bioavailability limitations restrict application to non-biologic therapeutic classes.
Institutional infusion retains volume leadership. Subcutaneous self-administration is gaining share fastest among ambulatory-eligible patients.
Treatment Approach:
Disease severity, autoimmune versus infectious etiology, and prior treatment response determine protocol selection.
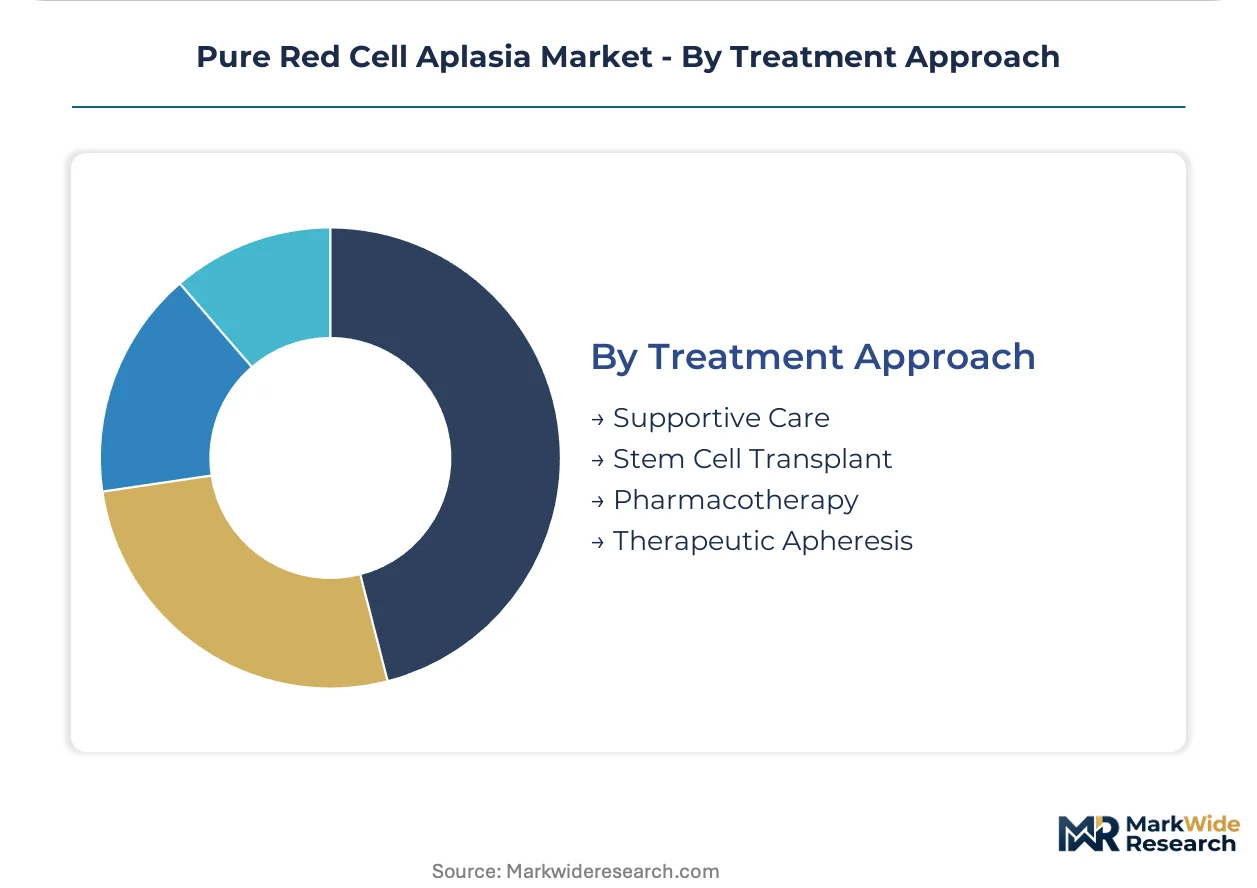
- Pharmacotherapy:Combination immunosuppression with erythropoietin stimulation represents the dominant first-line strategy. FDA orphan drug incentives and Japan's PMDA Sakigake designation accelerate pipeline development.
- Supportive Care:Transfusion dependency and infection prophylaxis sustain patients awaiting treatment response or transplant eligibility. Iron chelation requirements add cost without addressing underlying erythroid failure.
- Stem Cell Transplant:Allogeneic transplantation accelerates in refractory autoimmune cases where first-line immunosuppression fails. Specialized hematology infrastructure in United States, Germany, and Japan supports advanced access.
- Therapeutic Apheresis:Plasma exchange and immunoadsorption address severe antibody-mediated disease. Limited center availability restricts application to tertiary referral networks.
Pharmacotherapy commands current protocol share. Stem cell transplant adoption is climbing fastest among refractory autoimmune subtypes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pure Red Cell Aplasia Market traces its therapeutic foundation to recombinant erythropoietin development pioneered in United States biotechnology clusters during the 1980s, with subsequent clinical protocol refinement spreading through German hematology networks and Japanese regulatory innovation pathways.
United States
FDA orphan drug incentives and seven-year market exclusivity provisions accelerate PRCA therapeutic pipelines, while Medicare Advantage plans and patient advocacy foundations negotiate formulary placement for combination immunosuppressive regimens. Tertiary care centers in Boston and the Research Triangle manage refractory cases requiring multimodal intervention and specialized laboratory capacity for neutralizing antibody detection.
Germany
Statutory health insurers pilot risk-sharing agreements with manufacturers for novel combination protocols, leveraging the country's dense network of university-affiliated hematology centers in Munich, Heidelberg, and Berlin. EMA's PRIME Scheme offers accelerated assessment access for transfusion-independent remission candidates targeting curative approaches.
Japan
PMDA's Sakigake designation system fast-tracks regenerative medicine and biologic innovations, reducing review timelines for erythropoietin receptor agonists. Regional health insurance associations in Kanto and Kansai coordinate formulary placement through consolidated patient advocacy networks, enabling self-administered subcutaneous therapy transitions.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich retrofit legacy fed-batch facilities with continuous bioprocessing platforms, compressing batch cycle times for recombinant protein production. Swissmedic governs biologic licensing with stringent immunogenicity monitoring requirements that shape distribution compliance layers.
United Kingdom
NHS England's specialized commissioning framework concentrates PRCA treatment access in London and Manchester hematology centers with stem cell transplant capability. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for biologic immunosuppressants addressing refractory autoimmune subtypes.
Pure Red Cell Aplasia Market Competitive Landscape
Premium-margin players sit above commodity-margin players across manufacturing scale and cold chain infrastructure dimensions. The vendor base organizes around recombinant protein specialists, plasma-derived immunoglobulin suppliers, and integrated diagnostic-therapeutic platforms. Three archetypes dominate: large-cap biologics manufacturers with erythropoietin supply chain control, mid-cap immunosuppressive portfolio builders, and plasma fractionators addressing autoimmune-mediated subtypes. Competitive moves center on continuous bioprocessing technology licensing and hospital procurement contract consolidation.
Within the large-cap biologics tier, Amgen anchors recombinant protein manufacturing scale, while Roche exemplifies diagnostic-therapeutic integration in anemia management workflows. CSL Behring occupies a position among plasma-derived immunoglobulin specialists addressing autoimmune-mediated PRCA subtypes. These three represent distinct competitive vectors: manufacturing scale, workflow integration, and plasma portfolio depth.
| Leading Market Players |
|---|
| Amgen |
| Johnson & Johnson |
| Roche |
| Novartis |
| Pfizer |
| AbbVie |
| Bristol Myers Squibb |
| Sanofi |
| CSL Behring |
| Others |
Value Network & Pricing Analysis
Recombinant biologic certification tiers bifurcate the erythropoietin landscape into FDA-validated originator products and emerging biosimilar alternatives, with each tier commanding distinct procurement contracts and cold chain investment profiles across hospital systems.
Pricing Analysis
Three-tier pricing structure across premium originator, validated biosimilar, and economy-tier plasma-derived alternatives dominates hospital formulary negotiations. Price differentiation hinges on FDA immunogenicity certification status and volume commitment scale from academic medical centers. Cost compression in the biosimilar tier is intensifying because unresolved interchangeability standards force physician-controlled prescribing. Blood banks exhibit highest price sensitivity due to transfusion dependency volumes, while tertiary transplant centers prioritize premium-tier supply security.
Supply Chain Analysis
FDA and EMA cold chain qualification requirements gate market access for erythropoietin manufacturers, forcing continuous temperature validation investments. Manufacturing concentrates in the United States, Switzerland, and Singapore, with recombinant protein production drawing from CHO cell culture media, single-use bioreactor systems, and plasma fractionation feedstock. Single-source vulnerability runs through consolidated academic medical center contracting. Distribution runs through specialty pharmaceutical wholesalers with dedicated biologic handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pure Red Cell Aplasia Market functions as a regulatory compounder where FDA orphan drug exclusivity provisions and EMA PRIME Scheme accelerations compound development economics and access premiums.
For Market Incumbents: Extend manufacturing scale advantages through continuous bioprocessing retrofits in Swiss and Singaporean facilities to compress cost of goods for erythropoietin analogs. Defend against biosimilar substitution threats by deepening hospital procurement contract consolidation around single-source biologic supply agreements with high-volume academic medical centers.
For New Entrants and Emerging Players: The pricing gap between premium originator erythropoietin and economy-tier immunosuppressant alternatives opens white-space opportunity in subcutaneous auto-injector combination formats for ambulatory transition protocols. Target German university-affiliated hematology centers piloting risk-sharing agreements with statutory health insurers. Enter through diagnostic-therapeutic integration partnerships rather than standalone molecule competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where plasma-derived immunoglobulin portfolios face collection volatility in United States and German donor networks. Long-term viability favors manufacturers with captive bioreactor capacity and validated cold chain infrastructure. Mid-cap immunosuppressive portfolio builders with EMA PRIME Scheme designations represent priority acquisition archetypes. Monitor FDA biosimilar interchangeability determinations as the critical inflection signal for pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity accelerates PRCA therapeutic pipelines ahead of conventional indications. |
| Continuous Bioprocessing Scale-Up | Swiss and Singaporean CDMO retrofits enable 40-60% cost reduction for recombinant erythropoietin production. |
| Subcutaneous Auto-Injector Development | EMA MDR-compliant drug-device combinations capture patient migration from hospital infusion to home administration. |
| Risk-Sharing Agreement Pilot | German statutory health insurer partnerships create concentrated access points for novel combination immunosuppressive protocols. |
| Plasma Collection Network Expansion | CSL Behring and fractionators address autoimmune-mediated PRCA subtypes amid United States and German collection disruptions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hematology department heads, hospital procurement managers, regulatory affairs leads at biologic manufacturers, and payer access specialists with secondary validation against FDA orphan drug filings, EMA PRIME Scheme submissions, ClinicalTrials.gov protocols, and hospital formulary databases. Bottom-up patient population estimates and top-down therapeutic class spend analysis triangulated market sizing.
Comparable historical periods anchored the projection horizon across treatment approach, delivery mode, and autoimmune versus infectious etiology segments. CAGRs derived from clinician adoption curve modeling for subcutaneous self-administration, stem cell transplant eligibility expansion, and biosimilar penetration assumptions. Forecast inputs incorporated immunogenicity surveillance protocol expansion, plasma collection network capacity, and continuous bioprocessing technology diffusion rates.
Caveats apply where FDA biosimilar interchangeability determinations, plasma supply disruptions, or gene therapy clinical readouts could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pathway timelines and clinician prescribing behavior stability. A model refresh is warranted upon material change in EMA MDR certificate availability or PMDA Sakigake designation grant rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Asia-Pacific Down Syndrome Market