
 Cri-Du-Chat Syndrome Treatment Market | 2026-2036
Cri-Du-Chat Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cri-Du-Chat Syndrome Treatment Market Outlook
A shift from single-source genetic testing to multi-source diagnostic confirmation is rebalancing supply security for families seeking Cri-du-chat syndrome evaluations. Invitae Corporation leverages its broad rare-disease panel infrastructure to capture outpatient referral flows. Centogene AG anchors its position through centralized European laboratory capacity and biobank-linked analytics. Hoffmann-La Roche Ltd sustains competitive relevance via integrated companion diagnostic development alongside therapeutic pipelines.
Cri-du-chat syndrome treatment encompasses therapeutic and supportive interventions targeting the deletion on the short arm of chromosome 5, including speech therapy, behavioral management, and nutritional support delivered through multidisciplinary pediatric teams. Symptomatic treatment currently dominates clinical practice as the standard of care, while gene therapy represents an emerging frontier with concentrated R&D investment. Behavioral therapy commands sustained demand from school-age patient cohorts, and educational support programs are expanding fastest as public awareness of neurodevelopmental rare diseases rises.
The FDA Orphan Drug program and the European Medicines Agency's priority medicines scheme shape incentive structures for developers targeting chromosomal deletion syndromes. The Health Insurance Portability and Accountability Act in the United States and the EU's General Data Protection Regulation constrain how genomic data flows between clinics, laboratories, and research consortia. Stakeholders must monitor regulatory clarity on gene therapy reimbursement frameworks and data-sharing protocols to align portfolio decisions with evolving access pathways.
Market Dynamics
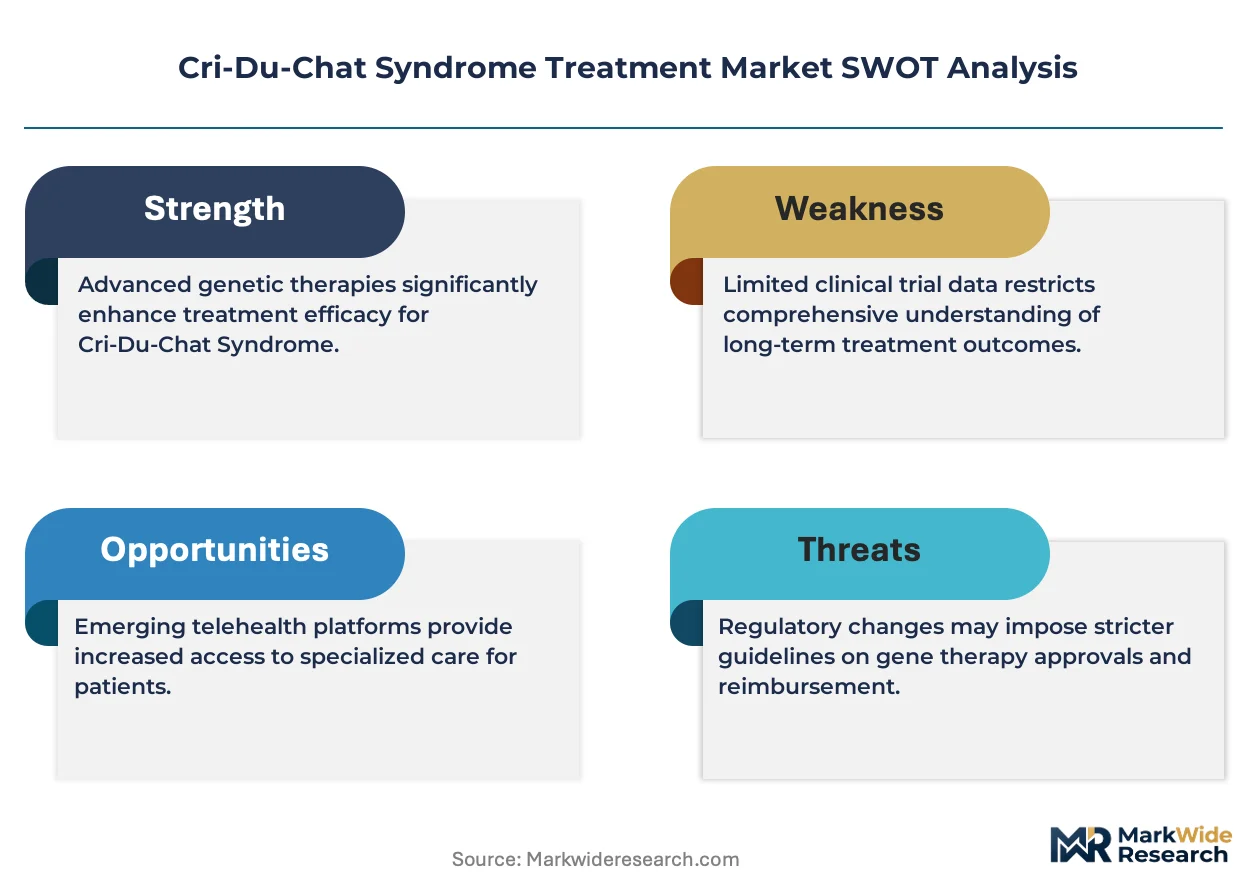
The FDA Orphan Drug Designation program is restructuring pharmaceutical investment priorities for chromosomal deletion syndromes, channeling R&D capital toward rare disease mechanisms previously deprioritized by blockbuster economics.
Growth Catalysts
- Orphan drug incentives:The FDA's tax credit and market exclusivity provisions reduce development risk for therapies targeting Cri-du-chat syndrome's small patient population.
- Multidisciplinary care centers:Pediatric neurodevelopmental clinics in the United States are expanding genetic counseling capacity to capture early diagnostic referrals.
- Chromosomal microarray testing:This diagnostic technology is shortening time-to-diagnosis from years to months for infants presenting with characteristic cry patterns.
Market Restraints
- Patient dispersion:The estimated 50-60 annual US births with Cri-du-chat syndrome create geographic fragmentation that complicates clinical trial recruitment.
- Gene therapy manufacturing costs:Viral vector production for chromosomal disorders requires specialized CDMO capacity concentrated in Massachusetts and North Carolina.
- HIPAA-GDPR data friction:Cross-border genomic data sharing between US clinics and European research consortia faces compliance bottlenecks.
Strategic Opportunities
- Educational support programs:School districts in California and New York are mandating specialized IEP services for rare neurodevelopmental conditions.
- Speech-generating devices:Augmentative communication technology is penetrating the behavioral therapy segment as Medicaid coverage expands.
- EMA priority medicines scheme:European accelerated assessment pathways could compress regulatory timelines for chromosomal syndrome therapeutics.
Industry Challenges
- Genetic counselor workforce gaps:The Association of Genetic Counseling programs reports insufficient graduates to meet rare disease diagnostic demand.
- Companion diagnostic co-development:Parallel validation of biomarker assays and therapeutic candidates stretches R&D timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cri-Du-Chat Syndrome Treatment Market |
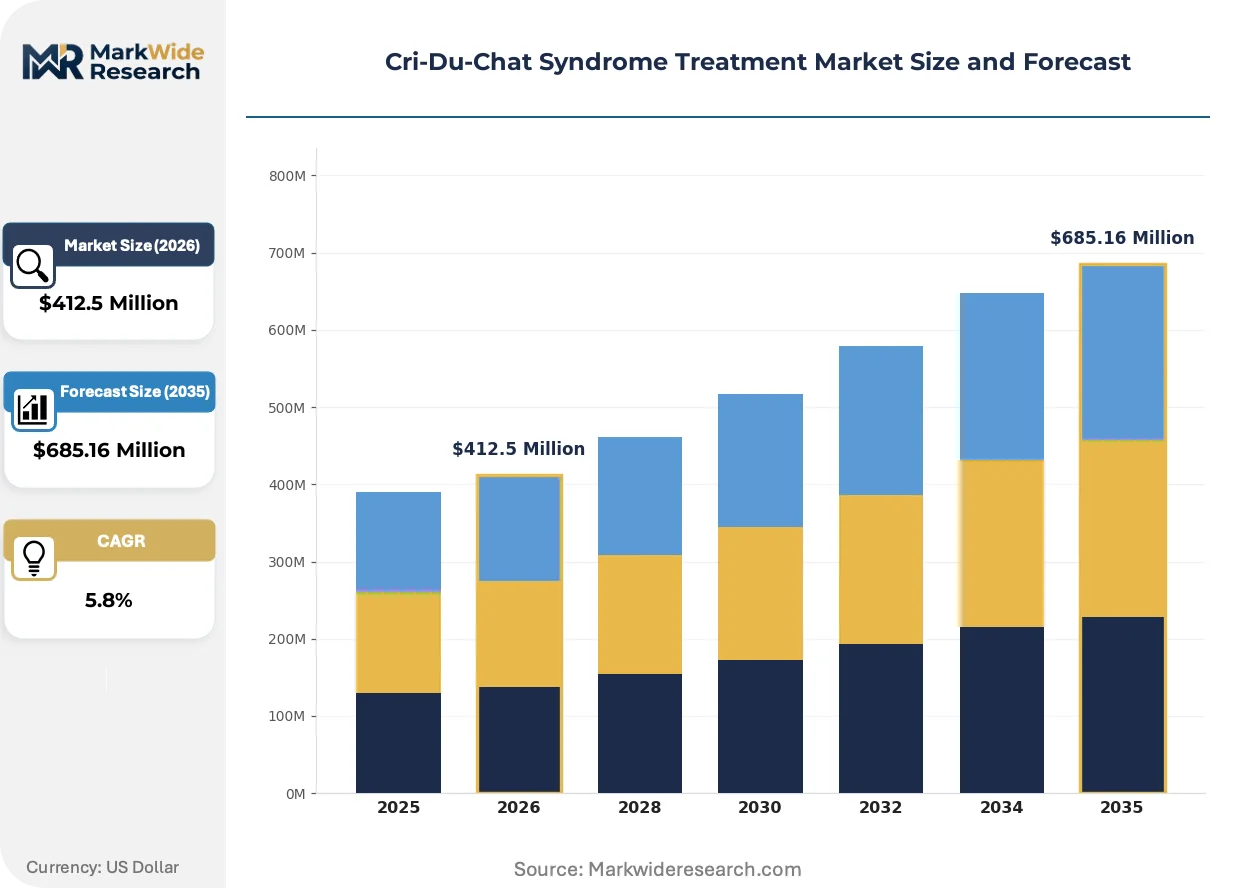
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Symptomatic Treatment, Educational Support, Behavioral Therapy Delivery Mode: Oral, Injectable, Inhalation, Transdermal End User: Pediatric Clinics, Hospitals, Rehabilitation Centers, Home Care Application: Behavioral Management, Nutritional Support, Speech Therapy, Cognitive Development |
| Companies Covered | Invitae Corporation, Centogene AG, Hoffmann-La Roche Ltd, Eurofins Scientific, Illumina Inc, Natera Inc, PerkinElmer Inc, Quest Diagnostics, Hoppers Physio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cri-Du-Chat Syndrome Treatment Market Strategic Shifts
Gene therapy platforms are displacing symptomatic management as the dominant R&D paradigm for chromosomal disorders, while regulatory frameworks scramble to adapt reimbursement models to one-time curative interventions.
CRISPR-based epigenome editing is consolidating research attention for Cri-du-chat syndrome, with academic medical centers in Boston and San Francisco establishing dedicated chromosomal engineering programs. Pediatric geneticists at these institutions are prioritizing preclinical models that address the 5p deletion's variable expressivity. The technology is consolidating investment away from traditional small-molecule symptomatic approaches toward permanent genetic correction strategies.
The European Medicines Agency's priority medicines scheme is accelerating assessment timelines for chromosomal syndrome therapies, compressing the gap between Phase II data and conditional approval. German and French regulators are piloting adaptive licensing pathways that allow post-authorization evidence generation. Rare disease patient advocacy groups in the Netherlands and Belgium are leveraging this framework to pressure earlier access negotiations.
Family-driven diagnostic journeys are shortening the path from pediatrician visit to geneticist referral, with parents of infants presenting cat-like cry symptoms now arriving at appointments with self-ordered microarray results. Telemedicine genetic counseling is displacing traditional in-person consultations in rural Texas and Montana markets where subspecialist density remains thin. This behavioral shift is most visible in Mountain West states where geographic isolation previously delayed diagnostic confirmation by 18-24 months.
Cri-Du-Chat Syndrome Treatment Market Segmentation
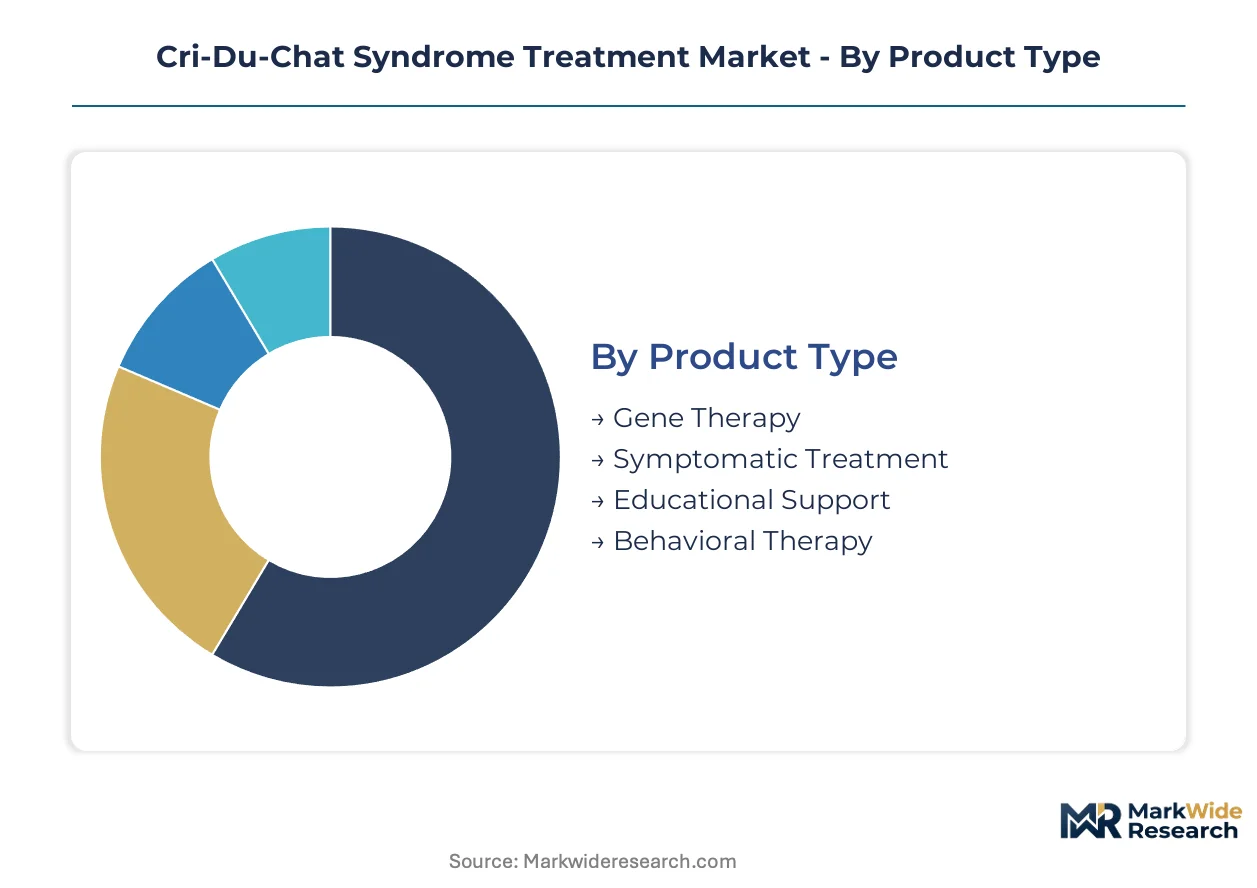
Segmentation in the Cri-du-chat syndrome treatment market reveals distinct procurement patterns across therapeutic modalities and care settings. Understanding these divisions helps stakeholders align R&D investment with reimbursement pathways and patient access points.
Product Type:
Standalone therapeutic interventions operate independently within clinical workflows, while embedded support systems integrate into broader neurodevelopmental care plans.
- Symptomatic Treatment:Encompasses pharmacological management of seizures, gastroesophageal reflux, and sleep disturbances through standard pediatric formulations. Demand concentrates in United States tertiary children's hospitals where multidisciplinary teams coordinate polypharmacy protocols for complex chromosomal presentations.
- Gene Therapy:Represents CRISPR-based and viral vector approaches targeting the 5p chromosomal deletion at its source. Investment is accelerating in Boston and San Francisco academic medical centers where preclinical models address variable deletion sizes.
- Behavioral Therapy:Applied behavior analysis and structured intervention programs address self-injury and social communication deficits.
- Educational Support:Individualized education programs and specialized classroom accommodations mandated under disability rights frameworks.
Symptomatic treatment leads volumes today; gene therapy is gaining share fastest.
Delivery Mode:
Route selection depends on developmental stage, with infant-friendly formulations commanding premium positioning against adolescent-compliant alternatives.
- Oral:Liquid suspensions and crushable tablets dominate early childhood administration where swallowing capability remains undeveloped. Medicaid reimbursement rates in California and New York influence formulary placement for these formulations.
- Injectable:Subcutaneous and intramuscular routes serve emergency seizure management and long-acting neuroleptic depot preparations. Hospital procurement committees in Texas and Florida drive volume commitments through GPO contracts.
- Inhalation:Nebulized bronchodilators address respiratory complications common in the syndrome's infant presentation.
- Transdermal:Patch-based delivery circumvents gastrointestinal motility issues frequent in this patient population.
Oral formulations capture the largest patient days; injectable gene therapy vectors show the steepest expansion trajectory.
End User:
Site-of-care decisions reflect diagnostic complexity, with centralized genetic expertise competing against distributed rehabilitation capacity.
- Pediatric Clinics:Specialized neurodevelopmental practices in metropolitan United States markets provide initial diagnosis and longitudinal care coordination. These sites capture the highest per-patient revenue through bundled genetic counseling and therapy referrals.
- Hospitals:Academic medical centers manage acute complications and surgical interventions for cardiac and renal anomalies associated with the syndrome.
- Rehabilitation Centers:Dedicated facilities deliver intensive speech and occupational therapy protocols.
- Home Care:Skilled nursing and therapy services extend institutional protocols into residential settings.
Pediatric clinics anchor diagnostic volumes; home care is expanding most quickly as payers push site-of-care migration.
Application:
Therapeutic focus areas align with developmental windows, creating sequential demand patterns across the patient lifespan.
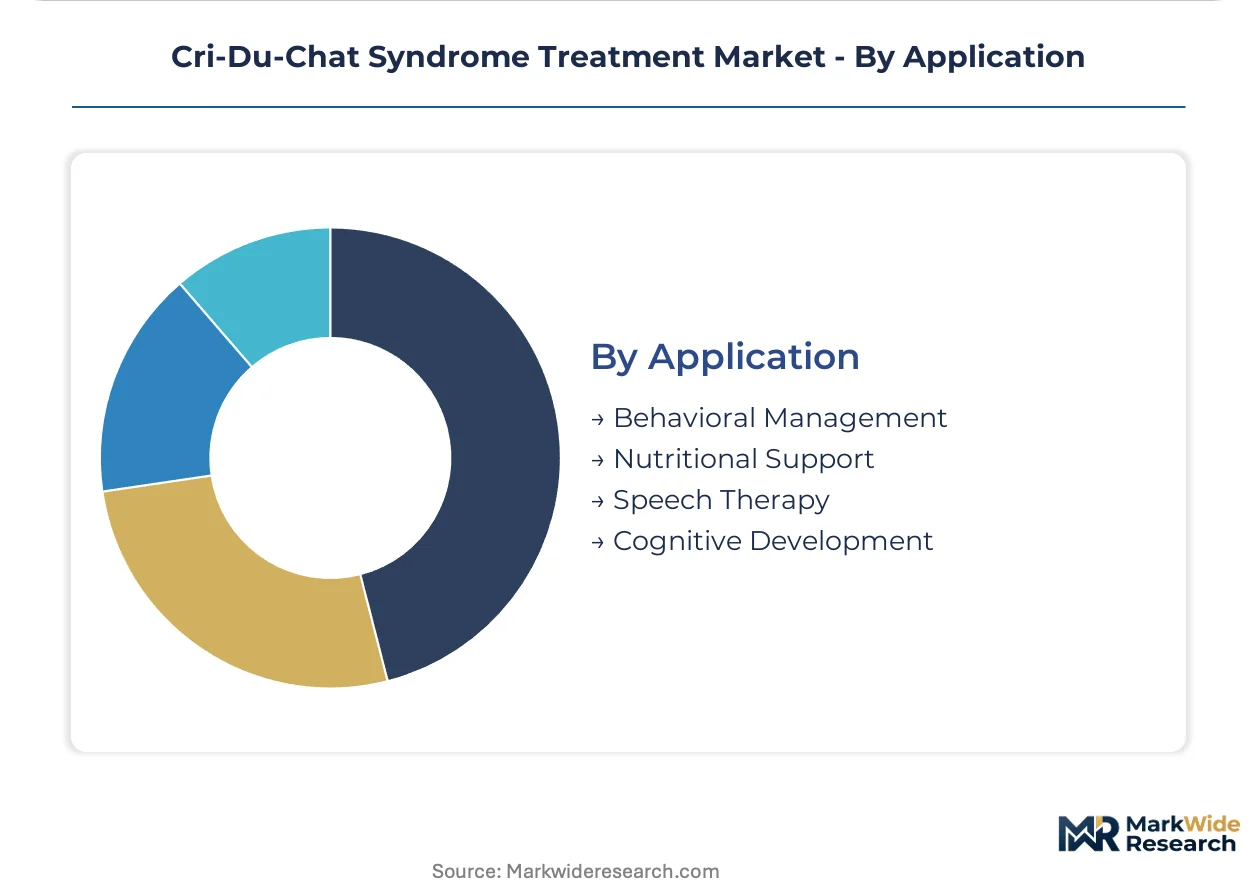
- Speech Therapy:Augmentative and alternative communication interventions address the syndrome's hallmark expressive language deficits. School districts in California and New York are mandating dedicated AAC specialist coverage in IEP teams.
- Behavioral Management:Functional behavioral assessment and intervention planning target self-injurious and aggressive presentations. Demand is intensifying in United States residential treatment facilities as transition-age youth exit pediatric systems.
- Nutritional Support:Enteral feeding and dysphagia management address failure-to-thrive presentations in infancy.
- Cognitive Development:Early intervention programs and adaptive skill curricula target intellectual disability across severity levels.
Speech therapy leads service utilization today; behavioral management is climbing the fastest as adolescent cohorts age into complex presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors chromosomal disorder research concentration, with academic medical centers driving gene therapy preclinical development and specialized pediatric neurodevelopmental clinics capturing diagnostic referral flows from across the United States.
United States
Pediatric neurodevelopmental centers in Massachusetts and North Carolina attract families seeking multidisciplinary Cri-du-chat syndrome care, while the FDA Orphan Drug Designation program channels tax credits and market exclusivity toward rare chromosomal disorder development. HIPAA compliance frameworks constrain cross-border genomic data sharing with European research consortia.
Germany
Centralized laboratory capacity in Rostock anchors rare disease diagnostic confirmation workflows, with Centogene AG leveraging biobank-linked analytics to capture European referral volumes. The EMA priority medicines scheme accelerates assessment timelines for chromosomal syndrome therapeutics, while adaptive licensing pilots in Berlin and Munich allow post-authorization evidence generation.
France
ANSM regulatory clarity on gene therapy reimbursement frameworks shapes pharmaceutical portfolio decisions, with Paris-based academic hospitals establishing dedicated chromosomal engineering research programs. Rare disease patient advocacy groups in Lyon and Marseille leverage EMA accelerated pathways to pressure earlier access negotiations for deletion syndrome interventions.
United Kingdom
London genetic counseling services coordinate longitudinal care for Cri-du-chat syndrome patients, with NHS England mandating specialized educational support programs under disability rights frameworks. Genomic England's data infrastructure enables research consortia to address variable 5p deletion expressivity in preclinical models.
Switzerland
Swissmedic's precision medicine frameworks attract Hoffmann-La Roche Ltd's integrated companion diagnostic development alongside therapeutic pipelines, with Basel clusters concentrating viral vector manufacturing expertise for chromosomal disorder applications. Zurich pediatric clinics expand telemedicine genetic counseling to address rural access gaps.
Cri-Du-Chat Syndrome Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue gene therapy platforms and digital diagnostic infrastructure. The market structures around three distinct maturity levels: legacy diagnostic laboratories with broad rare-disease panels, academic medical center spinouts commercializing chromosomal engineering research, and specialized genetic counseling networks capturing outpatient referral flows. Dominant competitive moves include strategic partnerships between diagnostic developers and therapeutic pipelines, plus geographic expansion of centralized laboratory capacity into underserved regional markets.
Among North American diagnostic specialists, Invitae Corporation, Natera Inc, and Quest Diagnostics represent the scale-driven archetype, each leveraging broad testing infrastructure to capture fragmented rare disease referral volumes. These entities exemplify how laboratory networks consolidate market position through outpatient clinic relationships rather than therapeutic development, occupying positions that bridge initial suspicion—typically cat-like cry presentation in infants—to confirmatory chromosomal microarray analysis.
| Leading Market Players |
|---|
| Invitae Corporation |
| Centogene AG |
| Hoffmann-La Roche Ltd |
| Eurofins Scientific |
| Illumina Inc |
| Natera Inc |
| PerkinElmer Inc |
| Quest Diagnostics |
| Hoppers Physio |
| Others |
Value Chain & Pricing Dynamics
HIPAA compliance certification gates qualified laboratory participation in United States Cri-du-chat syndrome diagnostic workflows, restricting premium-tier pricing access to vendors with validated genomic data infrastructure. This regulatory filter concentrates pricing power among centralized testing platforms while excluding smaller regional laboratories from high-margin rare-disease panel contracts.
Pricing Analysis
Input-cost pass-through from viral vector manufacturing and specialized CDMO capacity drives pricing stratification across gene therapy development tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated companion diagnostic bundles from basic chromosomal microarray screening and unbundled counseling services. Pricing pressure stems from Medicaid reimbursement compression in California and New York school-mandated educational support programs. Behavioral therapy providers exhibit highest price sensitivity due to thin margins on IEP-contracted services, while academic medical centers show lowest sensitivity given orphan drug tax credit offsets.
Supply Chain Analysis
Regional distribution centers in Massachusetts and North Carolina anchor hub-and-spoke patterns for viral vector production, with satellite cold-chain logistics extending into pediatric clinic networks across Texas and Florida. Manufacturing concentration in the United States, Germany, and Switzerland draws from plasmid DNA substrates, specialized cell lines, and GMP-grade reagents. Single-source vulnerability in CRISPR guide RNA synthesis creates bottleneck exposure for preclinical research consortia. Distribution runs through academic medical center procurement committees and GPO contracts rather than direct manufacturer-to-clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Cri-du-chat syndrome services hinges on telemedicine genetic counseling scale economics, collapsing per-consultation delivery costs while capturing geographically dispersed referral flows previously lost to diagnostic delay.
For Market Incumbents: Cement dominance through backward integration into viral vector manufacturing capacity in North Carolina and Massachusetts, capturing CDMO margin currently flowing to third-party suppliers. Deepen biobank-linked analytics partnerships with European research consortia to preempt emerging entrant platform launches. Genetic counselor workforce scarcity threatens service expansion timelines; automated counseling workflows represent the critical defensive investment area. For New Entrants and Emerging Players: Pediatric clinic networks in rural Mountain West states offer the most penetrable white-space geography, where telemedicine infrastructure gaps previously extended diagnostic confirmation by 18-24 months. School district IEP service mandates in California and New York create entry points for educational support program specialization. Go-to-market positioning should emphasize augmentative communication device bundling with behavioral therapy protocols. For Investors and Strategic Acquirers: Roll-up economics work for chromosomal disorder diagnostic platforms because FDA Orphan Drug Designation incentives concentrate development risk tolerance among scaled laboratory networks. Five-to-ten year viability favors entities with integrated companion diagnostic-therapeutic pipelines over standalone testing providers. Watch EMA adaptive licensing pathway adoption rates as the inflection signal for European market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Parallel biomarker validation with therapeutic candidates compresses FDA review timelines for chromosomal syndrome interventions. |
| Telemedicine Genetic Counseling Scale-Up | Remote consultation platforms capture rural referral flows in Texas and Montana previously lost to geographic isolation. |
| Biobank-Linked Analytics Partnership | Centogene AG's Rostock infrastructure demonstrates how European laboratory capacity anchors cross-border research collaboration. |
| Orphan Drug Designation Pursuit | FDA tax credits and market exclusivity provisions reduce development risk for therapies targeting 50-60 annual US births. |
| Augmentative Communication Device Bundling | Medicaid coverage expansion for speech-generating devices penetrates behavioral therapy segments with hardware-software integration. |
Study Parameters
Bottom-up pediatric clinic referral modeling reconciled against top-down pharmaceutical pipeline tracking forms the analytical core of this study. Primary interviews with genetic counselors, pediatric neurodevelopmentalists, hospital procurement managers, and orphan drug development executives combined with secondary validation against FDA Orphan Drug Designation filings, ClinicalTrials.gov entries, EMA priority medicines scheme records, and state Medicaid formulary databases. Triangulation between demand-side service utilization patterns and supply-side therapeutic development milestones ensures cross-verified market sizing.
Historical trendline analysis of chromosomal microarray testing adoption, gene therapy investment flows, and multidisciplinary care center expansion established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include therapeutic modality, delivery route, end-user site-of-care, and developmental-stage application need. CAGRs derived from fitted growth curves adjusted for regulatory pathway probability and reimbursement framework evolution. Forecast inputs incorporate orphan drug incentive utilization rates and telemedicine penetration thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy clinical trial readouts and CMS reimbursement policy shifts for one-time curative interventions. Outputs reflect documented assumptions regarding patient population stability and regulatory incentive continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market