
 Gastrointestinal Rare Diseases Treatment Market | 2026-2036
Gastrointestinal Rare Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Rare Diseases Treatment Market Foresight
Buyer concentration among specialty clinics is expanding as hospital systems consolidate rare disease service lines into dedicated centers of excellence. Takeda Pharmaceutical Company Limited anchors its position through deep vertical integration in gastroenterology biologics manufacturing. Nestlé Health Science differentiates via its nutrition-therapy hybrid model for short bowel syndrome management. Mirum Pharmaceuticals, Inc. specializes in bile acid modulation therapies for pediatric rare liver-gut disorders.
Gastrointestinal rare diseases treatment encompasses pharmacologic and nutritional interventions targeting conditions with prevalence below one in two thousand individuals, typically requiring biologic agents with cold-chain distribution and parenteral administration protocols. These therapies serve to modify disease progression, manage malabsorption, and prevent irreversible intestinal damage in patient populations with limited alternative options. Biologics currently occupy the largest margin pool due to manufacturing complexity and orphan pricing protections, while gene therapies represent the fastest-expanding category as vector delivery technologies mature. Enzyme replacement maintains steady demand in lysosomal storage disorders with gastrointestinal manifestations, though competition from substrate reduction therapies is intensifying.
The FDA Orphan Drug Act and EMA Committee for Orphan Medicinal Products jointly shape market access through tax credits, protocol assistance, and extended exclusivity periods that de-risk development for low-prevalence indications. ISO 14155 clinical investigation standards and country-specific pharmacovigilance requirements further govern trial design and post-market surveillance across regulated markets. Stakeholders must monitor how gene therapy durability data and biosimilar entry timelines will reshape investment priorities in gastrointestinal rare disease portfolios.
Market Dynamics
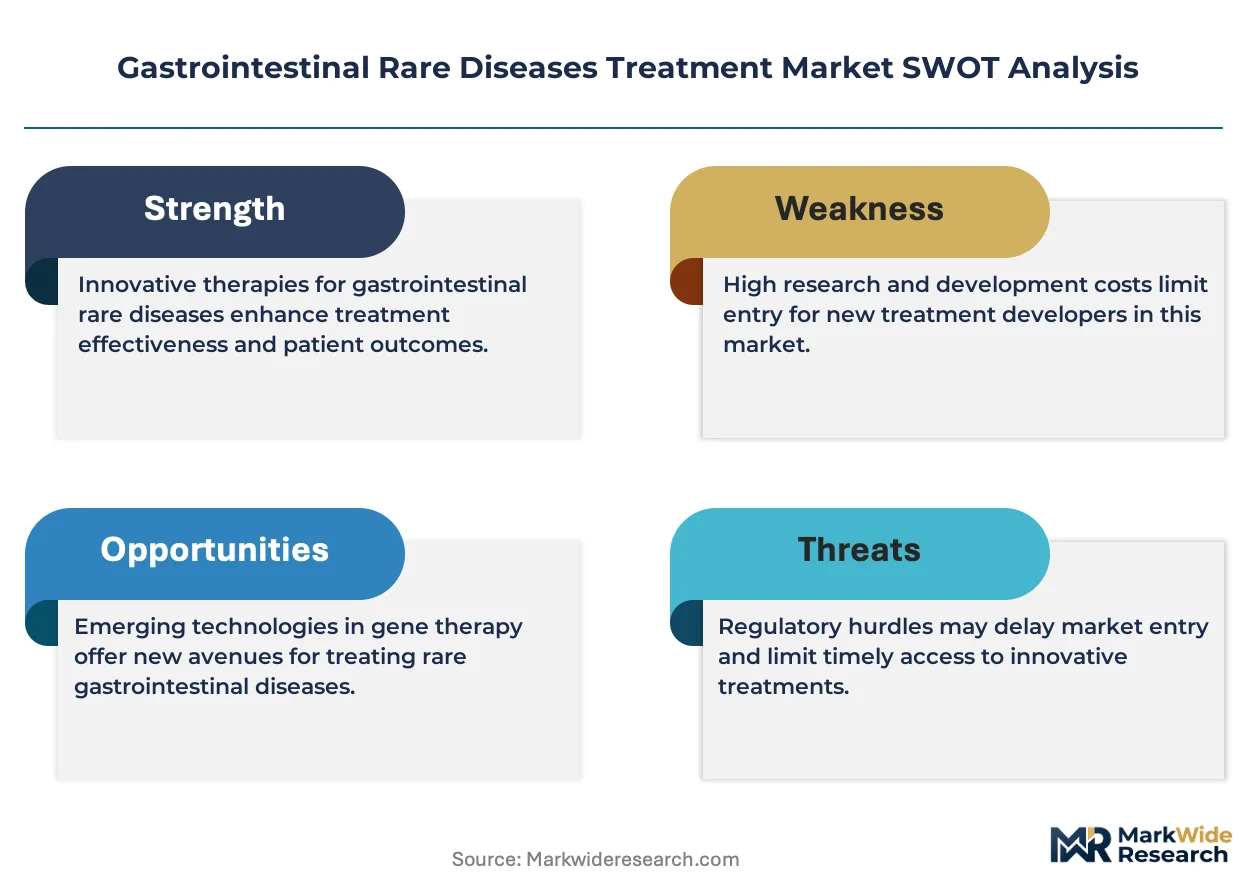
Specialty clinic consolidation into centers of excellence is concentrating purchasing power and reshaping how biologic therapies reach rare disease patients, with cold-chain distribution networks adapting to hub-and-spoke fulfillment models.
Growth Catalysts
- FDA Orphan Drug Act tax credits:Development cost offsets accelerate pipeline investment for ultra-low-prevalence gastrointestinal indications, reducing net R&D expenditure burdens.
- Gene therapy vector maturation:Adeno-associated virus delivery platforms now achieve durable transgene expression in hepatocytes, expanding addressable patient populations beyond enzyme replacement limitations.
- Germany's orphan drug reimbursement:The G-BA's early benefit assessment framework provides pricing certainty for innovative biologics entering the statutory health insurance system.
Market Restraints
- Plasmid DNA supply concentration:Contract manufacturing for gene therapy raw materials clusters among three North American suppliers, creating single-source vulnerability for viral vector production.
- Cold-chain infrastructure gaps:Parenteral biologics requiring minus-seventy-degree storage face distribution limitations in secondary and tertiary Japanese hospital networks.
- Substrate reduction therapy substitution:Oral small-molecule alternatives to intravenous enzyme replacement are capturing eligible lysosomal storage disorder patients, compressing addressable volumes.
Strategic Opportunities
- EMA PRIME designation pathway:Priority medicines status offers accelerated assessment and enhanced regulatory support for gene therapies targeting pediatric short bowel syndrome.
- Home infusion channel expansion:Specialty pharmacies are building nurse-administered parenteral capabilities, reducing hospital day-ward utilization for chronic maintenance regimens.
- Nutrition-biologic convergence:Combined enteral feeding and pharmacologic protocols create integrated care models for intestinal failure patients previously managed through separate service lines.
Industry Challenges
- Gene therapy durability uncertainty:Long-term expression data requirements from FDA and EMA extend post-approval commitment timelines, complicating revenue recognition and manufacturing scale planning.
- Biosimilar manufacturing qualification:Complex glycosylation patterns in reference biologics create analytical comparability hurdles, delaying abbreviated pathway submissions for orphan indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Rare Diseases Treatment Market |
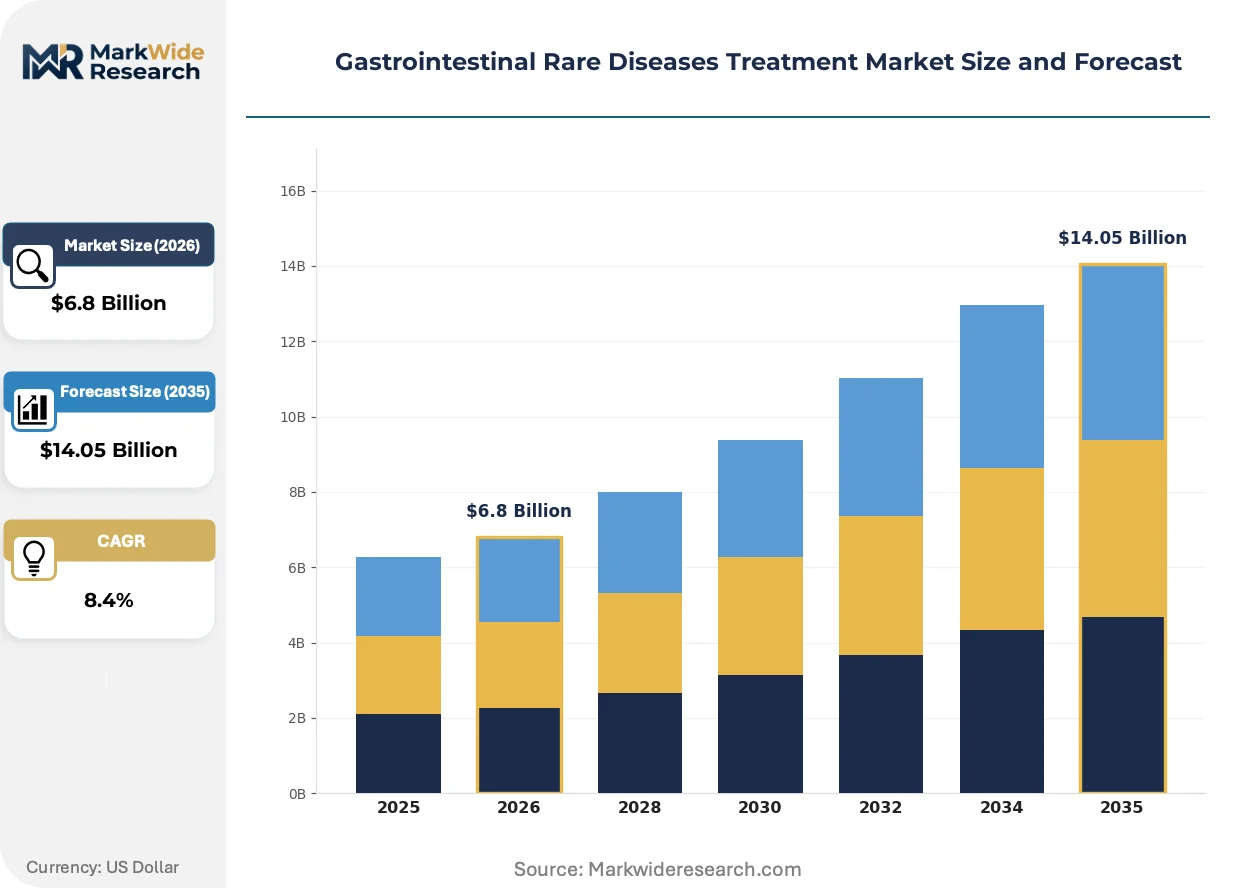
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Gene Therapies, Enzyme Replacement Therapy Area: Crohn's Disease, Ulcerative Colitis, Short Bowel Syndrome, Celiac Disease End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Administration Route: Oral, Subcutaneous, Intravenous, Intramuscular |
| Companies Covered | Takeda Pharmaceutical Company Limited, Nestlé Health Science, Mirum Pharmaceuticals, Inc., Recordati Rare Diseases Inc., Zealand Pharma A/S, Ironwood Pharmaceuticals, Inc., Novartis AG, Sanofi, Pfizer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Rare Diseases Treatment Market Shifts & Advancements
Next-generation delivery technologies and adaptive trial designs are compressing development timelines while reshaping how stakeholders capture value across the rare disease treatment continuum.
Gene editing platforms utilizing base and prime editing architectures is modularizing therapeutic development, allowing programmable correction of monogenic defects without double-strand break risks. Academic medical centers in the United States and Switzerland are establishing sponsored research agreements with vector manufacturers at accelerating pace. This modularization is collapsing the traditional distinction between discovery and clinical-stage assets, enabling platform licensing strategies that amortize development costs across multiple indications.
EMA's new Clinical Trials Regulation harmonized submission portals and safety reporting requirements across European member states, reducing administrative duplication for multi-country rare disease studies. Sponsors now face streamlined ethics review coordination but must adapt to enhanced transparency provisions around trial data sharing. Gene therapy developers targeting bile acid disorders are restructuring European site selection to prioritize countries with centralized pediatric hepatology networks.
Patient advocacy organizations are directly funding natural history studies and biomarker qualification work, compressing traditional investigator-initiated research timelines. These groups are aggregating longitudinal data through registries that pharmaceutical sponsors increasingly license as external control arms. The United States and United Kingdom host the most mature advocacy-funded infrastructure, with parent-led foundations in short bowel syndrome and familial chylomicronemia syndrome setting precedent for disease-specific data cooperatives.
Gastrointestinal Rare Diseases Treatment Market Segmentation
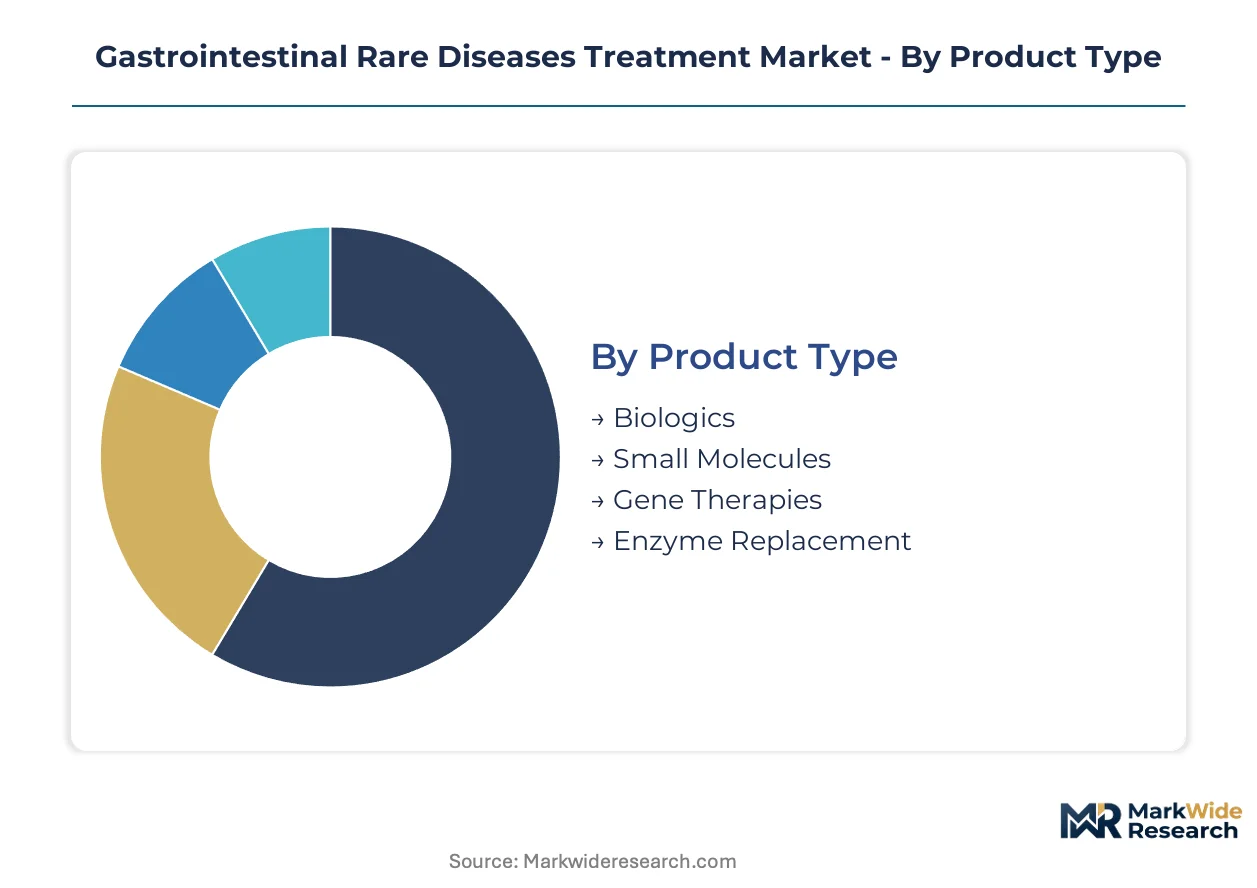
Segmentation in gastrointestinal rare diseases treatment reveals how supply chain configuration and patient access models dictate competitive positioning across modalities. Manufacturers must align portfolio investments with where purchasing power concentrates and where regulatory pathways offer clearest entry.
Product Type:
Supply concentration for advanced therapeutics clusters around viral vector manufacturing capacity and cold-chain distribution networks, with contract development organizations in the United States and Switzerland controlling critical production nodes.
- Biologics:Monoclonal antibodies and fusion proteins targeting inflammatory cytokines require mammalian cell culture production with complex glycosylation patterns. Demand concentrates in specialty clinics across Germany and Japan where reimbursement frameworks for orphan biologics are most established, though manufacturing bottlenecks at fill-finish contractors limit supply elasticity.
- Gene Therapies:Adeno-associated virus vectors deliver durable transgene expression for monogenic liver-gut disorders, with academic medical centers in the United States and Switzerland establishing sponsored research agreements with vector manufacturers at accelerating pace. Production scale-up for commercial batches remains constrained by plasmid DNA supply concentration among North American suppliers.
- Small Molecules:Oral agents targeting bile acid transport and intestinal inflammation offer simpler distribution logistics.
- Enzyme Replacement:Intravenous lysosomal enzyme formulations face substitution pressure from substrate reduction alternatives.
Today's leader: Biologics. Tomorrow's challenger: Gene Therapies.
Therapy Area:
Cost tier differentiation separates chronic maintenance indications from acute intervention segments, with lifetime therapy value calculations driving investment prioritization.
- Crohn's Disease:Chronic transmural inflammation of the gastrointestinal tract requires sequential biologic therapy with anti-TNF agents followed by interleukin inhibitors upon failure. Pediatric onset cases in the United States generate highest per-patient lifetime value due to extended treatment duration and early biologic initiation protocols.
- Short Bowel Syndrome:Intestinal failure following massive resection demands parenteral nutrition dependency reduction through GLP-2 analog therapy. German and Japanese centers of excellence concentrate eligible patients for teduglutide and emerging apraglutide access.
- Ulcerative Colitis:Mucosal inflammation limited to the colon permits oral and rectal delivery options with faster clinical trial endpoints than Crohn's.
- Celiac Disease:Gluten-free diet compliance remains primary management with limited pharmacologic penetration.
Short Bowel Syndrome commands premium pricing per treated patient. Ulcerative Colitis offers the largest addressable population base.
End User:
Customer type fragmentation is concentrating as hospital systems consolidate rare disease service lines, shifting procurement authority toward centralized pharmacy committees.
- Specialty Clinics:Dedicated centers of excellence for rare gastrointestinal conditions aggregate patient volumes sufficient to justify dedicated infusion suites and nutrition support teams. These sites in the United States and Germany negotiate directly with manufacturers for outcome-based contracts on high-cost biologics.
- Homecare Settings:Nurse-administered subcutaneous and intravenous therapies reduce hospital day-ward utilization for chronic maintenance regimens. Specialty pharmacies in Japan are building parenteral administration capabilities fastest, though cold-chain infrastructure gaps persist in secondary hospital networks.
- Hospitals:General academic centers retain emergency and surgical intervention roles.
- Research Institutions:Early-phase gene therapy trials depend on centralized pediatric hepatology networks.
Specialty clinics capture margin on chronic administration. Homecare channels are expanding most quickly for maintenance therapy.
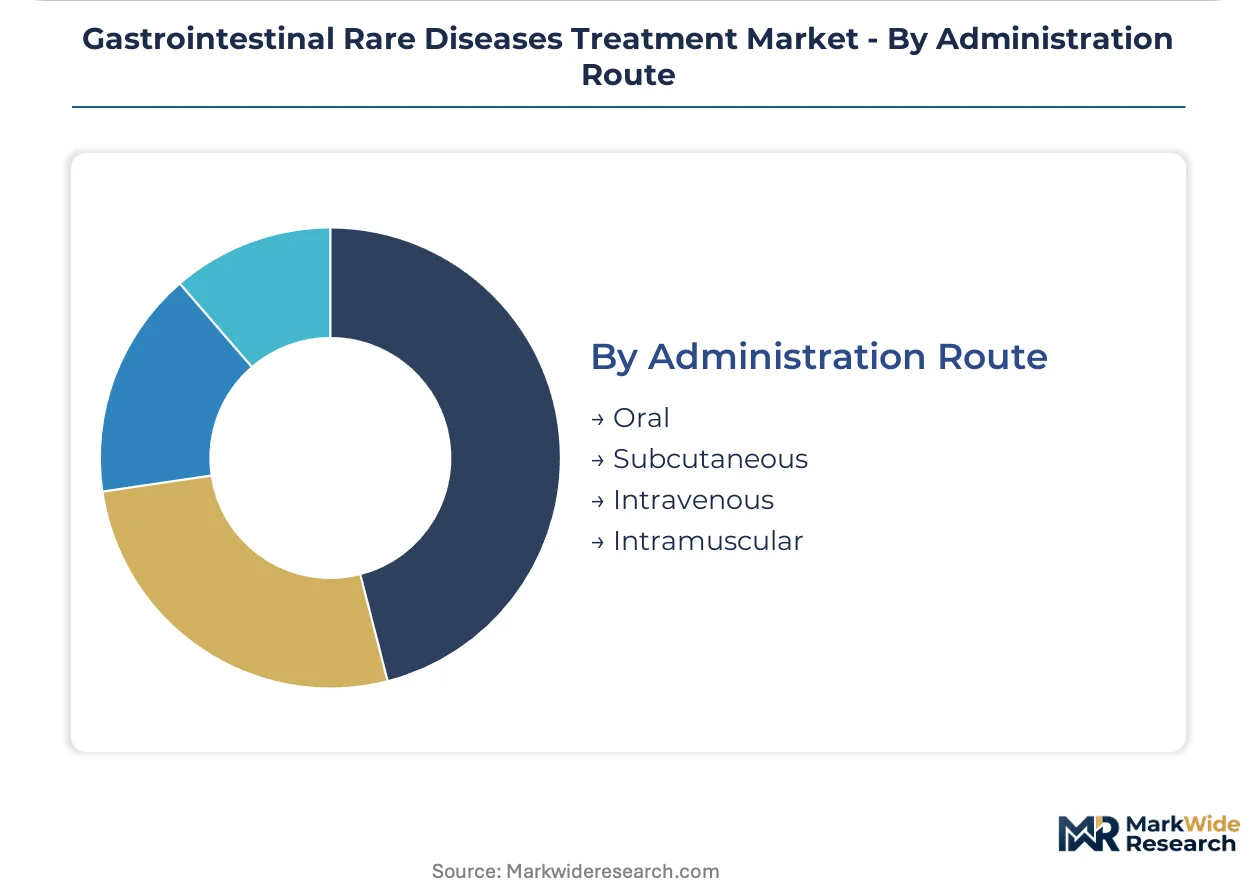
Administration Route:
Volume distribution across routes reflects the tension between patient convenience and pharmacokinetic requirements for large-molecule therapeutics.
- Intravenous:Infusion in controlled clinical settings enables immediate adverse event management for high-potency biologics and enzyme replacement therapies. United States hospital outpatient departments and German statutory health insurance day clinics process the highest infusion volumes for orphan gastrointestinal indications.
- Subcutaneous:Self-administered injection devices improve adherence for chronic maintenance and reduce healthcare system utilization. Japanese regulators have accelerated approval pathways for subcutaneous formulations that demonstrate non-inferior efficacy to intravenous equivalents.
- Oral:Small molecules and emerging peptide formulations offer simplest patient compliance.
- Intramuscular:Limited to specific depot formulations and vaccine adjuvants in rare disease contexts.
Intravenous dominates current biologic delivery. Subcutaneous formulations are gaining share fastest through patient preference and cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hepatology and gastroenterology talent clusters in the United States, Germany, Japan, Switzerland, and the United Kingdom anchor the geographic distribution of rare disease treatment development and patient access.
United States
FDA Orphan Drug Act tax credits and seven-year market exclusivity provisions concentrate biologic development investment in Massachusetts and California corridor clusters. Academic medical centers in Boston and San Francisco maintain sponsored research agreements with gene therapy vector manufacturers. The National Institutes of Health's Rare Diseases Clinical Research Network coordinates natural history studies that pharmaceutical sponsors license as external control arms.
Germany
The G-BA's early benefit assessment framework provides pricing certainty for innovative biologics entering statutory health insurance, with Heidelberg and Munich hosting Europe's densest pediatric hepatology networks. Germany's statutory health insurance day clinics process the highest infusion volumes for orphan gastrointestinal indications outside the United States. The country's orphan drug reimbursement pathway accelerates access decisions within three months of EMA approval.
Japan
PMDA's Sakigake designation system prioritizes review of innovative therapies for rare diseases with high unmet need, with Tokyo and Osaka medical centers concentrating eligible patient volumes. METI's healthcare technology assessment framework supports premium pricing for gene therapies demonstrating durable efficacy. Cold-chain infrastructure gaps persist in secondary hospital networks outside major metropolitan areas.
Switzerland
Swissmedic's expedited access pathway and proximity to European regulatory harmonization attract gene therapy developers establishing European headquarters in Basel and Zurich. The country's centralized pediatric hepatology networks support early-phase clinical trial recruitment. Swiss contract development organizations control critical viral vector manufacturing nodes for commercial-scale gene therapy production.
United Kingdom
NHS England's specialized commissioning framework concentrates rare disease treatment in London, Birmingham, and Manchester centers of excellence. The MHRA's innovative licensing pathway accelerates market access for therapies addressing ultra-rare gastrointestinal conditions. Patient advocacy organizations in the United Kingdom directly fund biomarker qualification work that compresses traditional research timelines.
Gastrointestinal Rare Diseases Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates manufacturing capability among contract development organizations and captive biologics production networks. Three strategic archetypes dominate: integrated pharmaceutical conglomerates with gastroenterology verticals, nutrition-therapy hybrid specialists, and gene therapy platform developers. Capacity expansion at fill-finish contractors and strategic partnerships for viral vector supply represent the dominant competitive moves reshaping supply security.
Among the diversified pharmaceutical conglomerates, Takeda Pharmaceutical Company Limited and Novartis AG occupy positions anchored by biologics manufacturing scale and rare disease portfolio breadth. Nestlé Health Science exemplifies the nutrition-therapy hybrid archetype, while Mirum Pharmaceuticals, Inc. represents focused specialization in bile acid modulation. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning across the treatment continuum.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Nestlé Health Science |
| Mirum Pharmaceuticals, Inc. |
| Recordati Rare Diseases Inc. |
| Zealand Pharma A/S |
| Ironwood Pharmaceuticals, Inc. |
| Novartis AG |
| Sanofi |
| Pfizer, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty pharmacy networks now control the majority of parenteral biologic distribution in the United States, compressing margins on cold-chain logistics while extracting volume rebates that reshape manufacturer net pricing. This ownership concentration creates asymmetric bargaining power against orphan drug developers, forcing pricing discipline through formulary exclusion threats and preferred product tiering.
Pricing Analysis
The bundled-vs-unbundled service split separates infusion administration fees from drug acquisition costs, with United States specialty clinics negotiating outcome-based contracts that wrap nursing services, adverse event monitoring, and patient adherence programs into per-patient monthly rates. Price differentiation hinges on orphan exclusivity status and cold-chain certification tier, with FDA breakthrough-designated biologics commanding premium positioning against standard-of-care alternatives. Pricing pressure stems from biosimilar preparation for adalimumab and infliximab analogs, eroding reference product margins in Crohn's disease maintenance therapy. Hospital procurement committees exhibit highest price sensitivity for chronic administration regimens, while centers of excellence with dedicated rare disease funding demonstrate lowest sensitivity due to pass-through reimbursement mechanisms.
Supply Chain Analysis
Hub-and-spoke distribution channels consolidate patient volumes through regional specialty pharmacy hubs that feed satellite infusion centers, with United States, Switzerland, and Germany hosting the densest cold-chain node networks. Plasmid DNA supply draws from concentrated North American contract manufacturers, creating single-source vulnerability for viral vector production scale-up. Fill-finish capacity at mammalian cell culture contractors represents the dominant bottleneck, with Swiss and German CDMOs controlling critical biologics finishing nodes. Tariff exposure on Chinese-sourced single-use bioreactor bags intensifies cost pressure across gene therapy manufacturing campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in gastrointestinal rare diseases treatment rests on gene therapy manufacturing cost curves flattening as plasmid DNA supply diversifies, enabling premium-tier pricing for durable one-time interventions against chronic maintenance comparators.
For Market Incumbents: Cement vector manufacturing partnerships through equity stakes or offtake guarantees, locking plasmid DNA supply ahead of competitor pipeline maturation. Expand captive fill-finish capacity in Switzerland or Germany to insulate against CDMO queue delays that threaten launch timelines for pediatric short bowel syndrome gene therapies. Substrate reduction therapy substitution in lysosomal storage disorders demands defensive indication expansion into combination regimens with enzyme replacement. For New Entrants and Emerging Players: Telehealth-enabled patient identification platforms offer the lowest-friction entry path for rare disease patient finding, bypassing entrenched specialty clinic relationships that incumbent field forces have cultivated over decades. Target home infusion channel expansion in Japan, where regulatory acceleration for subcutaneous formulations creates first-mover advantage against intravenous incumbents. Partner with parent-led advocacy foundations for natural history data licensing, compressing external control arm development timelines and regulatory submission preparation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap gene therapy platform developers with pediatric hepatology network access but pre-revenue pipelines, offering acquisition entry before clinical proof-of-concept readouts. The five-to-ten-year viability window favors vector manufacturing technology over single-asset biotechs, given platform amortization across multiple rare disease indications. Watch FDA durability data requirements for adeno-associated virus liver expression as the inflection signal for manufacturing scale commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Plasmid DNA Supply Diversification | Reduces single-source concentration risk for North American gene therapy vector manufacturers. |
| EMA PRIME Designation Pursuit | Accelerates regulatory assessment timelines for pediatric short bowel syndrome gene therapy candidates. |
| Home Infusion Channel Buildout | Captures Japanese patient preference for subcutaneous administration outside hospital day wards. |
| Advocacy Foundation Data Licensing | Compresses external control arm timelines through registry access from United Kingdom parent-led foundations. |
| Specialty Clinic Outcome Contracts | Locks United States and German centers of excellence into multi-year biologic purchasing commitments. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded the qualitative assessment, cross-referenced against FDA orphan drug designations, EMA submissions, ClinicalTrials.gov records, and statutory health insurance formulary databases. Bottom-up patient volume estimates by indication and top-down market sizing by therapeutic modality were reconciled through iterative triangulation.
Bottom-up modeling anchored volume projections to diagnosed prevalent cases, treatment penetration rates, and dosing intensity across the analysis window, while top-down approaches validated aggregate spending patterns against reimbursement claims data. Segmentation dimensions included product type, therapy area, end user, and administration route, with CAGRs derived from pricing trajectory assumptions and patient population evolution. Forecast inputs incorporated FDA exclusivity expiration timelines and EMA early benefit assessment outcomes.
The model assumes a particular technology adoption path; alternative pathways for base and prime editing platforms would alter the outlook if modular correction architectures displace viral vector delivery. Forecasts reflect assumptions around gene therapy durability and biosimilar entry timing that warrant periodic reassessment. Regulatory shifts in Germany's G-BA assessment framework or Japan's METI pricing methodology represent specific revision triggers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Batten Disease Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Asia-Pacific Down Syndrome Market