
 Rail Brake Frame Market | 2026-2036
Rail Brake Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Brake Frame Market Analysis
Chinese steel foundries is pivoting toward higher-grade alloy formulations for brake frame castings. Wabtec Corporation leverages its integrated braking systems portfolio to dominate North American freight retrofits. Knorr-Bremse AG sustains European market presence through specialized pneumatic brake technologies. CRRC Corporation Limited anchors Asia-Pacific supply chains with captive foundry capacity and domestic rail program alignment.
A rail brake frame is a structural mounting component that houses and positions brake actuation hardware against the wheel or axle assembly, typically cast from nodular iron or forged alloy steel to withstand cyclic thermal and mechanical loads exceeding 100 kN during emergency braking events. Disc brake configurations lead product type demand due to higher thermal capacity requirements in high-speed passenger applications, while electromagnetic brake technology is displacing legacy pneumatic systems in urban metro fleets where regenerative energy recovery is prioritized. Steel material grades still occupy the majority of unit volume, though composite-reinforced frames are penetrating light-rail segments where unsprung mass reduction directly improves track adhesion dynamics.
The Federal Railroad Administration mandates brake frame inspection intervals and material traceability under 49 CFR Part 232, while the European Union Agency for Railways enforces EN 14535-1 structural integrity standards for cast brake components. China's National Railway Administration implements GB/T criteria that align domestic foundries with CRRC's technical specifications, creating divergent certification pathways for exporters. Stakeholders must monitor how regional decarbonization mandates reshape material specifications and foundry energy costs across their supplier footprints.
Market Dynamics
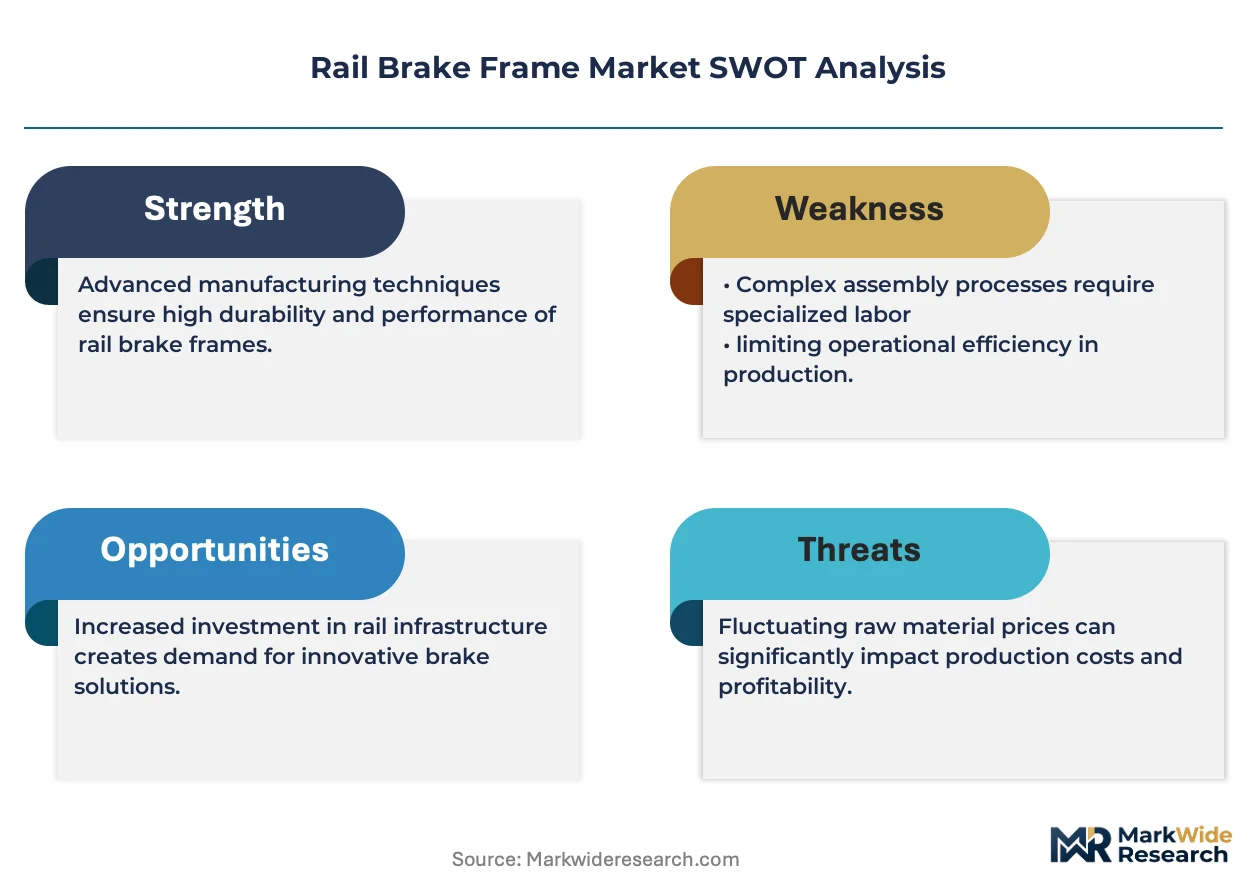
Freight operators face simultaneous pressure from Federal Railroad Administration brake safety mandates and thermal load thresholds from heavier axle configurations, forcing foundries to recertify alloy grades faster than traditional casting cycles permit.
Growth Catalysts
- 49 CFR Part 232 Inspection Mandates:The Federal Railroad Administration's tightened brake frame inspection intervals are accelerating replacement demand across North American freight fleets.
- High-Speed Rail Expansion:Disc brake configurations are capturing volume in passenger corridors where thermal capacity requirements exceed legacy pneumatic system limits.
- CRRC Domestic Program Alignment:China's National Railway Administration GB/T standards are synchronizing foundry output with state rail procurement schedules.
Market Restraints
- Alloy Steel Input Volatility:Nodular iron and forged alloy steel pricing swings compress foundry margins during contract renegotiation windows.
- Supplier Concentration Risk:Captive foundry capacity at integrated rail OEMs limits independent component supplier market access.
- Electromagnetic Substitution Threat:Regenerative braking systems in urban metro fleets are reducing mechanical brake frame attachment points per axle.
Strategic Opportunities
- Composite-Reinforced Penetration:Light-rail operators in Germany are testing unsprung mass reduction frames that improve track adhesion dynamics.
- EU Green Deal Foundry Incentives:Decarbonization mandates are subsidizing electric arc furnace upgrades at European brake component casters.
- Retrofit Channel Expansion:Third-party maintenance depots in India are building brake frame remanufacturing capabilities outside OEM service networks.
Industry Challenges
- EN 14535-1 Certification Timelines:European cast brake component structural integrity testing creates 18-24 month approval bottlenecks for new alloy formulations.
- Legacy Pneumatic Integration:Hybrid brake architectures require frame designs accommodating both electromagnetic actuation and fallback pneumatic systems.
- Metallurgical Talent Scarcity:Foundry engineering programs are producing fewer specialists in cyclic thermal load simulation for brake applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Brake Frame Market |
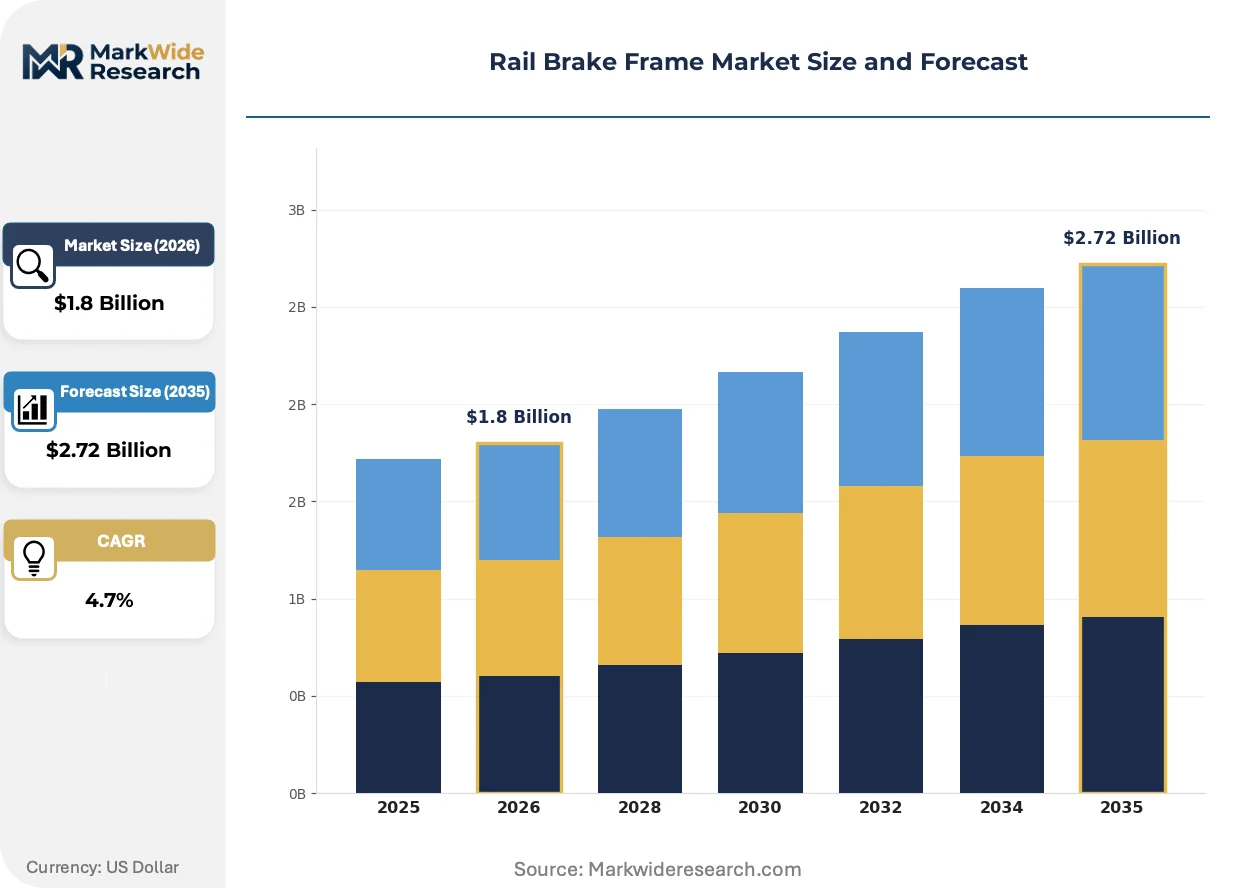
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Electromagnetic Brakes, Air Brakes Technology: Hydraulic, Pneumatic, Mechanical, Electronic End User: Freight Operators, Passenger Operators, Maintenance Providers, Railways Material: Steel, Alloy, Composite, Plastic |
| Companies Covered | Wabtec Corporation, Knorr-Bremse AG, CRRC Corporation Limited, Alstom, Miner Enterprises Inc., L.B. Foster, Caterpillar, AKEBONO BRAKE INDUSTRY CO., LTD., Fundiciones Del Estanda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Brake Frame Market Emerging Trajectories
Digital foundry technologies and material science advances are compressing the traditional brake frame development cycle while regional regulatory divergence forces parallel certification tracks.
Additive manufacturing is decentralizing prototype casting workflows for brake frame geometries. Tier-1 suppliers in Germany and Japan are adopting sand-printing hybrid methods to validate nodular iron microstructures before full production tooling commitment. This technology is decentralizing design authority from captive OEM engineering centers to specialized foundry engineering houses.
REACH substance restrictions on heavy-metal alloying elements are forcing reformulation of traditional brake frame cast irons. The European Chemicals Agency's candidate list updates are accelerating nickel-free alloy development programs. High-speed passenger operators in France and Spain are prioritizing suppliers with pre-certified alternative metallurgies to avoid fleet approval delays.
Freight operators are consolidating brake frame procurement under lifecycle cost frameworks rather than unit-price tenders. Class I railroads in the United States are bundling frame replacement with integrated braking system overhaul contracts. This pattern concentrates supplier selection authority at centralized engineering procurement functions rather than distributed maintenance divisions.
Rail Brake Frame Market Segmentation
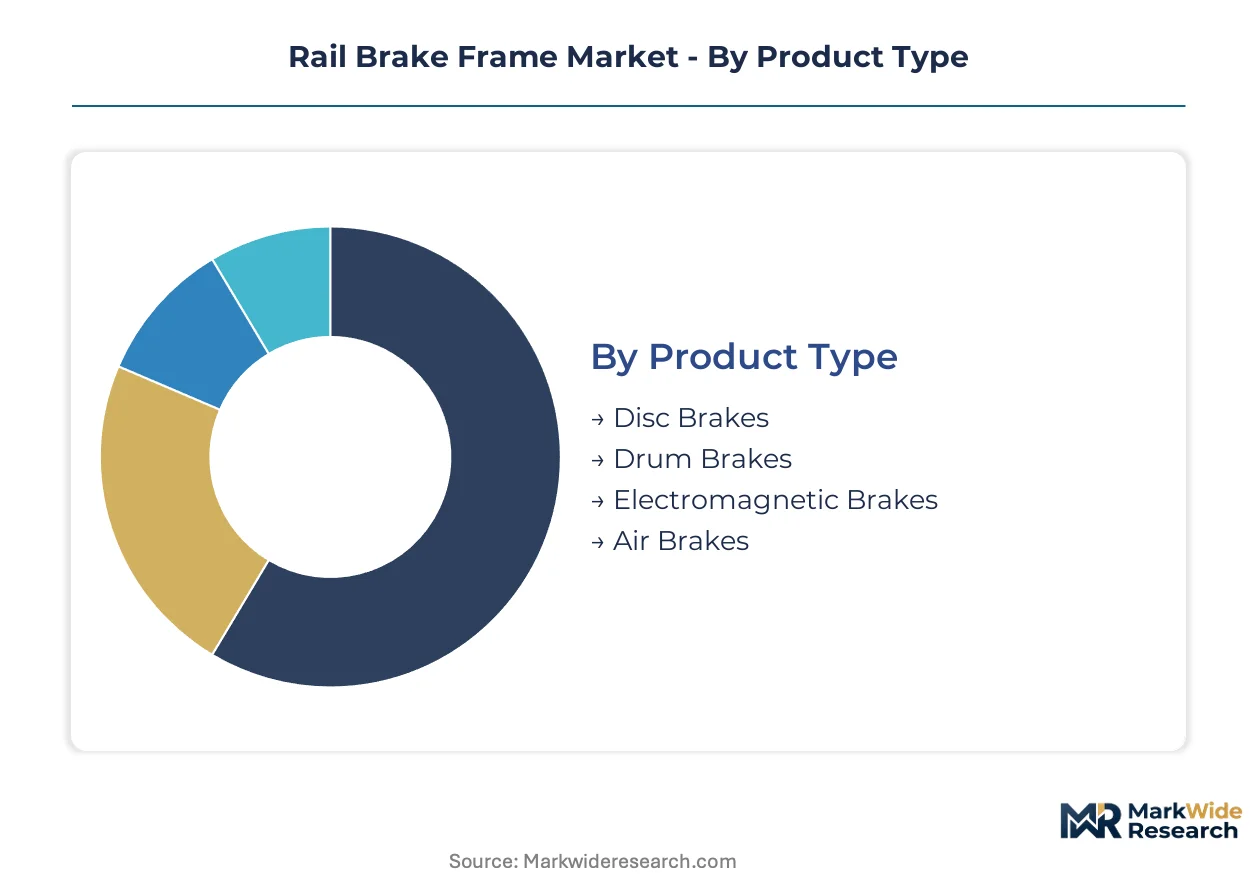
Rail brake frame procurement diverges sharply across operational profiles. Certification burdens, thermal load specifications, and fleet modernization cycles create distinct demand pockets that suppliers must navigate separately.
Product Type:
Disc brake frames carry EN 14535-1 and 49 CFR Part 232 dual-certification requirements for high-speed corridors. Drum brake configurations face lighter regulatory scrutiny but heavier wear-cycle documentation. Electromagnetic variants trigger electromagnetic compatibility testing under EU Agency for Railways protocols. Air brake systems maintain legacy pneumatic certification pathways established decades earlier.
- Disc Brakes:Cast nodular iron frames with enhanced thermal mass withstand repeated emergency braking cycles exceeding 100 kN. Demand concentrates in France's TGV network and Spain's AVE corridors where high-speed mandates dictate disc configurations.
- Drum Brakes:Forged alloy steel drums dominate North American freight retrofits under Federal Railroad Administration inspection tightening. Class I railroads bundle drum frame replacement with full brake system overhauls.
- Electromagnetic Brakes:Frame designs integrate coil mounting geometry and thermal shielding for metro regenerative systems.
- Air Brakes:Legacy pneumatic mounting interfaces persist in emerging-market freight fleets with slower electrification timelines.
Leading the category by volume: Disc Brakes. Expanding most quickly: Electromagnetic Brakes.
Technology:
Technology selection determines foundry process complexity and alloy grade specifications. Hydraulic systems command premium material traceability. Pneumatic architectures dominate installed base replacement.
- Hydraulic:High-pressure manifold integration demands nodular iron grades with guaranteed tensile properties. German foundries around Berlin specialize in hydraulic frame castings for export markets.
- Pneumatic:Compressed air actuator mounting dominates freight operator specifications across North America and India.
- Mechanical:Direct linkage frames persist in heritage railway preservation segments.
- Electronic:Sensor-integrated frames with embedded strain monitoring require electromagnetic compatibility validation.
Dominating replacement demand: Pneumatic. Gaining share fastest: Electronic.
End User:
End-user procurement authority shapes contract structure and supplier relationship intensity. Integrated operators consolidate engineering decisions. Third-party maintenance depots fragment purchasing.
- Freight Operators:Class I railroads in the United States centralize brake frame procurement under lifecycle cost frameworks rather than unit-price tenders.
- Passenger Operators:High-speed rail authorities in France and Spain prioritize pre-certified metallurgies to avoid fleet approval delays.
- Maintenance Providers:Indian third-party depots are building remanufacturing capabilities outside OEM service networks.
- Railways:State-owned operators in China align procurement with CRRC captive foundry output schedules.
Concentrating procurement authority: Freight Operators. Fragmenting fastest: Maintenance Providers.
Material:
Material selection reflects the tension between thermal performance, unsprung mass reduction, and regulatory substance restrictions. Steel grades retain volume leadership. Composites penetrate niche applications.
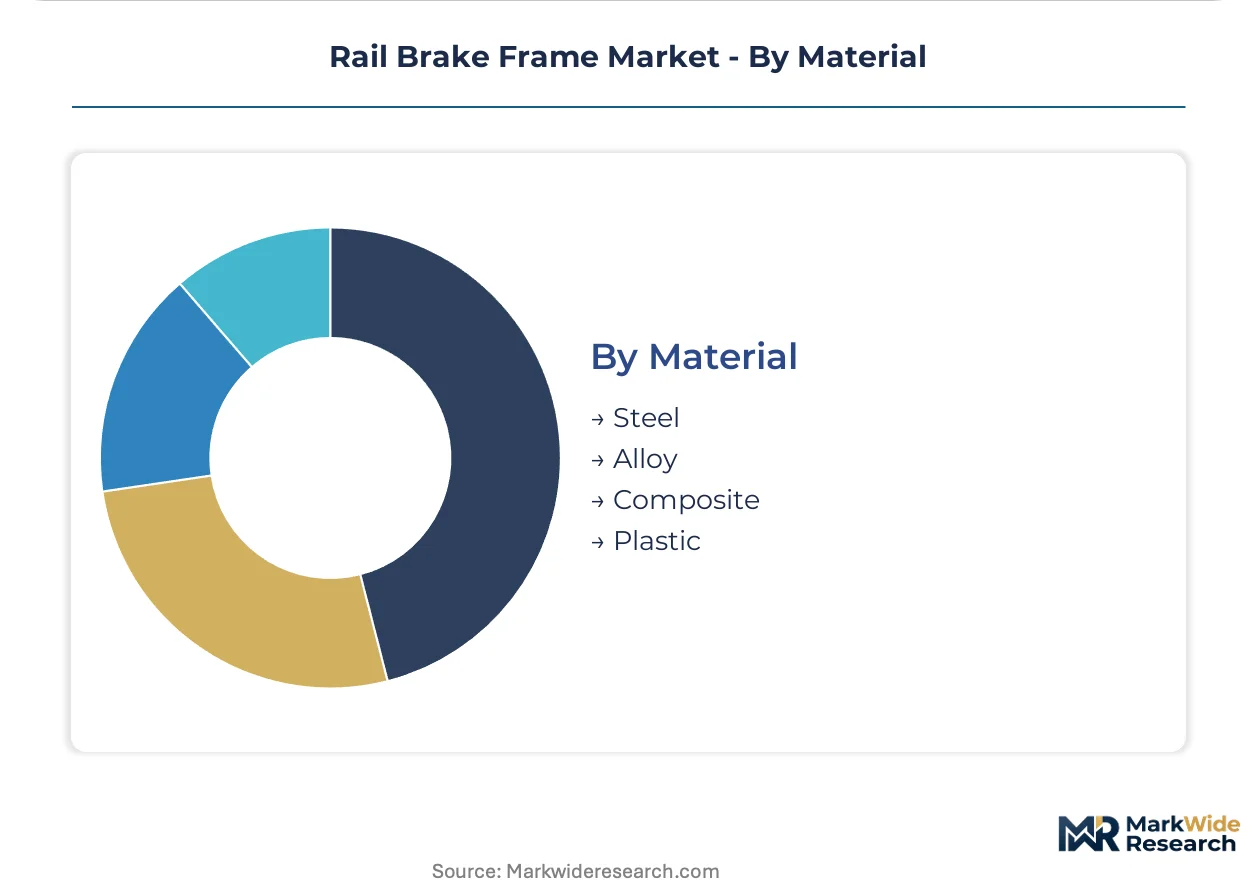
- Steel:Forged and cast carbon steel occupies the majority of unit volume across freight and legacy passenger fleets.
- Alloy:Nickel-free formulations are accelerating under European Chemicals Agency REACH candidate list pressure.
- Composite:Fiber-reinforced frames reduce unsprung mass in German light-rail test programs.
- Plastic:Polymer-based brackets serve non-structural auxiliary mounting in low-load applications.
Holding volume leadership: Steel. Climbing the fastest: Alloy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nodular iron feedstock from Hebei Province foundries anchors Chinese brake frame casting capacity. German steel mills around the Ruhr supply alloy grades for European high-speed rail certification. Brazilian iron ore shipments to Asian ports sustain foundry input costs across Pacific supply chains.
United States
Class I railroads centralize brake frame procurement under lifecycle cost frameworks rather than unit-price tenders. The Federal Railroad Administration's 49 CFR Part 232 mandates accelerate replacement demand across aging freight fleets. Pittsburgh-based engineering centers coordinate specification alignment with Midwest foundry clusters.
Germany
High-speed passenger operators prioritize pre-certified nickel-free metallurgies to avoid fleet approval delays. The EU Green Deal subsidizes electric arc furnace upgrades at component casters in Berlin and Hamburg. Foundries around Dortmund specialize in hydraulic frame castings for export corridors.
China
State-owned rail operators align procurement with captive foundry output schedules from CRRC's supply network. The National Railway Administration's GB/T standards synchronize domestic technical specifications with manufacturing capacity. Yangtze River Delta foundries pivot toward higher-grade alloy formulations for brake frame castings.
India
Third-party maintenance depots build brake frame remanufacturing capabilities outside OEM service networks. The Bureau of Indian Standards enforces structural integrity protocols for cast brake components entering state rail programs. Gujarat-based engineering workshops expand retrofit channel infrastructure for aging freight wagons.
Japan
Metro operators prioritize electromagnetic brake integration for regenerative energy recovery in dense urban corridors. METI standards govern electromagnetic compatibility validation for sensor-integrated frame designs. Osaka-Kobe manufacturing belt foundries adopt sand-printing hybrid methods for prototype validation.
Rail Brake Frame Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue composite-reinforced and electromagnetic niches. The supplier base concentrates around integrated rail OEMs with captive foundry capacity, limiting independent component access. Three archetypes dominate: diversified braking system integrators, specialized pneumatic technology houses, and state-aligned manufacturing conglomerates. Capacity expansion and strategic partnerships represent the primary competitive vectors as certification timelines lengthen.
Among diversified braking system integrators, Wabtec Corporation and Knorr-Bremse AG exemplify archetype positioning across North American and European freight corridors respectively. CRRC Corporation Limited occupies a position within the state-aligned tier, anchoring Asia-Pacific supply chain configuration through domestic program alignment. These three entities represent distinct geographic and structural approaches to brake frame market participation.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Knorr-Bremse AG |
| CRRC Corporation Limited |
| Alstom |
| Miner Enterprises Inc. |
| L.B. Foster |
| Caterpillar |
| AKEBONO BRAKE INDUSTRY CO., LTD. |
| Fundiciones Del Estanda |
| Others |
Supply Flow & Price Mechanics
Class I railroad lifecycle cost procurement frameworks are compressing foundry margins by bundling brake frame replacement with full system overhaul contracts, forcing suppliers to absorb certification and warranty costs into unit economics rather than pricing them separately.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering 10-year structural integrity guarantees from standard-tier competitors with limited coverage periods. Three-tier pricing structure across premium, standard, and economy levels reflects EN 14535-1 certification status, alloy traceability documentation, and foundry energy source disclosure under EU Green Deal criteria. Cost compression in the economy tier is intensifying because Chinese state-rail procurement schedules favor captive CRRC foundry output over independent exporters. Freight operators in North America exhibit lowest price sensitivity due to Federal Railroad Administration mandate-driven replacement urgency, while Indian third-party maintenance depots remain most price-sensitive as they build remanufacturing capabilities outside OEM networks.
Supply Chain Analysis
Regional distribution centers in Dortmund, Pittsburgh, and Yangtze River Delta cities coordinate hub-and-spoke patterns for certified brake frame castings. Supply concentrates in China, Germany, and the United States, with Hebei Province nodular iron feedstock and Ruhr Valley alloy grades anchoring upstream material flows. Foundry output draws from Brazilian iron ore shipments, nickel-free alloy formulations under REACH pressure, and composite fiber prepregs for light-rail test programs. Single-source vulnerability persists around electromagnetic brake frame coil integration, where Japanese METI-certified sensor designs face limited secondary sourcing. Distribution runs through OEM captive networks for new build programs and third-party depot channels for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable foundries as EN 14535-1 and 49 CFR Part 232 timelines stretch beyond 18 months, eliminating engineering-light competitors unable to sustain parallel approval tracks.
For Market Incumbents: Anchor market position through backward integration into nodular iron feedstock from Hebei Province or Ruhr Valley alloy suppliers, securing material traceability documentation that accelerates Federal Railroad Administration approval cycles. Deepen captive foundry capacity in Berlin-Hamburg clusters to capture EU Green Deal electric arc furnace subsidies while electromagnetic brake substitution threatens pneumatic frame volumes in urban metro segments. For New Entrants and Emerging Players: Launch via remanufacturing partnerships with Indian third-party maintenance depots in Gujarat, exploiting the fragmentation between OEM service networks and state rail procurement. Target composite-reinforced frame supply to German light-rail operators testing unsprung mass reduction, using sand-printing hybrid methods to validate geometries before full production tooling commitment. For Investors and Strategic Acquirers: The window for entry favors specialized foundry engineering houses with pre-certified nickel-free metallurgies and electromagnetic compatibility validation capabilities. Long-term viability rests on positioning ahead of REACH substance restriction expansions and dual-certification demand for high-speed corridors. Watch for electromagnetic brake adoption inflection in Japan's Osaka-Kobe manufacturing belt as the signal for mechanical frame displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Secures material traceability documentation required under 49 CFR Part 232 and EN 14535-1 certification pathways. |
| Electric Arc Furnace Upgrade | Captures EU Green Deal subsidies while positioning foundries for decarbonization-mandated procurement preferences in Germany. |
| Remanufacturing Capability Buildout | Opens retrofit channel access outside OEM captive networks, particularly in India's third-party depot expansion. |
| Electromagnetic Compatibility Validation | Prepares frame designs for METI-governed sensor integration as Japanese metro operators prioritize regenerative braking. |
| Sand-Printing Hybrid Method Adoption | Decentralizes prototype validation from OEM engineering centers to specialized foundry houses in Germany and Japan. |
Methodological Framework
Multi-period observation of foundry capacity utilization, certification timeline bottlenecks, and procurement bundling patterns anchored the trend analysis, supplemented by interviews with brake system engineering directors, freight operator procurement leads, foundry operations managers, and regulatory compliance officers at Federal Railroad Administration and EU Agency for Railways. Secondary validation drew from Bureau of Indian Standards filings, Chinese National Railway Administration GB/T updates, METI electromagnetic compatibility protocols, customs data on Brazilian iron ore shipments, and SEC disclosures from rail OEM suppliers. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to ensure consistency.
Segment-weighting across product type, technology architecture, end-user procurement authority, and material grade specifications structured the analytical framework across the projection horizon. Disc brake, drum brake, electromagnetic, and air brake configurations were modeled separately against freight operator lifecycle frameworks and passenger operator thermal capacity requirements. CAGRs were derived from foundry output alignment with state rail procurement schedules and alloy formulation recertification velocity. Industry-specific forecast inputs included Federal Railroad Administration inspection interval tightening schedules and REACH candidate list substance restriction timelines.
Alloy steel input volatility, electromagnetic substitution acceleration, and certification timeline extension beyond traditional casting cycles are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Doors Market
Railway
Freight Cars Market
Railway
Global Hyperloop Train Market
Railway
Railway System Market
Railway
Locomotive Maintenance Market
Railway
Railway Pantograph Market
Railway
Railway Bearing Market
Railway
Rolling Stocks Market
Railway
Rail Glazing Market
Railway
Railway Buffer Stops Market
Railway
Train Bogie Market
Railway
Railway Overhead Catenary System Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Global Smart Locomotive Market
Railway
Solar Train Market
Railway
India Rail Freight Transport Market