
 Drum Brake Market | 2026-2036
Drum Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Brake Market Foresight
Aftermarket distribution for drum brake components is tilting toward consolidated purchasing agreements with national fleet operators. Bosch leverages its global service network to sustain aftermarket penetration across multiple continents. Akebono Brake Industry anchors Japanese OEM supply relationships with specialized friction material expertise. ZF Friedrichshafen competes through integrated chassis systems that bundle braking with suspension modules.
A drum brake is a friction-based braking mechanism employing curved shoes that expand outward against a rotating cylindrical drum, typically manufactured from cast iron with specified thermal capacity ratings and SAE J661 friction performance certification. Its primary purpose is to decelerate or hold stationary wheeled equipment through mechanical, hydraulic, or pneumatic actuation. Dual action configurations lead in commercial vehicle applications where self-energizing geometry delivers superior stopping torque for loaded trucks. Aftermarket providers represent the fastest-growing end user channel as fleet operators extend vehicle replacement cycles and outsource maintenance to specialized service networks.
The US NHTSA Federal Motor Vehicle Safety Standards govern brake performance and labeling requirements for vehicles operating on American roads. India's BIS mandates component-level testing and certification for brake assemblies sold in domestic commerce. The EU's REACH regulation constrains friction material formulations by restricting certain heavy metal additives used in brake lining composites. Stakeholders must monitor evolving material compliance thresholds and fleet electrification timelines that could reshape brake system specifications across commercial vehicle categories.
Market Dynamics
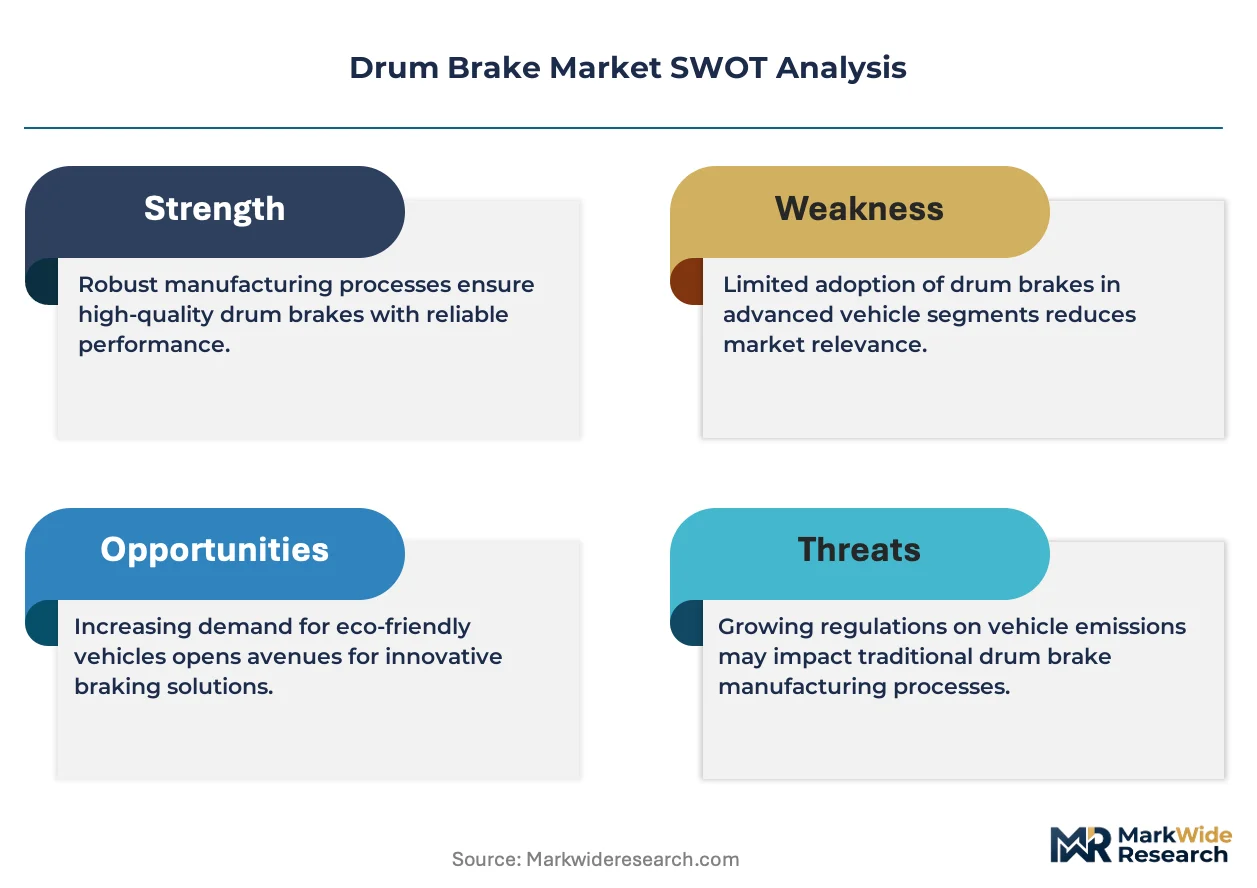
Fleet electrification timelines and commercial vehicle age-extension policies are compressing replacement cycles and rerouting aftermarket demand toward specialized service networks in high-growth economies.
Growth Catalysts
- India's BIS certification mandate:Tighter component-level testing requirements for brake assemblies sold in domestic commerce elevate product standards and filter substandard imports from neighboring manufacturing zones.
- Commercial vehicle fleet aging:Extended replacement cycles across Brazilian and Southeast Asian trucking operations expand the serviceable installed base for aftermarket drum brake providers.
- Cast iron thermal capacity specifications:SAE J661 friction performance certification requirements drive material upgrades that improve stopping torque reliability under heavy-load conditions.
Market Restraints
- Friction material input cost volatility:Copper and heavy metal additive prices fluctuate with mining supply disruptions, compressing margin structures for lining composite manufacturers.
- Supply concentration in East Asian foundries:Cast iron drum casting capacity clusters in specific industrial zones, creating geographic vulnerability to energy rationing or logistics bottlenecks.
- Disc brake substitution in light commercial segments:Hydraulic disc systems capture share in sub-3.5 ton vehicles where heat dissipation requirements are less severe.
Strategic Opportunities
- Brazilian aftermarket channel consolidation:Aging truck populations and outsourced fleet maintenance create white space for national service network partnerships.
- EU REACH regulatory tailwind:Restrictions on heavy metal additives in friction materials favor suppliers with pre-certified low-copper formulations ready for compliance deadlines.
- Telematics-brake integration:Convergence of pneumatic actuation systems with fleet monitoring platforms enables predictive maintenance service models.
Industry Challenges
- SAE J661 certification timeline compression:Extended laboratory testing protocols delay product launches for new friction material formulations.
- Legacy pneumatic-hydraulic system interoperability:Mixed fleet configurations require dual-skill technicians capable of servicing mechanical, hydraulic, and air-brake architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Brake Market |
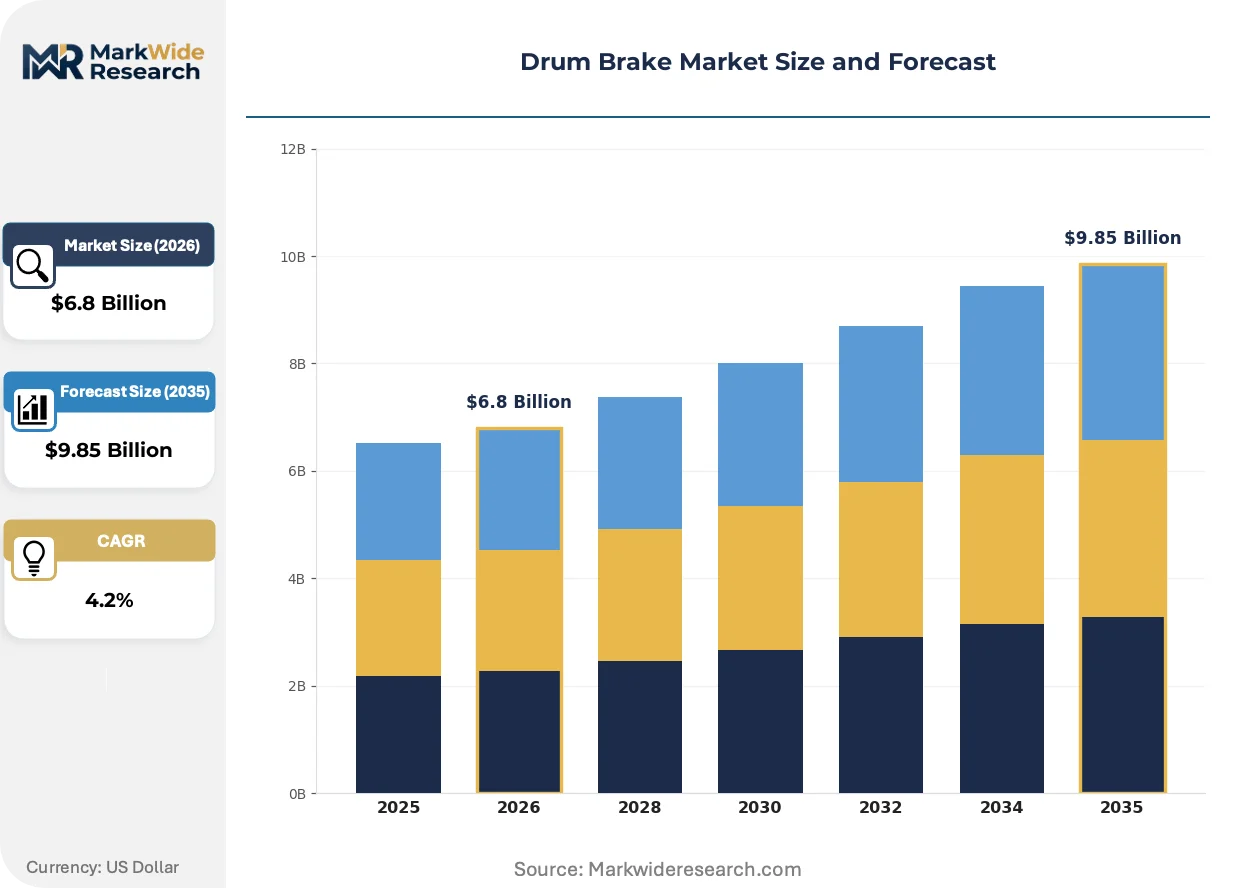
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Action, Dual Action, Air Operated, Hydraulic Application: Passenger Vehicles, Commercial Vehicles, Heavy Equipment, Motorcycles Material: Cast Iron, Aluminum, Composite, Steel End User: OEMs, Aftermarket Providers, Repair Shops, Fleet Management |
| Companies Covered | Bosch, Akebono Brake Industry, Brembo, ZF Friedrichshafen, Nissin Kogyo, Continental, ADVICS, Knorr-Bremse, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Brake Market Shifts & Advancements
Digital simulation tools and connected fleet infrastructure are virtualizing traditional brake testing and maintenance workflows, compressing development cycles and enabling remote diagnostics.
Finite element analysis software is virtualizing thermal stress modeling for cast iron drum designs, eliminating multiple physical prototype iterations. Tier-1 suppliers and OEM engineering teams deploy these tools to accelerate SAE J661 certification timelines. The technology is virtualizing traditional foundry-pattern development, reducing time-to-market for new thermal capacity ratings.
The EU's REACH regulation constrains copper and antimony content in friction lining composites, forcing reformulation investments across European supply chains. Brake material manufacturers must validate alternative fiber matrices and ceramic additives to maintain stopping performance. Commercial vehicle categories face the steepest compliance costs due to higher duty-cycle friction demands.
Fleet operators are consolidating maintenance spend through direct purchasing agreements with national parts distributors, bypassing traditional jobber networks. Large trucking companies in India and Brazil negotiate volume contracts covering brake shoes, drums, and installation labor. This channel compression is most visible in markets where telematics penetration enables usage-based contract structuring.
Drum Brake Market Segmentation
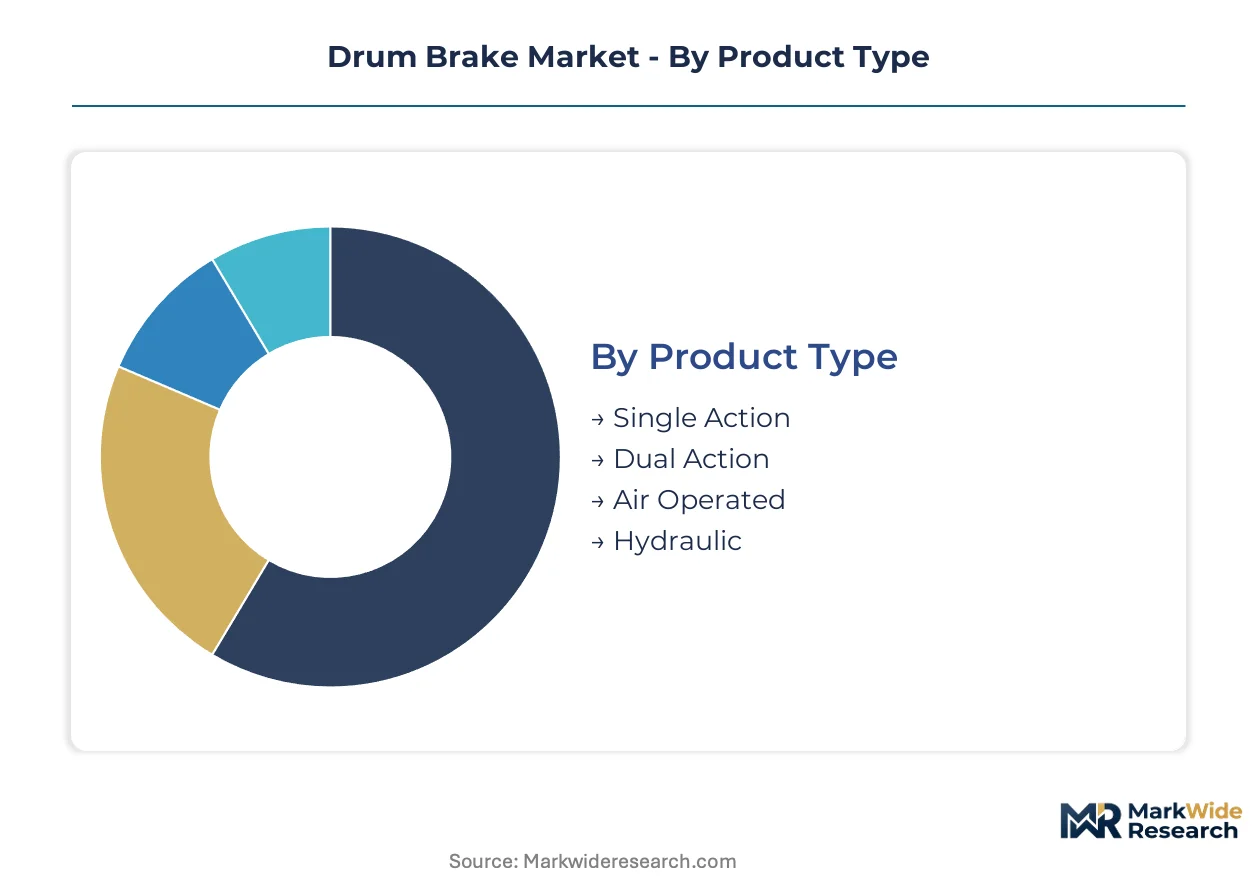
Drum brake market segmentation reveals distinct service intensity profiles across product architectures and end-use channels. Replacement cycle variability and fleet electrification timelines create divergent margin structures that reward precise segment targeting.
Product Type:
After-sales service intensity varies sharply across actuation mechanisms, with pneumatic systems demanding specialized tooling and dual-action configurations requiring precision shoe adjustment protocols.
- Dual Action:Self-energizing geometry expands brake shoes against the drum through wedge or cam mechanisms, delivering superior stopping torque for loaded commercial vehicles. Demand concentrates in Indian and Brazilian heavy-duty trucking fleets where regulatory load limits stress braking systems under mountain descent conditions. Fleet operators in these markets prioritize SAE J661-certified thermal capacity ratings to avoid liability exposure from brake fade incidents.
- Air Operated:Pneumatic actuation systems deploy compressed air through diaphragm chambers to generate clamping force, standard in multi-axle trailers and rigid trucks above 12 tons gross vehicle weight. Brazilian national fleet operators negotiate consolidated maintenance contracts covering air-brake servicing, compressing traditional jobber margins while expanding volume throughput for authorized distributors.
- Single Action:Simple cam-actuated design with one expanding shoe, common in motorcycle rear wheels and light trailers. India's two-wheeler OEMs specify single-action drums for cost-sensitive commuter segments.
- Hydraulic:Fluid-pressure systems transmit pedal force through wheel cylinders, dominant in passenger vehicles and light commercial trucks below 3.5 tons. Southeast Asian pickup truck assemblers specify hydraulic drums for rear axle applications where disc cost premiums prove uneconomical.
By volume, Dual Action leads. By growth pace, Air Operated is ahead.
Application:
Cost tier stratification separates commodity replacement parts from performance-specified assemblies, with heavy equipment commanding premium friction material formulations and passenger vehicles driving volume scale.
- Commercial Vehicles:Rigid trucks, tractor-trailers, and buses operate drum brakes on drive and trailer axles where heat dissipation requirements exceed disc brake economics at equivalent cost. India's BIS certification mandate for brake assemblies sold in domestic commerce elevates product standards, filtering substandard imports from neighboring manufacturing zones. Extended replacement cycles across Brazilian trucking operations expand the serviceable installed base for aftermarket drum providers.
- Heavy Equipment:Mining haul trucks, agricultural tractors, and construction machinery deploy oversized drum assemblies with specialized friction materials rated for continuous duty cycles. OEM procurement specifications in this segment emphasize thermal capacity margins and SAE J661 validation protocols that delay supplier qualification timelines.
- Passenger Vehicles:Rear drum configurations persist in economy segments where front disc-rear drum hybrid architectures balance cost and performance. Southeast Asian compact car assemblers specify cast iron drums for parking brake integration.
- Motorcycles:Single-action rear drums dominate emerging market two-wheelers where cost constraints override disc brake performance advantages. Indian commuter motorcycle production sustains steady drum brake demand.
By revenue concentration, Commercial Vehicles dominates. By margin expansion, Heavy Equipment is climbing fastest.
Material:
Supply concentration in East Asian foundries shapes procurement risk profiles, with cast iron capacity clustering in specific industrial zones vulnerable to energy rationing or logistics bottlenecks.
- Cast Iron:Gray iron alloys with specified carbon content and thermal conductivity ratings constitute the dominant drum material, machined to precise surface finishes for friction coefficient consistency. SAE J661 certification requirements drive material upgrades that improve stopping torque reliability under heavy-load conditions. Foundry capacity in China's industrial zones supplies global OEM and aftermarket demand.
- Composite:Ceramic fiber and carbon matrix formulations address REACH-regulated copper restrictions in European friction lining applications. Alternative fiber matrices require extended laboratory validation that compresses product launch timelines.
- Aluminum:Lightweight alloy drums reduce unsprung mass in performance-oriented motorcycle applications. Japanese sport bike manufacturers specify aluminum for rear wheel configurations.
- Steel:Stamped and welded steel drums serve cost-optimized trailer and agricultural equipment segments. Brazilian trailer manufacturers source steel drums from domestic metalworking clusters.
By installed base, Cast Iron leads. By regulatory tailwind, Composite gains share steepest.
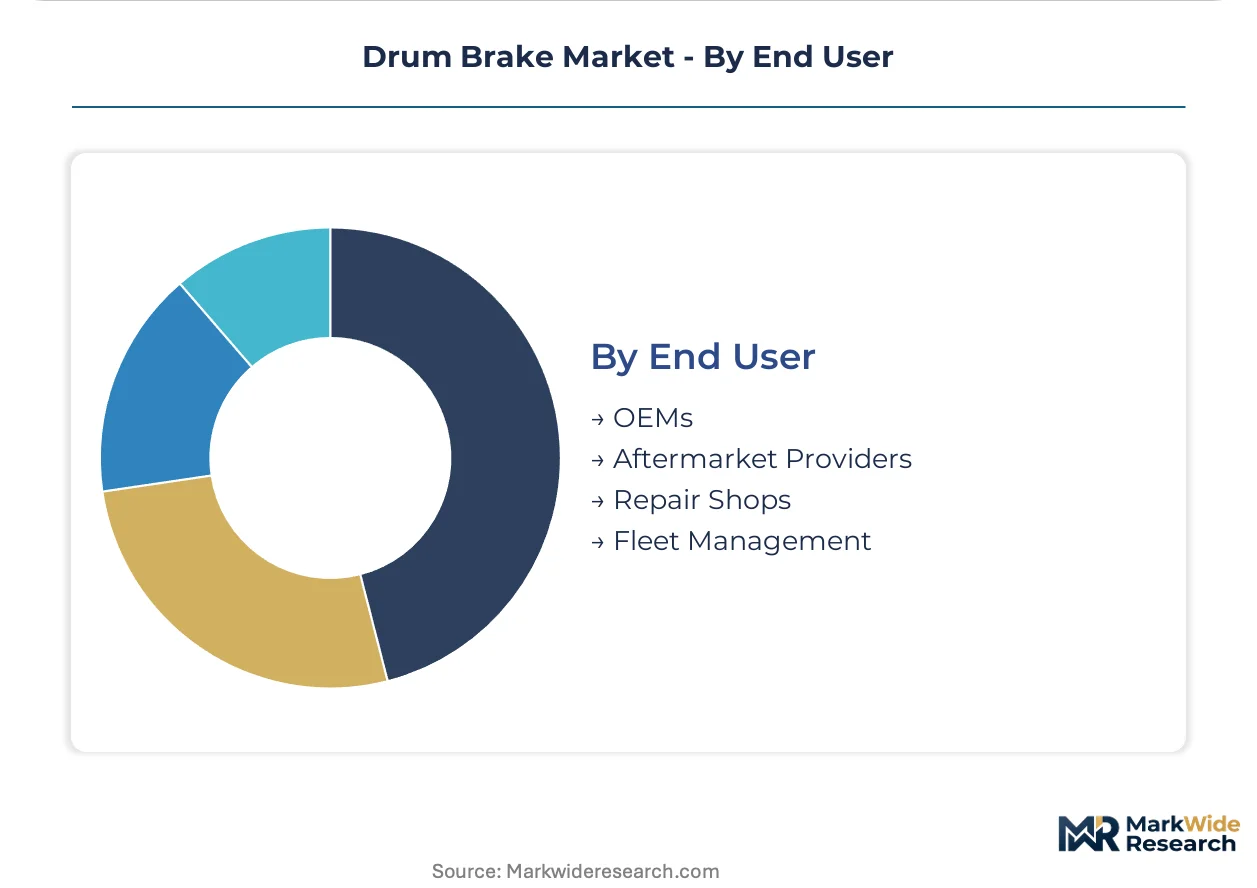
End User:
Customer type fragmentation separates consolidated fleet procurement from fragmented retail demand, with national service networks capturing margin pools that previously accrued to independent repair channels.
- Aftermarket Providers:National parts distributors and specialized brake service chains supply replacement drums, shoes, and hardware kits to fleet operators extending vehicle replacement cycles. Large trucking companies in India and Brazil negotiate volume contracts covering brake components and installation labor, compressing traditional jobber networks. Telematics penetration enables usage-based contract structuring in these markets.
- Fleet Management:Outsourced vehicle maintenance providers consolidate brake servicing spend through direct purchasing agreements with authorized distributors, bypassing wholesale channels. This channel compression is most visible where aging truck populations expand the serviceable installed base.
- OEMs:Vehicle assemblers specify drum brake systems for rear axle and parking brake applications, integrating thermal capacity ratings into platform engineering requirements. Indian commercial vehicle manufacturers anchor regional supply relationships with specialized friction material expertise.
- Repair Shops:Independent service garages perform retail brake maintenance for owner-operators and small fleet accounts, sourcing parts through traditional wholesale distributors. Technician skill gaps in pneumatic-hydraulic system interoperability constrain service quality in mixed fleet configurations.
By transaction volume, Aftermarket Providers leads. By contract value growth, Fleet Management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in cast iron drum exports, while India's Jawaharlal Nehru Port anchors friction material imports for domestic commercial vehicle assembly.
India
Commercial vehicle fleet operators in Maharashtra and Gujarat sustain replacement demand for dual-action drum assemblies. BIS certification mandates for brake components sold in domestic commerce filter substandard imports from neighboring manufacturing zones. The Pune-Aurangabad industrial corridor hosts foundry clusters supplying gray iron drums to regional OEMs.
Brazil
Aging truck populations across São Paulo and Minas Gerais expand the serviceable installed base for aftermarket drum brake providers. ANVISA-equivalent transport safety protocols govern commercial vehicle brake performance standards. The ABC Paulista metalworking belt concentrates steel drum fabrication for trailer and agricultural equipment segments.
Germany
EU REACH regulation constraints on copper and antimony content in friction lining composites force reformulation investments across European supply chains. KBA vehicle type approval requirements extend to brake system component certification. The Stuttgart industrial region anchors specialized friction material engineering for heavy-duty commercial applications.
United States
NHTSA Federal Motor Vehicle Safety Standards govern brake performance and labeling requirements for vehicles operating on American roads. Fleet electrification timelines in California and Texas compress replacement cycles for legacy pneumatic systems. The Detroit-Toledo manufacturing corridor retains foundry capacity for thermal-capacity-rated cast iron drums.
Japan
METI industrial standards and JIS certification requirements shape brake component specifications for domestic and export markets. Motorcycle rear drum demand from Tokyo-based OEMs sustains single-action configuration production. The Aichi Prefecture automotive cluster integrates drum brake supply relationships with specialized friction material expertise.
Drum Brake Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the friction material and casting segments. The vendor base organizes around three strategic archetypes: diversified automotive suppliers bundling braking with chassis modules, dedicated brake system engineers with foundry-to-friction vertical control, and regional fabricators serving aftermarket channels through price-competitive casting. Consolidation pressures favor scale players with captive thermal testing capacity, while niche specialists defend position through SAE J661 certification speed.
Among diversified system architects, Bosch and ZF Friedrichshafen exemplify platform integration strategies that combine pneumatic actuation with suspension and steering modules. Akebono Brake Industry occupies a position within the specialized friction tier, anchoring Japanese OEM supply relationships through material science capabilities. These three represent distinct competitive vectors: scale-driven bundling, technology-led component depth, and regional anchor tenant status.
| Leading Market Players |
|---|
| Bosch |
| Akebono Brake Industry |
| Brembo |
| ZF Friedrichshafen |
| Nissin Kogyo |
| Continental |
| ADVICS |
| Knorr-Bremse |
| Aisin Seiki |
| Others |
Supply & Pricing Matrix
East Asian foundry energy rationing risk determines both pricing tier spreads and supply chain shape across drum brake manufacturing, compressing margins on cast iron drum sourcing while rewarding suppliers with captive thermal testing capacity in diversified geographies.
Pricing Analysis
Volume-discount tiering structures dominate procurement between national fleet operators and authorized distributors, with three-tier pricing stratification across SAE J661-certified premium assemblies, standard BIS-compliant configurations, and economy-grade unbranded replacement kits. Price differentiation rests on certification level and geographic delivery cost, with Brazilian and Indian national fleets extracting steepest discounts through consolidated maintenance contracts. Cost compression in the economy tier intensifies because of copper and heavy metal additive volatility in friction material inputs. Small independent repair shops exhibit highest price sensitivity, while OEM platform engineering teams prioritize thermal capacity reliability over unit cost.
Supply Chain Analysis
Upstream feedstock procurement for gray iron alloys draws from foundry clusters in China, India, and Brazil, with machined drum finishing capacity concentrated in the same three manufacturing zones. Raw material dependencies center on iron ore pellet supply, carbon additive formulations, and SAE J661 validation laboratory access. Single-source vulnerability concentrates in China's industrial corridor foundries, where energy rationing protocols disrupt casting schedules without geographic redundancy. Distribution runs through national parts distributors consolidating fleet maintenance contracts, bypassing traditional wholesale jobber networks in high-growth economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification timelines and EU REACH compliance deadlines create simultaneous disruption vectors, compressing replacement cycle economics while forcing friction material reformulation investments that reshape competitive positioning across commercial vehicle categories.
For Market Incumbents: Insulate aftermarket margin pools by securing captive foundry capacity in India and Brazil outside Chinese supply concentration zones. Accelerate SAE J661 certification pipelines for low-copper friction formulations ahead of REACH enforcement timelines. Channel control through direct national fleet contracts offers defensive leverage against disc brake substitution in light commercial segments.
For New Entrants and Emerging Players: Brazilian national fleet service networks represent the most penetrable entry point, where aging truck populations and outsourced maintenance create white space for specialized air-brake service partnerships. India's BIS-certified component import substitution offers a secondary attack vector for domestic foundry investments. A telematics-integrated predictive maintenance go-to-market angle differentiates against legacy jobber relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized friction material engineers with pre-certified REACH-compliant formulations and captive thermal testing infrastructure. Long-term viability across the projection horizon hinges on electrification timeline resilience in heavy-duty commercial segments. The signal to watch is telematics penetration rates enabling usage-based brake maintenance contracts as a leading indicator of channel restructuring velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive gray iron drum casting in India and Brazil insulates against Chinese energy rationing disruptions. |
| REACH-Compliant Friction Material Launch | Pre-certified low-copper formulations capture regulatory tailwind ahead of EU enforcement deadlines. |
| Telematics-Enabled Predictive Maintenance | Pneumatic actuation integration with fleet monitoring platforms enables usage-based service contracts. |
| National Fleet Direct Contracting | Volume agreements with Brazilian and Indian trucking operators compress traditional distributor margins. |
| SAE J661 Certification Acceleration | Finite element analysis virtualization compresses thermal stress modeling timelines for new drum designs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, aftermarket parts distributors, OEM platform engineers, foundry operations managers, and friction material R&D leads. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, BIS certification registries, EU REACH substance restriction databases, vehicle production databases, and customs trade records for cast iron component flows. Bottom-up segment sizing and top-down macroeconomic calibration were triangulated to reconcile volume estimates.
Calibration against historical replacement cycle data and fleet electrification scenario modeling shaped the analytical framework across the projection horizon. Segmentation dimensions included actuation mechanism, vehicle application class, material composition, and end-user channel structure. CAGRs were derived from installed base aging curves and regulatory compliance timeline impacts. Industry-specific forecast inputs incorporated BIS mandate enforcement intensity and REACH reformulation cost pass-through assumptions.
Practitioners should monitor fleet electrification adoption curves and East Asian foundry energy policy shifts for early signals requiring forecast revision. Cross-checking against commercial vehicle registration databases and national fleet operator maintenance spend disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Global Intelligent Steering System Market